
 Global Cerebrospinal Fluid Management Devices Market | 2026-2036
Global Cerebrospinal Fluid Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cerebrospinal Fluid Management Devices Market Foresight
Silicone elastomer is expanding its share in shunt valve construction as manufacturers seek biocompatibility improvements over older polymers. Medtronic leverages integrated neurosurgery portfolios to sustain hospital contracting power across North America and Western Europe. B. Braun Melsungen AG anchors European manufacturing scale for CSF drainage catheters. Integra LifeSciences specializes in advanced dural repair and complementary neurocritical care accessories.
Cerebrospinal fluid management devices comprise implantable and external systems designed to regulate intracranial pressure, drain excess fluid, and monitor neurological status through calibrated flow-control mechanisms operating at physiological pressure ranges. Shunts with programmable valve mechanisms command premium positioning due to physician preference for non-invasive pressure adjustment after implantation. Microelectromechanical systems-based intracranial pressure monitors represent the fastest-growing technology segment as telemetry-enabled continuous monitoring displaces intermittent manual readings in critical care units. External ventricular drainage systems retain stable volume in trauma and emergency neurosurgery where immediate pressure relief takes priority over long-term implantation.
FDA Class III device designation and EMA Medical Device Regulation conformity assessments impose lengthy clinical trial obligations that filter market entrants and elevate R&D amortization across product lifecycles. The EU AI Act and FDA software-as-medical-device guidance are converging on algorithm-enabled diagnostic features in next-generation pressure monitoring systems. Stakeholders must weigh reimbursement dynamics for programmable versus fixed-valve shunts against the total cost of revision surgeries when evaluating portfolio priorities.
Market Dynamics
Programmable valve systems are restructuring competitive positioning across neurosurgical centers, with physician demand for non-invasive pressure adjustment capabilities forcing manufacturers to absorb elevated R&D amortization while defending premium pricing tiers against fixed-valve alternatives.
Growth Catalysts
- EMA Medical Device Regulation:Stringent conformity assessments for Class III neurological devices are filtering market entrants and consolidating incumbent manufacturer positions across European hospital procurement networks.
- Silicone elastomer material transition:Shunt valve constructors are abandoning legacy polymers in favor of biocompatibility-optimized elastomers, reducing inflammatory response rates and extending device functional lifespan.
- Japan's aging demographic profile:Hydrocephalus intervention volumes are concentrating in metropolitan neurosurgical centers, with Tokyo and Osaka medical clusters driving programmable valve adoption rates.
Market Restraints
- Platinum-cured silicone supply concentration:Medical-grade elastomer feedstock depends on a limited supplier base concentrated in Germany and the United States, exposing valve manufacturers to input cost volatility.
- FDA Class III clinical trial obligations:Lengthy premarket approval pathways impose capital intensity that excludes mid-scale entrants from programmable valve commercialization.
- External ventricular drainage substitution:Emergency neurosurgery protocols retain preference for immediate-pressure-relief systems over implantable shunts in trauma cases, capping long-term implantation market penetration.
Strategic Opportunities
- Telemetry-enabled continuous monitoring:Microelectromechanical systems-based intracranial pressure sensors are converging with wireless transmission protocols, creating algorithm-enabled diagnostic platforms for critical care units.
- India's neurosurgical infrastructure expansion:Underpenetrated tertiary care centers in Mumbai and Delhi present white-space demand for external drainage systems as trauma surgery capacity scales.
- EU AI Act algorithmic compliance pathways:Regulatory frameworks for software-as-medical-device are creating first-mover advantages for manufacturers embedding predictive pressure analytics into next-generation monitoring systems.
Industry Challenges
- Neurocritical care specialist scarcity:Qualified intensivists capable of interpreting continuous ICP waveform data are concentrated in academic medical centers, limiting telemetry system deployment to tier-one hospitals.
- ISO 13485 quality management recertification:Transition timelines for updated medical device quality standards are compressing engineering resources across European manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cerebrospinal Fluid Management Devices Market |
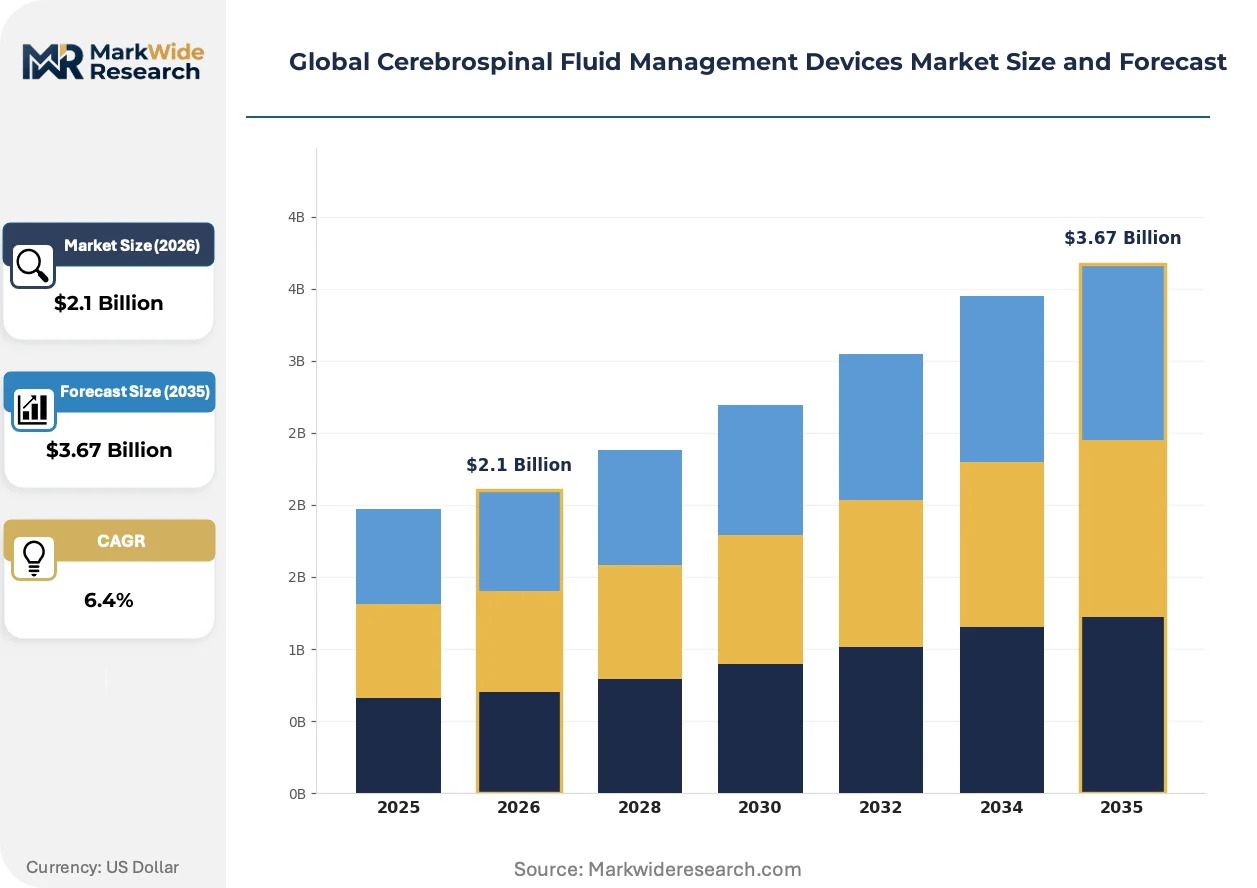
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Ventricular Drainage, Lumbar Drainage Systems, Shunts, Intracranial Pressure Monitors, Reservoirs Technology: Microelectromechanical Systems, Flow-Control Valves, Telemetry, Programmable Valves, Valve Mechanisms Application: Hydrocephalus Treatment, Trauma Care, Neurosurgical Procedures, Infection Management, Brain Tumor Therapy End User: Neurosurgical Centers, Critical Care Units, Specialty Clinics, Rehabilitation Facilities, Research Institutions |
| Companies Covered | Medtronic, B. Braun Melsungen AG, Integra LifeSciences, Johnson & Johnson, Stryker Corporation, Natus Medical Incorporated, Sophysa, Spiegelberg GmbH & Co. KG, Codman & Shurtleff, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cerebrospinal Fluid Management Devices Market Shifts & Advancements
Digital telemetry architectures are overtaking analog measurement conventions across neurocritical care, with algorithm-enabled diagnostics compressing the diagnostic loop between physiological signal detection and clinical intervention.
Microelectromechanical systems-based intracranial pressure monitors deliver continuous waveform telemetry through wireless transmission protocols. Neurocritical care units in academic medical centers are adopting these systems at accelerating rates, displacing intermittent manual manometer readings. This technology is overtaking legacy transducer-based monitoring by enabling predictive pressure trend analysis and reducing nursing documentation burden.
REACH substance restriction frameworks are tightening scrutiny on phthalate plasticizers in polymer-based device components. Manufacturers serving European hospital systems are reformulating catheter materials to maintain market access. Programmable valve shunts with silicone elastomer construction are most affected, with supply chains reconfiguring around compliant feedstock certification.
Hospital procurement committees are consolidating vendor relationships around integrated neurosurgery portfolios rather than discrete device categories. Neurosurgical centers in Germany and the United States are negotiating multi-year supply agreements bundling shunts, drainage catheters, and monitoring accessories. This concentration is most visible in university-affiliated hospital networks where standardization protocols reduce training complexity across rotating surgical staff.
Global Cerebrospinal Fluid Management Devices Market Segmentation
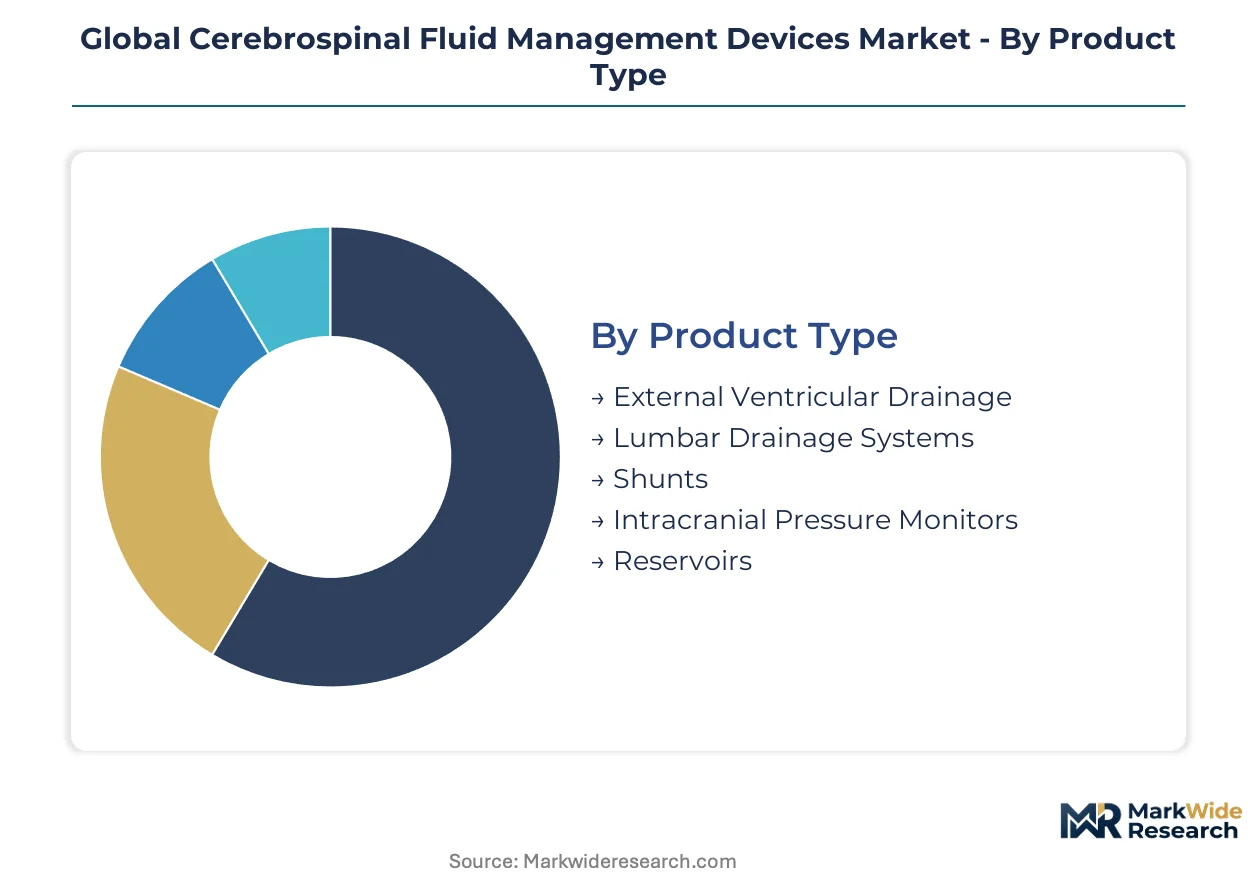
Segmentation in cerebrospinal fluid management devices reveals how regulatory burden, technology complexity, and care setting economics split demand across distinct procurement channels. Manufacturers configure certification strategies and pricing architectures around these fault lines.
Product Type:
FDA Class III PMA pathways apply to implantable shunts and programmable valves, while external drainage systems navigate 510(k) clearance. EMA MDR conformity assessments impose equivalent tiering across European markets.
- External Ventricular Drainage:Catheter-based temporary drainage for acute intracranial pressure relief. Demand concentrates in United States trauma centers and German emergency neurosurgery units where immediate pressure management protocols prioritize rapid deployment over long-term implantation economics.
- Shunts:Implantable diversion systems with silicone elastomer construction for chronic hydrocephalus. Tokyo and Osaka medical clusters in Japan drive programmable valve adoption within this segment as aging demographics expand intervention volumes.
- Intracranial Pressure Monitors:Microelectromechanical systems-based continuous telemetry sensors.
- Lumbar Drainage Systems:Spinal catheter configurations for cerebrospinal fluid diversion.
- Reservoirs:Subcutaneous access ports for intermittent fluid sampling or drug delivery.
Shunts sit at the top of the volume ranking, with intracranial pressure monitors climbing the fastest.
Technology:
Cost tiering separates premium programmable mechanisms from standard fixed-valve alternatives, with telemetry-enabled systems commanding hardware-plus-software recurring revenue models.
- Programmable Valves:Magnetically adjustable pressure settings enabling non-invasive post-implantation calibration. United States academic medical centers absorb premium pricing for revision-avoidance benefits, though FDA PMA timelines extend R&D amortization across elongated product lifecycles.
- Microelectromechanical Systems:Miniaturized pressure transducers with wireless data transmission. German neurocritical care units deploy these for continuous waveform analysis, displacing intermittent manual manometer readings in tier-one hospitals.
- Flow-Control Valves:Fixed-pressure differential mechanisms for standard shunt configurations.
- Telemetry:Wireless signal transmission protocols for remote patient monitoring.
- Valve Mechanisms:Core pressure-regulating components across fixed and adjustable architectures.
Programmable valves capture the highest margin tier, with microelectromechanical systems gaining share fastest.
Application:
Application segmentation tracks reimbursement intensity and procedure acuity, with chronic conditions supporting implantable device economics and acute indications favoring disposable external systems.
- Hydrocephalus Treatment:Chronic cerebrospinal fluid diversion for congenital or acquired ventricular enlargement. Pediatric and geriatric populations in Japan and the United States generate recurring shunt revision demand as device longevity remains constrained by biofilm formation and mechanical failure.
- Trauma Care:Emergency intracranial pressure management for traumatic brain injury. German and United States trauma surgery protocols retain preference for external ventricular drainage in acute phases, capping implantable penetration in this high-acuity setting.
- Neurosurgical Procedures:Perioperative fluid management across elective cranial surgeries.
- Infection Management:Temporary drainage during antibiotic therapy for ventriculitis.
- Brain Tumor Therapy:Pressure control adjunct to oncological resection or palliation.
Hydrocephalus treatment anchors the volume base, with trauma care expanding most quickly as emergency neurosurgery capacity scales.
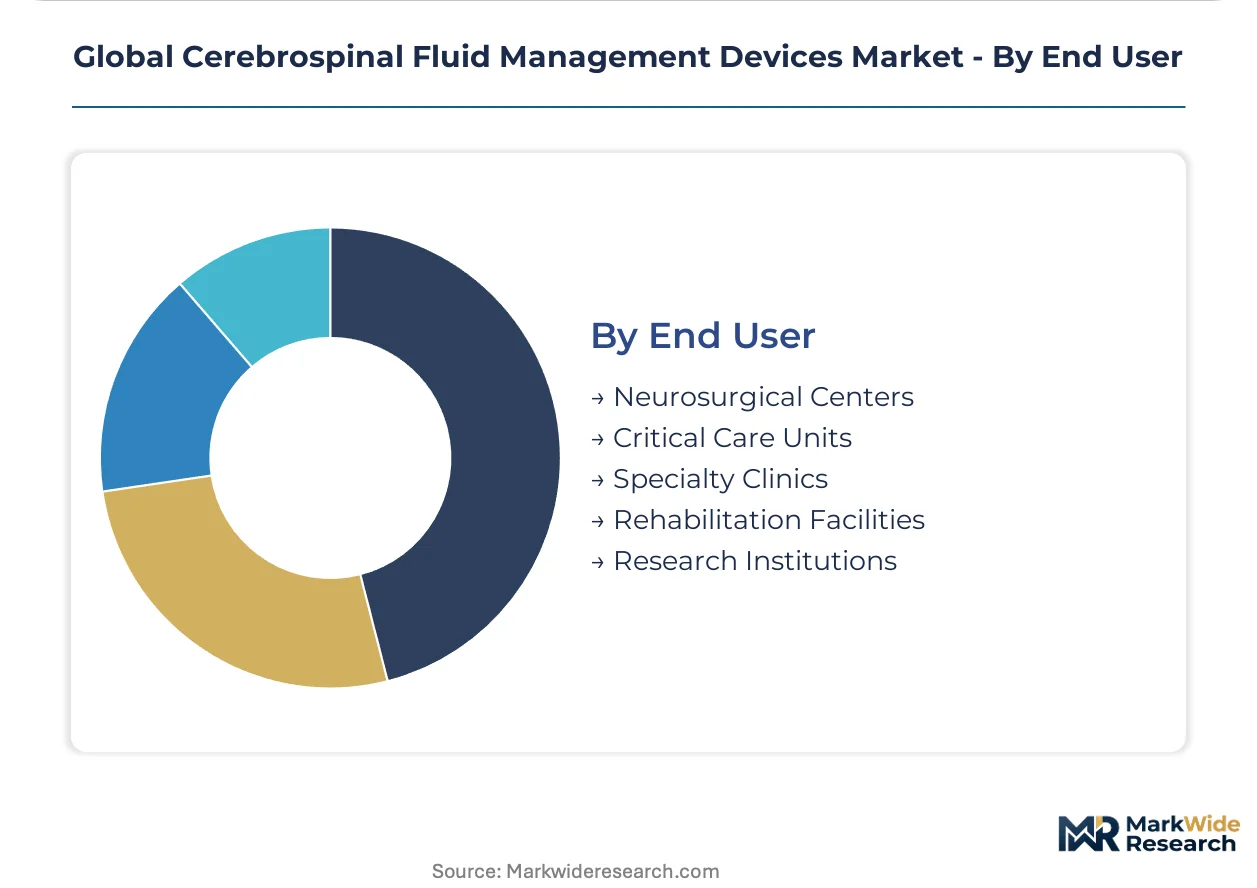
End User:
Customer type determines procurement sophistication, with consolidated hospital networks negotiating integrated portfolios and standalone facilities purchasing discrete device categories.
- Neurosurgical Centers:High-volume implantation sites with specialized operating infrastructure. University-affiliated networks in Germany and the United States bundle shunt, drainage, and monitoring contracts to standardize training protocols across rotating surgical staff.
- Critical Care Units:Neurointensive care environments with continuous monitoring requirements. Telemetry-enabled pressure sensors penetrate these settings in academic medical centers, though specialist scarcity limits deployment to tier-one hospitals capable of waveform interpretation.
- Specialty Clinics:Outpatient-focused neurological intervention facilities.
- Rehabilitation Facilities:Post-acute care settings with shunt maintenance protocols.
- Research Institutions:Clinical trial sites and biomarker collection programs.
Neurosurgical centers dominate procurement volume, with critical care units ascending fastest as telemetry adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo and Osaka medical clusters anchor hydrocephalus intervention volumes, with metropolitan neurosurgical centers driving programmable valve adoption across aging patient populations. Regulatory pathways in the United States, Germany, and Japan concentrate clinical trial obligations and hospital procurement sophistication.
United States
FDA Class III premarket approval pathways impose capital intensity that filters mid-scale entrants from programmable valve commercialization. Academic medical centers in Boston and Baltimore absorb premium pricing for magnetically adjustable shunt systems. Hospital procurement committees consolidate vendor relationships around integrated neurosurgery portfolios.
Germany
EMA Medical Device Regulation conformity assessments elevate clinical evidence requirements for neurological device market access. Platinum-cured silicone supply concentration in German chemical manufacturing exposes valve constructors to input cost volatility. Munich and Heidelberg neurosurgical centers deploy microelectromechanical systems-based pressure monitors for continuous waveform analysis.
Japan
METI industrial policy supports domestic medical device manufacturing scale for aging demographic healthcare demand. Tokyo medical clusters drive programmable valve adoption rates among geriatric hydrocephalus patients. Osaka neurosurgical centers specialize in pediatric shunt revision protocols.
United Kingdom
NICE technology appraisal frameworks evaluate cost-effectiveness thresholds for programmable versus fixed-valve shunt configurations. London teaching hospitals negotiate multi-year supply agreements bundling drainage catheters and monitoring accessories. Manchester and Birmingham trauma centers retain external ventricular drainage preference for emergency neurosurgery.
India
CDSCO medical device registration requirements are tightening quality management system documentation for imported neurological implants. Mumbai and Delhi tertiary care centers present white-space demand for external drainage systems as trauma surgery capacity scales. Government hospital procurement favors cost-optimized fixed-valve configurations over programmable alternatives.
Global Cerebrospinal Fluid Management Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory certification depth and hospital contracting sophistication. The vendor base stratifies between integrated portfolio holders and specialized component suppliers. Three archetypes dominate: diversified medtech conglomerates with neurosurgery divisions, European mid-cap manufacturers with regional manufacturing scale, and telemetry-focused sensor specialists. Competitive moves center on multi-year supply agreement consolidation and algorithm-enabled diagnostic platform development.
Among diversified portfolio holders, Medtronic and Johnson & Johnson exemplify integrated neurosurgery market presence. B. Braun Melsungen AG occupies a position within European manufacturing-centric supply chains. These three entities represent contrasting strategic postures—North American conglomerate breadth, diversified healthcare holding company scale, and German precision manufacturing specialization.
| Leading Market Players |
|---|
| Medtronic |
| B. Braun Melsungen AG |
| Integra LifeSciences |
| Johnson & Johnson |
| Stryker Corporation |
| Natus Medical Incorporated |
| Sophysa |
| Spiegelberg GmbH & Co. KG |
| Codman & Shurtleff |
| Others |
Supply & Pricing Matrix
Programmable-versus-fixed valve bifurcation separates premium magnetically-adjustable systems from commodity fixed-pressure alternatives, with this tier divergence manifesting in both hospital contracting premiums and concentrated platinum-cured silicone feedstock sourcing from German and United States chemical manufacturers. FDA Class III PMA pathways impose capital intensity that filters mid-scale entrants from premium tier participation, while EMA MDR conformity assessments elevate clinical evidence costs that amortize across elongated product lifecycles in European procurement networks.
Pricing Analysis
Platinum-cured silicone elastomer cost pass-through from limited German and United States suppliers elevates programmable valve manufacturing economics, with hospital procurement committees absorbing premium pricing for revision-avoidance benefits in academic medical centers while government hospital systems in India and Southeast Asia favor cost-optimized fixed-valve configurations. Price differentiation separates FDA PMA-certified programmable systems from 510(k)-cleared fixed-valve alternatives, with certification tier and after-sales telemetry bundling as primary drivers. Pricing pressure stems from REACH substance restriction compliance costs in European markets. Pediatric and geriatric hydrocephalus segments exhibit lowest price sensitivity due to revision surgery cost avoidance, while trauma care emergency procurement demonstrates highest sensitivity.
Supply Chain Analysis
Explanted shunt refurbishment and component recovery flows remain minimal given biofilm contamination risks, with reverse logistics instead concentrating on telemetry-enabled monitor recalibration and sensor replacement programs in academic medical center service contracts. Manufacturing concentration centers on Germany, the United States, and Japan for platinum-cured silicone feedstock, precision valve machining, and MEMS sensor fabrication respectively. Raw material dependencies rest on medical-grade elastomer polymers, rare-earth magnetic alloys for programmable mechanisms, and semiconductor substrates for wireless transmission modules. Single-source vulnerability in platinum-cured silicone supply exposes valve constructors to input cost volatility. Distribution runs through hospital procurement committees and group purchasing organizations in consolidated neurosurgical networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aging demographic trajectories across Japan, the United States, and Western Europe position cerebrospinal fluid management as a stable compounder, with hydrocephalus intervention volumes expanding predictably through geriatric population growth and pediatric congenital case persistence.
For Market Incumbents: Hedge against telemetry-enabled monitor commoditization by deepening backward integration into MEMS sensor fabrication and securing exclusive hospital system partnerships for algorithm-enabled diagnostic platforms. Absorb FDA PMA timeline extensions through captive platinum-cured silicone supply agreements with German chemical manufacturers. Prioritize CE marking pathway acceleration under EMA MDR to defend European market access against emerging Asian competitors. For New Entrants and Emerging Players: Specialty distributors serving underpenetrated Indian and Southeast Asian trauma centers present the most accessible channel partner type for external ventricular drainage system penetration. Target Mumbai and Delhi tertiary care infrastructure expansion with cost-optimized fixed-valve configurations and disposable drainage catheter bundles. Pursue CDSCO registration pathway simplification through local quality management system partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where telemetry software capabilities outpace hardware differentiation, favoring acquisition of algorithm-enabled diagnostic platforms over pure-play sensor manufacturers. Frame long-term viability around recurring revenue from continuous monitoring subscriptions and predictive analytics licensing. Watch FDA software-as-medical-device guidance evolution as the primary inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | PMA pathway completion for programmable valves unlocks academic medical center premium pricing in Boston and Baltimore clusters. |
| CE Marking Pathway | EMA MDR conformity assessment acceleration defends German and United Kingdom hospital procurement network positions. |
| Hospital System Partnership | Multi-year supply agreements with university-affiliated networks standardize training protocols across rotating surgical staff. |
| Software Companion Development | Algorithm-enabled pressure trend analytics embedded in MEMS monitors reduce nursing documentation burden in critical care units. |
| Reimbursement Strategy | NICE technology appraisal alignment for programmable valve cost-effectiveness secures United Kingdom National Health Service adoption. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with neurosurgeons, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers alongside secondary validation. Primary fieldwork drew from FDA 510(k) and PMA filings, EMA MDR conformity assessment databases, hospital procurement contract registries, and CMS Medicare reimbursement schedules. Secondary sources included medical device trade customs data, ISO 13485 certification directories, and academic neurosurgical journal publication patterns. Bottom-up shunt and monitor volume estimates triangulated against top-down neurosurgical procedure incidence projections.
Granularity-level modeling disaggregated volume and value across product type, technology tier, application acuity, and end-user procurement sophistication, with additional dimensioning by regional regulatory cluster and reimbursement intensity. CAGRs were derived from procedure volume elasticity to aging demographic projections and technology substitution curves for telemetry-enabled systems. Forecast inputs incorporated platinum-cured silicone supply capacity constraints, FDA software-as-medical-device guidance trajectory, and EMA MDR implementation timeline compliance costs across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory pathway duration variability, neurocritical care specialist availability constraints, and algorithm-enabled diagnostic reimbursement policy evolution. Base assumptions reflect continued FDA Class III PMA stringency, EMA MDR conformity assessment stability, and sustained Japanese METI domestic manufacturing support. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transilluminators Market
Medical Devices
Pressotherapy Systems Market
Medical Devices
Stent Delivery Systems Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Asia Pacific Brachytherapy Devices Market
Medical Devices
Balloon Valvuloplasty Device Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Global Bone Screw System Market
Medical Devices
North America Arthroscopy Devices Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Pharmaceutical Filtration Devices Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Global Infusion Pumps and Accessories Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
Band Ligators Market