
 Global Lithotripsy Market | 2026-2036
Global Lithotripsy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lithotripsy Market Foresight
Supply chain sourcing for lithotripter components is recalibrating from single-source electromechanical suppliers toward multi-source arrangements for piezoelectric arrays and electromagnetic coils. Boston Scientific Corporation leverages backward integration into shock wave generator manufacturing to protect margin pools on service contracts. Siemens Healthineers anchors its position through captive supply of imaging-integrated lithotripsy tables that bundle hardware with proprietary software workflows.
Lithotripsy denotes the non-invasive or minimally invasive fragmentation of calculi within the urinary, biliary, or pancreatic systems using focused acoustic energy, laser pulses, or pneumatic ballistic forces, typically operating at shock wave frequencies of 0.5–2.0 Hz with focal zones of 5–15 mm. Extracorporeal shock wave technology dominates installed base economics due to lower per-procedure capital burden, while laser-based systems command premium positioning in flexible ureteroscopy workflows where stone composition variability demands precise energy modulation. Electromagnetic lithotripters occupy the fastest-growing technology tier as hospitals replace aging electrohydraulic platforms seeking reduced anesthesia requirements and improved stone-free rates.
FDA 510(k) clearance pathways govern shock wave lithotripter market access in the United States, while the EU Medical Device Regulation and CE marking requirements impose strengthened clinical evaluation obligations across European member states. Japan's PMDA maintains distinct technical standards for electromagnetic pulse generators that shape product localization strategies for manufacturers. Stakeholders must monitor reimbursement code consolidation for ambulatory surgical center lithotripsy procedures and the evolving clinical evidence threshold for laser-based devices seeking expanded indication claims.
Market Dynamics
Electromagnetic lithotripter platforms are displacing aging electrohydraulic systems as hospitals prioritize reduced anesthesia protocols and improved stone-free rates, compressing replacement cycles and reshaping capital allocation across urology departments.
Growth Catalysts
- EU Medical Device Regulation:Strengthened clinical evaluation obligations for CE marking are accelerating product portfolio rationalization, pushing smaller manufacturers toward exit and concentrating share among validated suppliers.
- Japan's PMDA electromagnetic standards:Distinct technical requirements for pulse generators force localization investments that deepen installed base lock-in and extend equipment lifecycles.
- Aging demographics in Germany, Japan, and the United States:Established reimbursement pathways in these markets sustain procedural volume growth for stone fragmentation services.
Market Restraints
- Piezoelectric array supply concentration:Multi-source arrangements remain limited for high-voltage ceramic components, creating vulnerability to single-supplier disruption in electromechanical sourcing.
- EU MDR clinical evidence burden:Tightened requirements for shock wave devices extend time-to-market and inflate regulatory compliance costs for new market entrants.
- Laser-based flexible ureteroscopy:Precise energy modulation capabilities in stone composition variability cases present substitution pressure on extracorporeal platforms for complex calculi.
Strategic Opportunities
- India's CDSCO pathway:Underpenetrated reimbursement infrastructure for ambulatory lithotripsy creates first-mover advantage for electromagnetic platform vendors establishing local service networks.
- Imaging-integrated lithotripsy tables:Convergence of shock wave generators with proprietary software workflows enables bundled hardware-software contracting models.
- US ambulatory surgical center consolidation:Reimbursement code consolidation for outpatient procedures favors capital-efficient electromagnetic systems with lower per-procedure burden.
Industry Challenges
- Electromagnetic coil qualification:Specialized winding and insulation expertise for high-reliability pulse generators faces constrained talent pipelines in precision electromechanical manufacturing.
- FDA 510(k) predicate strategy:Evolving clinical evidence thresholds for expanded indication claims on laser-based devices complicate regulatory pathway planning and predicate selection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lithotripsy Market |
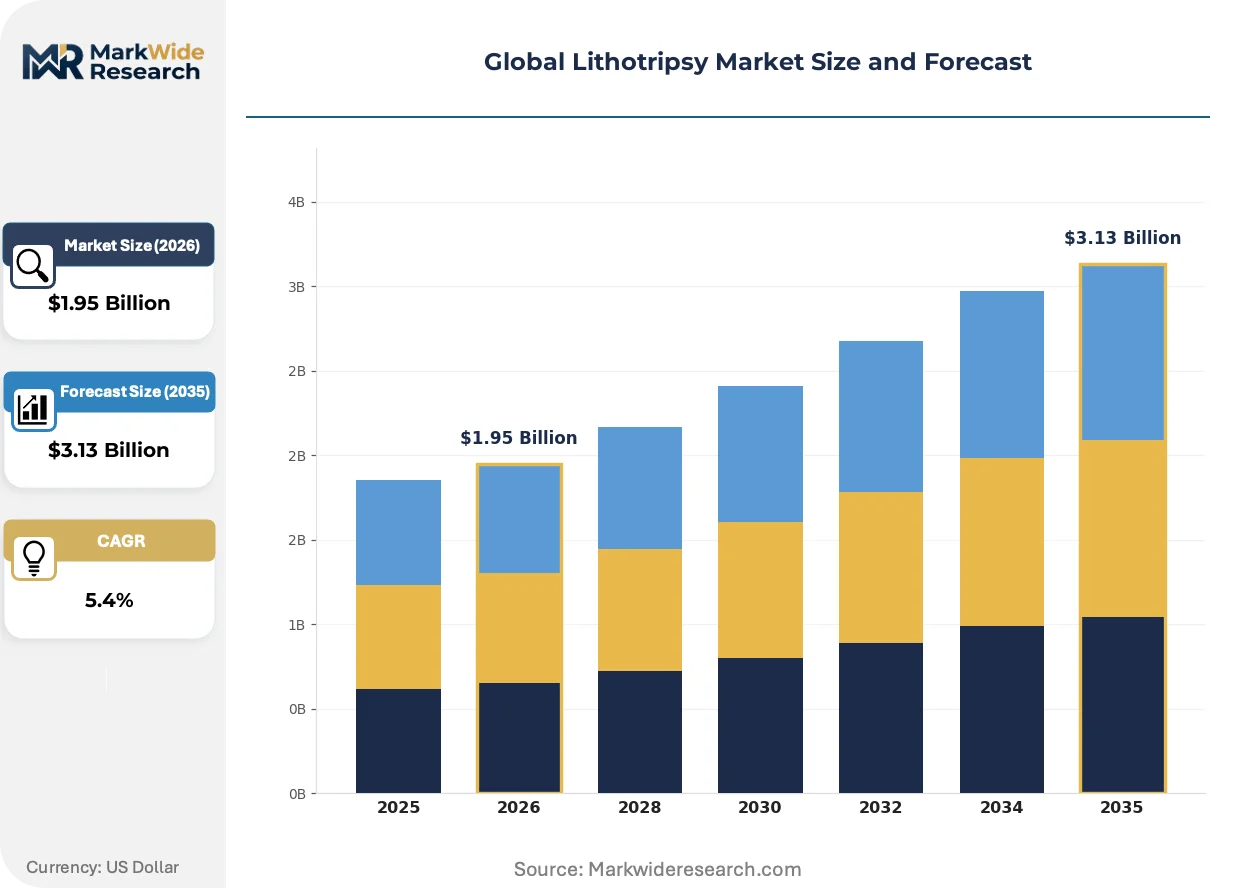
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrohydraulic, Electroconductive, Piezoelectric, Ultrasonic Technology: Extracorporeal Shock Wave, Laser-Based, Pneumatic, Electromagnetic Application: Urolithiasis Treatment, Bile Duct Stones, Pancreatic Duct Stones, Gallstones End User: Specialty Clinics, Ambulatory Surgical Centers, Diagnostic Laboratories, Urology Centers |
| Companies Covered | Boston Scientific Corporation, Dornier MedTech, Olympus Corporation, Siemens Healthineers, EDAP TMS, KARL STORZ, Richard Wolf GmbH, DirexGroup, STORZ MEDICAL AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lithotripsy Market Shifts & Advancements
Shock wave lithotripsy is fragmenting across multiple technology platforms simultaneously, with electromagnetic systems, laser-based flexible ureteroscopy, and portable piezoelectric units each capturing distinct clinical workflows and capital deployment patterns.
Electromagnetic lithotripter technology is decentralizing stone fragmentation from centralized hospital radiology suites toward ambulatory surgical centers and specialized urology clinics. Community hospitals and outpatient facilities in the United States and Germany are adopting compact electromagnetic platforms at accelerated replacement cycles. This geographic diffusion is compressing the addressable market for traditional electrohydraulic systems and redistributing service revenue toward regional equipment distributors.
The EU Medical Device Regulation's strengthened clinical evidence requirements for shock wave devices are extending regulatory timelines and inflating documentation burdens for manufacturers seeking CE marking. European notified bodies are demanding expanded post-market surveillance data for electromagnetic pulse generators, forcing portfolio prioritization decisions. High-volume urology centers in France and Germany are responding by consolidating supplier relationships toward established vendors with validated quality management systems.
After-sales service unbundling is disrupting traditional capital equipment contracting models in the lithotripsy market. Hospital procurement functions in Japan and the United States are separating hardware acquisition from maintenance agreements, pressuring OEM margin pools on long-term service contracts. This behavioral shift is most visible in academic medical centers with dedicated clinical engineering departments capable of independent electromagnetic coil replacement and software calibration.
Global Lithotripsy Market Segmentation
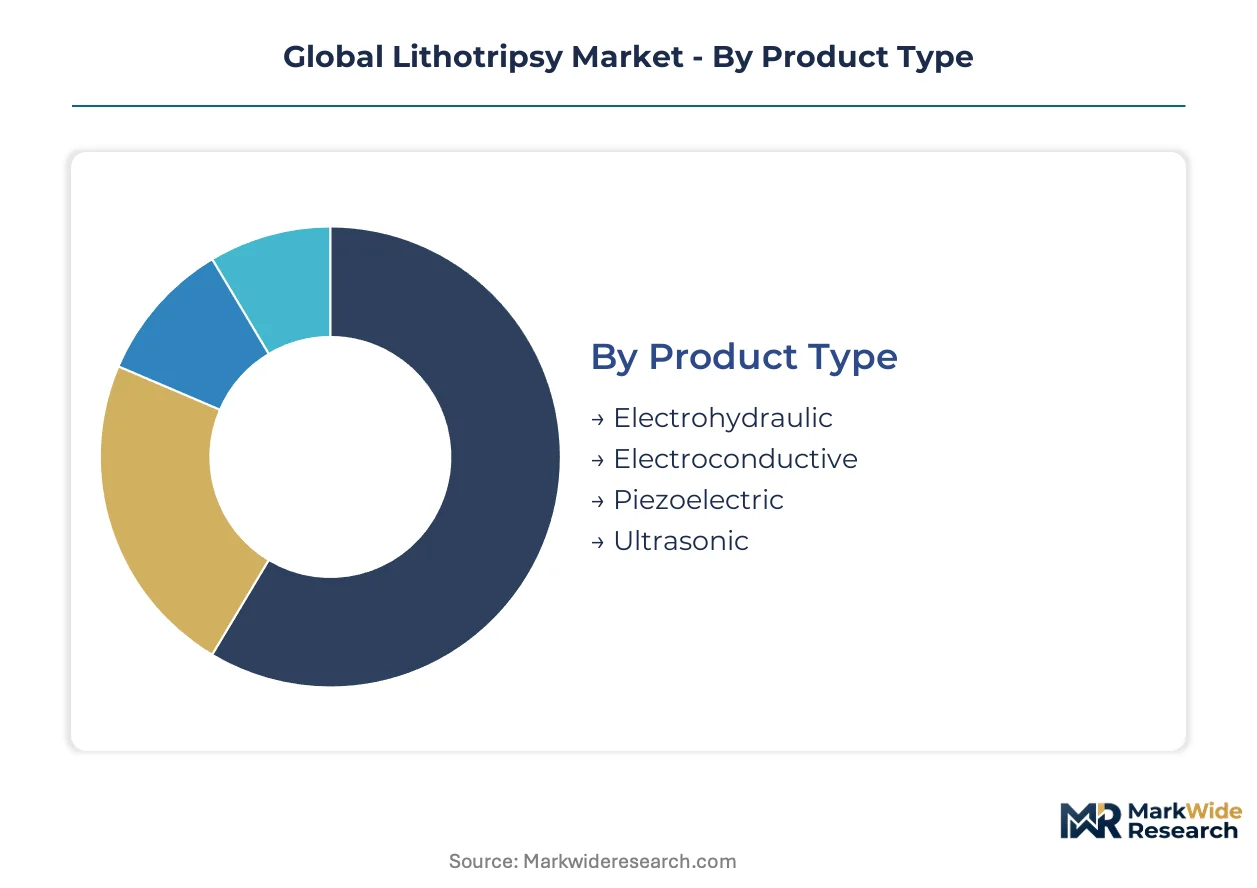
Technology heterogeneity in lithotripsy creates distinct capital deployment patterns across healthcare systems. Product type selection directly determines anesthesia protocols, stone-free rates, and equipment replacement cycles in urology departments.
Product Type:
Buyers differentiate primarily by energy conversion efficiency and maintenance burden in electromechanical systems.
- Electrohydraulic:Spark-gap discharge through water medium generates shock waves with broad focal zones. German hospital networks are retiring these platforms fastest due to higher anesthesia requirements and electrode replacement costs.
- Electroconductive:Electrical discharge across conductive fluid creates acoustic pulses with reduced electrode erosion versus electrohydraulic designs. Japanese urology centers favor this architecture for extended equipment lifecycles under PMDA maintenance protocols.
- Piezoelectric:Ceramic array excitation enables precise focal targeting with minimal tissue injury. Supply concentration in high-voltage ceramic components constrains multi-source procurement strategies for OEMs.
- Ultrasonic:High-frequency mechanical vibration fragments soft calculi through direct contact probes. Limited penetration in extracorporeal workflows restricts adoption to percutaneous nephrolithotomy adjunct procedures.
Electrohydraulic systems lead volumes today; electroconductive platforms are gaining share fastest.
Technology:
Capital efficiency and reimbursement alignment shape technology selection across ambulatory and inpatient settings.
- Extracorporeal Shock Wave:Non-invasive acoustic fragmentation dominates installed base economics through lower per-procedure capital burden. United States ambulatory surgical centers prioritize these systems for outpatient kidney stone protocols under consolidated reimbursement codes.
- Laser-Based:Holmium and thulium fiber lasers enable precise energy modulation across variable stone compositions. Flexible ureteroscopy workflows in France and Germany command premium positioning for complex lower pole calculi.
- Pneumatic:Ballistic probe systems deliver mechanical impact forces through rigid endoscopes. Limited to intracorporeal applications with higher invasibility profiles constraining market expansion.
- Electromagnetic:Coil-driven membrane vibration produces consistent pressure waveforms with reduced anesthesia protocols. Community hospitals in the United States and Germany are accelerating replacement cycles toward these platforms.
Extracorporeal shock wave technology anchors current installed base; electromagnetic systems are climbing the fastest.
Application:
Stone location and composition variability drive procedural volume distribution across anatomical targets.
- Urolithiasis Treatment:Kidney and ureteral calculi fragmentation constitutes the dominant procedural category. Aging demographics in Japan, Germany, and the United States sustain volume growth through established reimbursement pathways for outpatient stone management.
- Bile Duct Stones:Endoscopic retrograde cholangiopancreatography-guided lithotripsy addresses hepatobiliary obstructions. European centers in France and Germany report rising procedural volumes concurrent with metabolic syndrome prevalence.
- Pancreatic Duct Stones:Chronic pancreatitis-associated calculi require specialized endoscopic expertise. Limited specialist availability constrains addressable market expansion outside academic medical centers.
- Gallstones:Extracorporeal shock wave lithotripsy for cholelithiasis competes with laparoscopic cholecystectomy. Reimbursement compression for non-surgical alternatives has redirected volume toward definitive surgical management in United States markets.
Urolithiasis treatment commands dominant volume today; bile duct stone applications are expanding most quickly.
End User:
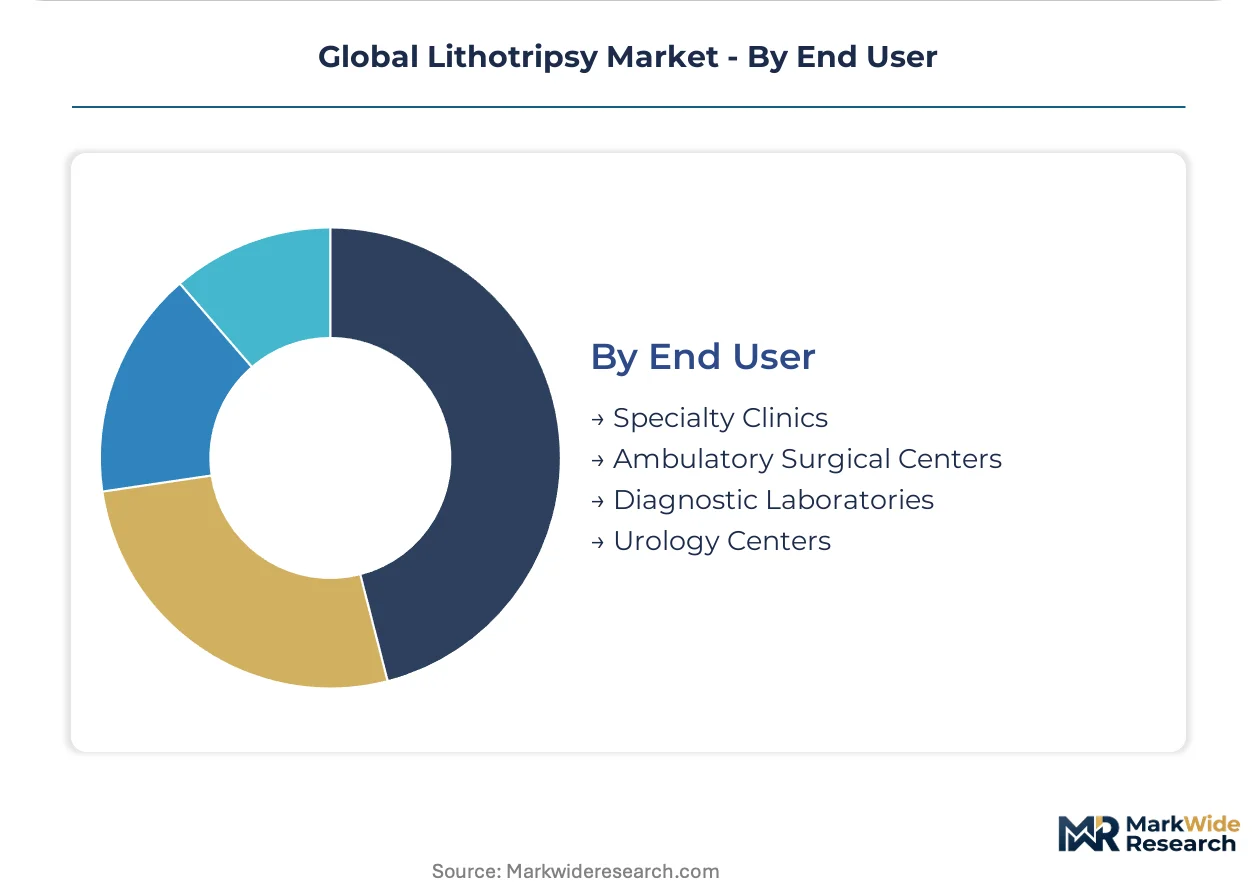
Facility type determines capital allocation flexibility and service contracting sophistication in equipment procurement.
- Specialty Clinics:Focused urology practices prioritize compact electromagnetic platforms with streamlined maintenance requirements. Independent operators in Germany leverage regional distributor networks for service unbundling.
- Ambulatory Surgical Centers:Outpatient-focused facilities demand capital-efficient systems aligned with consolidated reimbursement structures. United States ASC consolidation favors electromagnetic platforms with lower per-procedure burden.
- Diagnostic Laboratories:Imaging-integrated stone detection workflows create bundled hardware-software procurement opportunities. Siemens Healthineers anchors positioning through captive supply of lithotripsy tables with proprietary software.
- Urology Centers:High-volume academic and community hospitals concentrate advanced laser-based flexible ureteroscopy capabilities. Boston Scientific protects margin pools through backward integration into shock wave generator manufacturing.
Urology centers lead installed base today; ambulatory surgical centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Munich-Heidelberg medical technology corridor anchors lithotripsy equipment development through dense clusters of precision electromechanical manufacturers and university hospital validation networks. Equipment procurement patterns diverge sharply across reimbursement environments, with established markets prioritizing replacement cycles while emerging systems build initial installed bases.
United States
Ambulatory surgical centers in Florida and Texas drive electromagnetic platform adoption through consolidated reimbursement codes for outpatient kidney stone procedures. FDA 510(k) clearance pathways govern market access for shock wave lithotripters, with predicate device strategies shaping competitive positioning. The Greater Boston cluster concentrates academic medical centers that unbundle service contracts and perform independent electromagnetic coil maintenance.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia accelerate retirement of electrohydraulic systems due to higher anesthesia requirements and electrode replacement costs. EU Medical Device Regulation strengthened clinical evaluation obligations for CE marking, extending regulatory timelines for electromagnetic pulse generators. The Stuttgart region hosts precision winding specialists for high-reliability coil manufacturing.
Japan
Aging demographics in Tokyo and Osaka sustain procedural volume growth for stone fragmentation services through established reimbursement pathways. PMDA maintains distinct technical standards for electromagnetic pulse generators that force localization investments and deepen installed base lock-in. The Nagoya medical device cluster supports extended equipment lifecycles through specialized maintenance protocols.
India
Underpenetrated reimbursement infrastructure for ambulatory lithotripsy in Maharashtra and Karnataka creates first-mover advantage for electromagnetic platform vendors establishing local service networks. CDSCO regulatory pathways remain less burdensome than EU or US equivalents, attracting manufacturers seeking faster market entry. Delhi-NCR academic centers concentrate training capacity for flexible ureteroscopy workflows.
France
High-volume urology centers in Paris and Lyon consolidate supplier relationships toward established vendors with validated quality management systems under EU MDR pressure. ANSM post-market surveillance requirements for shock wave devices demand expanded documentation from electromagnetic platform manufacturers. The Grenoble cluster specializes in piezoelectric ceramic array development for precise focal targeting applications.
Global Lithotripsy Market Competitive Landscape
Global majors compete with regional champions across technology platforms and service contracting models in lithotripsy equipment supply. The vendor base concentrates around three tiers: integrated imaging-device bundlers, standalone lithotripter specialists, and regional service-focused distributors. Strategic archetypes include backward-integrated shock wave generator manufacturers, imaging-table bundlers with proprietary software workflows, and precision electromechanical component suppliers. Dominant competitive moves encompass M&A for coil winding capabilities and strategic partnerships for piezoelectric ceramic sourcing.
Among Germany-based precision medical device fabricators, Richard Wolf GmbH and KARL STORZ occupy positions exemplifying the integrated endoscopy-lithotripsy archetype, while STORZ MEDICAL AG anchors the standalone electromagnetic platform specialist tier. Boston Scientific Corporation represents the backward-integrated model through in-house shock wave generator manufacturing. These three entities illustrate divergent approaches to protecting margin pools as hospital procurement functions increasingly unbundle hardware acquisition from long-term service agreements.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Dornier MedTech |
| Olympus Corporation |
| Siemens Healthineers |
| EDAP TMS |
| KARL STORZ |
| Richard Wolf GmbH |
| DirexGroup |
| STORZ MEDICAL AG |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between electromagnetic platforms and aging electrohydraulic systems manifests in both procurement premiums and component sourcing strategies, as EU MDR compliance costs and PMDA localization requirements stratify supplier tiers across distinct electromechanical qualification ladders.
Pricing Analysis
Input-cost pass-through from high-voltage ceramic arrays and precision electromagnetic coils feeds directly into platform pricing, with three-tier pricing structure across premium, standard, and economy levels anchored by CE marking tier, anesthesia protocol efficiency, and after-sales bundling configuration. Price differentiation stems from FDA 510(k) predicate complexity and ISO 13485 certification depth. Pricing pressure stems from service contract unbundling in academic medical centers. Ambulatory surgical centers exhibit highest price sensitivity; integrated imaging-device bundlers demonstrate lowest.
Supply Chain Analysis
Piezoelectric ceramic supply rests on Japanese and German specialty manufacturers, with electromagnetic coil winding concentrated in Stuttgart-region precision fabricators and Chinese electromechanical assemblers. Critical inputs span high-purity lead zirconate titanate substrates, copper-alloy magnet wire, and medical-grade membrane polymers. Single-source vulnerability in high-voltage ceramic arrays creates disruption exposure. Distribution runs through regional equipment distributors with captive service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory validation into durable competitive moats, with EU MDR clinical evidence thresholds and Japan PMDA electromagnetic standards accelerating portfolio consolidation among validated suppliers.
For Market Incumbents: Hedge against laser-based flexible ureteroscopy substitution by deepening backward integration into shock wave generator manufacturing and accelerating electromagnetic platform refresh cycles in United States ambulatory surgical centers. Prioritize CE marking pathway investments to exploit smaller manufacturer exit pressure under EU MDR documentation burdens. Channel control through regional distributor lock-in protects service revenue streams. For New Entrants and Emerging Players: Regional equipment distributors with independent clinical engineering capabilities offer the most penetrable channel architecture for electromagnetic platform penetration in India's underpenetrated Maharashtra and Karnataka markets. Target CDSCO regulatory pathway speed advantages against EU and US timeline compression. White-space concentration in compact electromagnetic systems for community hospital outpatient suites enables first-mover positioning before reimbursement infrastructure matures. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR compliance costs exceed smaller manufacturers' quality management system capabilities, concentrating share among validated suppliers with captive coil winding or ceramic array sourcing. Five-to-ten year viability favors precision electromechanical component specialists with PMDA-validated pulse generator architectures. Signal to monitor: ANSM post-market surveillance documentation demands from electromagnetic platform manufacturers in French high-volume urology centers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR clinical evidence requirements compress competitive field toward validated quality management systems. |
| Backward Integration into Coil Manufacturing | Precision winding expertise scarcity in Stuttgart-region talent pipelines deepens supplier moats. |
| Hospital System Partnership | Academic medical center service unbundling demands flexible contracting models from equipment vendors. |
| Software Companion Development | Imaging-integrated lithotripsy tables with proprietary workflows enable bundled hardware-software contracting. |
| Reimbursement Strategy | United States ASC consolidation under consolidated codes favors capital-efficient electromagnetic platform positioning. |
Research Methodology
Coverage spans United States, Germany, Japan, India, and France, with primary inputs from each market combining structured interviews with urology department heads, hospital procurement committee members, biomedical engineering directors, and regional equipment distributor principals against secondary validation through FDA 510(k) filings, PMDA technical documentation, EU MDR notified body guidance, hospital procurement databases, and GPO contract repositories. Bottom-up equipment installation tracking and top-down procedural volume estimates triangulate market sizing.
Granularity-level modeling disaggregates volume and value across technology platform, application anatomy, end-user facility type, and regional regulatory cluster throughout the forecast period. CAGRs derive from replacement cycle compression analysis and procedural volume elasticity to demographic aging patterns. Industry-specific forecast inputs include electromagnetic platform adoption curves in United States ambulatory settings and EU MDR regulatory timeline elasticity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA electromagnetic standard revisions, EU MDR notified body capacity constraints, and laser-based ureteroscopy reimbursement code expansion. Forecasts reflect documented assumptions regarding anesthesia protocol evolution and stone-free rate clinical evidence thresholds. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Urology
Uraemia Treatment Market
Urology
Chronic Pyelonephritis Treatment Market
Urology
Acquired Cystic Kidney Disease Treatment Market
Urology
Global Bladder Cancer Market
Urology
Pelvic Cancer Induced Hemorrhegic Cystitis Market
Urology
Nordic Urinary Catheters Market
Urology
Primary Aldosteronism Market
Urology
Voiding Cystourethrogram Market
Urology
Prostatic Arterial Embolization (PAE) Market
Urology
Global Hydronephrosis Market
Urology
Pyelonephritis Treatment Market
Urology
Urinary Tract Infection (UTI) Treatment Market
Urology
Middle East and Africa Bladder Disorders Market
Urology
Urothelial Carcinoma Treatment Market
Urology
Uncomplicated Urinary Tract Infection Treatment Market
Urology
India Urology Market