
 Blood Warmers Market | 2026-2036
Blood Warmers Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Warmers Market Intelligence
Perfusion technologist shortages across North American and European hospital systems is unwinding installed-base expansion for high-complexity warming platforms. Stryker Corporation leverages its surgical segment integration to bundle warming systems with orthopaedic procedure kits. Barkey GmbH & Co. KG anchors its position through specialized manufacturing of precision thermal devices for transfusion medicine. 3M sustains channel dominance via extensive healthcare supply contracts that bundle warming accessories with broader patient temperature management portfolios.
Blood warmers are electromechanical devices designed to raise refrigerated blood products and intravenous fluids to physiologic temperature, typically maintaining output between 37°C and 42°C through controlled heat exchange surfaces or warming plates. The primary purpose is preventing hypothermia, coagulopathy, and cardiac arrhythmia during massive transfusion protocols or prolonged surgical procedures. Intravenous warming systems occupy the largest revenue share due to mandatory use in Level I trauma centers and cardiac surgery suites, while surface warming platforms represent the fastest-growing category as preoperative patient warming becomes standard protocol. Electric technology dominates installed bases, though resistive warming approaches are gaining traction in military and field-deployed emergency medical services where power reliability varies.
The FDA's 510(k) premarket notification framework governs device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for thermal regulation equipment marketed in Europe. ISO 10993 biocompatibility standards and IEC 60601 electrical safety specifications shape product design requirements across all major jurisdictions, effectively raising engineering barriers for new entrants. Stakeholders must monitor evolving harmonization gaps between FDA and EMA post-market surveillance requirements, as divergent vigilance reporting obligations will determine regional launch sequencing and compliance cost structures.
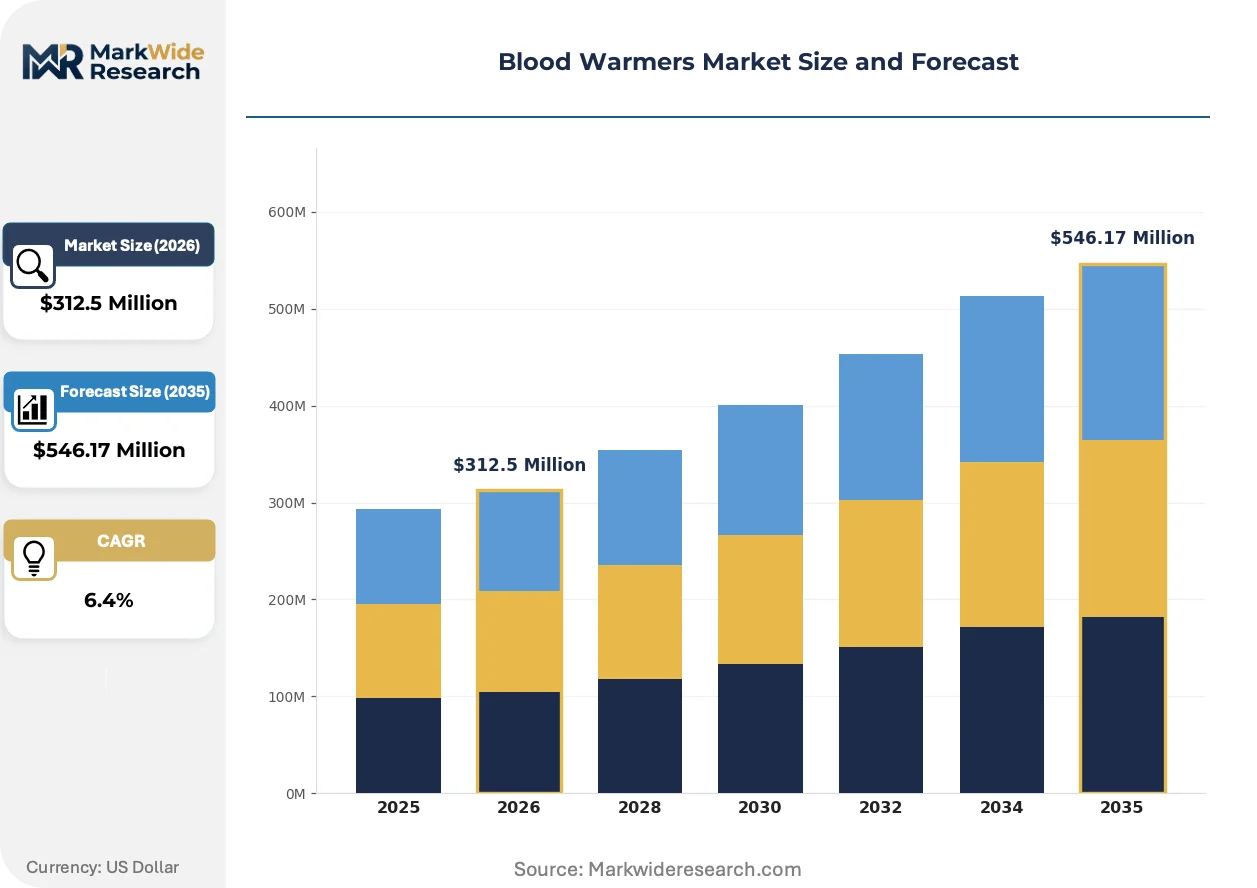
Market Dynamics
Perfusion technologist shortages across North American and European hospital systems are constraining installed-base expansion for high-complexity warming platforms, forcing manufacturers to simplify device interfaces and reduce training dependencies.
Growth Catalysts
- Level I Trauma Center Mandates:United States emergency care regulations now require active fluid warming during massive transfusion protocols, cementing intravenous warming systems as standard equipment in designated trauma facilities.
- EU Medical Device Regulation:Stricter clinical evidence requirements for thermal regulation equipment are accelerating consolidation around established manufacturers with robust quality management systems.
- Resistive Warming Technology:Military and field-deployed emergency medical services are adopting power-adaptive warming approaches where electrical reliability varies.
Market Restraints
- Precision Sensor Input Costs:Platinum-based temperature sensing elements face price volatility that compresses margins on mid-tier warming platforms.
- German Component Concentration:Precision thermal control modules rely heavily on specialized Bavarian manufacturing clusters, creating single-source vulnerability.
- IEC 60601 Electrical Safety:Subclause revisions for electromagnetic compatibility impose redesign costs that disproportionately burden smaller device manufacturers.
Strategic Opportunities
- Japanese Preoperative Warming Protocols:Surgical suites in Tokyo and Osaka medical centers are expanding surface warming platform adoption ahead of anesthesia induction.
- ISO 10993 Biocompatibility Harmonization:Converging international standards for patient-contact materials reduce regional customization burdens for thermal exchange surfaces.
- Subscription-Based Device Access:Cash-constrained rural hospitals are piloting managed service arrangements that bundle warming hardware with maintenance and consumable supply.
Industry Challenges
- Perfusion Technologist Pipeline Collapse:North American training programs graduate insufficient certified specialists to operate high-complexity warming platforms at projected deployment rates.
- 510(k) Clearance Timeline Compression:FDA's updated premarket notification pathway for thermal regulation devices demands more extensive predicate device analysis, extending regulatory cycles.
- Legacy Hospital Information System Integration:Proprietary data protocols in older patient monitoring networks obstruct seamless temperature data logging from modern warming devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Warmers Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous, Surface, Forced Air, Fluid Warmer End User: Hospitals, Blood Banks, Emergency Medical Services, Surgical Centers Technology: Electric, Microwave, Resistive, Chemical Distribution Channel: Online, Direct Sales, Distributors, Healthcare Supply Stores |
| Companies Covered | Belmont Medical Technologies, Barkey GmbH & Co. KG, 3M, MEQU, Gentherm Medical, Stryker Corporation, Vyaire Medical, Estill Medical Technologies, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Warmers Market Strategic Shifts & Innovations
Device miniaturization and power efficiency improvements are redefining competitive boundaries between stationary surgical suite equipment and portable emergency deployment systems.
Carbon-film resistive heating elements are supplanting traditional aluminum warming plates in next-generation intravenous fluid warmers. Field emergency services in Germany and Japan are adopting these lighter, lower-power units for helicopter and ground ambulance deployment. The technology is supplanting established electric warming architectures in applications where battery operation and rapid thermal response outweigh maximum flow-rate capacity.
The FDA's updated 510(k) clearance pathway for thermal regulation devices is extending product development timelines by demanding more extensive predicate device comparisons. Manufacturers must now submit additional human factors validation data for devices with modified user interfaces. Cardiac surgery suites and Level I trauma centers in the United States are experiencing delayed access to incremental warming platform improvements as firms navigate expanded documentation requirements.
Hospital procurement departments are consolidating temperature management device purchasing under broader patient warming category contracts. Single-source agreements now bundle intravenous warmers, surface warming blankets, and temperature monitoring accessories, displacing standalone device negotiations. This concentration is most visible in United States integrated delivery networks where supply chain rationalization targets reduce vendor management overhead across multi-hospital systems.
Blood Warmers Market Segmentation
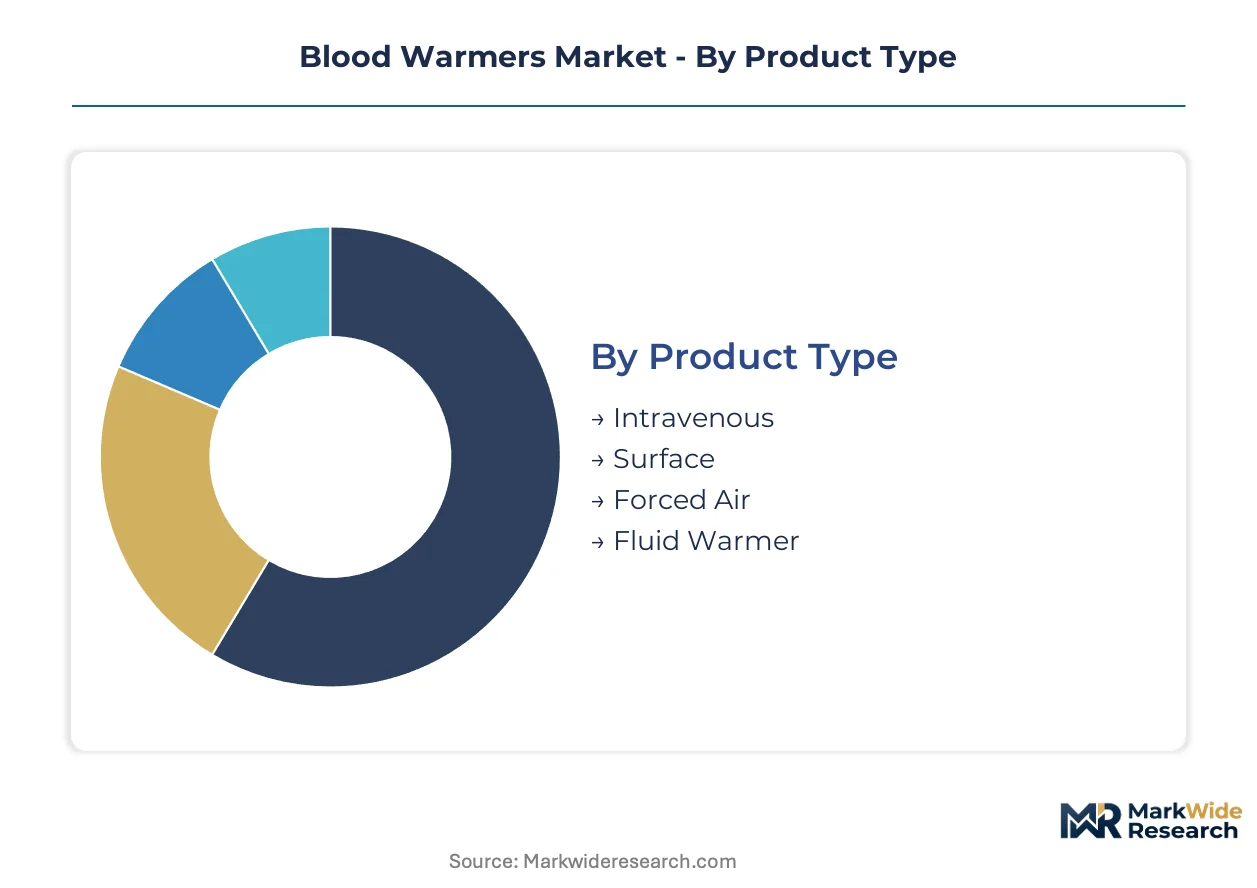
Blood warmer procurement patterns diverge sharply across clinical settings, with trauma centers prioritizing flow capacity while surgical suites emphasize precision control. Technology selection hinges on power infrastructure reliability and regulatory clearance timelines in target geographies.
Product Type:
Margin pools concentrate in intravenous warming systems where Level I trauma center mandates enforce mandatory deployment and consumable attachment rates run highest.
- Intravenous:These systems employ counter-current heat exchange chambers or warming plates to elevate refrigerated blood products and crystalloid solutions to physiologic temperature during massive transfusion protocols. Demand concentrates in United States Level I trauma centers and cardiac surgery suites where FDA mandates require active fluid warming. Stryker bundles these systems with orthopaedic procedure kits to defend installed base positions.
- Surface:Forced-air and conductive warming blankets raise patient skin temperature preoperatively to reduce hypothermia incidence. Tokyo and Osaka medical centers are expanding adoption ahead of anesthesia induction, making this category the steepest expansion trajectory in Japanese surgical suites.
- Forced Air:Blower units deliver temperature-controlled air through disposable blankets draped over patients. German hospital procurement departments favor these for compatibility with existing surgical workflow infrastructure.
- Fluid Warmer:Portable units designed for field emergency services and military applications where battery operation supersedes flow-rate maximization. Bavarian manufacturing clusters supply precision thermal control modules for these devices.
Intravenous systems hold installed capacity. Surface warming is rotating up the share rankings.
End User:
Volume concentration tracks surgical procedure density and trauma system investment levels across developed healthcare economies.
- Hospitals:Emergency departments and operating rooms deploy multi-modal warming platforms across trauma, cardiac, and orthopaedic service lines. United States integrated delivery networks consolidate temperature management purchasing under single-source agreements that bundle intravenous warmers with surface blankets and monitoring accessories.
- Emergency Medical Services:Ground and helicopter ambulance crews adopt carbon-film resistive heating elements for reduced weight and power draw. German and Japanese field emergency services lead adoption of these lighter, battery-operated units.
- Blood Banks:Transfusion services utilize precision thermal devices for controlled thawing of frozen plasma and cryoprecipitate. Barkey anchors its market position through specialized manufacturing for this segment.
- Surgical Centers:Ambulatory facilities prioritize compact footprint and simplified interfaces to accommodate perfusion technologist shortages constraining high-complexity platform deployment.
Hospitals dominate current procurement volume. Emergency Medical Services is climbing the fastest as prehospital warming protocols expand.
Technology:
Application context dictates technology selection, with stationary surgical environments tolerating higher power draw than field-deployed systems.
- Electric:Aluminum warming plates and counter-current exchange chambers maintain installed base dominance in United States cardiac surgery suites. IEC 60601 electrical safety compliance and ISO 10993 biocompatibility certification requirements favor established manufacturers with robust quality management systems.
- Resistive:Carbon-film heating elements enable lighter, lower-power operation for military and emergency medical services where electrical reliability varies. These units sacrifice maximum flow-rate capacity for rapid thermal response and battery compatibility.
- Microwave:Electromagnetic warming approaches achieve rapid heating rates for high-volume transfusion scenarios. Regulatory clearance complexity under FDA 510(k) pathways limits commercial penetration relative to thermal conduction alternatives.
- Chemical:Single-use warming packs activate through exothermic reactions for austere environments lacking electrical infrastructure. Military logistics chains represent primary demand concentration.
Electric technology holds installed capacity. Resistive systems are rotating up the share rankings.
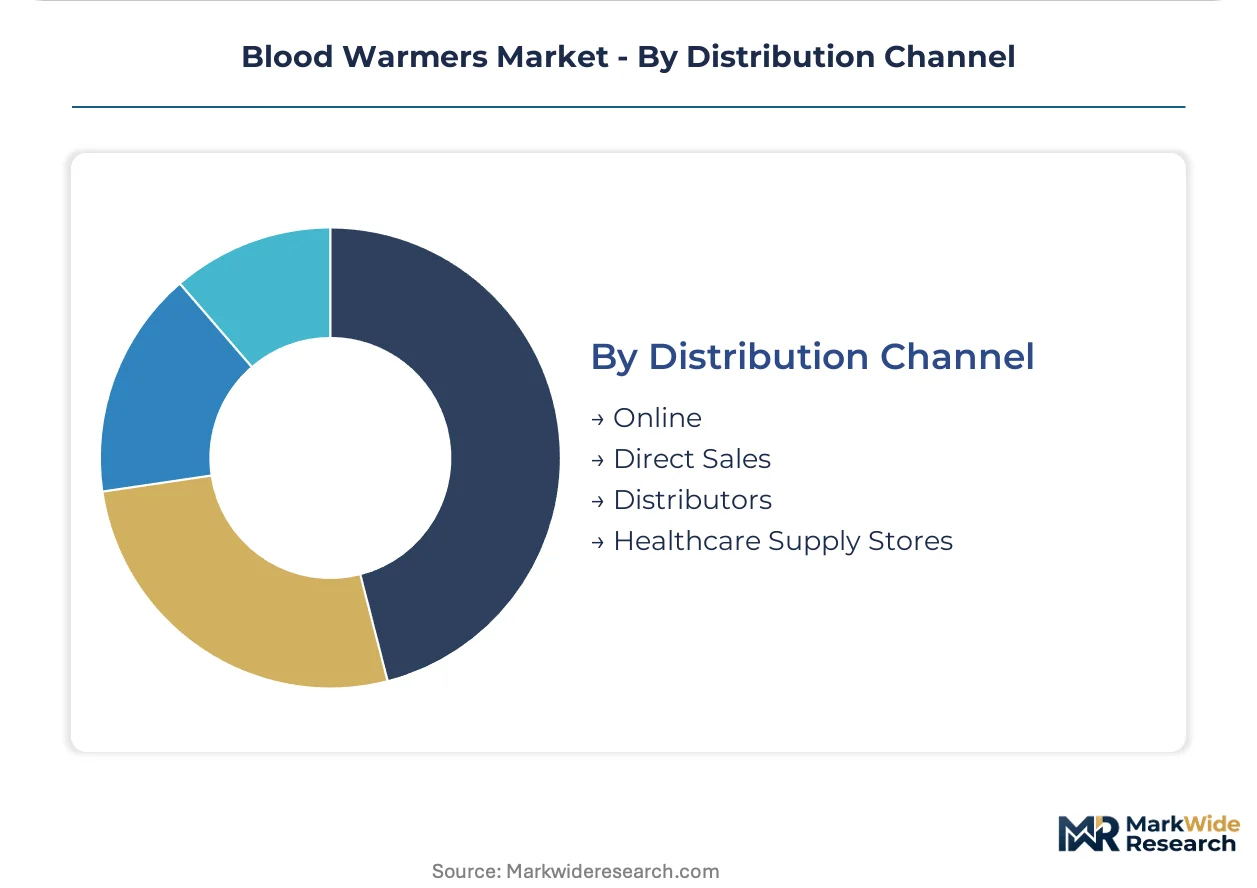
Distribution Channel:
Channel selection reflects customer scale and supply chain rationalization priorities across healthcare systems.
- Direct Sales:Original equipment manufacturers maintain dedicated field organizations for Level I trauma center and integrated delivery network accounts. 3M leverages extensive healthcare supply contracts to bundle warming accessories with broader patient temperature management portfolios.
- Distributors:Regional medical device distributors serve mid-tier hospitals and surgical centers with inventory management and technical support services. German component concentration in precision thermal control modules creates single-source vulnerability through this channel.
- Online:E-commerce platforms accommodate smaller blood banks and rural emergency medical services with standardized product configurations. Subscription-based device access pilots are emerging for cash-constrained facilities.
- Healthcare Supply Stores:Local procurement channels serve replacement part and consumable demand for legacy installed bases. Legacy hospital information system integration challenges obstruct seamless temperature data logging from modern warming devices purchased through this channel.
Direct sales holds installed capacity. Online channels are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's updated 510(k) clearance pathway for thermal regulation devices anchors the United States as the dominant geography, while surgical volumes and trauma system investments concentrate procurement in Germany and Japan.
United States
Level I trauma center mandates now require active fluid warming during massive transfusion protocols, cementing intravenous warming systems as standard equipment in designated trauma facilities. The FDA's 510(k) premarket notification framework governs device clearance and demands more extensive predicate device analysis than prior pathways. Integrated delivery networks in Texas and California are consolidating temperature management purchasing under single-source agreements that bundle warming hardware with consumable supply.
Germany
Bavarian manufacturing clusters supply precision thermal control modules for high-complexity warming platforms serving cardiac surgery suites across the country. The EU Medical Device Regulation imposes stricter clinical evidence requirements for thermal regulation equipment marketed in Europe. Emergency medical services in Bavaria and North Rhine-Westphalia are adopting carbon-film resistive heating elements for helicopter and ground ambulance deployment.
Japan
Tokyo and Osaka medical centers are expanding surface warming platform adoption ahead of anesthesia induction, making this category the steepest expansion trajectory in Japanese surgical suites. METI oversees medical device standards harmonization with international technical specifications. Perfusion technologist shortages in Kanto and Kansai regions are forcing manufacturers to simplify device interfaces and reduce training dependencies for high-complexity platforms.
United Kingdom
NHS procurement frameworks are consolidating temperature management device purchasing under broader patient warming category contracts across hospital trusts. The Medicines and Healthcare products Regulatory Agency enforces CE marking and post-market surveillance requirements for thermal regulation equipment. London and Southeast England surgical centers are prioritizing compact footprint and simplified interfaces to accommodate staffing constraints.
Canada
Health Canada regulates medical device licensing through the Medical Devices Bureau, with requirements aligned to ISO 13485 quality management standards. Ontario and Quebec hospital systems are piloting subscription-based device access arrangements that bundle warming hardware with maintenance services. Rural facilities in Prairie Provinces are driving demand for portable units where electrical reliability varies across emergency medical service territories.
Blood Warmers Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier that concentrates on precision thermal applications. The market structure reflects consolidation around manufacturers with robust quality management systems capable of navigating FDA 510(k) and EU MDR compliance burdens. Three archetypes dominate: diversified surgical equipment conglomerates bundling warming systems with procedure kits, precision thermal specialists serving transfusion medicine niches, and broad healthcare suppliers leveraging supply contract scale. Competitive moves center on strategic partnerships with integrated delivery networks and portfolio diversification into surface warming platforms.
Among diversified surgical equipment conglomerates, Stryker Corporation exemplifies the bundling archetype through orthopaedic segment integration. Barkey GmbH & Co. KG anchors the precision thermal specialist tier with German engineering heritage visible in its corporate structure. 3M occupies a position within the broad healthcare supplier archetype, leveraging extensive supply contracts that bundle warming accessories with patient temperature management portfolios.
| Leading Market Players |
|---|
| Belmont Medical Technologies |
| Barkey GmbH & Co. KG |
| 3M |
| MEQU |
| Gentherm Medical |
| Stryker Corporation |
| Vyaire Medical |
| Estill Medical Technologies |
| ICU Medical |
| Others |
Cost & Logistics Intelligence
Carbon-film resistive heating elements replacing aluminum warming plates in portable units are redrawing procurement geography toward East Asian component suppliers while compressing margins on mid-tier electric platforms. This substitution simultaneously loosens Bavarian manufacturing's grip on precision thermal modules and intensifies price competition between established German engineering houses and emerging Asian electronics producers.
Pricing Analysis
United States trauma centers pay 15-25% premiums over German hospital procurement for identical intravenous warming platforms due to FDA 510(k) compliance documentation costs embedded in landed pricing. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified surgical suite systems from emergency medical service field units and basic blood bank thawing devices. Cost compression in the economy tier is intensifying because platinum sensor price volatility forces manufacturers to absorb input spikes on fixed-price GPO contracts. Rural surgical centers exhibit highest price sensitivity, while Level I trauma centers prioritize flow capacity over unit cost.
Supply Chain Analysis
Inventory buffers for precision thermal control modules stretch 8-12 weeks as Bavarian manufacturing clusters operate at capacity serving cardiac surgery demand. Supply concentrates in Germany, China, and Japan for heating elements, temperature sensors, and medical-grade polymers respectively. Raw material dependencies span platinum-group metals for sensing elements, medical-grade aluminum for warming plates, and specialized polymer films for disposable blankets. Single-source vulnerability in Bavarian precision module production creates supply chain risk for manufacturers lacking dual-qualified suppliers. Distribution runs through direct sales for integrated delivery networks and regional distributors for mid-tier hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumable attachment rates for disposable warming blankets and temperature sensors are expanding faster than hardware replacement cycles, positioning aftermarket service contracts as the dominant value-capture mechanism. This recurring-revenue layer now determines enterprise valuations more than installed base scale alone.
For Market Incumbents: Shield market position by deepening backward integration into platinum sensor supply chains and accelerating CE marking under EU MDR ahead of smaller competitors. Consolidate GPO contract positions through bundled temperature management portfolios that raise switching costs for hospital procurement committees. Counter carbon-film substitution threats by emphasizing flow-rate superiority in cardiac surgery applications where performance specifications dominate procurement criteria. For New Entrants and Emerging Players: Remote technical support for perfusion technologist-starved surgical centers represents a service-layer gap where incumbents under-serve with standardized training protocols. Target Japanese preoperative warming protocols in Tokyo and Osaka medical centers expanding surface platform adoption fastest. Pursue subscription-based device access pilots with cash-constrained rural hospitals as the primary go-to-market angle, bundling hardware with maintenance and consumable supply. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision thermal specialists with ISO 13485 certification and established FDA predicate device libraries. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Monitor 510(k) clearance timeline compression as the inflection signal—extended FDA cycles will strand capital in development-stage assets and favor acquirers with existing predicate pathways.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Stricter clinical evidence requirements favor established manufacturers with robust quality management systems over emerging entrants. |
| Hospital System Partnership | Single-source agreements with integrated delivery networks bundle warming hardware with consumable supply, raising competitor switching costs. |
| Software Companion Development | Legacy hospital information system integration challenges obstruct seamless temperature data logging, creating demand for middleware solutions. |
| Reimbursement Strategy | Level I trauma center mandates requiring active fluid warming cement intravenous systems as standard equipment with predictable procurement. |
| Backward Integration | Platinum sensor price volatility compresses margins on mid-tier platforms, favoring manufacturers with captive supply of temperature sensing elements. |
Research Approach
A spread of perspectives from perfusion technologists, hospital procurement managers, biomedical engineers, and GPO contracts managers converged on the working assumptions shaping this analysis. Primary field engagement with cardiac surgery suites and Level I trauma centers combined with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and ISO certification registries. Bottom-up installed base enumeration and top-down surgical procedure volume estimates were triangulated to anchor market size calculations.
Segmentation dimensions modeled span product type, end user, technology, and distribution channel across the projection horizon. CAGRs were derived from procedure volume trajectories, regulatory mandate implementation schedules, and technology substitution curves. Forecast inputs incorporated perfusion technologist pipeline constraints, platinum commodity price assumptions, and trauma center designation expansion plans.
Forecasts assume regulatory continuity in FDA 510(k) and EU MDR regimes; material policy shifts would require re-modeling clearance timeline and compliance cost assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Micro Syringes Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Intraoperative Sensor Market
Medical Devices
Hypodermic Syringes Market
Medical Devices
Continuous Bladder Irrigation Devices Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Middle East and Africa Single-Use Medical Device Reprocessing Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Specimen Retrieval Nets Market
Medical Devices
EEG Amplifiers Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Europe 3D Printing in Healthcare Market