
 Global Surgical Visualization Systems Market | 2026-2036
Global Surgical Visualization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Surgical Visualization Systems Market Foresight
Aftermarket service revenue is reconfiguring profitability dynamics across the surgical visualization landscape. Olympus Corporation leverages its endoscope installed base to sustain recurring service contracts across Asia-Pacific hospitals. Karl Storz GmbH & Co. KG anchors its competitive stance through rigid endoscope refurbishment programs that extend equipment lifecycles. Stryker Corporation dominates integrated operating room installations where visualization hardware bundles with surgical navigation platforms.
Surgical visualization systems encompass camera heads, light sources, display monitors, and image processing units that capture, transmit, and render anatomical imagery during operative procedures, typically operating at 1080p to 4K resolution with frame rates exceeding 60 Hz to eliminate motion artifact. These systems enable real-time tissue discrimination and surgical precision across minimally invasive and open interventions. Digital imaging systems command the largest revenue pool due to universal compatibility requirements across hospital networks. Augmented reality segments are expanding fastest as overlay capabilities merge preoperative planning with live operative views. Fluorescence imaging occupies a specialized margin niche where indocyanine green contrast agents reveal perfusion dynamics invisible to standard white-light modalities.
FDA 510(k) clearances govern market entry for novel visualization modalities in the United States, while EU MDR technical documentation requirements extend certification timelines for European commercialization. Japan's PMDA enforces stringent electrical safety and biocompatibility standards that filter non-compliant imports. Stakeholders must monitor evolving software-as-a-medical-device classifications that reclassify AI-enhanced visualization algorithms under separate regulatory frameworks.
Market Dynamics
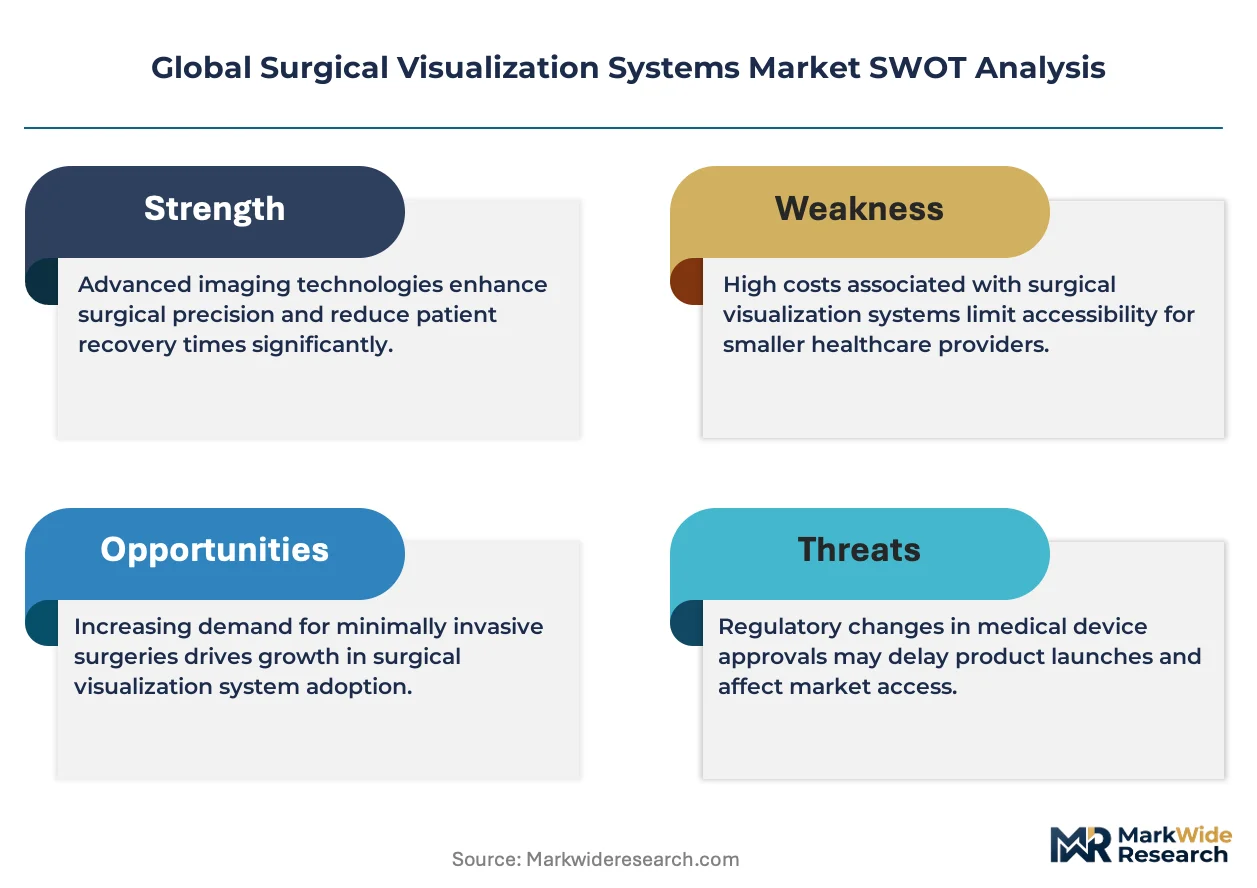
Capital equipment replacement cycles are compressing as 4K resolution becomes the minimum viable specification for new hospital tenders, forcing manufacturers to accelerate R&D cadences while managing legacy 1080p installed base obsolescence.
Growth Catalysts
- FDA 510(k) clearance streamlining:Expedited pathways for predicate-device-equivalent visualization hardware reduce time-to-revenue for iterative camera head improvements.
- Ambulatory surgery center expansion:Compact visualization platforms address space constraints in freestanding outpatient facilities performing same-day orthopedic and ophthalmic procedures.
- Indocyanine green perfusion imaging:Fluorescence contrast protocols extend system utility beyond standard white-light visualization into vascular and oncologic surgery.
Market Restraints
- Optical sensor supply concentration:Sony and OmniVision dominate CMOS sensor fabrication for surgical cameras, creating single-source vulnerability.
- EU MDR technical documentation burden:Extended certification timelines delay European commercialization for novel visualization modalities.
- Reusable endoscope durability limits:Rigid endoscope refurbishment economics degrade beyond 300-400 sterilization cycles.
Strategic Opportunities
- India's hospital infrastructure buildout:Greenfield medical cities in Gujarat and Tamil Nadu specify integrated visualization suites without legacy compatibility constraints.
- Software-as-a-medical-device reclassification:AI-enhanced image processing algorithms create recurring revenue streams separate from hardware sales.
- Augmented reality overlay convergence:Preoperative CT/MRI fusion with live laparoscopic views enables precision oncology applications.
Industry Challenges
- Sterile processing technician shortage:Complex endoscope reprocessing protocols exceed staffing capacity at mid-sized hospitals.
- Interoperability certification complexity:DICOM compliance and HL7 FHIR integration require dedicated software engineering resources.
- Legacy analog signal infrastructure:SDI-to-IP transition demands simultaneous display monitor and routing hardware replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Surgical Visualization Systems Market |
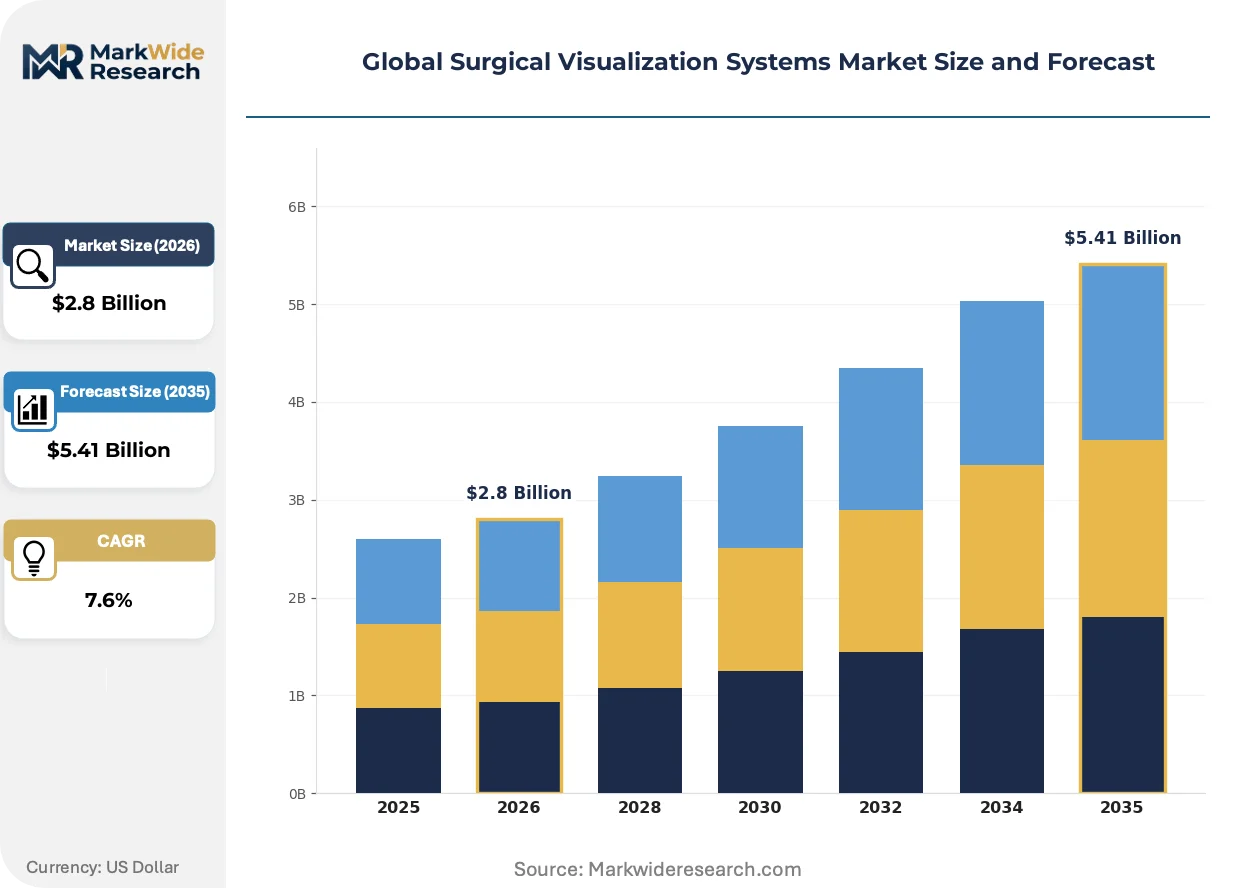
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Endoscopy, Fluorescence Imaging, Microscopic Visualization, Augmented Reality, Digital Imaging Systems, Optical Scopes Technology: High-Definition Imaging, Laser Imaging, Navigation Systems, Image-Guided Surgery, Virtual Reality, Intraoperative MRI Application: Neurosurgery, Orthopedic Surgery, Cardiovascular Procedures, ENT Surgeries, Urology, General Surgery End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Research Institutes, Government Facilities, Academic Medical Centers |
| Companies Covered | Olympus Corporation, Stryker Corporation, Karl Storz GmbH & Co. KG, Medtronic, Fujifilm Corporation, B. Braun Melsungen AG, Conmed Corporation, Boston Scientific Corporation, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Surgical Visualization Systems Market Shifts & Advancements
Visualization architecture is migrating from hardware-centric to software-defined platforms, compressing product lifecycles and reconfiguring vendor competitive moats around algorithmic differentiation rather than optical engineering alone.
Head-mounted displays are virtualizing surgical field visualization by replacing fixed boom-mounted monitors with surgeon-worn 4K OLED screens. Academic medical centers in Germany and Japan are piloting these systems for ergonomic relief during prolonged spinal and cardiac procedures. The technology is virtualizing operating room spatial design, eliminating sightline constraints that previously dictated equipment placement.
EU MDR Article 10 technical documentation requirements now mandate clinical evidence for visualization software updates, not just hardware modifications. This regulatory friction is extending certification timelines by 12-18 months for European market entry. Fluorescence imaging modules face heightened scrutiny under biocompatibility and electrical safety annexes, prompting manufacturers to front-load conformity assessment resources.
Hospital procurement committees are consolidating vendor relationships through integrated operating room bundling contracts. Single-source agreements covering visualization, insufflation, and energy platforms displace best-of-breed component purchasing. This concentration is most pronounced in United States health systems exceeding 50 hospitals, where standardization reduces training and spare parts inventory costs.
Global Surgical Visualization Systems Market Segmentation
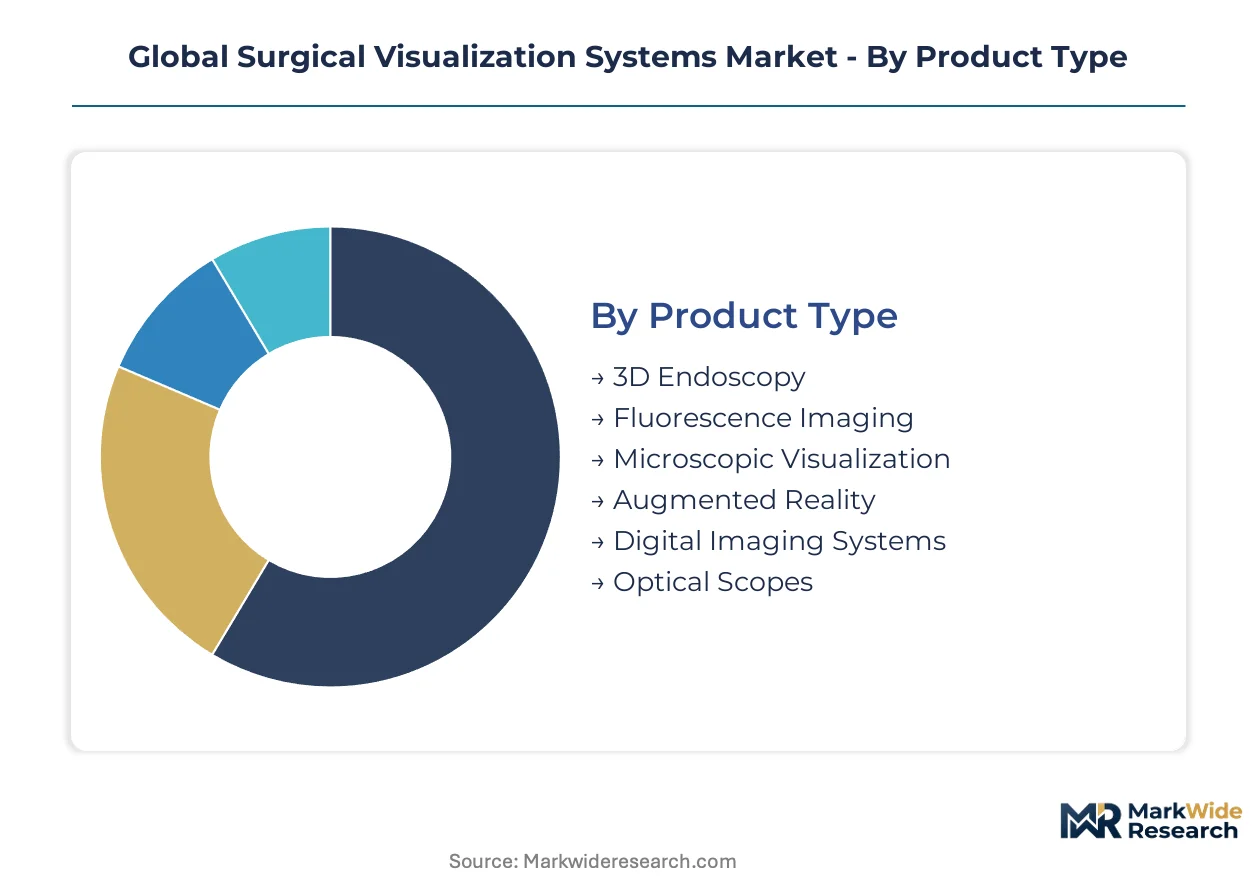
Surgical visualization systems fragment across multiple technical and commercial dimensions that determine procurement criteria, pricing architecture, and regulatory pathway complexity. Product type classifications reflect fundamental differences in optical physics and image processing requirements, while application segments impose distinct performance specifications on resolution, latency, and field-of-view parameters.
Product Type:
Cost tier differentiation separates premium integrated platforms from modular component purchases across hospital procurement frameworks.
- Digital Imaging Systems:Camera heads, light sources, and image processing units operating at 1080p to 4K resolution with frame rates exceeding 60 Hz. United States health systems exceeding 50 hospitals drive standardization contracts that bundle these components with surgical navigation platforms.
- Augmented Reality:Overlay systems merging preoperative CT/MRI planning with live operative views through head-mounted or boom-mounted displays. Germany and Japan academic medical centers pilot these for precision oncology applications where anatomical registration accuracy determines resection margins.
- Fluorescence Imaging:Indocyanine green contrast protocols revealing perfusion dynamics invisible to standard white-light modalities.
- 3D Endoscopy:Stereoscopic visualization for depth perception in laparoscopic and endoscopic procedures.
- Microscopic Visualization:Optical magnification systems for ophthalmic and neurological microsurgery.
- Optical Scopes:Rigid and flexible endoscopes for direct anatomical visualization.
Digital Imaging Systems commands the established base. The steepest expansion runs through Augmented Reality.
Technology:
Application requirements dictate technology selection, with surgical precision demands determining imaging modality specifications.
- High-Definition Imaging:4K resolution capture and transmission infrastructure now constituting minimum viable specifications for new hospital tenders. Capital equipment replacement cycles compress as 1080p installed bases face obsolescence.
- Image-Guided Surgery:Real-time navigation integrating preoperative datasets with live anatomical views. Neurosurgery and orthopedic spine procedures in United States academic medical centers concentrate demand for sub-millimeter registration accuracy.
- Laser Imaging:Coherent light sources for specialized tissue interaction and diagnostic illumination.
- Navigation Systems:Spatial tracking hardware for instrument localization within surgical fields.
- Virtual Reality:Immersive preoperative planning and surgical training environments.
- Intraoperative MRI:Magnetic resonance imaging adapted for real-time surgical guidance.
High-Definition Imaging anchors current procurement volumes. Image-Guided Surgery is gaining share fastest among advanced modalities.
Application:
Customer type segmentation reveals divergent purchasing authority and budget allocation patterns across surgical service lines.
- General Surgery:Broadest addressable procedure volume spanning abdominal, thoracic, and soft tissue interventions. Ambulatory surgery center expansion in United States outpatient facilities drives compact platform adoption for same-day procedures.
- Neurosurgery:Highest precision requirements demanding sub-millimeter navigation accuracy and specialized fluorescence perfusion assessment. Germany and Japan academic medical centers concentrate investment in integrated microscope-navigation systems.
- Orthopedic Surgery:Arthroscopic and open procedures requiring robust camera durability against irrigation fluid exposure.
- Cardiovascular Procedures:Fluorescence imaging for coronary and valvular surgery perfusion assessment.
- ENT Surgeries:Rigid endoscopy for sinus and laryngeal procedures with specialized angled optics.
- Urology:Flexible and rigid endoscopy for renal and prostatic interventions.
General Surgery captures the largest installed base. Neurosurgery exhibits the steepest technology premium trajectory.
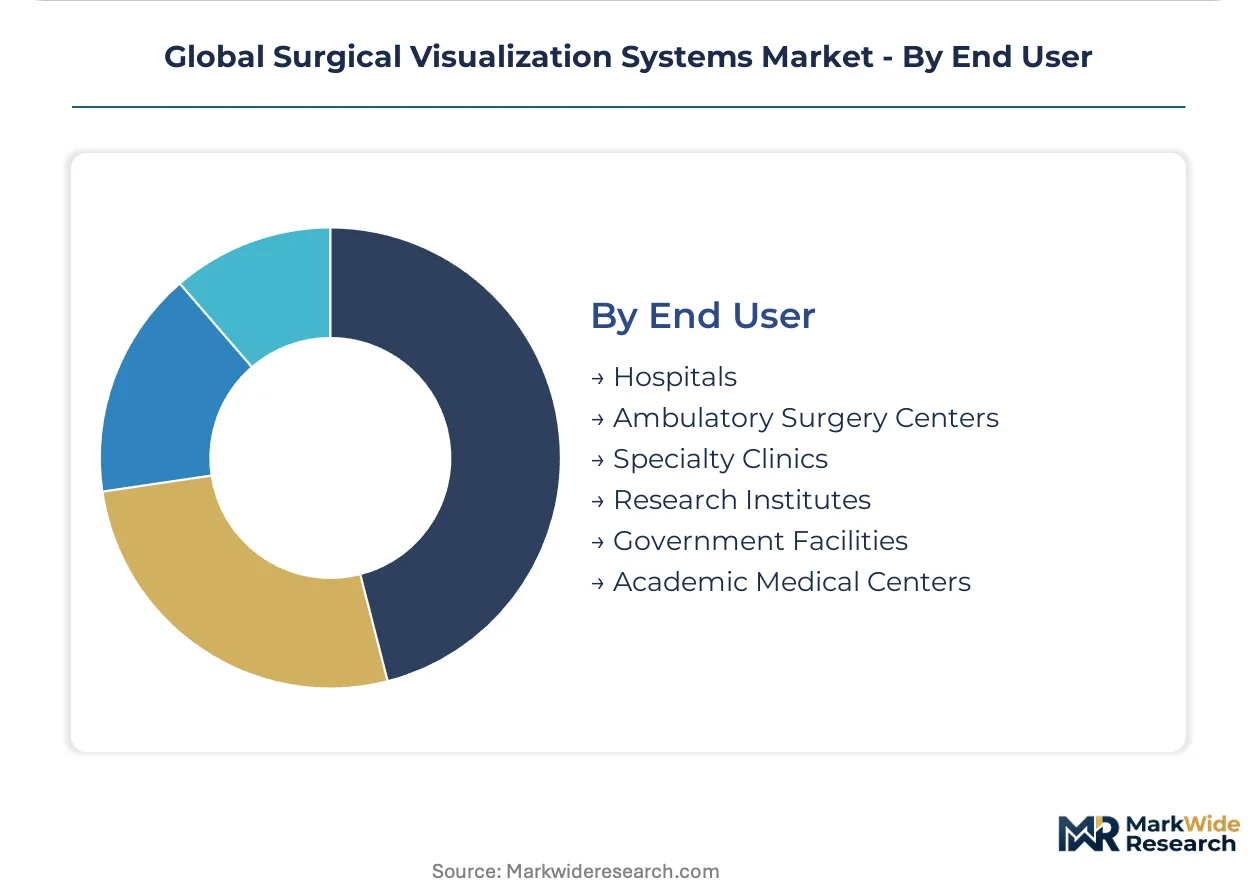
End User:
Volume concentration varies dramatically by care setting, determining sales cycle length and service contract structure.
- Hospitals:Integrated operating room installations with multi-year capital equipment replacement programs. United States health systems consolidate vendor relationships through bundling contracts covering visualization, insufflation, and energy platforms.
- Ambulatory Surgery Centers:Freestanding outpatient facilities with space constraints favoring compact visualization platforms. Same-day orthopedic and ophthalmic procedure growth drives specification demand for rapid setup and breakdown.
- Academic Medical Centers:Research and training missions supporting early adoption of augmented reality and head-mounted display technologies.
- Specialty Clinics:Focused procedure volumes in ophthalmology or gastroenterology with dedicated endoscope inventories.
- Research Institutes:Preclinical and clinical trial support for novel visualization modality validation.
- Government Facilities:Public hospital systems with extended procurement cycles and standardization mandates.
Hospitals maintain the dominant procurement volume. Ambulatory Surgery Centers are climbing the fastest as site-of-care migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMOS sensor fabrication concentrates in Japan and the United States, while system integration and end-user demand distribute across Germany, Japan, and the United States where capital replacement cycles accelerate.
United States
Health systems exceeding 50 hospitals consolidate vendor relationships through integrated operating room bundling contracts. FDA 510(k) clearance pathways expedite predicate-device-equivalent visualization hardware launches. Academic medical centers in Boston and the Research Triangle pilot head-mounted display technologies for prolonged spinal procedures.
Germany
Academic medical centers in Bavaria and Baden-Württemberg drive augmented reality adoption for precision oncology applications. EU MDR Article 10 technical documentation requirements extend certification timelines by 12-18 months for novel visualization modalities. The Stuttgart-Karlsruhe corridor anchors rigid endoscope refurbishment economics.
Japan
PMDA electrical safety and biocompatibility standards filter non-compliant imports while METI promotes domestic manufacturing. Tokyo and Osaka academic medical centers concentrate investment in integrated microscope-navigation systems for neurosurgery. Sony's CMOS sensor dominance creates single-source supply vulnerability for surgical camera components.
India
Greenfield medical cities in Gujarat and Tamil Nadu specify integrated visualization suites without legacy compatibility constraints. CDSCO medical device regulations tighten import quality standards while PLI scheme incentives attract domestic assembly operations. Hyderabad and Bengaluru emerge as procurement hubs for South Asian hospital networks.
South Korea
MFDS enforces stringent software-as-a-medical-device classifications for AI-enhanced visualization algorithms. Seoul Capital Area hospitals compress replacement cycles as 4K resolution becomes minimum viable specification. Busan-Ulsan manufacturing clusters supply display panel components for regional OEM integration.
Global Surgical Visualization Systems Market Competitive Landscape
Diversified conglomerates and specialized endoscope manufacturers split the market across premium integrated platforms and modular component tiers. Concentration remains moderate with consolidation pressure from hospital procurement committee vendor rationalization. Three archetypes dominate: optical engineering specialists with century-long endoscope legacies, diversified medtech conglomerates bundling visualization with surgical navigation, and imaging sensor suppliers controlling upstream component supply. Competitive moves center on integrated operating room contract bundling and software-as-a-medical-device algorithm development.
Within the optical engineering tier, Karl Storz GmbH & Co. KG and Richard Wolf GmbH exemplify German precision manufacturing heritage. Olympus Corporation anchors the Asia-Pacific installed base through endoscope service contract penetration. Stryker Corporation represents the diversified conglomerate archetype with integrated platform bundling capabilities.
| Leading Market Players |
|---|
| Olympus Corporation |
| Stryker Corporation |
| Karl Storz GmbH & Co. KG |
| Medtronic |
| Fujifilm Corporation |
| B. Braun Melsungen AG |
| Conmed Corporation |
| Boston Scientific Corporation |
| Richard Wolf GmbH |
| Others |
Supply & Pricing Matrix
The Stuttgart-Karlsruhe corridor in Germany anchors rigid endoscope refurbishment capacity, and its throughput constraints amplify pricing power for premium visualization platforms serving academic medical centers with extended equipment lifecycles. CMOS sensor fabrication concentration in Japan and the United States feeds directly into camera head cost structures, while ambulatory surgery center procurement committees exploit modular component sourcing to compress capital outlays.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across the United States market, separating predicate-device-equivalent hardware from novel modality premiums. Three-tier pricing structure across premium integrated platforms, standard modular components, and economy refurbished units captures hospital system consolidation effects. Cost compression in the economy tier is intensifying because single-use endoscope alternatives eliminate sterilization infrastructure investments. Ambulatory surgery centers exhibit highest price sensitivity due to capital constraint structures, while academic medical centers absorb premium positioning for research-aligned technologies.
Supply Chain Analysis
CMOS image sensors feed from fabrication facilities concentrated in Japan, the United States, and Taiwan, with Sony and OmniVision controlling surgical camera component supply. Optical glass for rigid endoscope rod lenses draws from German and Japanese specialty manufacturers, while display panel assembly rests on South Korean and Chinese production clusters. Single-source vulnerability around Sony sensor supply creates procurement risk for camera head manufacturers. Distribution runs through direct hospital system contracts and specialized medical device distributors serving mid-sized facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surgical visualization market is recovering from capital equipment deferral cycles, with hospital replacement programs reaccelerating as 4K resolution becomes non-negotiable in tender specifications.
For Market Incumbents: Insulate installed base profitability through endoscope refurbishment program expansion and captive service contract renewal. Olympus Corporation's Asia-Pacific hospital penetration demonstrates how recurring revenue streams offset hardware margin compression. Backward integration into CMOS sensor supply negotiations reduces single-source exposure from Japanese fabrication concentration. For New Entrants and Emerging Players: Build out compact visualization platform portfolios targeting ambulatory surgery center expansion in the United States and greenfield medical cities in India. Software-as-a-medical-device reclassification creates white-space for AI-enhanced image processing algorithms with recurring SaaS revenue models. Hospital procurement committee vendor rationalization favors component specialists with rapid FDA 510(k) clearance capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified conglomerates with integrated operating room bundling capabilities over pure-play optical engineering specialists. Long-term viability hinges on algorithmic differentiation moats in augmented reality overlay and fluorescence imaging modalities. The signal to watch is EU MDR certification timeline compression as conformity assessment body capacity expands.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Streamlining | Expedited predicate-device pathways reduce time-to-revenue for iterative camera head improvements. |
| Software-as-a-Medical-Device Development | AI-enhanced algorithms create recurring revenue streams separate from hardware sales cycles. |
| Integrated Operating Room Bundling | Single-source agreements covering visualization, insufflation, and energy platforms displace component purchasing. |
| EU MDR Conformity Assessment Investment | Front-loaded technical documentation resources compress 12-18 month certification timeline extensions. |
| Ambulatory Surgery Center Partnership | Compact platform specifications address space constraints in freestanding outpatient facilities. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, hospital procurement databases, and CMS Medicare equipment reimbursement data anchors the qualitative findings. Clinician input from academic medical centers in Germany and Japan informed technology adoption trajectory assessments. Bottom-up segment sizing triangulates against top-down health system capital expenditure patterns.
Calibration against historical replacement cycle data and tender specification evolution across the analysis window informs the projection framework. Segmentation dimensions span product type, technology modality, surgical application, and end-user facility tier. CAGRs derive from equipment installed base depreciation schedules and resolution upgrade elasticity. Fluorescence imaging protocol expansion rates and head-mounted display pilot program outcomes supply procedure-specific forecast inputs.
Sensitivities concentrate around EU MDR certification timeline volatility and CMOS sensor supply disruption scenarios. Forecasts reflect assumptions regarding hospital capital budget recovery trajectories and ambulatory surgery center site-of-care migration velocity. Quarterly review of FDA 510(k) clearance cadences and health system bundling contract announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Alpha Emitter Market
Medical Devices
Catheter Coatings Market
Medical Devices
Global Hernia Mesh Devices Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Mobile Healthcare Devices Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Implantable Neurostimulation Device EMI and Safety Test Systems Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Implantable Port Devices Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Auto Keratometer Market
Medical Devices
Subcutaneous Injection Ports Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market