
 Global Home Healthcare Software Market | 2026-2036
Global Home Healthcare Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Healthcare Software Market Foresight
Cloud-native infrastructure is broadening the addressable market for home healthcare software beyond traditional enterprise buyers. Cerner leverages its EHR integration depth to anchor large health system deployments. WellSky competes across post-acute and human services verticals with specialized workflow tools. AlayaCare differentiates through AI-driven scheduling optimization for mid-market home health agencies.
Home healthcare software encompasses clinical, operational, and financial management platforms designed for care delivery outside institutional settings. These systems integrate real-time patient monitoring data, electronic visit verification timestamps, and billing code automation to coordinate distributed care teams. Cloud-based deployment leads the market as providers prioritize elastic scalability and reduced IT overhead. Remote patient monitoring represents the fastest-growing solution category, driven by reimbursement expansion for connected physiologic devices. Billing and scheduling remains the most mature segment, though margin pools are compressing as vendors bundle these capabilities into platform suites.
The FDA regulates software-as-medical-device classifications for diagnostic algorithms embedded in home health platforms, while HIPAA mandates encryption standards for patient data transmission across mobile endpoints. The EU AI Act introduces conformity requirements for clinical decision-support tools deployed in European home care settings. Stakeholders must monitor evolving reimbursement rules for remote therapeutic monitoring as Medicare and national health services recalibrate coverage thresholds.
Market Dynamics
Cloud-native infrastructure is consolidating vendor positions across the home healthcare software landscape, as providers abandon on-premise installations for elastic platforms that reduce IT overhead and accelerate deployment cycles.
Growth Catalysts
- Medicare reimbursement expansion:The US Centers for Medicare and Medicaid Services has broadened coverage for remote therapeutic monitoring CPT codes, directly expanding addressable revenue pools for connected care platforms.
- EU AI Act compliance deadlines:European home care agencies face mandatory conformity assessments for clinical decision-support algorithms, forcing procurement of certified software suites before enforcement windows close.
- Japan's super-aged society:METI's Society 5.0 initiative funds municipal deployments of integrated home health platforms to manage chronic disease burden among the world's oldest population cohort.
Market Restraints
- Interoperability fragmentation:Proprietary data formats from legacy EHR vendors create integration friction that prolongs implementation timelines and inflates professional services costs.
- Cybersecurity liability concentration:HIPAA breach notification requirements and state-level privacy laws expose home health agencies to catastrophic penalties from endpoint vulnerabilities in distributed care networks.
- Skilled nursing labor scarcity:Clinical workforce shortages in the United States and Germany constrain the operational bandwidth available to deploy and optimize software-enabled care models.
Strategic Opportunities
- Brazil's ANVISA digital health pathway:Regulatory clarity for software-as-medical-device classifications opens Latin America's largest home care market to validated international platforms.
- Voice-first interfaces:Natural language processing convergence with ambient clinical documentation enables hands-free data capture for mobile caregivers in patient homes.
- Direct-to-employer channels:Self-insured corporations in the United States are contracting home health platforms as population health benefits, bypassing traditional payer intermediaries.
Industry Challenges
- API integration complexity:Home health agencies struggle to synchronize real-time biometric streams from heterogeneous connected device fleets into unified clinical workflows.
- Clinical informatics talent gaps:Mid-market providers lack specialized staff to configure population health analytics and quality reporting modules within purchased platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Healthcare Software Market |
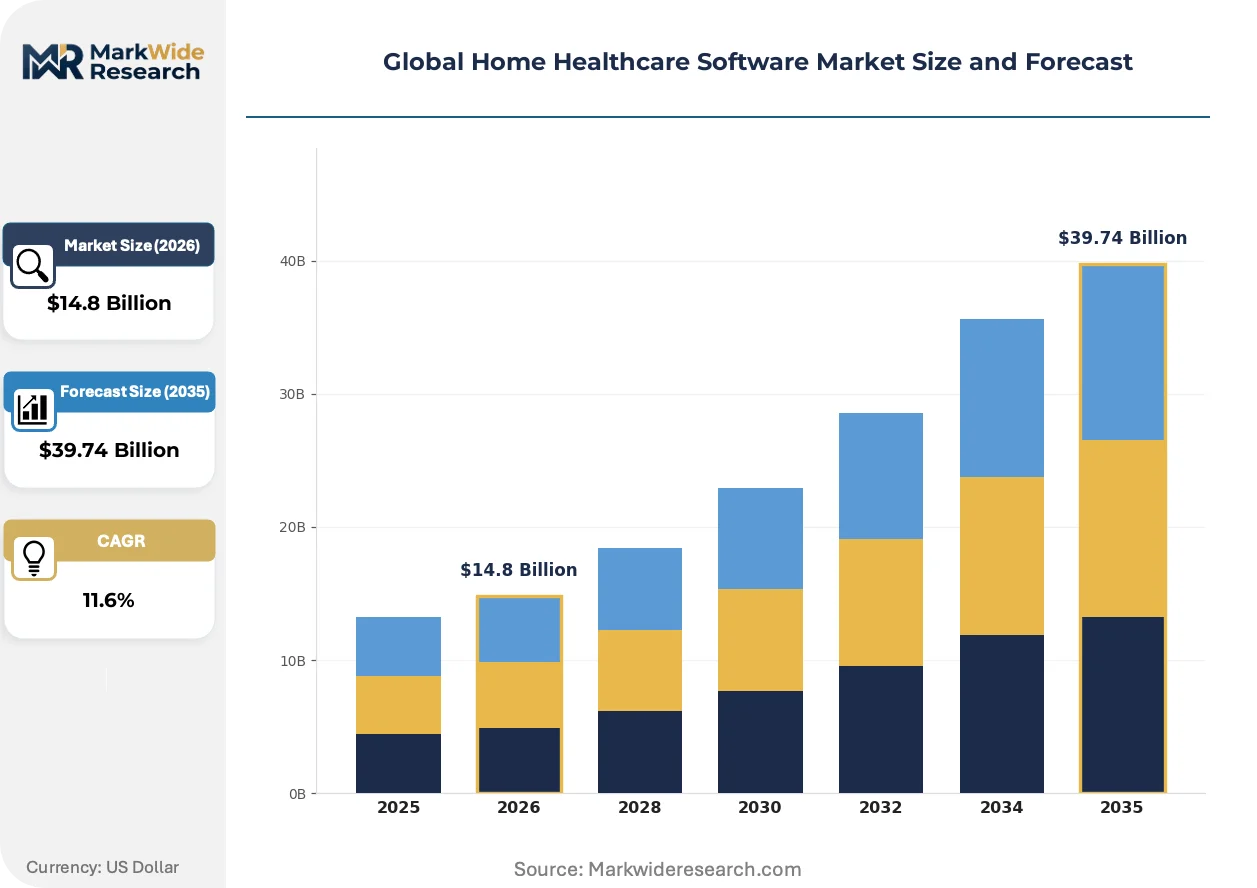
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Care Coordination, Remote Patient Monitoring, Electronic Visit Verification, Billing & Scheduling, Analytics Platforms Use Case: Chronic Disease Management, Post-Acute Care, Elderly Care Management, Pediatric Care, Physical Therapy Monitoring End User: Skilled Nursing Providers, Home Health Agencies, Hospice Care Providers, Rehabilitation Centers, Assisted Living Facilities |
| Companies Covered | Homecare Homebase, Allscripts, WellSky, McKesson, Cerner, Netsmart Technologies, AlayaCare, Kinnser Software, MatrixCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Healthcare Software Market Shifts & Advancements
Artificial intelligence is penetrating core operational functions of home healthcare software, compressing manual scheduling and documentation burdens while raising new questions about algorithmic accountability in clinical settings.
Machine learning-driven predictive scheduling is consolidating workforce management platforms across the home health sector. These algorithms analyze historical visit duration patterns, travel time between patient locations, and acuity indicators to optimize caregiver routes. Large multi-site agencies in Germany and the United States are deploying these tools at scale, reducing overtime costs and improving visit completion rates. The technology is consolidating competitive advantage around vendors with proprietary training datasets derived from millions of historical encounters.
The EU AI Act's risk classification framework is reshaping product development roadmaps for clinical decision-support modules. High-risk algorithms supporting diagnostic or treatment recommendations now require conformity assessments, technical documentation, and human oversight protocols before European market entry. Home health software vendors are restructuring European deployments to segregate AI-enabled features from baseline workflow tools, with Germany and France representing the most stringent enforcement environments.
Subscription pricing for platform access is displacing perpetual license models across buyer segments in the United States and Japan. Home health agencies prefer operational expenditure treatment and embedded technical support over capital-intensive upfront investments. This shift favors established cloud-native vendors with proven infrastructure economics, while pressuring legacy on-premise providers to accelerate SaaS transitions or exit mid-market segments entirely.
Global Home Healthcare Software Market Segmentation
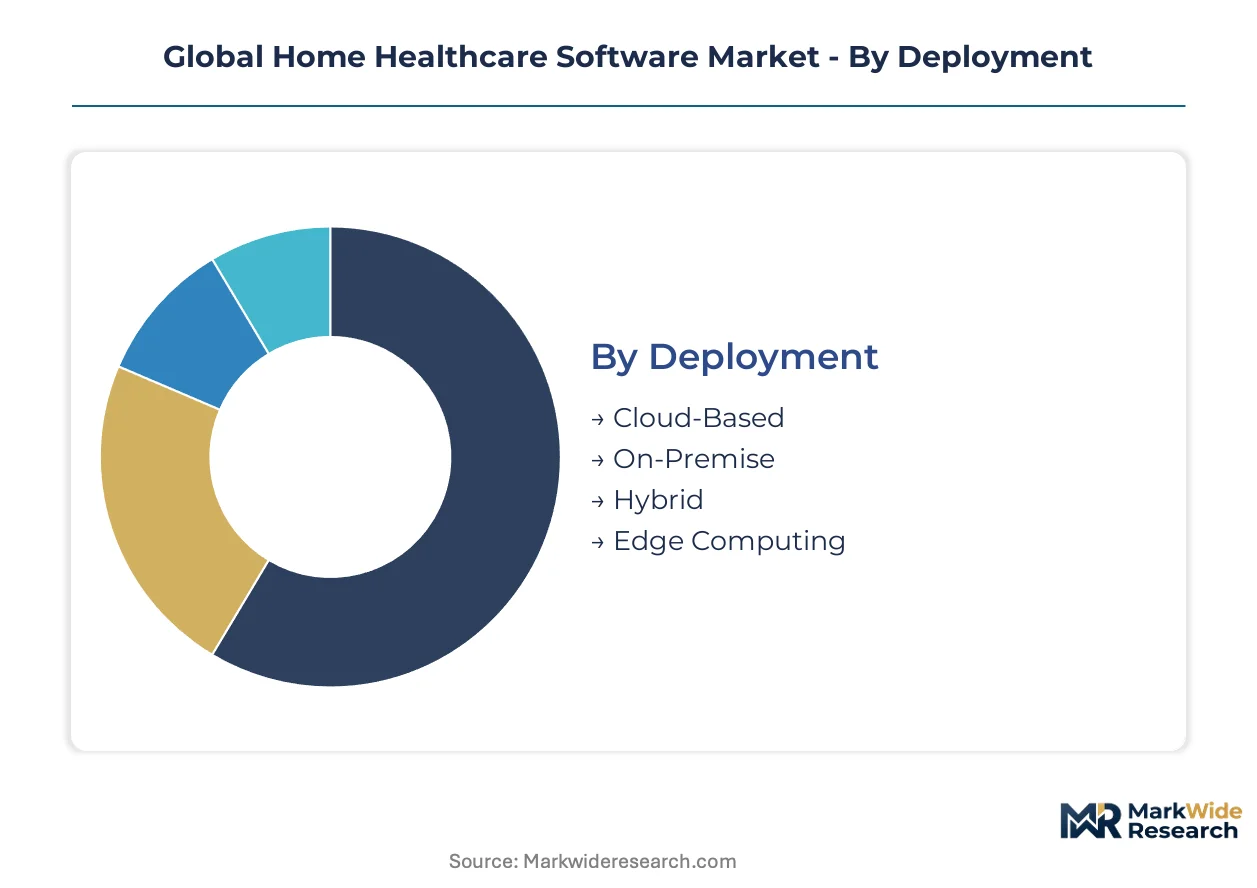
Home healthcare software segments diverge sharply by infrastructure requirements and clinical workflow complexity. Deployment architecture determines total cost of ownership, while solution specialization dictates which provider types can extract measurable operational returns.
Deployment:
Supply concentration among hyperscale cloud providers is reshaping how home health agencies provision infrastructure.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for seasonal patient census fluctuations. United States home health agencies dominate procurement volumes, driven by Medicare reimbursement pressure to minimize capital expenditure.
- On-Premise:Dedicated server installations within agency data centers retain appeal for large skilled nursing providers with legacy IT security mandates. Germany enforces strict data residency requirements that sustain regional demand despite higher operational overhead.
- Hybrid:Split workloads route sensitive patient data through on-premise nodes while offloading analytics to public cloud. Mid-market agencies in Japan favor this model to balance METI cloud guidelines with local privacy preferences.
- Edge Computing:Distributed processing nodes at patient residences enable real-time biometric analysis with minimal latency. Physical therapy monitoring applications in rural United States markets drive pilot deployments.
Cloud-Based deployments absorb the bulk of installed capacity; Edge Computing is expanding most quickly.
Solution Offering:
Cost tier differentiation separates enterprise-grade platforms from point solutions targeting specific workflow bottlenecks.
- Care Coordination:Unified dashboards synchronize multidisciplinary teams across distributed patient populations. Home health agencies in Germany deploy these systems to comply with EU AI Act documentation requirements for care pathway algorithms.
- Remote Patient Monitoring:Continuous physiologic data streams from connected devices feed predictive analytics engines. United States reimbursement expansion for remote therapeutic monitoring CPT codes accelerates adoption among skilled nursing providers.
- Electronic Visit Verification:GPS-timestamped mobile applications document caregiver arrival and departure for compliance auditing. State Medicaid programs mandate these tools, creating captive demand.
- Billing & Scheduling:Revenue cycle automation integrates visit documentation with claims submission workflows. Mature functionality compresses margins as vendors bundle capabilities into broader suites.
- Analytics Platforms:Population health dashboards aggregate outcomes data for quality reporting and contract negotiation. Hospice care providers leverage these tools to demonstrate value-based care performance.
Billing & Scheduling retains the deepest installed base; Remote Patient Monitoring is climbing the fastest.
Use Case:
Application maturity varies by clinical complexity and reimbursement stability across patient populations.
- Chronic Disease Management:Longitudinal tracking of diabetes, heart failure, and COPD progression through connected devices. Japan's super-aged society drives municipal platform deployments under Society 5.0 funding.
- Post-Acute Care:Transition coordination from hospital discharge to home recovery with medication reconciliation and wound care protocols. United States health systems prioritize these tools to reduce readmission penalties.
- Elderly Care Management:Comprehensive assessment and monitoring for functional decline in aging populations. German statutory long-term care insurance funds platform subscriptions for approved agencies.
- Pediatric Care:Family-centered documentation and developmental milestone tracking for home-based nursing. Smaller addressable market limits vendor specialization.
- Physical Therapy Monitoring:Exercise adherence verification through motion sensors and video analysis. Direct-to-employer contracts in the United States bypass traditional payer channels.
Chronic Disease Management commands the largest revenue pool; Physical Therapy Monitoring is gaining share fastest.
End User:
Customer type determines procurement sophistication and platform configuration requirements.
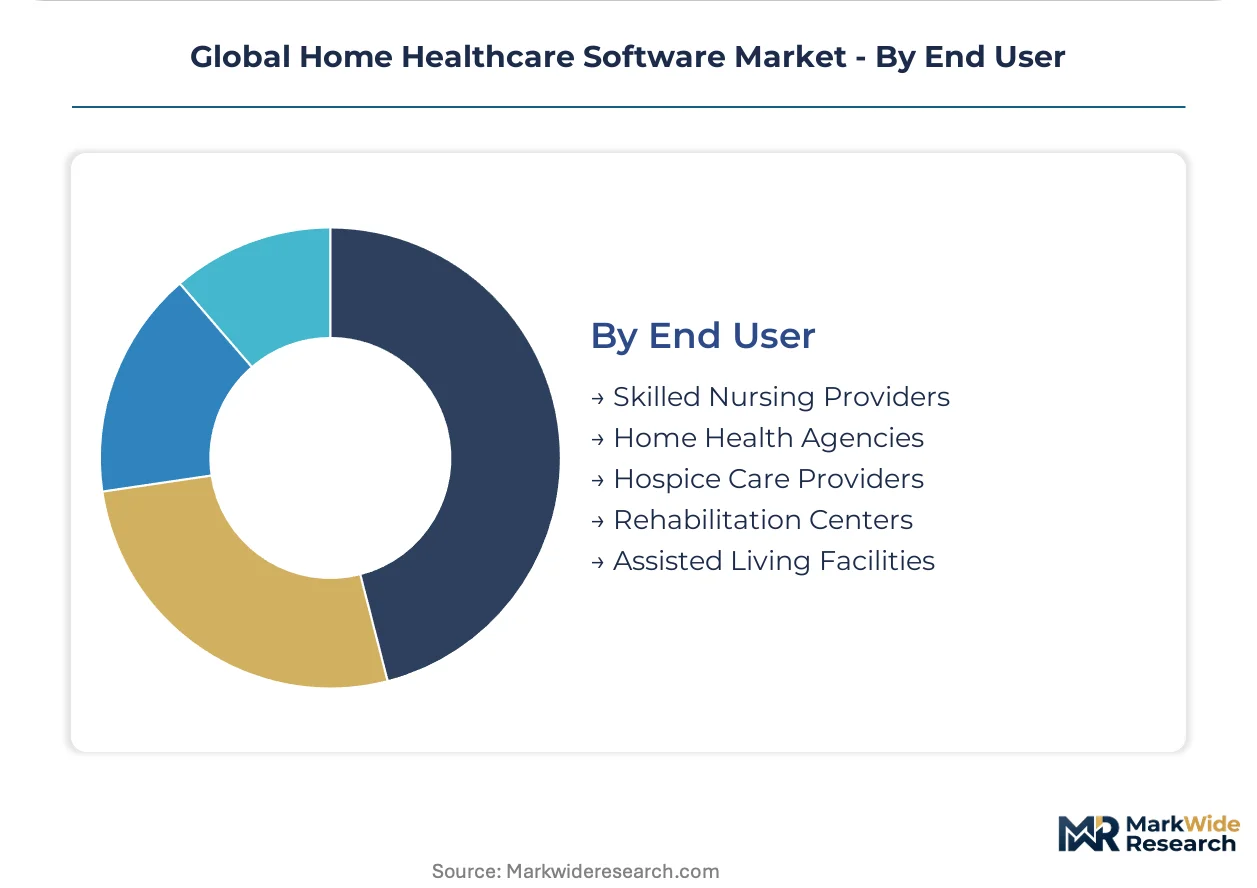
- Skilled Nursing Providers:Licensed clinical staff delivering complex medical interventions in patient homes. United States agencies face HIPAA breach notification exposure that drives cybersecurity investment.
- Home Health Agencies:Medicare-certified organizations coordinating episodic care under prospective payment systems. Cloud migration dominates technology roadmaps to reduce IT overhead.
- Hospice Care Providers:Palliative and end-of-life services requiring specialized documentation for bereavement and spiritual care. Regulatory complexity sustains demand for purpose-built modules.
- Rehabilitation Centers:Outpatient therapy practices extending services into home settings. Smaller scale limits enterprise software adoption.
- Assisted Living Facilities:Residential care settings integrating health monitoring with hospitality operations. Family communication features differentiate vendor selection.
Home Health Agencies represent the dominant customer segment; Hospice Care Providers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Home healthcare software procurement concentrates in the United States, Germany, and Japan, where aging demographics and reimbursement policy shifts create concentrated demand for cloud-based clinical platforms.
United States
Medicare-certified home health agencies drive cloud migration to reduce IT overhead and capture expanded remote therapeutic monitoring reimbursements. CMS has broadened CPT code coverage for connected physiologic devices, directly expanding addressable revenue pools for platform vendors. The Boston-to-Washington corridor hosts the densest concentration of health system deployments, with large multi-site agencies in Texas and Florida accelerating predictive scheduling adoption.
Germany
Statutory long-term care insurance funds platform subscriptions for approved home care agencies managing elderly populations. The EU AI Act mandates conformity assessments for clinical decision-support algorithms, forcing procurement of certified software suites before enforcement windows close. North Rhine-Westphalia and Bavaria lead municipal deployments, with Cologne-based agencies piloting integrated chronic disease management systems under regional digital health initiatives.
Japan
METI's Society 5.0 initiative funds municipal deployments of integrated home health platforms to manage chronic disease burden among the world's oldest population cohort. The super-aged society drives demand for voice-first interfaces and ambient documentation tools that reduce caregiver documentation burden. Tokyo and Osaka anchor health technology procurement, with Fukuoka emerging as a testbed for edge computing deployments in rural physiologic monitoring.
United Kingdom
NHS England's digitization mandates push integrated care systems toward unified patient record platforms spanning hospital and home settings. GDPR compliance requirements and national cybersecurity standards reshape vendor selection criteria for community health providers. London and the Southeast concentrate health technology procurement, while Manchester and Birmingham health systems pilot remote patient monitoring for post-acute discharge management.
Brazil
ANVISA's digital health pathway provides regulatory clarity for software-as-medical-device classifications, opening Latin America's largest home care market to validated international platforms. Private health insurers in São Paulo and Rio de Janeiro drive demand for billing automation and electronic visit verification tools. The Southeast region concentrates procurement activity, with Belo Horizonte emerging as a hub for telehealth-integrated home nursing platforms.
Global Home Healthcare Software Market Competitive Landscape
Platform consolidation dominates the current landscape as cloud-native vendors absorb mid-market competitors and legacy on-premise providers accelerate SaaS transitions. The vendor base separates into three tiers: enterprise health system integrators with EHR depth, specialized post-acute workflow providers, and AI-native challengers attacking scheduling optimization. Strategic archetypes include vertical specialists bundling human services capabilities, horizontal platform players prioritizing interoperability, and point-solution vendors defending niche billing segments. M&A activity and API ecosystem expansion represent the dominant competitive vectors reshaping market structure.
Within the enterprise integration tier, Cerner leverages health system relationships to anchor large deployments, while WellSky competes across post-acute and human services verticals with specialized workflow depth. AlayaCare exemplifies the AI-native challenger archetype, differentiating through machine learning-driven scheduling optimization purpose-built for mid-market home health agencies. These three anchors illustrate how competitive positioning stratifies around infrastructure scale, vertical specialization, and algorithmic capability respectively.
| Leading Market Players |
|---|
| Homecare Homebase |
| Allscripts |
| WellSky |
| McKesson |
| Cerner |
| Netsmart Technologies |
| AlayaCare |
| Kinnser Software |
| MatrixCare |
| Others |
Supply & Pricing Matrix
Cloud infrastructure costs cascade through subscription tiers as hyperscale compute pricing from AWS, Microsoft Azure, and Google Cloud Platform feeds directly into SaaS vendor margins and end-user licensing structures. HIPAA-compliant data residency requirements in Germany and Japan force premium pricing for localized server deployments, segmenting the market by regulatory overhead rather than feature depth alone.
Pricing Analysis
Volume concentrates in mid-market SaaS tiers while margin pools shift toward enterprise integrations with EHR systems. Three-tier pricing structure across premium, standard, and economy levels reflects deployment complexity, with premium tiers bundling AI-driven scheduling and predictive analytics. Pricing pressure stems from vendor consolidation as platform suites absorb point solutions and compress standalone module margins. Home health agencies with fewer than 500 patients exhibit highest price sensitivity, while integrated health systems prioritize interoperability over cost.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud providers in the United States, where AWS, Microsoft, and Google concentrate global infrastructure capacity. Software development draws from distributed engineering talent pools in India, Poland, and Vietnam, with API middleware components sourced from Israel and Ireland. Supply chain risk centers on regulatory fragmentation as EU AI Act conformity assessments delay European feature rollouts. Distribution runs through direct enterprise sales teams and channel partners serving mid-market agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compliance costs function as a structural moat in this market, with FDA digital health guidance and HIPAA breach notification requirements raising capital barriers that favor established cloud-native vendors over point-solution challengers.
For Market Incumbents: Extend platform consolidation through targeted acquisition of AI-native scheduling specialists and voice-first documentation tools. Cerner and WellSky should deepen EHR integration moats before emerging challengers achieve interoperability parity. Cloud infrastructure scale remains the priority lever for margin defense. For New Entrants and Emerging Players: Begin with edge computing deployments for rural physiologic monitoring in the United States and Japan, where latency requirements and METI funding create white-space opportunity. Target physical therapy monitoring for direct-to-employer contracts, bypassing entrenched payer channels through outcome-based pricing models. For Investors and Strategic Acquirers: ANVISA digital health pathway clearances in Brazil are the leading indicator that Latin American market entry timing is compressing, with São Paulo and Rio de Janeiro health systems accelerating procurement cycles. Acquisition targets should demonstrate EU AI Act technical documentation readiness or FDA software-as-medical-device classification. Long-term viability hinges on recurring revenue density above patient monitoring device integration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deepens EHR connectivity with Cerner and Epic systems to anchor health system deployments. |
| Acquisition of Specialist Firm | Absorbs AI-native scheduling vendors to compress workforce optimization development timelines. |
| Regulatory Certification Pathway | Secures EU AI Act conformity assessments ahead of enforcement windows in Germany and France. |
| Geographic Expansion | Establishes localized data centers in Japan to satisfy METI cloud guidelines and privacy preferences. |
| Strategic Partnership | Contracts with Medicare Advantage plans to embed remote therapeutic monitoring into bundled payments. |
Research Methodology
CMS Medicare reimbursement databases, FDA 510(k) clearance filings, and EU AI Act implementation guidance formed the secondary backbone for demand-side validation. Primary interviews with home health agency CIOs, HIPAA compliance officers, and GPO contracts managers triangulated against secondary sources including hospital procurement databases and cloud vendor capex disclosures. Bottom-up patient census modeling and top-down health system IT budget analysis converged on segment-level estimates.
Bottom-up deployment counts by agency size and electronic visit verification mandate status anchored volume estimates across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution specialization, clinical use case, and end-user organization type. CAGRs derived from elasticity-adjusted reimbursement expansion curves and cloud infrastructure cost deflation trends, with remote patient monitoring adoption curves and AI scheduling penetration rates serving as key forecast inputs.
Underlying measurement precision varies by segment; cloud-based deployment and billing-scheduling modules carry tighter precision than emerging edge computing and voice-first interface categories. Forecasts reflect assumptions around Medicare CPT code stability, EU AI Act enforcement timing, and cloud vendor pricing continuity. Cybersecurity breach frequency, skilled nursing labor availability, and interoperability standard adoption represent specific risk factors that could revise trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Healthcare
House Call Market
Home Healthcare
Elder Care Products Market
Home Healthcare
Smart Home Healthcare Market
Home Healthcare
Europe Home Care Market
Home Healthcare
US House Calls Market
Home Healthcare
Senior in-Home Care Services Market
Home Healthcare
Home Healthcare Market
Home Healthcare
US Home Healthcare Services Market
Home Healthcare
Home Care Service Market
Home Healthcare
Elder Care Subscription Market
Home Healthcare
Elderly Care Apps Market
Home Healthcare
Portable Toilet for Elderly Market
Home Healthcare
Smart Mattress Market
Home Healthcare
Smart Pillow Market
Home Healthcare
Global Elderly Care Market
Home Healthcare
Home Care Market