
 Europe Otoscope Market | 2026-2036
Europe Otoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Otoscope Market Insights
German optical instrument manufacturing is repositioning toward higher-precision otoscope production for European hospital networks. Heine Optotechnik leverages its Ruhr Valley engineering base to sustain premium fiber optic leadership. Riester competes through specialized ENT diagnostic portfolios across Central European clinics. Karl Storz SE & Co. anchors its position via rigid endoscopy expertise that extends into advanced otologic visualization systems.
An otoscope is a handheld diagnostic instrument combining a light source and magnifying lens for examining the external auditory canal and tympanic membrane, typically employing halogen, LED, or fiber optic illumination with speculum attachments ranging from 2.5mm to 4.0mm diameter for pediatric and adult anatomy. Digital otoscopes with integrated CMOS sensors and wireless image transmission now dominate capital procurement in tertiary hospitals, while handheld otoscopes retain volume leadership in primary care settings where portability and cost structure determine purchasing patterns. LED illumination technology captures expanding share from legacy halogen systems due to longer service intervals and color temperature stability that improves tympanic membrane assessment accuracy.
EMA's Medical Device Regulation and CE marking requirements under the EU Medical Device Regulation shape product registration pathways and clinical evidence standards for otoscope manufacturers seeking European market access. REACH compliance and RoHS substance restrictions additionally govern material selection for optical housings and electronic components. Stakeholders must monitor reimbursement coding evolution for digital otoscopy in national health systems and the pace of fiber-to-LED technology substitution in public procurement frameworks.
Market Dynamics
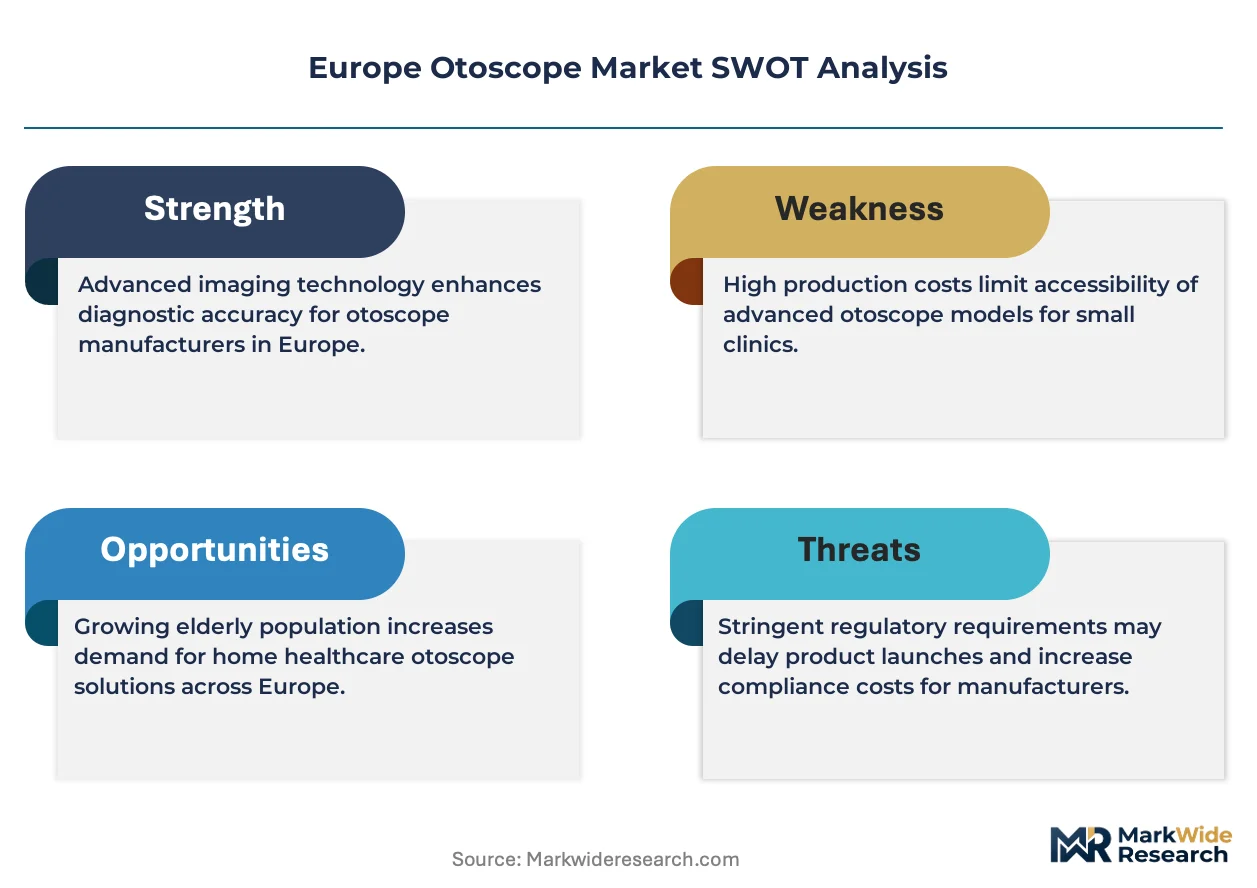
Fiber-to-LED technology substitution is compressing replacement cycles across European hospital procurement frameworks, while EMA's Medical Device Regulation elevates clinical evidence thresholds for new market entrants.
Growth Catalysts
- EU MDR compliance pathways:Stricter quality thresholds under the Medical Device Regulation are filtering substandard imports and creating protected market space for certified European manufacturers.
- Aging demographic screening volumes:France and the United Kingdom are expanding routine auditory assessments in primary care networks, driving replacement demand for handheld diagnostic equipment.
- Fiber optic illumination:German ENT clinics are prioritizing premium visualization systems that reduce diagnostic uncertainty in tympanic membrane assessment.
Market Restraints
- Optical component concentration:Precision lens grinding capacity concentrates in southern Germany and Switzerland, creating single-source vulnerability for mid-tier manufacturers.
- CE marking timeline friction:Extended notified body review periods under MDR Article 52 are delaying product launches by 12-18 months for novel digital otoscope systems.
- Smartphone-based substitutes:Consumer-grade otoscope attachments with CMOS sensors are capturing price-sensitive primary care segments in southern European markets.
Strategic Opportunities
- Polish and Romanian clinic networks:Underpenetrated secondary cities in eastern Europe present first-mover potential for portable digital systems with wireless image transmission.
- REACH-compliant material innovation:Bio-based optical housings that satisfy substance restrictions open differentiation pathways in sustainability-focused Nordic procurement frameworks.
- Tele-ENT integration:Convergence of digital otoscopy with remote consultation platforms is creating bundled service opportunities in United Kingdom integrated care systems.
Industry Challenges
- Optomechanical engineering scarcity:Specialized talent for miniature illumination system design is concentrated among retiring cohorts in German and Austrian precision manufacturing clusters.
- Legacy system interoperability:Hospital IT departments face integration complexity when connecting new wireless otoscope outputs to established electronic health record architectures.
- Notified body capacity bottlenecks:MDR certification queues are forcing manufacturers to sequence market launches and delay revenue recognition from intended product rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Otoscope Market |
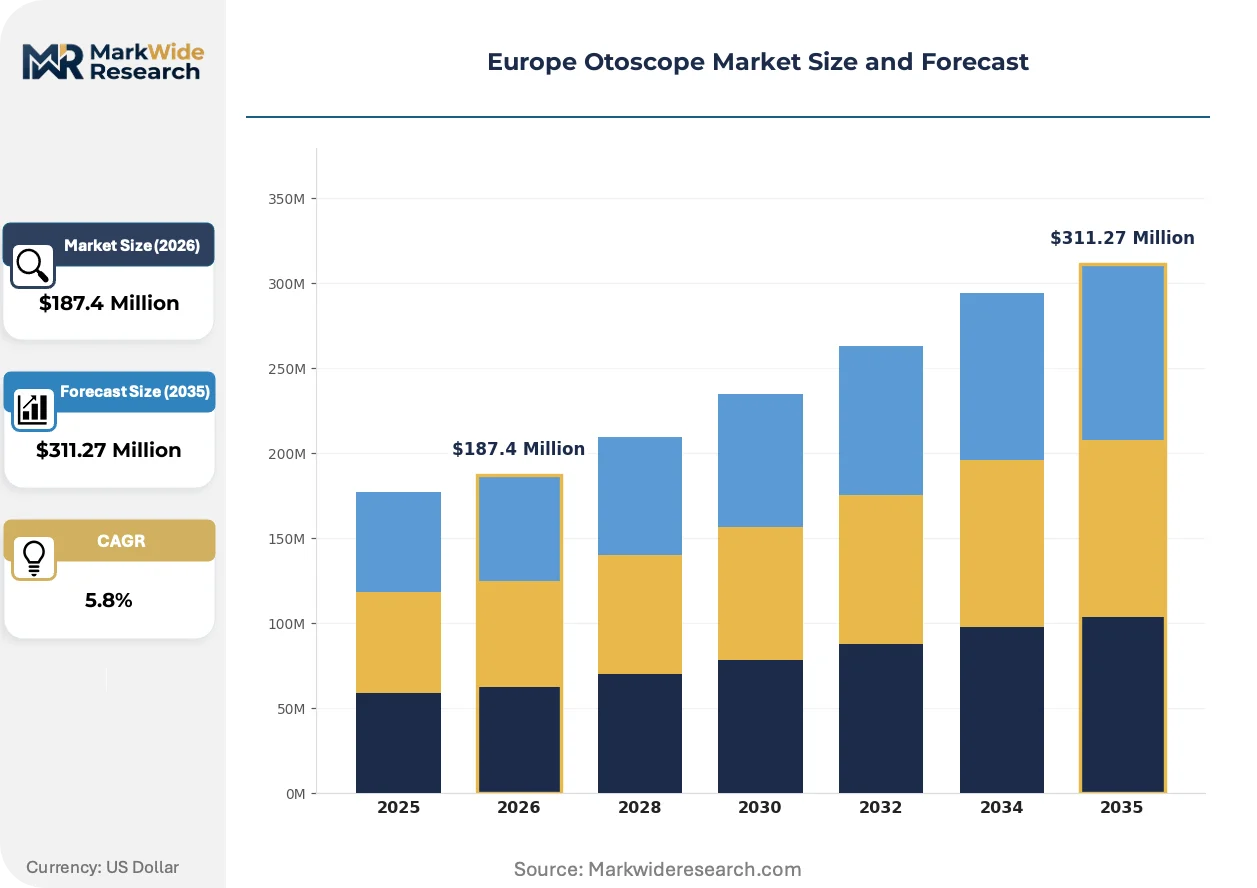
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Otoscopes, Video Otoscopes, Handheld Otoscopes, Standard Otoscopes End User: Hospitals, Clinics, Diagnostic Centers, Home Care Technology: Fiber Optic Technology, LED Illumination, Wireless Technology, Direct Visualization Application: Routine Check-ups, Ear Canal Examination, Tympanic Membrane Assessment, Diagnosis of Ear Disorders |
| Companies Covered | Heine Optotechnik GmbH & Co. KG, Riester GmbH & Co. KG, Welch Allyn, Medtronic plc, Olympus Europa SE & Co. KG, Karl Storz SE & Co., Luxamed GmbH & Co. KG, Richard Wolf GmbH, Orlvision GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Otoscope Market Trends and Innovations
Digital image capture is rewiring diagnostic workflows across European ENT departments, compressing the gap between examination and specialist consultation while elevating documentation standards for reimbursement.
CMOS sensor modules with integrated LED arrays are absorbing the illumination and imaging functions previously handled by separate fiber optic bundles. Tertiary hospitals in Germany and the Netherlands are adopting these systems for resident training programs, where stored image libraries support competency progression. The technology is absorbing capital budgets previously allocated to rigid endoscopy suites, enabling ward-level deployment of advanced visualization.
EMA's Medical Device Regulation is tightening post-market surveillance obligations for Class I reusable diagnostic instruments. Manufacturers must now maintain systematic complaint databases and trend analysis for otoscope-related adverse events. German and French notified bodies are applying heightened scrutiny to electrical safety testing for battery-powered digital variants, extending technical documentation requirements.
Buying committees in United Kingdom NHS trusts are consolidating supplier relationships and demanding extended warranty coverage with predictive maintenance provisions. Traditional equipment distributors are losing ground to manufacturer-direct service contracts that bundle device provision with staff training and software updates. This concentration is most visible in England's sustainability and transformation partnership regions, where procurement centralization favors vendors with national service infrastructure.
Europe Otoscope Market Segmentation
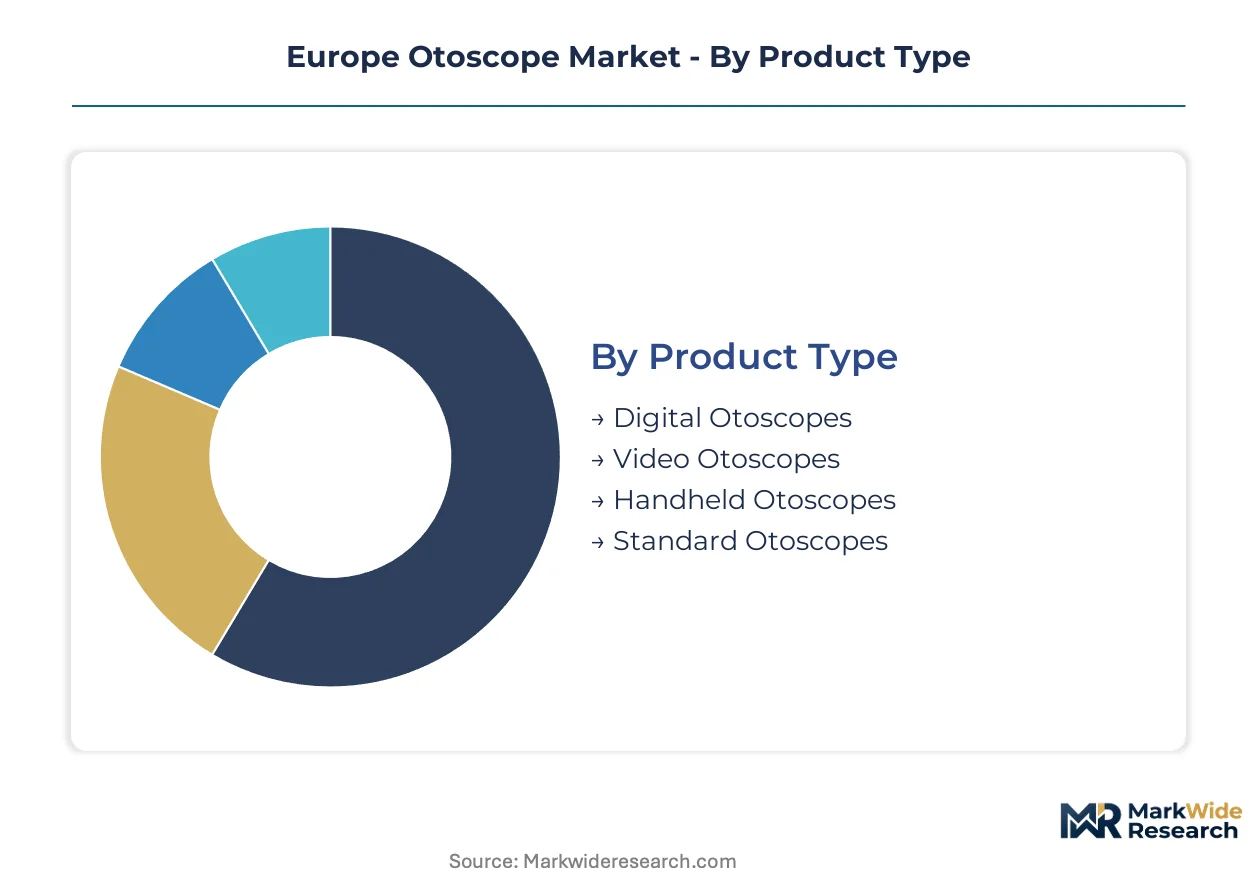
Segmentation in the Europe Otoscope Market reflects divergent procurement priorities across primary care networks and tertiary hospital systems. Technology substitution patterns and reimbursement frameworks create distinct demand profiles for each category.
Product Type:
Customization intensity varies sharply across this category, from configurable digital platforms to standardized handheld units.
- Digital Otoscopes:Integrated CMOS sensors capture high-resolution tympanic membrane images with wireless transmission to electronic health records. German and Dutch tertiary hospitals are absorbing these systems for resident training programs where image libraries support diagnostic competency progression.
- Video Otoscopes:External display connectivity enables real-time visualization during procedures and remote consultation support. United Kingdom NHS trusts are consolidating procurement around these systems for integrated care networks requiring tele-ENT capabilities.
- Handheld Otoscopes:Battery-powered portability dominates French and British primary care screening volumes.
- Standard Otoscopes:Conventional halogen or LED illumination retains cost-sensitive replacement cycles in southern European clinic networks.
Most installed capacity flows through Handheld Otoscopes. Expansion is steepest in Digital Otoscopes.
End User:
Procurement scale and technical specification intensity separate high-volume institutional buyers from dispersed point-of-care operators.
- Hospitals:Capital procurement committees prioritize wireless connectivity and EMA MDR compliance documentation. German university hospitals are absorbing premium fiber optic and digital systems for ENT department centralization.
- Clinics:French and British primary care networks drive replacement demand for portable screening equipment as aging demographic protocols expand routine auditory assessments.
- Diagnostic Centers:Specialized otology facilities in the Netherlands and Belgium concentrate demand for video-linked examination systems.
- Home Care:Consumer-grade smartphone attachments are capturing price-sensitive segments in southern European markets.
Clinics hold the largest installed base. Hospitals are climbing the fastest in absolute unit terms.
Technology:
Illumination source selection determines replacement cycle timing and service interval economics across procurement frameworks.
- Fiber Optic Technology:Cold light transmission through flexible bundles delivers superior color rendering for tympanic membrane assessment. German ENT clinics prioritize these systems for diagnostic certainty in complex otologic cases.
- LED Illumination:Solid-state arrays with stable color temperature and extended service intervals are displacing halogen in public procurement tenders. United Kingdom NHS sustainability frameworks favor LED for reduced maintenance burden.
- Wireless Technology:Bluetooth and Wi-Fi image transmission enables telemedicine integration and remote specialist consultation.
- Direct Visualization:Conventional optical pathways retain presence in cost-constrained primary care settings.
LED Illumination carries the dominant installed base. Wireless Technology is gaining share fastest as tele-ENT platforms mature.
Application:
Clinical purpose shapes specification requirements from basic screening to advanced diagnostic documentation.
- Routine Check-ups:High-volume screening protocols in French and British primary care networks demand durable, portable equipment with rapid speculum exchange.
- Ear Canal Examination:Visualization of external auditory canal pathology requires adjustable focus and multiple speculum diameters. German outpatient clinics prioritize ergonomic designs for high daily examination volumes.
- Tympanic Membrane Assessment:Precise color rendering and magnification distinguish normal from pathological findings in otitis media diagnosis.
- Diagnosis of Ear Disorders:Comprehensive otologic evaluation combines otoscopy with pneumatic and microscopic adjuncts in specialized ENT practice.
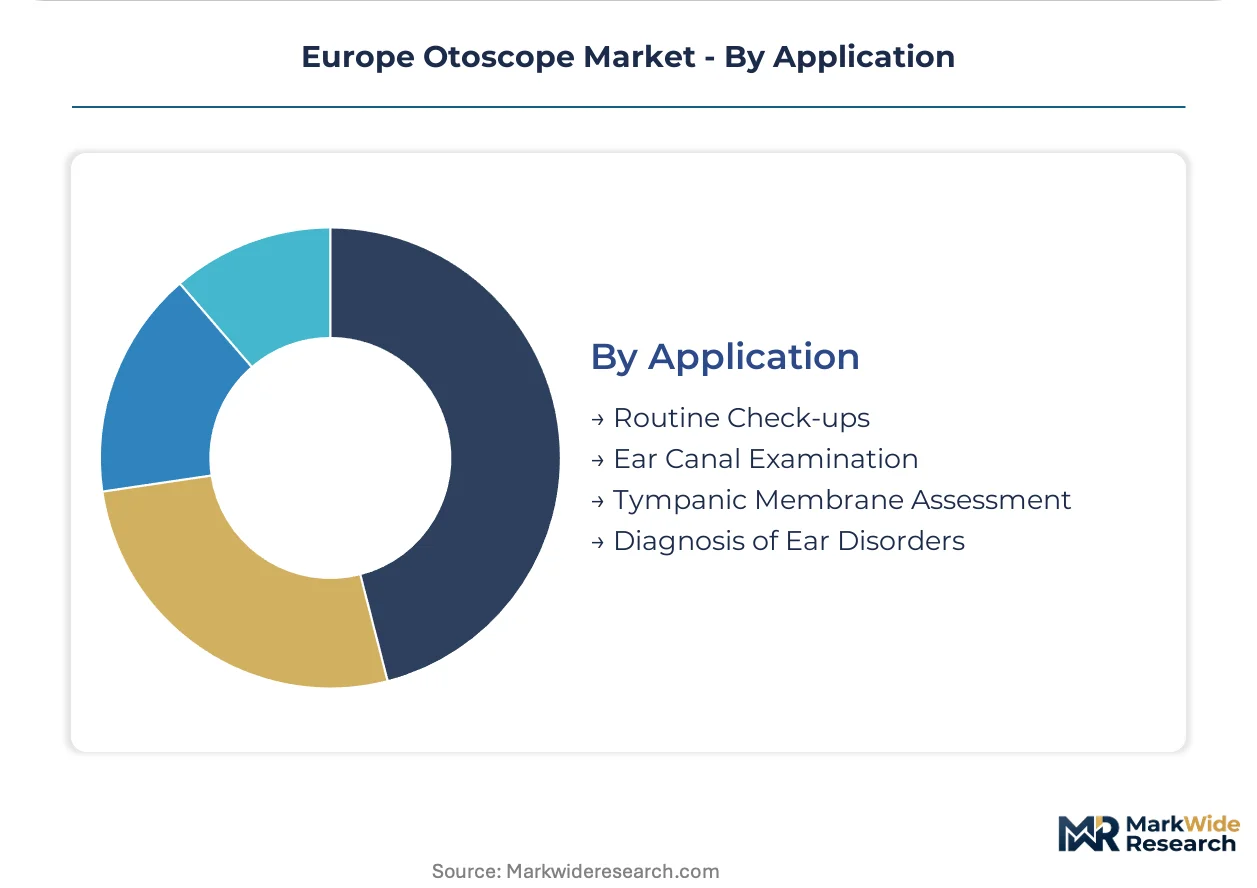
Routine Check-ups absorb the greatest equipment volume. Diagnosis of Ear Disorders commands the highest per-unit specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate assembly to jurisdictions with streamlined CE marking pathways under EU MDR. Cost-of-compliance gaps between established and emerging European manufacturing bases are accelerating facility investment decisions.
Germany
Ruhr Valley engineering clusters sustain precision optical instrument manufacturing for ENT diagnostic equipment. EMA's Medical Device Regulation enforcement through German notified bodies maintains stringent quality thresholds that filter substandard imports. Bavarian medical technology hubs around Munich and Nuremberg concentrate fiber optic assembly operations serving university hospital networks.
United Kingdom
NHS integrated care systems are consolidating procurement around digital otoscopy platforms with tele-ENT capabilities for remote consultation workflows. MHRA post-Brexit regulatory autonomy has introduced parallel registration requirements alongside residual CE marking obligations. London and Southeast England health technology clusters drive adoption of wireless image transmission systems in tertiary referral centers.
France
Aging demographic protocols are expanding routine auditory screening volumes across primary care networks in Île-de-France and regional hospital centers. ANSM national vigilance requirements supplement EU MDR compliance for post-market surveillance of reusable diagnostic instruments. Auvergne-Rhône-Alpes medical device manufacturing corridors supply portable handheld units for clinic-based screening programs.
Netherlands
Diagnostic centers in Randstad metropolitan corridors concentrate demand for video-linked examination systems enabling specialist remote consultation. Health Technology Assessment frameworks through ZIN influence reimbursement coding for digital otoscopy in hospital procurement. Eindhoven-region optoelectronics clusters supply CMOS sensor modules for integrated LED illumination systems.
Poland
Underpenetrated secondary city clinic networks present first-mover opportunities for portable digital systems with wireless image transmission capabilities. Polish notified body capacity under EU MDR is attracting manufacturers seeking accelerated certification timelines relative to Western European queues. Warsaw and Kraków medical distributor networks are expanding coverage for Central European ENT equipment markets.
Europe Otoscope Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital imaging integration and telemedicine connectivity. The vendor structure stratifies across three capability levels: precision optical heritage manufacturers, diversified medical technology conglomerates, and specialized digital diagnostic entrants. Two dominant competitive vectors are shaping positioning: backward integration into CMOS sensor supply chains and geographic expansion through distributor acquisition in underpenetrated Eastern European markets.
Among German precision engineering specialists, Heine Optotechnik GmbH & Co. KG and Riester GmbH & Co. KG exemplify the heritage optical instrument archetype with Ruhr Valley manufacturing lineage. Karl Storz SE & Co. occupies a position spanning rigid endoscopy expertise into advanced otologic visualization systems. Welch Allyn represents the diversified medical technology conglomerate model with broad diagnostic equipment portfolios.
| Leading Market Players |
|---|
| Heine Optotechnik GmbH & Co. KG |
| Riester GmbH & Co. KG |
| Welch Allyn |
| Medtronic plc |
| Olympus Europa SE & Co. KG |
| Karl Storz SE & Co. |
| Luxamed GmbH & Co. KG |
| Richard Wolf GmbH |
| Orlvision GmbH |
| Others |
Pricing and Supply Chain Analysis
Precision optomechanical engineering talent concentrated in Germany's Ruhr Valley and Bavarian manufacturing corridors creates labor-cost differentials that widen pricing-tier spreads between premium fiber optic systems and economy handheld units. EMA MDR compliance investments further stratify procurement budgets across European hospital networks.
Pricing Analysis
Distributor margins of 25-35 percent separate manufacturer list prices from end-user acquisition costs across European ENT equipment channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EU MDR Article 52 and volume-scale procurement by NHS trusts versus individual clinic purchases. Cost compression in economy handheld segments stems from smartphone-attachment substitutes penetrating southern European primary care markets. Price sensitivity peaks among Polish and Romanian clinic networks prioritizing wireless digital systems at lowest acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with precision lens grinding capacity concentrated in southern Germany and Swiss optical manufacturing clusters. CMOS sensor modules draw from Eindhoven-region optoelectronics suppliers and East Asian semiconductor foundries, while LED illumination arrays source from German and Austrian precision electronics manufacturers. Tariff exposure on Chinese electronic components creates margin volatility for mid-tier digital otoscope assemblers. Distribution runs through manufacturer-direct service contracts displacing traditional equipment distributors in United Kingdom and German hospital procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on LED-to-fiber technology substitution compressing service interval costs and enabling premium-tier positioning for integrated digital systems. Cost-down drivers in CMOS sensor commodification support profitability migration toward software-enabled tele-ENT platforms.
For Market Incumbents: To counter smartphone-based diagnostic attachments capturing price-sensitive primary care segments, Heine Optotechnik and Riester should deepen backward integration into CMOS sensor supply chains through Eindhoven-region partnerships. Certification investment in EU MDR technical documentation creates switching costs that protect German manufacturing margins against emerging Polish assembly competitors. For New Entrants and Emerging Players: Polish medical distributor networks offer the most penetrable channel infrastructure for portable digital otoscopes with wireless image transmission capabilities. Underpenetrated secondary city clinics in Romania and Bulgaria present white-space demand for tele-ENT-integrated examination systems. Go-to-market execution should prioritize CE marking acceleration through Polish notified body capacity relative to congested Western European queues. For Investors and Strategic Acquirers: Diversified medical technology conglomerates represent the most active acquirer category in this space, seeking digital diagnostic capabilities to complement rigid endoscopy portfolios. Acquisition targets with captive CMOS sensor relationships and established NHS service infrastructure command structural premiums. The signal to monitor is reimbursement coding evolution for digital otoscopy in French and British national health systems as inflection indicator for tele-ENT platform monetization.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 52 compliance unlocks protected market access for certified manufacturers. |
| Hospital System Partnership | NHS trust consolidation favors vendors with national predictive maintenance infrastructure. |
| Software Companion Development | Tele-ENT platform integration creates recurring revenue streams beyond device sales. |
| Backward Integration | Captive CMOS sensor supply insulates margins from semiconductor foundry volatility. |
| Reimbursement Strategy | ZIN and NICE coding alignment determines digital otoscopy adoption in procurement frameworks. |
Research Methodology
Coverage spans Western Europe, Central Europe, and Nordic markets, with primary inputs from each territory's hospital procurement networks and clinic distribution channels. Primary interviews with ENT clinicians, biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and medical device regulatory affairs specialists combined with secondary validation from EMA MDR guidance documents, NHS procurement databases, ANSM vigilance reports, and ZIN health technology assessments. Bottom-up equipment shipment tracking and top-down healthcare expenditure modeling provided triangulation across volume and value estimates.
Rate-of-change decomposition separated replacement cycle compression from technology substitution effects and demographic screening volume expansion across the projection horizon. Segmentation dimensions modeled include product type, end-user institution scale, illumination technology, and application purpose. CAGRs derived from equipment procurement pipeline analysis and reimbursement coding trajectory assessment. Forecast inputs incorporated EU MDR notified body queue lengths and REACH compliance material cost trajectories specific to optical housing production.
Revisions become necessary when EMA MDR enforcement intensity shifts, REACH substance restriction amendments materialize, or tele-ENT reimbursement coding achieves national health system adoption at differential speeds across European markets. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
AI Colonoscopy Withdrawal Quality Monitoring System Market
Medical Devices
Germany Aesthetic Devices Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
IV Fluid Transfer Drugs Devices Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
Crescent Ultrasonic Cleansers Market
Medical Devices
Urinary Collection Device Market
Medical Devices
Ultrasonic Aspirator Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Artificial Implants Market
Medical Devices
Cranial Navigation Systems Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Global Blood Banking Devices Market