
 Europe Minimally Invasive Surgery Devices Market | 2026-2036
Europe Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Minimally Invasive Surgery Devices Market Foresight
CE-marked Class III certification tiers is reorganizing procurement criteria across European hospital networks. Stryker Corporation leverages its endoscopy portfolio to sustain channel control in German university hospitals. Medtronic PLC anchors its position through deep specialization in energy devices for laparoscopic applications. Intuitive Surgical Inc. dominates robotic surgical system placements across French and Benelux markets.
Minimally invasive surgery devices encompass instruments, visualization systems, and energy platforms designed for procedures performed through small incisions under image guidance, typically utilizing 5-12 mm port diameters with 4K or 3D digital imaging resolution. These systems reduce tissue trauma, shorten recovery times, and lower postoperative complication rates compared to open surgical approaches. Robotic surgical systems command premium positioning due to capital intensity and software dependency, while laparoscopic instruments represent the mature volume base with replacement-driven revenue. Endoscopes benefit from optical technology refresh cycles, and energy devices capture margin pools through disposable blade and generator cartridge economics.
The EU Medical Device Regulation and EMA oversight reshape clinical trial obligations and post-market surveillance intensity for manufacturers seeking European market access. CE marking requirements under MDR extend conformity assessment timelines and elevate notified body scrutiny for reusable instrument reprocessing validation. Germany's BfArM and France's ANSM coordinate vigilance reporting standards that influence product design decisions across the supply base. Stakeholders must monitor reimbursement parity between robotic-assisted and conventional laparoscopic procedures as health technology assessment bodies in Italy and Spain finalize coverage frameworks.
Market Dynamics
The EU Medical Device Regulation is compressing conformity assessment timelines and elevating notified body scrutiny, forcing manufacturers to restructure clinical evidence portfolios and reprocessing validation protocols for reusable instruments across European hospital networks.
Growth Catalysts
- MDR Clinical Evidence Mandates:Stricter post-market surveillance requirements under EU MDR are accelerating hospital procurement of single-use instrument sets to mitigate reprocessing liability exposure.
- German Ambulatory Expansion:Hospitals across Germany are scaling same-day surgical programs for orthopedic interventions, expanding addressable procedure volumes for laparoscopic platforms.
- Robotic-Assisted Cardiac Demand:French and United Kingdom cardiac centers are prioritizing da Vinci system placements for mitral valve repair, driving capital equipment refresh cycles.
Market Restraints
- Notified Body Bottlenecks:CE marking capacity constraints under MDR are extending time-to-market for Class III devices by 12-18 months, freezing product pipeline velocity.
- Capital Intensity Thresholds:Robotic surgical systems require €2-3 million upfront investment plus annual service contracts, restricting placement feasibility to tier-one academic medical centers.
- Reimbursement Parity Gaps:Health technology assessment bodies in Italy and Spain have not established equivalent DRG codes for robotic-assisted versus conventional laparoscopic procedures, dampening adoption incentives.
Strategic Opportunities
- Poland and Czech Republic Penetration:Central European surgical centers remain under-equipped with advanced energy platforms, creating first-mover positioning for bipolar vessel sealing systems.
- 3D-Printed Patient-Specific Instruments:Convergence of additive manufacturing with preoperative imaging is enabling custom retractor and guide designs for complex hepatobiliary procedures.
- CE-MDR Software Classification:AI-enabled surgical planning tools with autonomous instrument guidance features are attracting premium pricing under new software-as-medical-device pathways.
Industry Challenges
- Reprocessing Validation Complexity:Reusable instrument manufacturers must demonstrate sterilization efficacy across 500+ use cycles to satisfy BfArM and ANSM vigilance standards, extending R&D timelines.
- Integration with Legacy PACS:4K and 3D visualization systems require DICOM conformance upgrades that many European hospitals have deferred due to IT budget constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Minimally Invasive Surgery Devices Market |
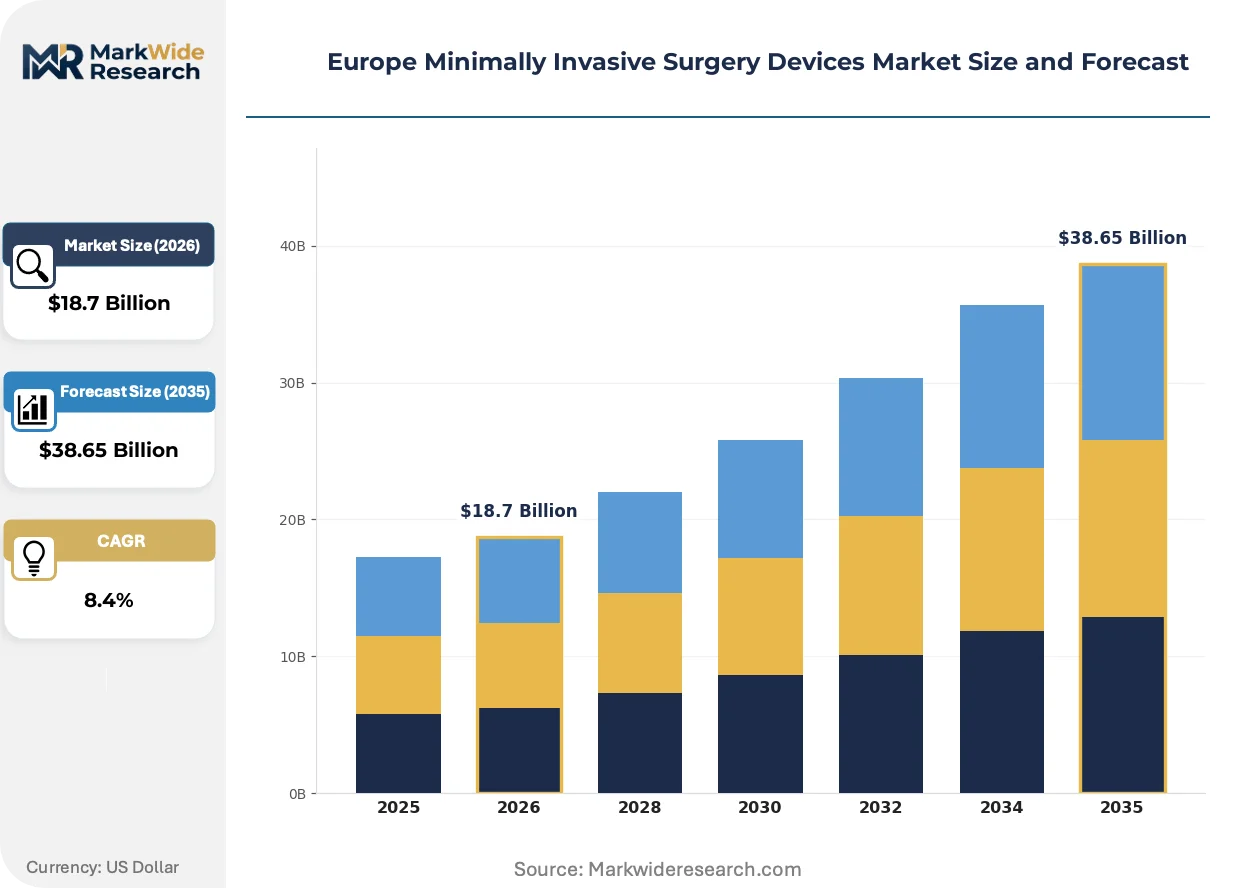
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Laparoscopic Instruments, Robotic Surgical Systems, Endoscopes, Energy Devices Application: Cardiac Surgery, Orthopedic Surgery, Gastrointestinal Surgery, Urological Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Digital Imaging, Navigation Systems, Telemedicine, Wearable Technology |
| Companies Covered | Koninklijke Philips NV, Stryker Corporation, Medtronic PLC, Johnson & Johnson Services, Inc., Intuitive Surgical Inc., Olympus Corporation, GE Healthcare, B. Braun SE, Siemens Healthineers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Minimally Invasive Surgery Devices Market Shifts & Advancements
Digital imaging resolution standards and disposable instrument economics are actively restructuring procurement criteria across European hospital networks, with optical technology refresh cycles now overlapping with regulatory recertification windows.
Single-use laparoscopic instruments are fragmenting the reusable device installed base as German and French hospitals prioritize infection control liability reduction over per-procedure cost optimization. Academic medical centers in the Benelux region are piloting fully disposable trocar and grasper sets for routine cholecystectomy workflows. This shift is compressing aftermarket service revenue pools while expanding recurring consumable attach rates for manufacturers with sterile packaging capabilities.
EMA coordination with notified bodies under MDR Article 120 transition provisions is tightening post-market clinical follow-up obligations for reusable energy devices. Manufacturers must now submit annual safety update reports with real-world performance data from European registries. Class III electrosurgical instruments with reusable handpieces face the steepest compliance burden, driving design pivots toward modular disposable tip architectures.
Hospital procurement consortia in France and Italy are consolidating vendor panels through framework agreements that bundle capital equipment, disposables, and training services into multi-year commitments. Independent surgical centers and smaller regional hospitals are losing direct purchasing autonomy as purchasing power concentrates within regional health authorities. This concentration is most visible in Spain's autonomous community procurement structures, where Andalusia and Catalonia negotiate system-wide robotic surgery contracts.
Europe Minimally Invasive Surgery Devices Market Segmentation
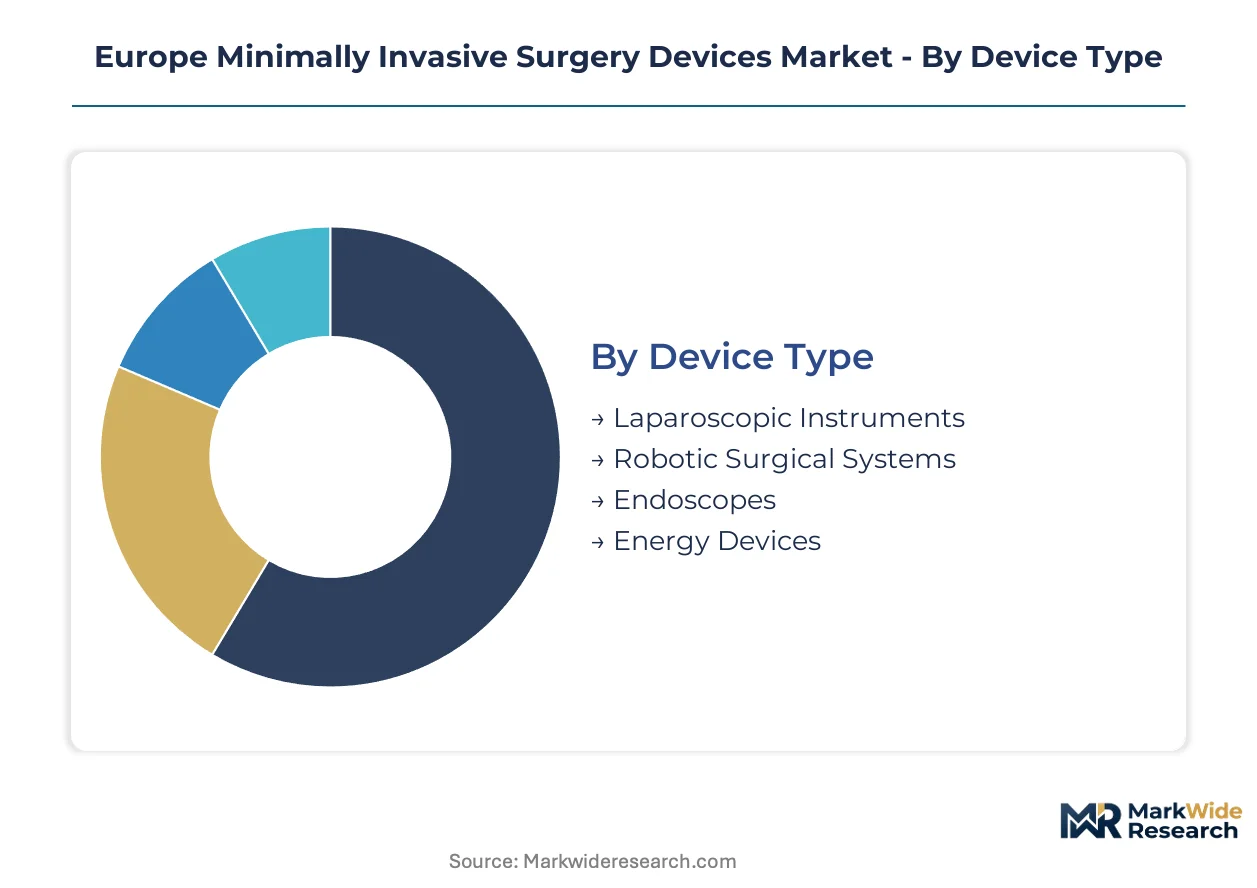
Segmentation in the Europe minimally invasive surgery devices market reveals how regulatory tiers, capital intensity, and reimbursement frameworks reshape procurement patterns across German university hospitals, French cardiac centers, and Benelux ambulatory networks.
Device Type:
CE marking classifications under EU MDR create divergent compliance burdens that stratify competitive positioning across reusable and disposable instrument architectures.
- Laparoscopic Instruments:Graspers, scissors, and trocars with 5-12 mm port diameters form the procedural backbone for cholecystectomy and hernia repair workflows. German hospital networks are consolidating procurement of single-use instrument sets to eliminate reprocessing validation liability under BfArM vigilance standards.
- Robotic Surgical Systems:Capital-intensive platforms with articulated instrument arms and 3D visualization consoles command placement decisions at tier-one academic centers. French cardiac surgery departments are prioritizing da Vinci system acquisitions for mitral valve repair procedures, though ANSM post-market surveillance requirements extend commissioning timelines.
- Endoscopes:Flexible and rigid optical systems with 4K resolution capabilities serve diagnostic and interventional workflows across gastrointestinal and urological applications.
- Energy Devices:Electrosurgical generators and ultrasonic scalpels with disposable blade economics capture recurring revenue pools through generator cartridge replacement cycles.
Established volume favors laparoscopic instruments; emerging adoption favors robotic surgical systems.
Application:
Procedure reimbursement parity and clinical evidence requirements determine capital allocation across surgical service lines in European health systems.
- Cardiac Surgery:Robotic-assisted mitral valve repair and coronary artery bypass grafting demand specialized instrument sets with microsurgical precision capabilities. United Kingdom cardiac centers are expanding minimally invasive valve programs, though NICE technology appraisal timelines delay diffusion beyond London and Manchester academic networks.
- Orthopedic Surgery:Arthroscopic platforms for joint reconstruction and sports medicine procedures concentrate in German ambulatory surgical centers scaling same-day discharge protocols.
- Gastrointestinal Surgery:Laparoscopic colectomy and bariatric procedures drive high-volume instrument utilization across French regional hospital consortia.
- Urological Surgery:Prostatectomy and nephrectomy workflows utilize advanced energy platforms for vessel sealing in confined anatomical spaces.
Orthopedic surgery is climbing the fastest as German ambulatory expansion accelerates; cardiac surgery maintains premium positioning through robotic capital intensity.
End User:
Purchasing autonomy concentration and framework agreement structures reshape vendor access across European care delivery settings.
- Hospitals:Tertiary academic centers and regional general hospitals with centralized sterilization departments manage reusable instrument lifecycle economics under MDR reprocessing mandates.
- Ambulatory Surgical Centers:Same-day procedure facilities in Germany and the Netherlands are adopting fully disposable trocar and grasper sets to streamline workflow efficiency and infection control protocols.
- Specialty Clinics:Focused orthopedic and ophthalmology practices in Spain's autonomous communities participate in regional procurement consortia with limited direct vendor negotiation leverage.
- Research Institutions:Preclinical and clinical trial centers support device development pipelines with specialized imaging and navigation platform requirements.
Hospital procurement concentration favors framework agreements; ambulatory surgical center expansion favors disposable instrument attach rates.
Technology:
Software-as-medical-device classifications and DICOM conformance standards create integration barriers that segment vendor competitiveness.
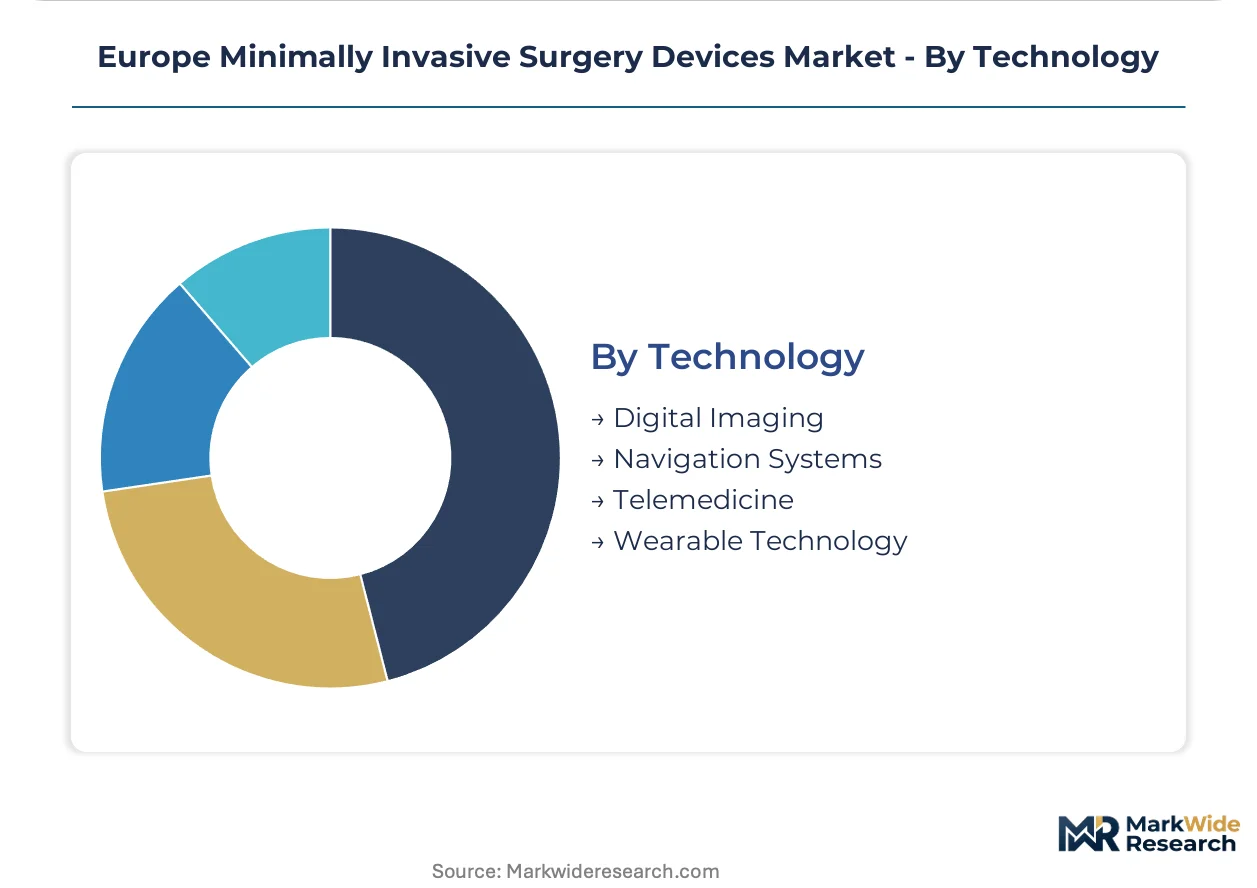
- Digital Imaging:4K and 3D visualization systems with enhanced depth perception capabilities require PACS infrastructure upgrades that many Italian and Spanish hospitals have deferred due to IT budget constraints.
- Navigation Systems:Image-guided surgical planning tools with preoperative CT/MRI registration are gaining adoption in complex hepatobiliary procedures at Benelux academic centers.
- Telemedicine:Remote proctoring and surgical observation platforms support training and quality assurance across distributed hospital networks.
- Wearable Technology:Intraoperative monitoring and surgeon ergonomics devices represent nascent categories with undefined regulatory pathways under MDR software classifications.
Digital imaging holds established installed base; navigation systems are gaining share fastest through AI-enabled surgical planning differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export minimally invasive surgery devices to French and Benelux hospital networks, establishing a north-south trade corridor that channels capital equipment and disposable instrument flows across core EU markets.
Germany
BfArM vigilance standards and MDR reprocessing mandates drive hospital procurement toward single-use instrument sets. The country's national medical device regulator enforces sterilization validation protocols that extend conformity assessment timelines. Bavarian university hospitals in Munich and Erlangen anchor robotic surgical system placements for cardiac and orthopedic workflows.
France
ANSM post-market surveillance requirements and cardiac center expansion fuel demand for da Vinci system acquisitions. The national health safety agency coordinates with EMA on Class III device clinical follow-up obligations. Paris and Lyon academic medical clusters concentrate mitral valve repair procedures and drive capital equipment refresh cycles.
United Kingdom
NICE technology appraisal timelines and NHS procurement frameworks shape adoption of laparoscopic platforms for gastrointestinal surgery. The national health technology assessment body evaluates robotic-assisted procedure reimbursement parity. London and Manchester cardiac networks lead minimally invasive valve program expansion.
Italy
Regional health authority procurement concentration and DRG code gaps for robotic procedures influence capital allocation decisions. The country's national medical device regulator aligns vigilance reporting with EMA MDR transition provisions. Lombardy and Emilia-Romagna hospital consortia negotiate framework agreements bundling equipment and disposables.
Netherlands
Ambulatory surgical center expansion and same-day discharge protocols accelerate disposable trocar and grasper set adoption. The country's national health institute evaluates infection control protocols for reusable instrument reprocessing. Randstad medical centers in Amsterdam and Rotterdam pilot fully disposable workflows for routine cholecystectomy.
Europe Minimally Invasive Surgery Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded multinationals commanding robotic system placements while family-owned instrument fabricators capture disposable volume. The market structures around three concentration nodes: premium robotic platforms, mid-tier laparoscopic devices, and commoditized single-use accessories. Strategic archetypes include integrated imaging-to-instrument conglomerates, pure-play energy device specialists, and regional sterile packaging suppliers. Dominant competitive moves encompass M&A for optical technology capabilities and backward integration into generator cartridge manufacturing.
Among diversified health technology conglomerates, Koninklijke Philips NV and Siemens Healthineers exemplify the imaging-to-navigation integrated archetype, while Stryker Corporation and Medtronic PLC occupy positions spanning capital equipment through disposable attach rate economics. Johnson & Johnson Services, Inc. and B. Braun SE represent the sterile packaging and wound closure integration model. Intuitive Surgical Inc. and Olympus Corporation anchor the premium platform tier through software-dependent recurring revenue structures. GE Healthcare sits within the diagnostic imaging extension archetype, leveraging PACS infrastructure relationships for surgical visualization placement.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Stryker Corporation |
| Medtronic PLC |
| Johnson & Johnson Services, Inc. |
| Intuitive Surgical Inc. |
| Olympus Corporation |
| GE Healthcare |
| B. Braun SE |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
CE marking tiers under EU MDR gate both supplier qualification and price differentiation simultaneously, compressing procurement windows for reusable instrument manufacturers while elevating premium positioning for single-use architectures that eliminate reprocessing liability.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers based on CE-MDR certification grade and sterilization validation burden. German university hospitals absorb premium positioning for robotic surgical systems with embedded service contracts, while Polish regional hospitals exhibit acute price sensitivity toward laparoscopic instrument sets. Pricing pressure stems from framework agreement consolidation in France and Italy, where multi-year bundled contracts compress per-unit margins for standalone device vendors.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for optical sensor components and precision-machined instrument housings. Manufacturing concentration in Germany, Switzerland, and the United States feeds European distribution networks with electrosurgical generators and robotic system consoles. Single-source dependency on Japanese CMOS image sensors for 4K endoscopes creates vulnerability to semiconductor allocation volatility. Distribution runs through GPO-affiliated medical device distributors and direct hospital contracts managed by regional procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach economics now outpace hardware revenue growth across European minimally invasive surgery markets, with disposable blade replacement cycles and annual software maintenance contracts expanding faster than capital equipment placements.
For Market Incumbents: Consolidate channel control through backward integration into sterile packaging capabilities and exclusive framework agreements with German hospital networks. CE-MDR recertification timelines threaten smaller reusable instrument competitors lacking validation infrastructure. Capacity expansion in Poland and Czech Republic addresses Central European demand gaps while defending margin pools against emerging energy device specialists. For New Entrants and Emerging Players: Differentiate on AI-enabled surgical planning tools qualifying under CE-MDR software-as-medical-device pathways. Poland and Czech Republic surgical centers remain under-equipped with advanced vessel sealing platforms, presenting first-mover positioning absent entrenched vendor relationships. Direct contracting with ambulatory surgical centers bypasses GPO concentration in France and Italy. For Investors and Strategic Acquirers: EU MDR Article 120 transition completion reshapes the acquisition landscape by eliminating marginal reusable instrument manufacturers unable to sustain clinical evidence portfolios. Five-to-ten year viability favors modular disposable tip architectures over legacy handpiece designs. Target acquisition archetype: sterile packaging specialists with CE-MDR quality management systems already validated. The signal to watch is ANSM and BfArM vigilance enforcement intensity against reprocessing protocol deviations.| Strategic Initiative | Industry Significance |
|---|---|
| CE-MDR Recertification Investment | Extended notified body engagement secures market access for Class III reusable instruments under BfArM scrutiny. |
| Disposable Instrument Portfolio Expansion | Single-use trocar and grasper sets capture recurring revenue from German ambulatory surgical center expansion. |
| Hospital System Partnership | Multi-year framework agreements with French regional health authorities lock out competing vendors. |
| Software Companion Development | AI-enabled surgical planning tools attract premium pricing under CE-MDR software-as-medical-device classifications. |
| Reimbursement Strategy | Health technology assessment engagement in Italy and Spain establishes DRG parity for robotic-assisted procedures. |
Research Methodology
A spread of perspectives from hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs directors at notified bodies converged on the working assumptions. Primary interview intelligence combined with EMA MDR guidance documents, BfArM vigilance reports, hospital procurement databases, and GPO contract disclosures. Bottom-up procedure volume modeling triangulated against top-down capital equipment shipment tracking.
Segmentation dimensions modeled encompass device type, application specialty, end-user setting, and technology platform across the analysis window. CAGRs derive from procedure volume elasticity to ambulatory surgical center expansion, robotic system placement cycles, and disposable instrument attach rate trajectories. Forecast inputs incorporate EU MDR transition timeline adherence and health technology assessment reimbursement parity developments.
Forecasts assume regulatory continuity in EU MDR enforcement and EMA-notified body coordination; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anti-Fatigue Lenses Market
Medical Devices
Global Uterine Manipulation Devices Market
Medical Devices
Netherlands Aesthetic Devices Market
Medical Devices
Orthokeratology Lens Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Microneedle Flu Vaccine Market
Medical Devices
Asia-Pacific Arthroscopy Devices Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Intrauterine Devices (IUD) Market
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
North America Neurostimulation Devices Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
High Pressure Contrast Media Injectors Market