
 Chewing Gum Market | 2026-2036
Chewing Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Chewing Gum Market Analysis
Indonesian gum base suppliers is rebalancing output toward synthetic elastomers after natural chicle harvests contracted. Mars Wrigley leverages its North American retail footprint to sustain impulse-buy placement at checkout counters. Mondelez International anchors its European position through sugar-free Trident variants positioned for dental health claims. Perfetti Van Melle competes in emerging markets with localized fruit flavors and aggressive price points.
Chewing gum comprises a water-insoluble gum base—typically polyisobutylene, polyvinyl acetate, or natural latex—combined with sweeteners, softeners, and flavoring agents, designed for mastication without swallowing to deliver oral refreshment, breath masking, or active ingredient release. Sugar-free gum, powered by xylitol and sorbitol formulations, captures the fastest expansion as dental associations endorse its caries-prevention properties; bubble gum retains volume leadership in children's channels but faces margin compression from parental sugar scrutiny. Functional gum incorporating caffeine, vitamins, or CBD extracts commands premium positioning, while stick packs dominate convenience distribution though pouches gain traction in travel and on-the-go segments.
The U.S. FDA governs food additive approvals for gum bases and sweeteners, while the EU's EFSA evaluates health claim substantiation for sugar-free and functional positioning; Japan's Ministry of Health, Labour and Welfare enforces strict labeling for quasi-drug gum products containing active ingredients. These frameworks elevate R&D costs for novel formulations but simultaneously create defensible market positions for compliant manufacturers. Stakeholders must monitor evolving sweetener safety assessments and regional claim restrictions to prioritize formulation pipelines and geographic launch sequencing.
Market Dynamics
The chewing gum market restructures around sugar-tax pressure and sweetener substitution, with the EU's front-of-pack labeling rules and national levies forcing rapid reformulation toward polyol-based alternatives that dental associations now endorse.
Growth Catalysts
- Xylitol Formulations:Dental health claims approved by EFSA are accelerating sugar-free adoption across European pharmacy channels. Manufacturers reformulate around this polyol to access premium positioning.
- Functional Positioning:Caffeine, vitamin, and CBD-infused variants command higher margins as consumers seek on-the-go delivery formats beyond traditional confectionery.
- Convenience Expansion:Checkout-counter shelf space allocation favors impulse categories, with synthetic elastomer supply stabilizing after Indonesian chicle harvest volatility.
Market Restraints
- Natural Latex Supply Concentration:Indonesian chicle harvest contraction creates raw material volatility, pushing suppliers toward petroleum-derived polyisobutylene with associated sustainability scrutiny.
- Sweetener Safety Assessments:EFSA and FDA ongoing evaluations of high-intensity sweeteners generate regulatory uncertainty that delays new product launches and claim substantiation.
- Parental Sugar Scrutiny:Bubble gum faces margin compression in children's channels as sugar-content concerns drive purchasing decisions toward sugar-free alternatives.
Strategic Opportunities
- Travel-Format Pouches:Stick-pack alternatives gain traction in airport retail and hospitality channels, addressing on-the-go consumption patterns with portable sizing.
- Quasi-Drug Positioning:Japan's Ministry of Health, Labour and Welfare framework for active-ingredient gum creates a regulatory pathway for nicotine cessation and oral therapeutic products.
- Brazilian Market Expansion:Urban consumer density and established mastication culture support functional gum penetration beyond basic breath-freshening applications.
Industry Challenges
- Claim Substantiation Expertise:Health positioning requires clinical validation capabilities that stretch mid-tier R&D budgets, particularly for caries-prevention and active-release efficacy studies.
- Multi-Jurisdiction Labeling Complexity:Divergent EU, FDA, and Japanese requirements for quasi-drug classification force SKU fragmentation and inventory management strain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chewing Gum Market |
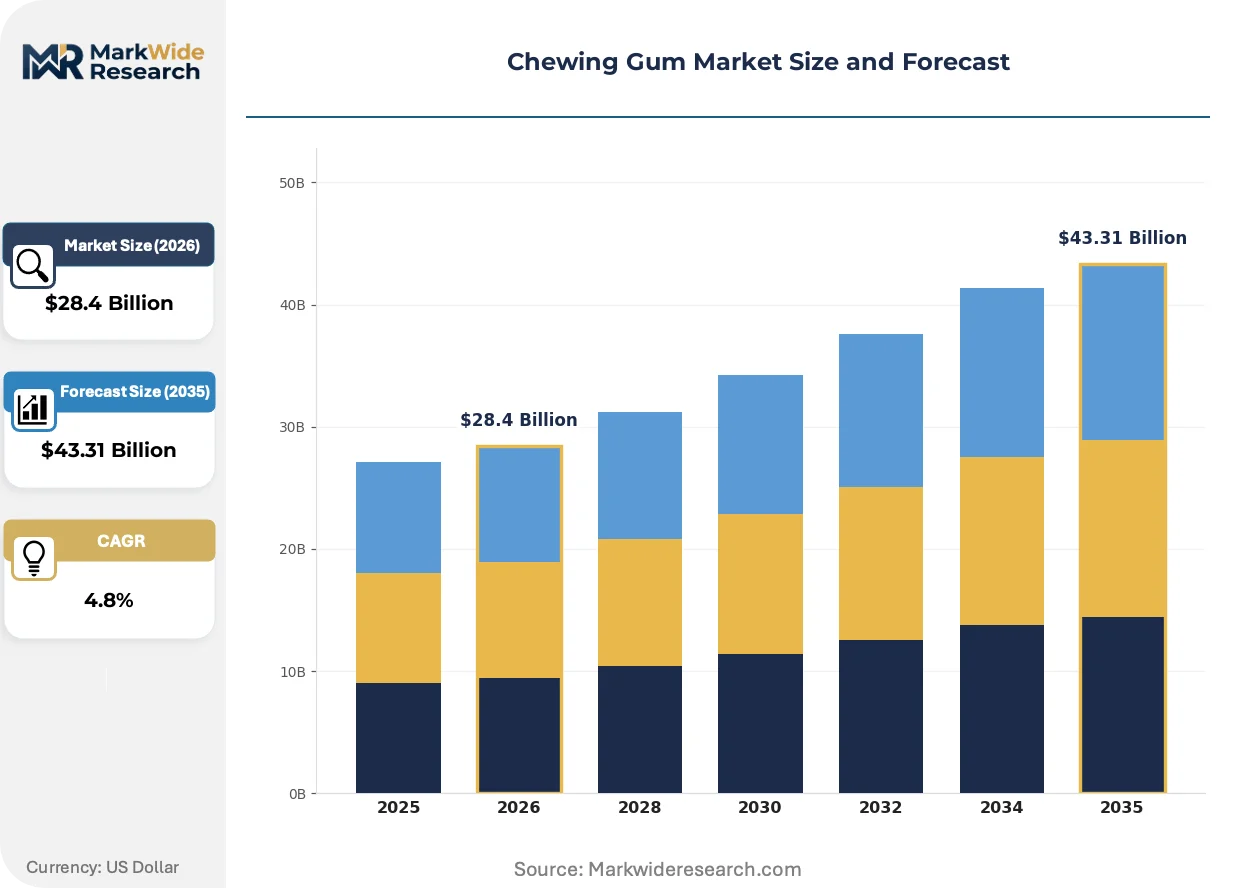
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $43.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Gum, Mints, Sugar-Free Gum, Functional Gum Flavor: Mint, Fruit, Cinnamon, Chocolate Package Type: Stick Packs, Bottles, Pouches, Tins End User: Kids, Teenagers, Adults, Seniors |
| Companies Covered | Lotte Confectionery, Cloetta, Mars Wrigley, Haribo, Ferrero Group, Mondelez International, The Hershey Company, Gumlink Confectionery Company, Perfetti Van Melle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chewing Gum Market Emerging Trajectories
Formulation science and distribution architecture are converging to redefine competitive advantage, with synthetic materials replacing agricultural inputs and channel strategies fragmenting across impulse, health, and travel occasions.
Microencapsulation technology for flavor and active-ingredient release is decentralizing manufacturing flexibility toward regional production hubs. Mid-sized manufacturers adopt these systems to reduce batch minimums and accelerate flavor localization. This capability compresses lead times for market-specific variants and weakens the scale advantages of centralized production networks.
The EU's Sugar Tax and front-of-pack Nutri-Score labeling rules are forcing reformulation timelines that compress product development cycles. Manufacturers must demonstrate nutritional profile improvements to maintain retail access, particularly in French and British markets where levy structures directly affect price positioning. Sugar-free variants now dominate new product pipelines as compliance becomes a baseline market entry requirement.
Urban Chinese consumers are pivoting toward oral-care-positioned gum as dental hygiene awareness spreads through tier-one cities. Pharmacy and professional dental channels are displacing traditional convenience-store dominance for premium functional products. This channel rotation is most pronounced in Shanghai and Beijing, where professional endorsement carries greater purchasing influence than impulse placement.
Chewing Gum Market Segmentation
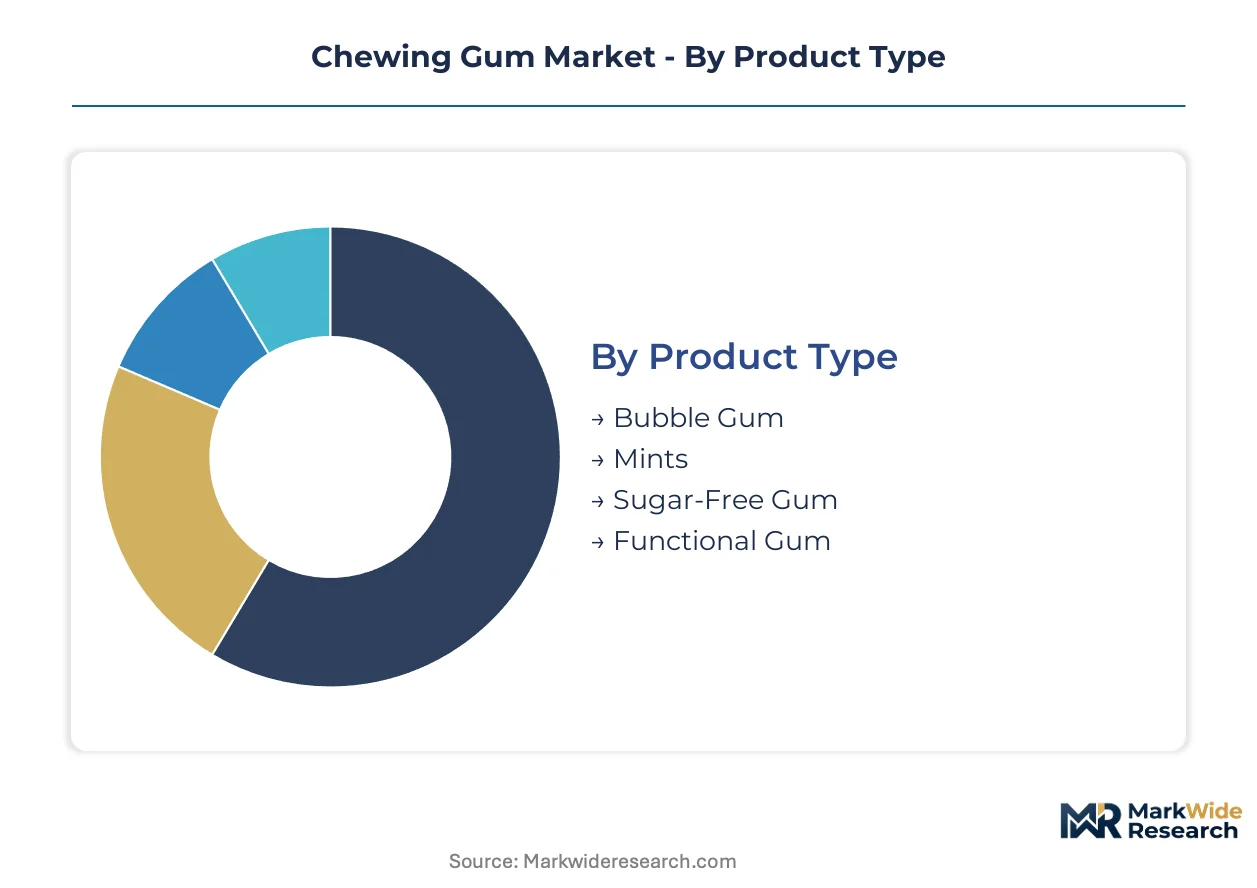
Segmentation in chewing gum reveals how formulation science and occasion-based consumption fragment purchasing decisions across distinct technical and demographic boundaries. Manufacturers align R&D investment and channel strategy to capture value in each slice.
Product Type:
Standalone impulse purchases dominate checkout-counter placement, while embedded functional systems integrate with pharmacy and wellness retail formats.
- Sugar-Free Gum:Xylitol and sorbitol formulations replace sucrose to deliver dental health claims endorsed by EFSA and national dental associations. Pharmacy channels in Germany and France now allocate premium shelf space to these variants as sugar-tax compliance becomes a baseline requirement.
- Functional Gum:Caffeine, vitamin, and CBD-infused variants embed active ingredients into mastication routines for on-the-go delivery. Urban professionals in São Paulo and Shanghai drive demand for energy and wellness positioning beyond basic breath freshening.
- Bubble Gum:Traditional sucrose-based formulations retain volume in children's channels but face margin pressure from parental sugar scrutiny and school vending restrictions.
- Mints:Compressed tablet alternatives compete for breath-freshening occasions with faster dissolution and lower per-unit pricing.
Volume placements concentrate in sugar-free formulations; the faster expansion belongs to functional gum.
Flavor:
Cost-tier differentiation separates commodity mint from premium positioned variants, with fruit and spice extracts commanding formulation premiums.
- Mint:Peppermint and spearmint oils deliver the standard refreshment profile across all demographic segments. North American and European consumers treat mint as the default functional choice for oral hygiene occasions.
- Fruit:Citrus and berry formulations localize for emerging market preferences in Brazil and Southeast Asia. Perfetti Van Melle deploys regional fruit variants to capture price-sensitive volume outside traditional mint strongholds.
- Cinnamon:Spiced positioning targets seasonal and nostalgic purchasing patterns with limited year-round distribution.
- Chocolate:Confectionery crossover appeals to dessert-substitute occasions with higher calorie density and shorter chew duration.
Standard mint captures the largest volume base; fruit variants are climbing the fastest in emerging market expansion.
Package Type:
Application context dictates format selection, with portability requirements driving innovation beyond traditional stick configurations.
- Stick Packs:Individual wrapped sticks dominate convenience store and checkout-counter distribution. Mars Wrigley maintains impulse-placement dominance through retail footprint control in the United States.
- Pouches:Resealable flexible packaging addresses travel and on-the-go consumption with reduced bulk. Airport retail and hospitality channels in Japan and the United Kingdom accelerate adoption.
- Bottles:Multi-piece containers serve desk and automotive storage occasions with cost-per-piece efficiency.
- Tins:Metal packaging supports premium gifting and collectible positioning in Asian duty-free channels.
Stick packs retain the volume concentration; pouches are gaining share fastest in travel-format disruption.
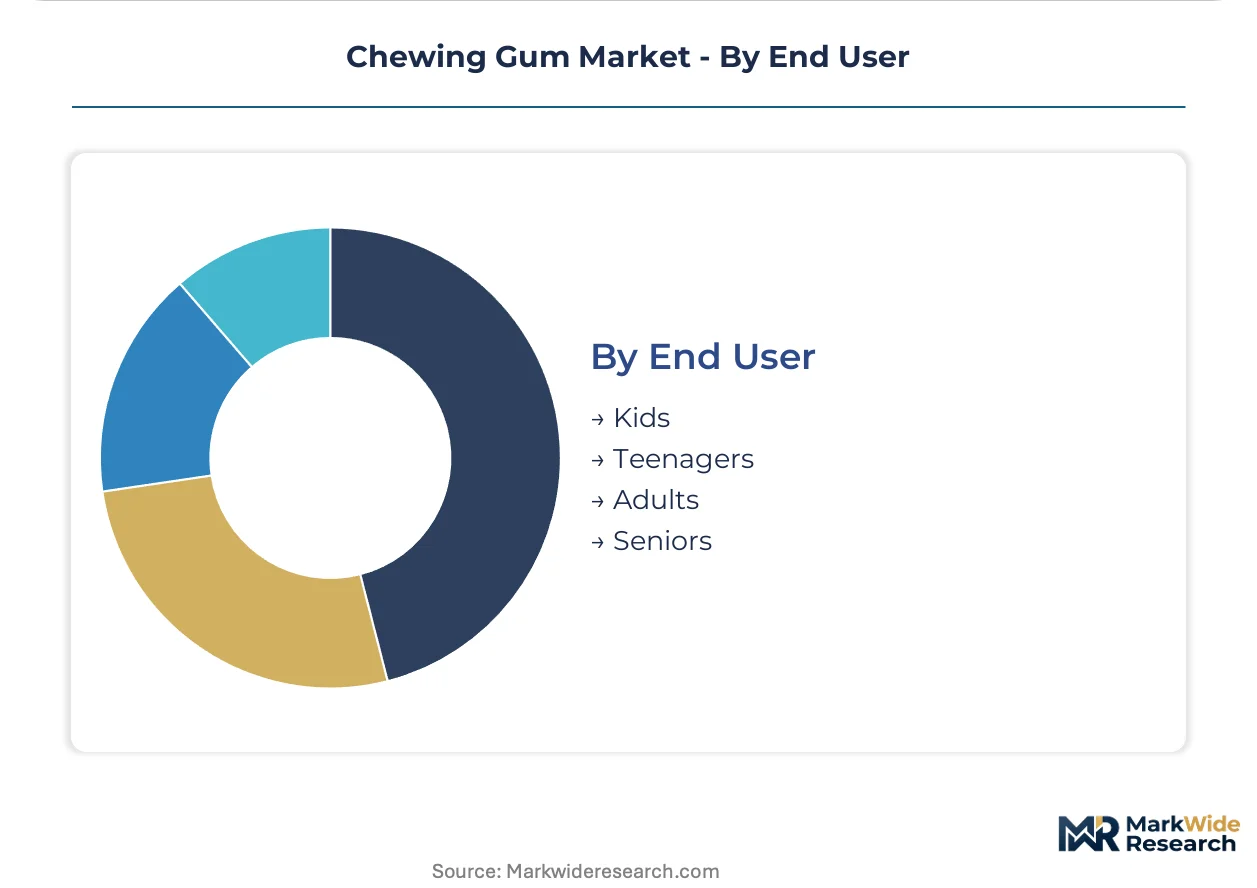
End User:
Customer life-stage determines functional claim relevance and price elasticity, with adult segments driving premiumization.
- Adults:Working-age consumers purchase sugar-free and functional variants for professional and wellness occasions. Dental health claims and active-ingredient positioning resonate with health-conscious urban demographics.
- Teenagers:Social and impulse consumption drives bubble gum and flavor novelty purchases with higher frequency and lower per-transaction value.
- Kids:Parental gatekeeping limits sugar exposure and channels spending toward sugar-free alternatives or non-gum confectionery.
- Seniors:Dry-mouth formulations and therapeutic positioning address age-specific oral health needs through pharmacy and professional dental channels.
Adult segments command the volume concentration; senior-targeted therapeutic positioning shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian chicle harvests anchor raw material flows for natural gum base, while synthetic elastomer production clusters in petroleum-processing zones across multiple continents.
United States
Checkout-counter impulse placement drives volume concentration in convenience retail chains. The FDA governs food additive approvals for polyisobutylene and polyvinyl acetate gum bases. Mars Wrigley maintains dominant shelf-space allocation through retail footprint control in metropolitan Chicago and the Northeast corridor.
Germany
Pharmacy channel expansion accelerates sugar-free adoption among health-conscious consumers. EFSA health claim substantiation rules elevate R&D costs for xylitol formulations. Industrial clusters around Cologne and Hamburg concentrate flavor compounding and flexible packaging production for European distribution.
China
Tier-one urban consumers pivot toward oral-care-positioned gum as dental hygiene awareness spreads. SAMR enforces labeling standards for functional products containing active ingredients. Shanghai and Beijing host the strongest pharmacy channel penetration for premium functional variants with professional endorsement.
Brazil
Urban consumer density and established mastication culture support functional gum penetration beyond breath-freshening. ANVISA regulates food additive safety assessments for imported sweetener formulations. São Paulo anchors demand concentration for energy and wellness-positioned variants among working professionals.
Japan
Quasi-drug classification creates regulatory pathways for nicotine cessation and therapeutic gum products. METI and the Ministry of Health, Labour and Welfare enforce strict labeling for active-ingredient formulations. The Kanto region around Tokyo concentrates specialized manufacturing for pharmaceutical-grade gum production.
Chewing Gum Market Vendor Landscape
Global majors compete with regional champions across formulation technology and distribution reach. The market structure consolidates around multinational confectionery conglomerates with integrated supply chains, while mid-tier specialists occupy niche positioning in functional and premium segments. Three archetypes dominate: scale-driven checkout-counter operators, pharmacy-channel health-positioned players, and emerging-market price-competitive manufacturers. Capacity expansion in synthetic elastomer production and strategic partnerships for microencapsulation technology represent the dominant competitive moves.
Within the scale-driven tier, Mars Wrigley and Mondelez International exemplify global operators with established retail footprint dominance. Perfetti Van Melle occupies a position among emerging-market-focused specialists leveraging localized flavor portfolios. Lotte Confectionery represents the Asia-Pacific anchored conglomerate with integrated confectionery operations. These three entities collectively illustrate the competitive spectrum from impulse-placement scale to regional adaptation capability.
| Leading Market Players |
|---|
| Lotte Confectionery |
| Cloetta |
| Mars Wrigley |
| Haribo |
| Ferrero Group |
| Mondelez International |
| The Hershey Company |
| Gumlink Confectionery Company |
| Perfetti Van Melle |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between EFSA-validated xylitol formulations and commodity sucrose-based alternatives manifests in divergent margin structures and procurement patterns. Premium dental-health-positioned variants command ingredient traceability from Indonesian chicle or synthetic elastomer suppliers, while economy bubble gum draws from spot-market petroleum derivatives with minimal compliance documentation.
Pricing Analysis
Service-bundling separates clinical-validation-included pricing from bare-product transactional models. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA claim substantiation costs, with pharmacy-channel dental variants capturing the highest per-unit realization. Price differentiation hinges on xylitol purity grades and professional endorsement packaging. Cost compression in children's bubble gum intensifies because parental sugar scrutiny forces reformulation investment without commensurate price recovery. Mass-market convenience buyers exhibit highest price sensitivity; pharmacy-channel wellness purchasers show lowest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian natural chicle harvests, which contracted sharply and forced reformulation toward petroleum-derived alternatives. Raw material flows draw from Indonesia, Thailand, and synthetic elastomer production clusters in the United States and Germany. Polyisobutylene, polyvinyl acetate, and natural latex constitute the core input dependencies. Tariff exposure on Southeast Asian agricultural imports creates margin volatility for natural-base formulations. Distribution runs through convenience store chains, pharmacy networks, and duty-free travel retail channels with divergent service-level requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the EU's front-of-pack Nutri-Score labeling rules erect regulatory moats favoring incumbents with validated EFSA health claims and established reformulation pipelines.
For Market Incumbents: Anticipate margin compression in children's bubble gum segments as school vending restrictions and parental sugar scrutiny accelerate category decline. Defensive consolidation moves should prioritize backward integration into synthetic elastomer production to neutralize Indonesian chicle volatility, while channel control investments in pharmacy networks capture wellness-premiumization tailwinds. Certification maintenance in EFSA-validated xylitol formulations preserves pricing power against commodity competitors lacking clinical substantiation budgets. For New Entrants and Emerging Players: Microencapsulation technology for active-ingredient release offers a technology-first wedge into functional gum segments where incumbent R&D cycles lag consumer demand for caffeine and vitamin delivery formats. White-space targets concentrate on travel-format pouches for airport hospitality channels and CBD-infused variants in regulatory-permissive jurisdictions. Brazil's urban professional demographic presents the most penetrable geography given established mastication culture and ANVISA's evolving framework for active-ingredient classification. Go-to-market execution should anchor in direct-to-pharmacy distribution bypassing incumbent checkout-counter gatekeepers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier manufacturers possessing EFSA-validated formulation libraries and underutilized microencapsulation capacity, given accelerated sugar-tax adoption across European member states. Long-term viability over the coming decade favors entities with diversified input sourcing across natural and synthetic elastomer bases. Acquisition screening should prioritize targets with clinical validation capabilities and established pharmacy-channel relationships. The signal to watch is regulatory harmonization between EU Nutri-Score requirements and emerging Asian front-of-pack labeling standards, which would compress geographic launch sequencing advantages.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Validation Investment | Secures premium pharmacy-channel positioning and defensible pricing against commodity competitors lacking clinical substantiation. |
| Synthetic Elastomer Backward Integration | Neutralizes Indonesian chicle harvest volatility and satisfies sustainability scrutiny from European retail buyers. |
| Microencapsulation Technology Licensing | Enables regional flavor localization and active-ingredient release capabilities that compress incumbent scale advantages. |
| Pharmacy Channel Expansion | Captures urban Chinese and Brazilian wellness-positioned demand where professional endorsement outweighs impulse placement. |
| Travel-Format Pouch Development | Addresses on-the-go consumption patterns in Japanese and British airport retail with portable resealable packaging. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with brand managers, category buyers at convenience chains, supply planners, and pharmacy procurement officers combined with secondary validation from EFSA health claim registers, FDA food additive approvals, and Nielsen retail audit data. Bottom-up volume modeling across product types and flavors triangulated against top-down market sizing from trade association aggregates.
Data-stream reconciliation employed cross-validation between manufacturer production disclosures and channel shipment reports. Segmentation dimensions modeled include product type, flavor profile, package format, and end-user demographic across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and sweetener substitution elasticities. Forecast inputs incorporated sugar-tax implementation schedules and dental association endorsement patterns.
Several conditions sit outside the modeled scope, including potential EFSA reclassification of high-intensity sweeteners, Indonesian chicle harvest recovery trajectories, and CBD regulatory harmonization failures. Forecasts reflect documented assumptions about reformulation cost pass-through rates and pharmacy channel expansion velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
North America Pasta Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Freekeh Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
United States Online Grocery Market