
 Indonesia Snack Bar Market | 2026-2036
Indonesia Snack Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Snack Bar Market Foresight
Asset-light contract manufacturing and third-party co-packing arrangements is fragmenting competitive dynamics in Indonesia's snack bar sector. PT Mayora Indah Tbk leverages its sprawling domestic distribution network to maintain shelf presence across tier-two cities. Mondelez International sustains brand recognition through localized flavor development tailored to Indonesian palates. PT Kalbe Farma Tbk anchors its position by cross-selling snack bars through established pharmaceutical and nutrition retail channels.
Indonesia snack bars comprise shelf-stable, individually wrapped baked or extruded food products typically containing cereals, proteins, nuts, or fruit binders, formulated for ambient storage and portable consumption. These products serve as meal replacements or supplementary nutrition for mobile consumers requiring convenient caloric intake. Protein bars capture premium margin pools as fitness culture expands in Jakarta and Bali, while granola bars occupy volume leadership through supermarket and convenience store penetration. Health food stores and online retailers represent the fastest-growing distribution channel as direct-to-consumer brands bypass traditional wholesale markups.
Indonesia's Badan Penyelenggara Jaminan Produk Halal (BPJPH) enforces mandatory halal certification timelines that compress product development cycles for domestic and imported brands alike. The National Agency of Drug and Food Control (BPOM) governs nutritional labeling and health claims, restricting functional positioning unless clinical substantiation meets established thresholds. Stakeholders must monitor evolving halal certification enforcement and local content requirements as these frameworks determine market access eligibility and competitive differentiation.
Market Dynamics
Indonesia's mandatory halal certification regime under BPJPH is compressing product development timelines and forcing simultaneous reformulation of ingredient sourcing, manufacturing protocols, and labeling systems across all market entrants.
Growth Catalysts
- Fitness culture expansion:Protein bar consumption accelerates in Jakarta and Bali gym ecosystems as post-workout nutrition becomes ritualized among urban millennials seeking convenient macronutrient delivery.
- BPJPH halal mandate:The 2024 enforcement timeline creates first-mover advantages for domestic manufacturers already compliant with Indonesia's Badan Penyelenggara Jaminan Produk Halal standards.
- Extrusion technology advancement:Cold-extrusion protein bar manufacturing reduces thermal degradation of functional ingredients, enabling cleaner-label positioning without shelf-stability tradeoffs.
Market Restraints
- Palm oil price volatility:Binding and coating formulations depend on refined palm olein supplies concentrated in Riau and North Sumatra estates, exposing margin structures to commodity swings.
- Import dependency for whey isolates:High-grade dairy protein inputs arrive primarily from New Zealand and Australian processors, creating forex exposure and supply concentration risk.
- BPOM health claim substantiation:Indonesia's National Agency of Drug and Food Control requires clinical validation for functional positioning, blocking rapid innovation in adaptogen and probiotic bar segments.
Strategic Opportunities
- Eastern Indonesia penetration:Makassar, Manado, and Ambon retail corridors remain underserved by premium snack bar distribution, offering volume expansion for halal-certified domestic brands.
- Direct-to-consumer channel development:TikTok Shop and Shopee Live commerce bypass traditional wholesale markups, enabling margin capture and consumer data accumulation for emerging players.
- Local ingredient valorization:Moringa, sago, and red fruit (pandanus) integration satisfies BPJPH traceability requirements while differentiating against imported formulations.
Industry Challenges
- Halal auditor scarcity:BPJPH-certified inspection personnel remain concentrated in Java, extending certification timelines for manufacturers in Sulawesi and Papua production zones.
- Cold chain fragmentation:Ambient-stable bar formulations face quality degradation during last-mile distribution through unrefrigerated inter-island ferry networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Snack Bar Market |
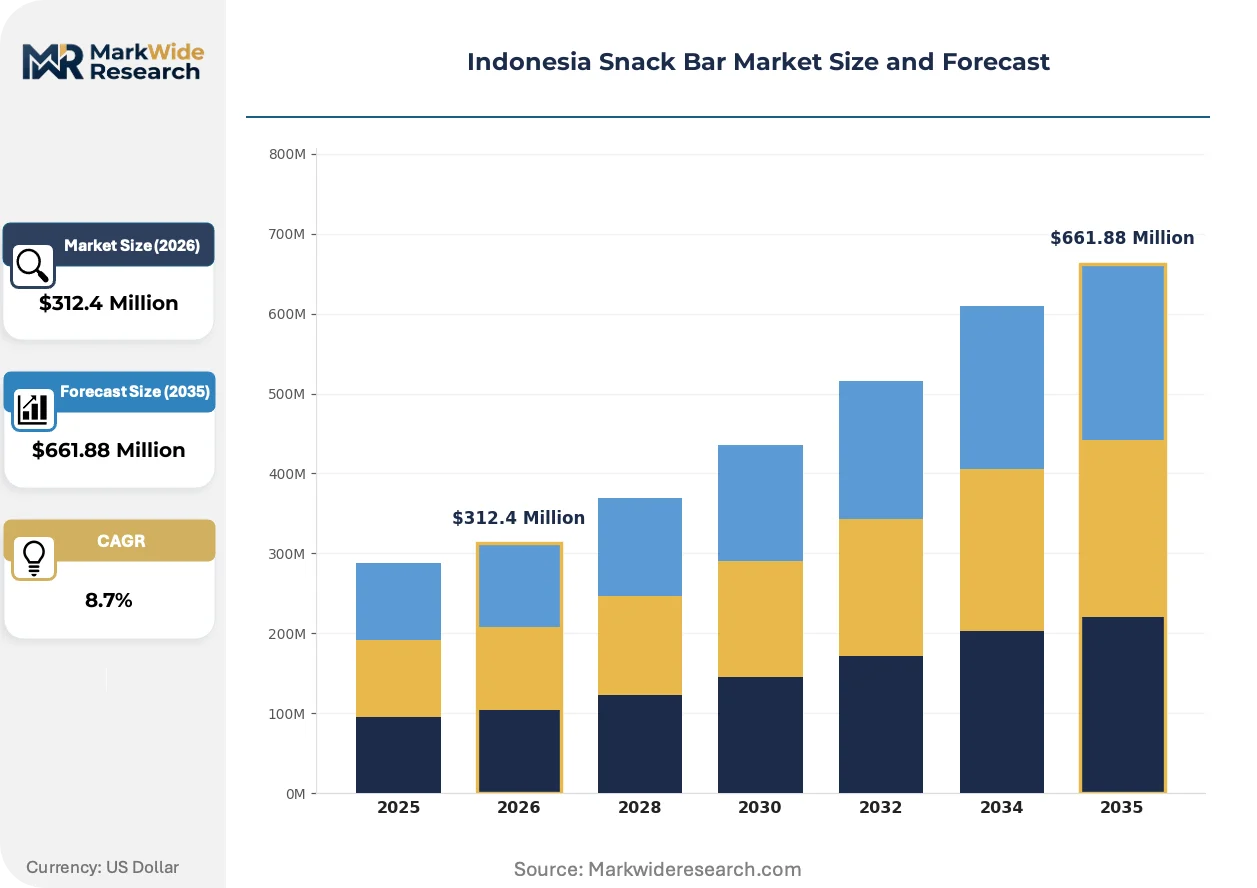
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granola Bars, Protein Bars, Nut Bars, Energy Bars Customer Type: Health-Conscious Consumers, Fitness Enthusiasts, Busy Professionals, Students Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Stores Flavor Profile: Chocolate, Fruit, Nutty, Savory |
| Companies Covered | Mondelez International, PT Tata Nutrisana, PT Kalbe Farma Tbk, Clif Bar & Company, PT Mayora Indah Tbk, Otsuka Pharmaceutical Co., Ltd., General Mills, Inc., Premier Nutrition Corp., Nestlé S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Snack Bar Market Shifts & Advancements
Reformulation priorities are converging around clean-label positioning, localized flavor systems, and packaging sustainability as Indonesian consumers scrutinize ingredient transparency alongside religious compliance.
Blockchain-enabled ingredient traceability is digitizing supply chain verification for halal compliance. Domestic manufacturers in Sidoarjo and Bekasi industrial zones deploy distributed ledger systems to document slaughterhouse certification, transport segregation, and cross-contamination prevention. BPJPH auditors access immutable batch records, compressing inspection timelines from weeks to days and accelerating product launch cycles.
BPJPH's 2024 mandatory halal certification deadline is restructuring competitive access requirements. All domestic and imported snack bar brands must complete facility audit and ingredient verification before October 2024 or face distribution prohibition. Java-based manufacturers with existing compliance infrastructure capture shelf space as smaller importers withdraw pending certification completion.
Subscription-based replenishment models are displacing supermarket impulse purchases among Jakarta and Surabaya fitness enthusiasts. Direct-to-consumer brands offer monthly protein bar curation via WhatsApp commerce integration, bypassing traditional modern trade slotting fees. This channel shift concentrates lifetime value capture with emerging players while eroding incumbent supermarket dominance in premium segments.
Indonesia Snack Bar Market Segmentation
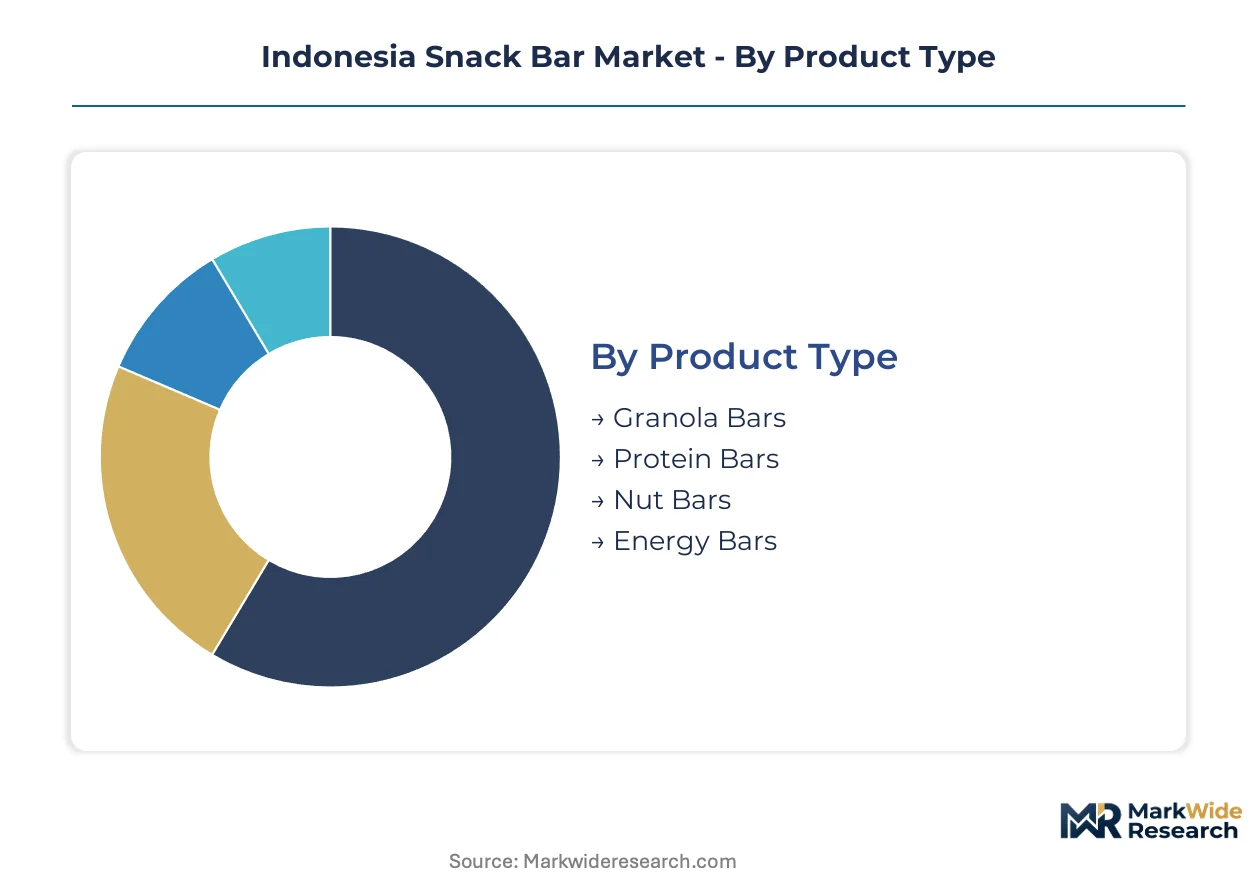
Indonesia's snack bar segmentation reveals distinct consumption rituals across product formats and purchase contexts. Each dimension carries implications for halal certification pathways, distribution infrastructure requirements, and margin capture potential in Java versus Eastern Indonesia corridors.
Product Type:
After-sales service intensity varies sharply across product categories, with protein bars demanding nutritional counseling support while granola bars require minimal post-purchase engagement.
- Protein Bars:Cold-extruded formulations preserve amino acid integrity through reduced thermal processing. Demand concentrates in Jakarta and Bali gym ecosystems where post-workout consumption rituals drive premium positioning and subscription replenishment models.
- Granola Bars:Baked oat-and-honey matrices with ambient stability suit broad retail penetration. Volume leadership in Surabaya and Bandung supermarket channels reflects family-oriented snacking occasions and school lunchbox integration.
- Nut Bars:Almond and cashew-dominant formulations with higher fat content requiring precise moisture control in tropical storage conditions.
- Energy Bars:Caffeine and carbohydrate-dense variants targeting endurance athletes and shift workers in manufacturing zones around Bekasi and Karawang.
By volume, granola bars lead. By growth pace, protein bars are climbing the fastest.
Customer Type:
Cost tier stratification separates premium protein bar purchasers from mass-market granola consumers, with distinct channel preferences and brand loyalty patterns.
- Health-Conscious Consumers:Clean-label scrutiny drives ingredient transparency demands and BPJPH traceability verification. Concentrated in Jakarta's affluent Kemang and Senopati districts where organic certification commands price premiums.
- Fitness Enthusiasts:Macronutrient tracking behaviors favor high-protein formulations with disclosed amino acid profiles. Bali's Canggu and Uluwatu fitness communities sustain direct-to-consumer subscription volumes bypassing traditional retail.
- Busy Professionals:Meal replacement occasions in Jakarta's Sudirman CBD corridor favor portable calorie density and minimal packaging waste.
- Students:Price-sensitive trial behavior in university towns like Depok and Malang drives single-serve convenience store purchases and flavor experimentation.
Health-conscious consumers anchor revenue per transaction. Fitness enthusiasts are gaining share fastest through digital channel migration.
Distribution Channel:
Margin structures diverge dramatically between modern trade slotting fees and direct-to-consumer fulfillment economics.
- Supermarkets:Planogram placement battles in Hero, Ranch Market, and Transmart chains determine visibility for incumbent brands with established halal certification. Volume concentration in Greater Jakarta and Surabaya metropolitan areas.
- Online Retailers:TikTok Shop and Shopee Live commerce enable emerging brands to bypass wholesale markups and accumulate first-party consumer data. Fastest expansion in Jakarta's smartphone-saturated millennial demographic.
- Convenience Stores:Indomaret and Alfamart networks provide impulse purchase access across tier-two and tier-three cities with standardized planogram compliance requirements.
- Health Food Stores:Specialized retail in Jakarta's Kemang and Bali's Ubud clusters serves clean-label seekers with curated premium assortments and staff nutritional guidance.
Supermarkets maintain volume leadership. Online retailers show the steepest expansion trajectory as live commerce penetration deepens.
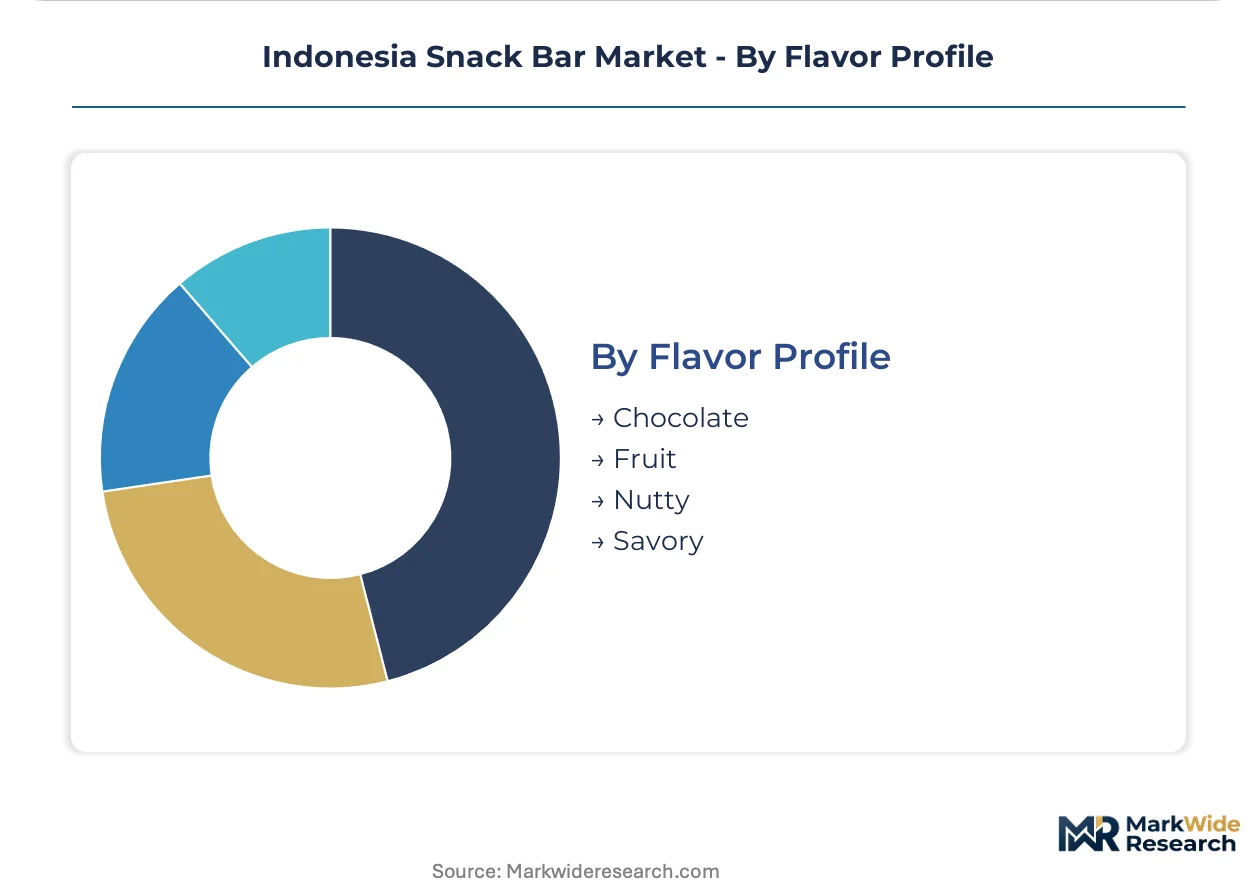
Flavor Profile:
Application context shapes flavor preference intensity, with chocolate dominating indulgence occasions and savory variants capturing meal replacement positioning.
- Chocolate:Cocoa-based coatings and inclusions requiring BPJPH-certified emulsifier sourcing. Dominates children's snacking and gift purchase occasions in Jakarta's modern trade channels.
- Fruit:Local jackfruit, durian, and salak formulations differentiating against imported berry-dominant competitors. Concentrated demand in Yogyakarta and Surabaya where regional palate preferences resist Western flavor hegemony.
- Nutty:Peanut and cashew profiles with established halal slaughterhouse certification documentation for export-adjacent production.
- Savory:Emerging rendang, sambal, and tempeh variants targeting meal replacement positioning and differentiation from sweet-dominant imported alternatives.
Chocolate captures the widest demographic reach. Savory profiles are expanding most quickly as local ingredient valorization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's BPJPH halal certification mandate is redistributing manufacturing capacity across the archipelago as producers seek compliant facilities outside Java. Provincial governments in Sulawesi and Sumatra are accelerating industrial zone development to capture migrating investment.
Java
Jakarta and Surabaya gym cultures sustain premium protein bar demand through subscription replenishment models. BPOM nutritional labeling enforcement concentrates compliance expertise in Bekasi and Sidoarjo manufacturing corridors. Cold-extrusion production clusters in East Java are capturing technology transfer from Australian equipment suppliers.
Sumatra
Medan and Palembang retail networks are expanding convenience store penetration for granola bar volume growth. Provincial industrial authorities are streamlining BPJPH audit access for palm oil-adjacent binding ingredient processors. Riau estate proximity is reducing refined palm olein transport costs for coating formulations.
Sulawesi
Makassar and Manado distribution corridors remain underserved by premium snack bar brands, creating first-mover opportunities for halal-certified domestic entrants. BPJPH auditor scarcity extends certification timelines, delaying facility approvals. Local sago and red fruit ingredient valorization is differentiating regional formulations against Java-imported alternatives.
Bali
Canggu and Uluwatu fitness communities are sustaining direct-to-consumer protein bar volumes through WhatsApp commerce integration. Tourism-dependent retail is exposing brands to seasonal demand volatility. Health food store density in Ubud is supporting clean-label trial behavior among expatriate and affluent Indonesian consumers.
Eastern Indonesia
Ambon and Jayapura retail infrastructure gaps are constraining ambient-stable bar distribution through unrefrigerated inter-island ferry networks. Halal certification penetration lags national averages, limiting product assortment depth. Provincial nutrition programs are creating institutional demand for fortified energy bar procurement.
Indonesia Snack Bar Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: multinational FMCG conglomerates with established halal infrastructure, diversified domestic food and pharmaceutical groups leveraging cross-channel distribution, and emerging direct-to-consumer brands bypassing traditional wholesale. Strategic archetypes include certification-first incumbents capturing shelf space ahead of BPJPH deadlines, ingredient-integrated players controlling palm oil supply chains, and digital-native entrants accumulating consumer data through TikTok Shop commerce. Dominant competitive moves center on M&A absorption of compliant smaller facilities and backward integration into binding ingredient production.
Within the multinational tier, Mondelez International and Nestlé S.A. exemplify halal-certification-ready market presence. Among domestic diversified groups, PT Mayora Indah Tbk and PT Kalbe Farma Tbk occupy positions spanning pharmaceutical retail and mass-market distribution. These named entities represent archetype anchors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Mondelez International |
| PT Tata Nutrisana |
| PT Kalbe Farma Tbk |
| Clif Bar & Company |
| PT Mayora Indah Tbk |
| Otsuka Pharmaceutical Co., Ltd. |
| General Mills, Inc. |
| Premier Nutrition Corp. |
| Nestlé S.A. |
| Others |
Supply & Pricing Matrix
Palm oil price volatility determines both pricing tier spreads and supply chain shape across Indonesia's snack bar sector. Binding and coating formulations draw from refined palm olein supplies concentrated in Riau and North Sumatra estates, exposing margin structures to commodity swings while compressing cost differentiation between premium and mass-market tiers.
Pricing Analysis
Certification level creates the primary spread between premium protein bars and economy granola segments. BPJPH halal compliance and BPOM nutritional labeling substantiation separate certified domestic manufacturers from pending-import alternatives. Cost compression in the standard tier is intensifying because contract manufacturers compete for limited auditor bandwidth. Health-conscious consumers in Jakarta's Kemang district show least price sensitivity; students in Depok and Malang drive single-serve trial behavior with highest elasticity.
Supply Chain Analysis
Extended payment terms from New Zealand and Australian whey isolate suppliers strain working capital for Java-based processors. Raw material dependencies center on imported dairy proteins, domestic palm olein, and regional sago flour. Single-source vulnerability concentrates in high-grade whey isolates arriving through Port of Tanjung Priok. Distribution runs through Indomaret and Alfamart networks for mass-market penetration, with direct-to-consumer fulfillment gaining share via TikTok Shop and Shopee Live commerce.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of BPJPH-certified auditors constrains facility approval velocity, creating competitive moats for manufacturers with existing compliance infrastructure. This capability gap rewards early certification investment while penalizing delayed entrants.
For Market Incumbents: Insulate shelf position by absorbing compliant smaller facilities in Sidoarjo and Bekasi industrial zones before certification deadlines eliminate non-compliant competitors. Anchor backward integration into palm olein refining to capture margin from binding ingredient volatility. Prioritize cold-extrusion capacity expansion to preserve amino acid integrity claims against emerging clean-label entrants. For New Entrants and Emerging Players: Eastern Indonesia corridors in Makassar, Manado, and Ambon represent the most penetrable entry point given incumbent underdistribution and halal certification lags. Subscription-based WhatsApp commerce integration bypasses modern trade slotting fees while accumulating first-party consumer data. Local ingredient valorization through moringa and red fruit differentiation satisfies BPJPH traceability requirements against imported formulations. For Investors and Strategic Acquirers: The market sits at a certification-transition phase that favors compliant domestic manufacturers with established auditor relationships and cross-channel distribution infrastructure. Acquisition targets should demonstrate facility-level BPJPH approval and pharmaceutical retail channel access. Watch halal auditor training pipeline expansion as the signal indicating certification timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Acceleration | BPJPH facility approval before enforcement deadlines secures modern trade shelf access against import withdrawals. |
| Local Ingredient Integration | Moringa and sago valorization satisfies traceability requirements while differentiating against Australian whey-dependent competitors. |
| Direct-to-Consumer Channel Launch | TikTok Shop and Shopee Live commerce bypass Indomaret slotting fees and accumulate consumer data for emerging brands. |
| Cold-Extrusion Technology Adoption | Reduced thermal processing preserves functional ingredient integrity and enables premium clean-label positioning. |
| Eastern Indonesia Distribution Expansion | Makassar and Ambon retail corridors offer volume growth with limited incumbent premium brand presence. |
Research Methodology
A spread of perspectives from brand managers at domestic manufacturers, category buyers at Hero and Ranch Market chains, supply planners at palm olein processors, and regulatory affairs leads navigating BPJPH certification converged on the working assumptions. Secondary validation drew from BPOM nutritional labeling guidelines, BPJPH halal certification databases, Nielsen retail audit data, and Indonesian customs import records. Bottom-up channel volume estimates and top-down macroeconomic scaling were triangulated against facility-level production capacity assessments.
Demand-supply balance modeling across the analysis window incorporated protein bar, granola bar, nut bar, and energy bar segmentation with flavor profile and distribution channel dimensions. CAGRs were derived from cohort-based adoption curves and per-capita consumption intensity trends. Forecast inputs included BPJPH auditor capacity expansion timelines, palm olein price volatility bands, and TikTok Shop penetration rates in Jakarta and Surabaya millennial demographics.
Practitioners should monitor BPJPH enforcement consistency, auditor training pipeline expansion, and inter-island ferry network reliability for early signals of supply chain constraint or demand acceleration. Macroeconomic rupiah depreciation, regulatory deadline extensions, or cold-extrusion technology cost breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
No Fat Snacks Market
Snacks
UK Snack Market
Snacks
Organic Snacks Market
Snacks
Roasted Corn Market
Snacks
Low Calorie Crackers Market
Snacks
Fat Free Meals and Snacks Market
Snacks
Middle East and Africa Frozen Snacks Market
Snacks
North America Potato Chips Market
Snacks
Dried Fruit Snacks Market
Snacks
Energy Bar Market
Snacks
North America Pretzel Market
Snacks
Tortilla Mix Market
Snacks
Allergy-Free Snacks Market
Snacks
Fried Potato Chips Market
Snacks
Nachos Market
Snacks
Saudi Arabia Snacks Industry Market