
 Instant Beverage Premix Market | 2026-2036
Instant Beverage Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Instant Beverage Premix Market Analysis
ISO 22000 food safety management certification is rotating as the primary gating standard for supplier qualification across major retail and foodservice procurement programs. Nestlé S.A. leverages its in-house dairy and coffee sourcing infrastructure to control input costs across multiple continents. Tata Consumer Products Limited anchors its competitive position through deep distribution networks in South Asian traditional trade channels. Unilever PLC differentiates via formulation expertise spanning both hot and cold instant beverage platforms.
An instant beverage premix is a pre-formulated dry or liquid concentrate combining soluble extracts, sweeteners, flavoring agents, and stabilizers in calibrated ratios, typically requiring only the addition of water or milk for reconstitution to a finished drink. These formulations serve commercial and residential users seeking speed, batch consistency, and minimal equipment investment in beverage preparation. Powdered packets and sachets capture dominant volume share due to lower shipping weights and extended shelf stability, though canister formats retain stronger margins in premium household segments. The foodservice channel generates outsized value contribution from hotels, restaurants, and cafés despite representing smaller unit volumes than retail.
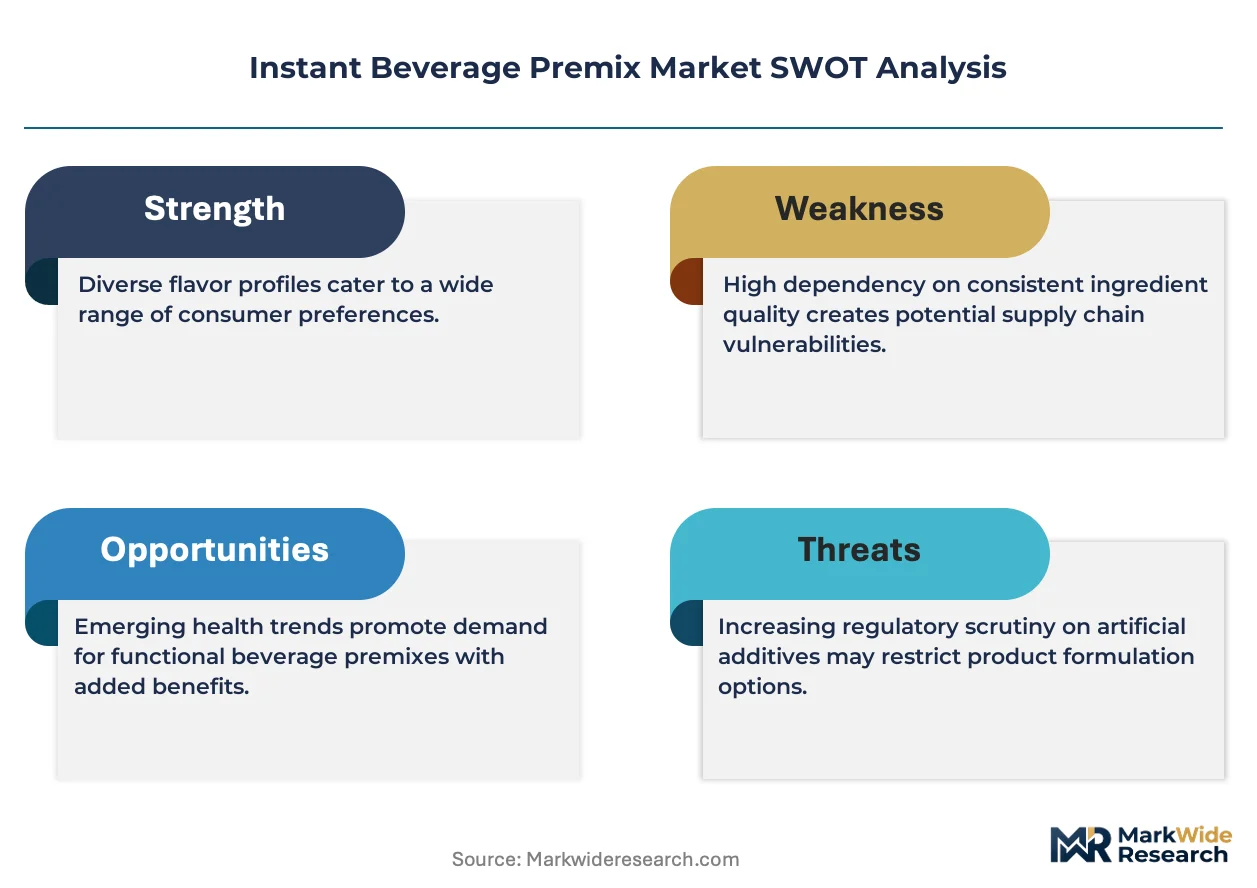
FDA nutrition labeling requirements and the EU Green Deal sustainable packaging mandates jointly reshape formulation transparency and material selection across export-oriented production. BIS certification for food-grade premixes governs market access within India, creating compliance complexity for multinational suppliers. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to regionalize packaging specifications or pursue unified global formats.
Market Dynamics
The EU Green Deal packaging rules are compressing format choices across export-oriented production, forcing manufacturers to regionalize specifications or absorb compliance costs while maintaining cross-border supply fluidity.
Growth Catalysts
- Urban café proliferation:Quick-service beverage formats in Indian metropolitan clusters multiply points of consumption for single-serve sachets.
- FSSAI alignment with ISO 22000:Indian food safety convergence streamlines supplier qualification for multinational retail procurement programs.
- Soluble extract stabilization:Advanced microencapsulation extends shelf life without refrigeration, unlocking traditional trade penetration in tropical climates.
Market Restraints
- Dairy input volatility:Powdered milk concentrate costs fluctuate with New Zealand and EU dairy auction cycles, compressing margin predictability.
- Southeast Asian supply concentration:Hotel and restaurant demand clusters in Thailand, Vietnam, and Indonesia create geographic revenue vulnerability.
- Extended producer responsibility:EU Green Deal mandates impose packaging redesign costs that disproportionately burden mid-scale exporters.
Strategic Opportunities
- Tier-two Indian cities:Lucknow, Indore, and Kochi exhibit underpenetrated modern trade beverage aisles relative to Mumbai and Delhi.
- Cold-soluble expansion:Iced coffee and chilled tea premixes address gaps in Southeast Asian hospitality outdoor service programs.
- BIS certification arbitrage:Early compliance investment creates preferential access as India's domestic standards tighten against imports.
Industry Challenges
- Formulation talent scarcity:Food technologists with dual expertise in flavor chemistry and scale-up manufacturing command premium compensation.
- Legacy equipment retrofitting:Existing dry-mix lines require capital-intensive modification to handle recyclable film specifications.
- Multi-jurisdiction label harmonization:Divergent FDA, EFSA, and FSSAI nutrition declaration formats inflate packaging SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instant Beverage Premix Market |
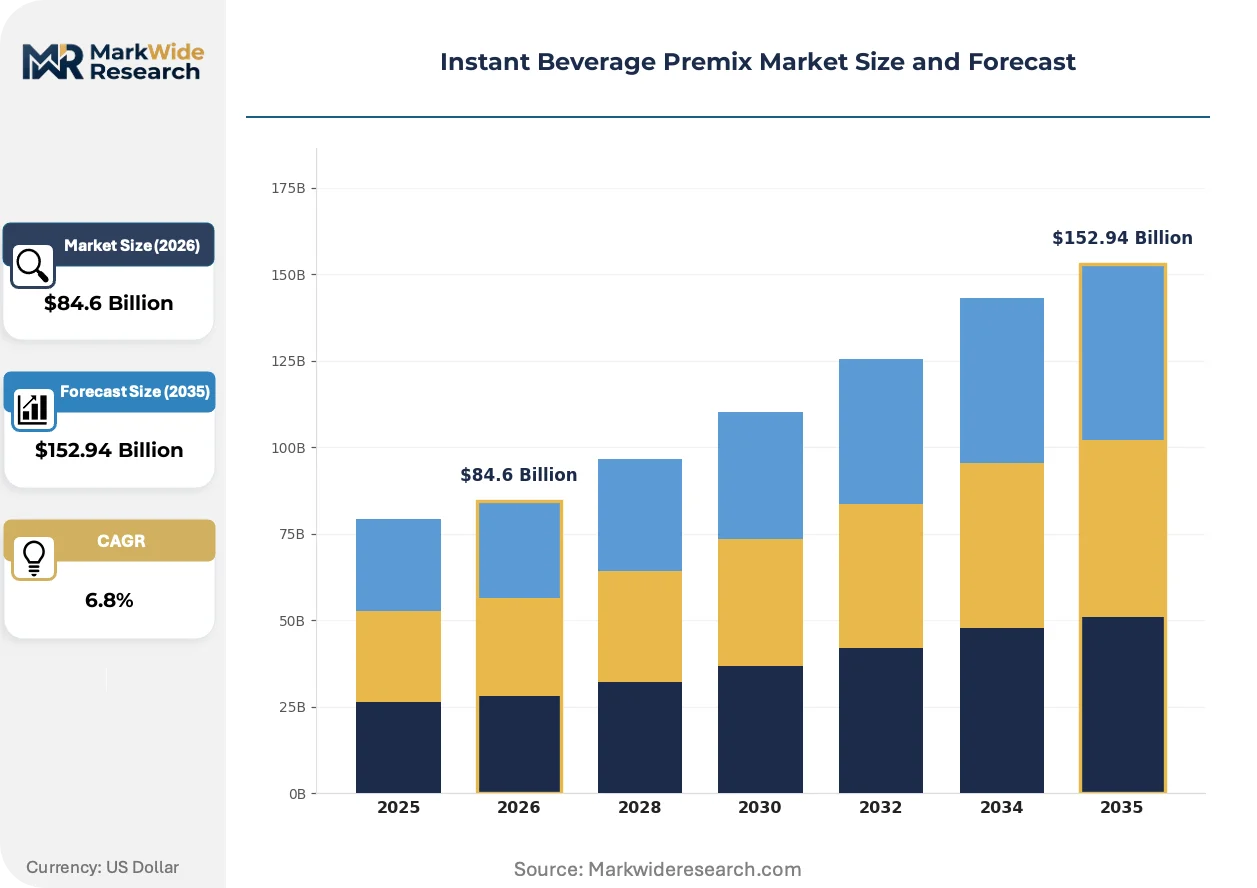
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $152.94 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tea, Coffee, Hot Chocolate, Flavored Drink Packaging Type: Powdered Packets, Sachets, Bottles, Canisters Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Foodservice End User: Households, Hotels, Restaurants, Cafés |
| Companies Covered | The Coca-Cola Co., JDE Peet's N.V., Nestlé S.A., Tata Consumer Products Limited, The Kraft Heinz Company, Unilever PLC, Mondelēz International, Inc., Starbucks Corporation, PepsiCo Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instant Beverage Premix Market Emerging Trajectories
Active packaging formats and regulatory convergence are redrawing competitive boundaries between commodity premix suppliers and premium formulation specialists.
Microencapsulation technology for volatile flavor compounds is bifurcating the premix landscape. Premium hospitality chains in Singapore and Dubai adopt these stabilized formats for menu consistency. Commodity producers without encapsulation capability face margin compression as buyers segment on sensory performance.
REACH substance restrictions on certain plasticizers are forcing laminate film reformulation across EU-bound shipments. Manufacturers must validate alternative barrier materials without sacrificing sachet seal integrity. Indian exporters to Europe bear disproportionate testing costs relative to domestic-focused competitors.
Direct procurement from roasters and dairies is consolidating buyer power among large hotel groups. Traditional distributor networks in Southeast Asian foodservice face disintermediation as chains centralize ingredient sourcing. Bangkok-based hospitality procurement consortia exemplify this concentration pattern.
Instant Beverage Premix Market Segmentation
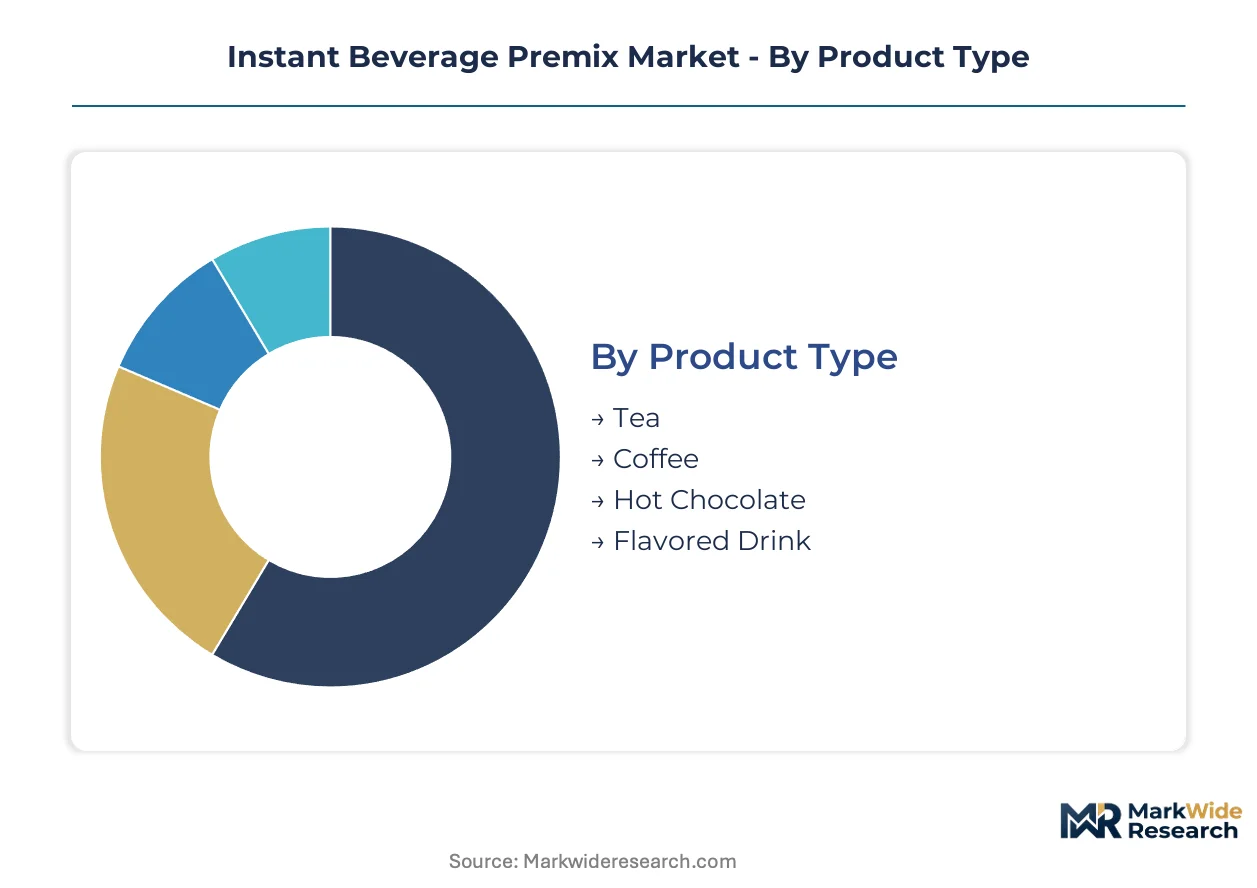
Premix suppliers calibrate formulation complexity and packaging investment against distinct consumption occasions across residential and commercial channels. Segment boundaries blur as hospitality groups adopt retail-format sachets for back-of-house consistency and households upgrade to canister formats for premium positioning.
Product Type:
Coffee and tea premixes face divergent substitution pressures from fresh-brewed alternatives, with coffee more vulnerable to capsule systems and tea to loose-leaf premiumization.
- Tea:Black and chai variants dominate South Asian household penetration, with cardamom and masala formulations commanding loyalty in Gujarat and Punjab traditional trade. Microencapsulation of volatile spice oils now enables consistent flavor release in low-temperature reconstitution.
- Coffee:Spray-dried and freeze-dried soluble formats split on price-performance, with Southeast Asian hotel breakfast programs driving freeze-dried adoption for aroma retention. Dairy-coffee blends face margin pressure from New Zealand whole milk powder auction volatility.
- Hot Chocolate:Cocoa butter replacer formulations reduce input cost exposure to Côte d'Ivoire bean price swings.
- Flavored Drink:Malt-based and fruit-flavored concentrates target pediatric and adolescent consumption in Indian school canteen procurement.
Tea anchors the volume base while coffee gains share at the steepest rate.
Packaging Type:
Format selection tracks distribution economics and shelf-life requirements, with cost tier rather than application driving most procurement decisions.
- Powdered Packets:Multi-serve foil laminates balance moisture barrier performance with tear-open convenience for Indian kirana store distribution. FSSAI-mandated nutritional disclosure panels consume 30% of printable surface area, constraining brand messaging.
- Sachets:Single-serve 15-20 gram units dominate Southeast Asian foodservice portion control, with Bangkok and Ho Chi Minh City hotel procurement consortia standardizing on 18 gram coffee sachets for breakfast buffet cost accounting.
- Bottles:Liquid concentrate formats concentrate in Vietnamese iced coffee street vendor channels for speed of service.
- Canisters:Tin-plate and composite canister formats retain household premium positioning in Mumbai and Delhi modern trade, with resealable lid designs extending post-opening stability.
Powdered packets generate the highest unit volumes while sachets expand most quickly across foodservice adoption.
Distribution Channel:
Channel mix reflects urban retail infrastructure maturity and e-commerce penetration gradients across target geographies.
- Supermarkets:Organized retail chains in Indian tier-one cities allocate dedicated beverage aisles for premium canister displays, with private label premix programs expanding at Reliance Retail and D-Mart.
- Online Retail:Quick-commerce platforms in Bangalore and Hyderabad drive sachet assortment expansion for impulse replenishment, with 10-minute delivery value propositions favoring lightweight formats.
- Convenience Stores:7-Eleven and Lawson outlets across Thailand and Indonesia stock rotating flavor promotions for traveler trial.
- Foodservice:Direct procurement contracts with Accor and Marriott properties in Dubai and Singapore bypass distributor markups for volume commitments.
Supermarkets and foodservice split value contribution while online retail climbs the fastest.
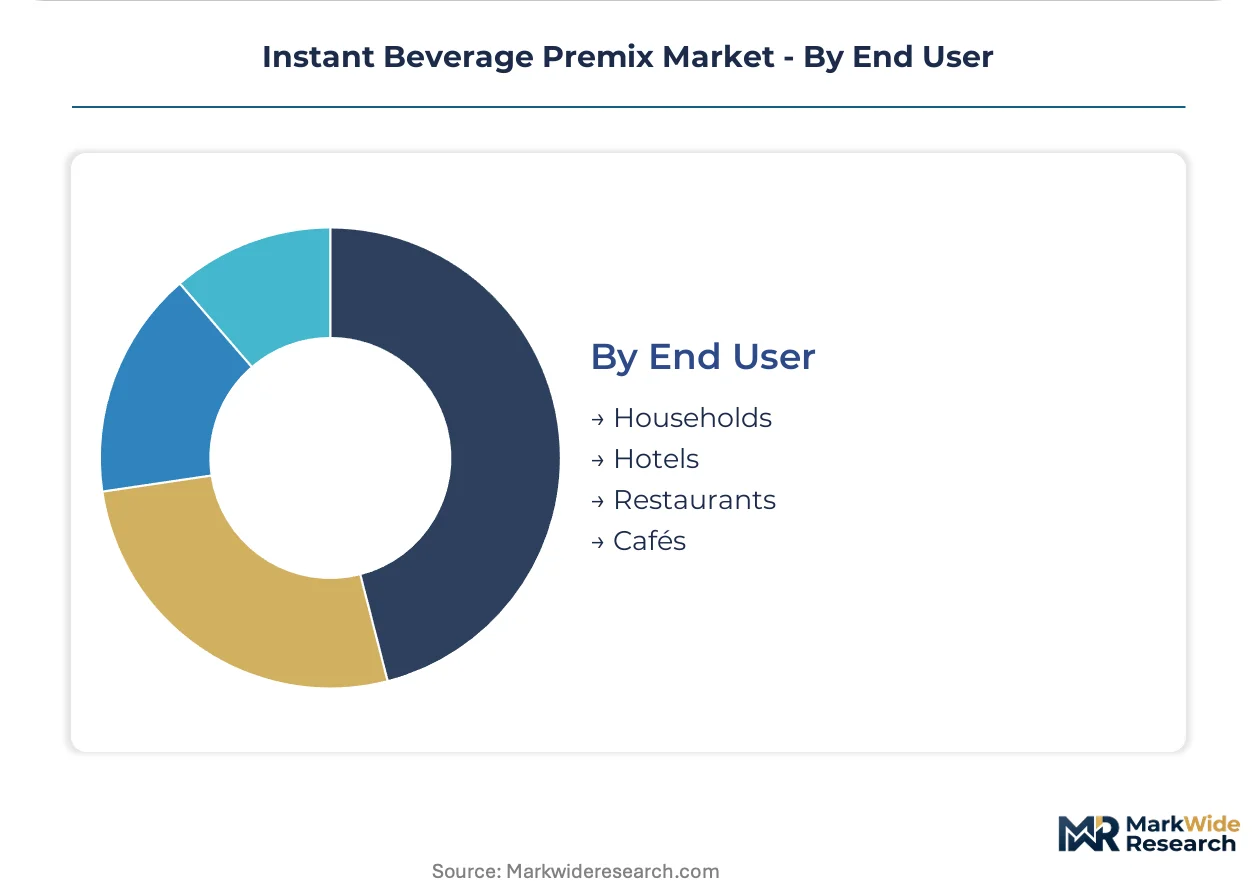
End User:
User segments diverge sharply on batch size requirements, equipment investment tolerance, and formulation complexity preferences.
- Households:Urban Indian nuclear families drive single-serve sachet trial before canister conversion, with flavor variety packs reducing perceived risk in initial purchase.
- Hotels:Full-service properties in Kerala and Rajasthan standardize on in-room tea and coffee premix amenities, with ISO 22000 certification gating supplier qualification for international chain flagships.
- Restaurants:Quick-service chains in Jakarta and Manila deploy back-of-house premix systems for beverage menu consistency across franchise locations.
- Cafés:Independent coffee shops in Bandung and Cebu adopt cold-soluble formats for iced beverage menu expansion without espresso equipment capital.
Households anchor the volume base while cafés gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foodservice procurement managers in Southeast Asian hospitality clusters and Indian quick-service operators drive the steepest volume concentration, with regulatory compliance costs fragmenting supplier access across export corridors.
India
Urban café chains in Mumbai, Bangalore, and Delhi-NCR multiply single-serve sachet consumption for back-of-house beverage programs. FSSAI alignment with ISO 22000 streamlines multinational retail qualification while tightening domestic standards. Lucknow and Indore traditional trade channels exhibit underpenetrated modern trade aisles relative to tier-one saturation.
Thailand
Bangkok hotel procurement consortia standardize 18-gram coffee sachet specifications for breakfast buffet cost accounting across Accor and Marriott properties. The country's national food and drug administration enforces labeling harmonization with ASEAN cosmetic directive frameworks. Chiang Mai and Phuket hospitality clusters drive freeze-dried soluble adoption for aroma retention in high-occupancy properties.
Vietnam
Ho Chi Minh City street vendor networks concentrate liquid concentrate formats for iced coffee speed of service without equipment capital. The Ministry of Health implements circulars on food additive limits that reshape imported premix formulation thresholds. Da Nang hospitality developments expand cold-soluble trial programs for outdoor poolside service menus.
Indonesia
Jakarta quick-service chains deploy premix systems for beverage menu consistency across sprawling franchise footprints. The national food and drug control agency enforces halal certification mandates that filter supplier eligibility for institutional procurement. Bandung independent cafés adopt cold-soluble formats to expand iced beverage menus without espresso machine investment.
Singapore
Premium hospitality chains in Marina Bay and Sentosa adopt microencapsulated formats for menu consistency across property portfolios. The Singapore Food Agency enforces strict import documentation for dairy-coffee blend ingredients that delay customs clearance for non-compliant shipments. Changi airport transit retail channels rotate flavor promotions for traveler trial in 24-hour convenience formats.
Instant Beverage Premix Market Vendor Landscape
Player mix skews toward diversified multinational conglomerates with captive ingredient sourcing infrastructure, creating tiered competition between integrated giants and regional formulation specialists. Three archetypes dominate: vertically integrated beverage conglomerates controlling upstream dairy and coffee supply, distribution-heavy South Asian traditional trade anchors, and premium hospitality-focused microencapsulation technology licensors. Competitive moves concentrate on backward integration into soluble extract production and geographic expansion through direct procurement contracts with hotel groups.
Within the integrated multinational tier, Nestlé S.A., Unilever PLC, and Tata Consumer Products Limited exemplify divergent strategic positions. Nestlé leverages in-house dairy and coffee sourcing infrastructure across multiple continents to control input cost volatility. Unilever occupies a formulation expertise position spanning both hot and cold instant beverage platforms with dual-temperature solubility capabilities. Tata Consumer Products anchors competitive position through deep distribution networks in South Asian traditional trade channels, representing the regional-heavy archetype against globally diversified competitors.
| Leading Market Players |
|---|
| The Coca-Cola Co. |
| JDE Peet's N.V. |
| Nestlé S.A. |
| Tata Consumer Products Limited |
| The Kraft Heinz Company |
| Unilever PLC |
| Mondelēz International, Inc. |
| Starbucks Corporation |
| PepsiCo Inc |
| Others |
Supply Flow & Price Mechanics
Scale economies in spray-dried soluble coffee production concentrate manufacturing capacity in Vietnam and Indonesia, compressing unit costs for bulk dairy-coffee blends while elevating price floors for microencapsulated specialty formats. This capacity concentration grants integrated multinationals procurement leverage over New Zealand whole milk powder auctions, forcing mid-scale exporters to absorb margin compression or exit commodity tiers.
Pricing Analysis
Cost-plus contracts with Global Dairy Trade indexation dominate dairy-coffee blend procurement, locking hotel chains into quarterly price adjustments that track New Zealand and EU auction cycles. Three-tier pricing structure across premium freeze-dried, standard spray-dried, and economy maltodextrin-extended tiers separates buyers by sensory performance requirements and ISO 22000 certification status. Pricing pressure stems from extended producer responsibility mandates under the EU Green Deal, which inflate packaging redesign costs for export-bound shipments. Quick-service chains in Jakarta and Manila exhibit highest price sensitivity due to franchisee margin constraints, while Singapore premium hospitality groups prioritize sensory consistency over unit cost.
Supply Chain Analysis
Inbound logistics costs through Singapore and Tanjung Pelepas ports fluctuate with container availability on Asia-Europe trade lanes, compressing landed costs for Indian exporters to EU markets. Soluble extract production concentrates in Vietnam, Indonesia, and India, with spray-drying capacity anchored in Ho Chi Minh City and Malang industrial zones. Raw material dependencies span New Zealand whole milk powder, Côte d'Ivoire cocoa butter, and Indian cardamom oleoresins. Single-source vulnerability in dairy inputs exposes margin predictability to Fonterra auction volatility. Distribution runs through Bangkok and Jakarta hospitality procurement consortia that bypass traditional distributor markups for direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The instant beverage premix market functions as a service-attach opportunity where formulation customization and technical support contracts expand faster than base product volumes, particularly as Southeast Asian hotel groups centralize procurement around sensory consistency guarantees.
For Market Incumbents: Shield margin position by accelerating backward integration into microencapsulation technology licensing, countering disintermediation from Bangkok and Singapore hospitality procurement consortia. Deepen captive supply of dairy extracts across multiple continents to buffer Global Dairy Trade auction volatility. Prioritize FSSAI-ISO 22000 dual certification investment to gate multinational retail qualification against emerging regional formulators.
For New Entrants and Emerging Players: Differentiate on cold-soluble formulation expertise targeting Bandung and Cebu independent cafés seeking iced beverage menu expansion without espresso equipment capital. Penetrate Lucknow and Indore modern trade aisles where organized retail beverage sections remain underdeveloped relative to Mumbai saturation. Pursue direct procurement contracts with tier-two Indian quick-service chains as a beachhead before scaling to franchise networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional formulation specialists with microencapsulation capability and established BIS certification compliance. Long-term viability hinges on formulation talent retention and backward integration into soluble extract production. The inflection signal to monitor is consolidation velocity among Bangkok and Ho Chi Minh City hospitality procurement consortia, which would accelerate distributor disintermediation and compress acquisition multiples for traditional channel-dependent targets.
| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Captures premium hospitality procurement in Singapore and Dubai through sensory consistency guarantees. |
| Backward Integration into Soluble Extract Production | Reduces exposure to New Zealand dairy auction cycles and Fonterra supply concentration. |
| BIS Certification Pre-Compliance Investment | Creates preferential market access as India's domestic standards tighten against import competition. |
| Cold-Soluble Format Development | Addresses unmet demand in Southeast Asian outdoor hospitality service programs without equipment capital. |
| Direct Procurement Contracting with Hotel Consortia | Bypasses distributor markups in Bangkok and Jakarta while locking volume commitments from Accor and Marriott properties. |
Methodological Framework
Initial hypotheses were tested against primary input from foodservice procurement managers, premix formulation technologists, retail category buyers, and dairy ingredient sourcing directors, then refined through secondary validation against FSSAI regulatory circulars, EU Green Deal packaging mandate documentation, Global Dairy Trade auction records, and SEC filings of listed beverage conglomerates. Bottom-up channel volume estimates were triangulated against top-down macroeconomic consumption proxies.
Variance decomposition across product type, packaging format, distribution channel, and end-user segments shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs incorporated soluble extract stabilization technology adoption curves and extended producer responsibility compliance cost trajectories.
The analysis sits within stated boundaries; outcomes outside sustained urban café proliferation in Indian tier-two cities or abrupt EU packaging mandate acceleration would require recalibration. Forecasts reflect documented assumptions about dairy input price normalization and ASEAN regulatory harmonization velocity. Recalibration cycles align with material shifts in Global Dairy Trade auction patterns and FSSAI enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Canned Soup Market
Packaged Foods
Canned Goods Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Packaged Food Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Packaged Currants Market