
 North America Ready-To-Eat Food Market | 2026-2036
North America Ready-To-Eat Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ready-To-Eat Food Market Analytics
Grocery e-commerce is tilting toward subscription and direct-to-consumer models as legacy retailers recalibrate fulfillment economics. Conagra Brands leverages its frozen-food infrastructure to sustain shelf-space dominance in conventional retail. Tyson Foods anchors protein-centric ready-to-eat portfolios through refrigerated supply chain control. HelloFresh Group competes via meal-kit customization that narrows the gap between scratch cooking and convenience.
North America ready-to-eat food comprises commercially prepared items requiring no further preparation beyond optional heating, typically formulated with moisture content below 0.85 water activity for ambient stability or blast-frozen at minus 18 degrees Celsius for extended preservation, serving time-constrained consumers and institutional food operations. Frozen foods lead volume contribution due to entrenched cold-chain infrastructure and consumer trust in sensory retention. Meal kits capture margin expansion as subscription economics reduce customer acquisition costs over repeat purchase cycles. Snacks occupy the broadest distribution footprint across convenience stores and vending channels.
The FDA governs nutrition labeling and pathogen standards under the Food Safety Modernization Act, while USDA FSIS oversees ready-to-eat meat and poultry processing facilities. The EPA regulates per- and polyfluoroalkyl substances in food-contact packaging, pressuring converters toward fluorine-free barrier technologies. Stakeholders must monitor state-level extended producer responsibility legislation in California and New York as packaging compliance costs diverge across jurisdictions.
Market Dynamics
The FDA's updated Nutrition Facts labeling rules are compressing formulation timelines as manufacturers reformulate sodium, sugar, and saturated fat levels across ambient and refrigerated portfolios to maintain shelf positioning.
Growth Catalysts
- FSMA Pathogen Standards:The Food Safety Modernization Act mandates preventive controls for human food, elevating compliance costs for smaller processors while consolidating volume with large-scale refrigerated supply chain operators.
- Dual-Income Household Density:Urban coastal corridors in the United States concentrate time-constrained consumers willing to pay premium prices for protein-forward ready-to-eat meals requiring minimal preparation.
- Blast-Freezing Infrastructure:Minus 18 degrees Celsius cold-chain networks preserve sensory attributes across extended distribution radii, extending product reach beyond traditional metropolitan markets.
Market Restraints
- Input Cost Volatility:Animal protein and specialty grain prices fluctuate with climate-driven feed crop yields, compressing gross margins for frozen meal manufacturers locked into annual retail pricing agreements.
- Fluorine-Free Barrier Migration:EPA regulations on per- and polyfluoroalkyl substances in food-contact packaging force converters to abandon legacy grease-resistant technologies before cost-competitive alternatives achieve scale.
- Refrigerated Last-Mile Constraints:Temperature-controlled e-commerce fulfillment requires capital-intensive micro-fulfillment networks that concentrate delivery economics within top-20 metropolitan statistical areas.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:California and New York state legislation mandates packaging recycling targets, creating first-mover advantages for brands deploying mono-material or fiber-based packaging ahead of compliance deadlines.
- Meal-Kit Subscription Convergence:Portion-controlled ingredient bundles with pre-prepped proteins narrow the convenience gap with scratch cooking, capturing repeat purchase economics in suburban Canadian markets.
- Convenience Store Channel Expansion:Ambient-stable protein snacks and shelf-stable bowls penetrate rural and exurban locations underserved by full-service grocery, leveraging existing tobacco and beverage distribution networks.
Industry Challenges
- Reformulation Expertise Scarcity:Food scientists capable of balancing clean-label demands with 12-month ambient shelf stability command premium compensation, constraining R&D throughput at mid-tier manufacturers.
- Legacy ERP Integration Friction:Temperature monitoring and lot-traceability requirements under FSMA strain outdated manufacturing execution systems, requiring costly middleware deployments for regulatory audit readiness.
- Co-Manufacturer Qualification Timelines:USDA FSIS facility approvals for ready-to-eat meat and poultry processing extend 18-24 months, throttling capacity expansion for brands without captive production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ready-To-Eat Food Market |
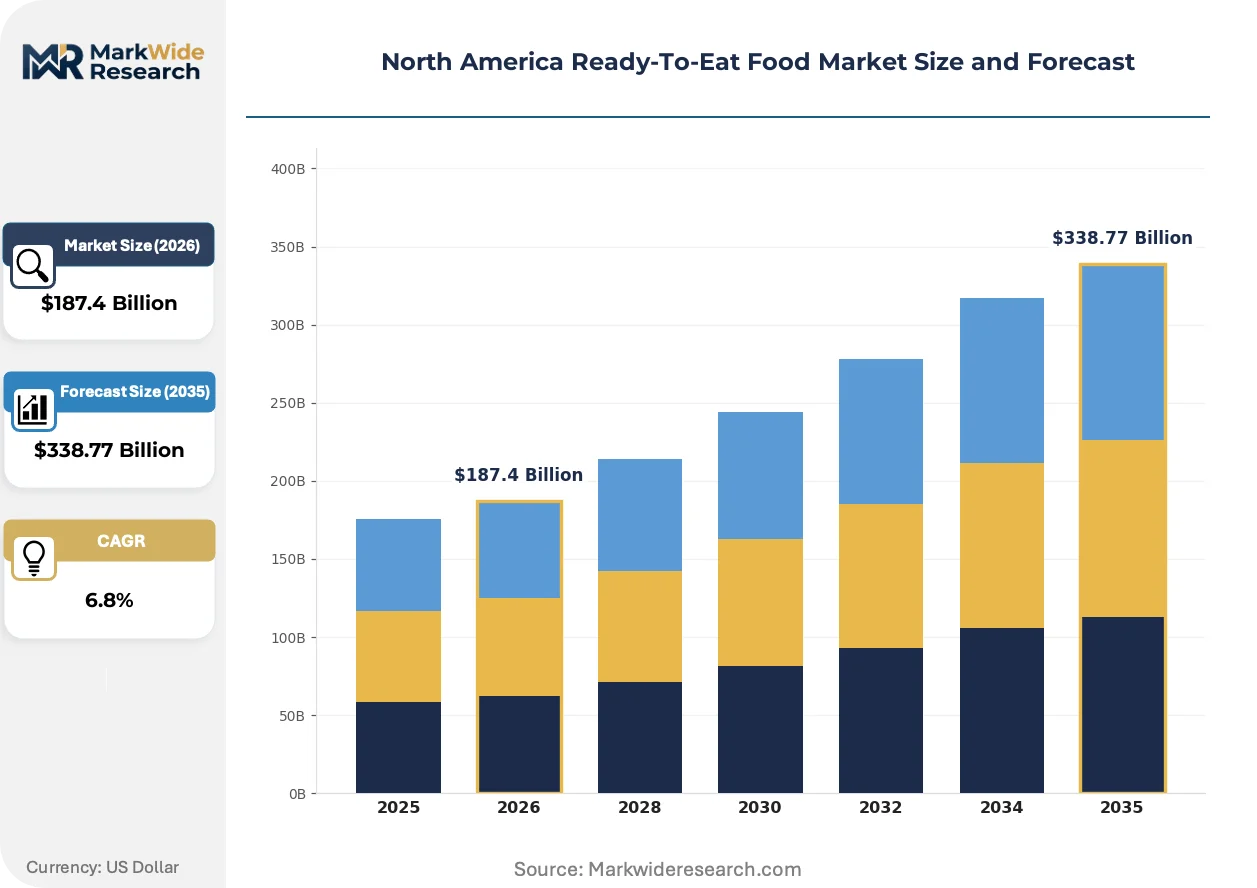
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Meal Kits, Frozen Foods, Canned Foods Packaging Type: Plastic Containers, Pouches, Boxes, Trays End User: Households, Food Service, Institutions, Retailers Sales Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers |
| Companies Covered | Nestle SA, Conagra Brands, The Kraft Heinz Company, General Mills, Tyson Foods, HelloFresh Group, Campbell Soup Company, Hormel Foods Corporation, Nomad Foods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ready-To-Eat Food Market Evolving Landscape
Refrigeration and packaging technologies are compressing the trade-off between convenience and perceived freshness, while regulatory pressure and channel fragmentation reshape competitive requirements.
High-pressure processing technology inactivates pathogens without thermal degradation, preserving organoleptic qualities in refrigerated proteins and extending shelf life. Premium retailers and foodservice operators are adopting HPP at accelerating rates. Thermal pasteurization for refrigerated ready-to-eat meats is rendering obsolete among brands targeting clean-label positioning.
California's extended producer responsibility legislation mandates 30% recycled content in food packaging by 2030, with annual escalators. This forces converters to qualify post-consumer resin streams for food-contact applications ahead of federal requirements. Frozen meal and snack manufacturers with national distribution footprints face the steepest compliance cost divergence across state jurisdictions.
Subscription-based replenishment models now capture household pantry planning decisions before in-store or browser-based shopping begins. Direct-to-consumer meal-kit operators and Amazon's Subscribe & Save program displace conventional grocery stock-up trips for core protein and grain categories. This pattern concentrates in United States suburban households with children under age twelve.
North America Ready-To-Eat Food Market Segmentation
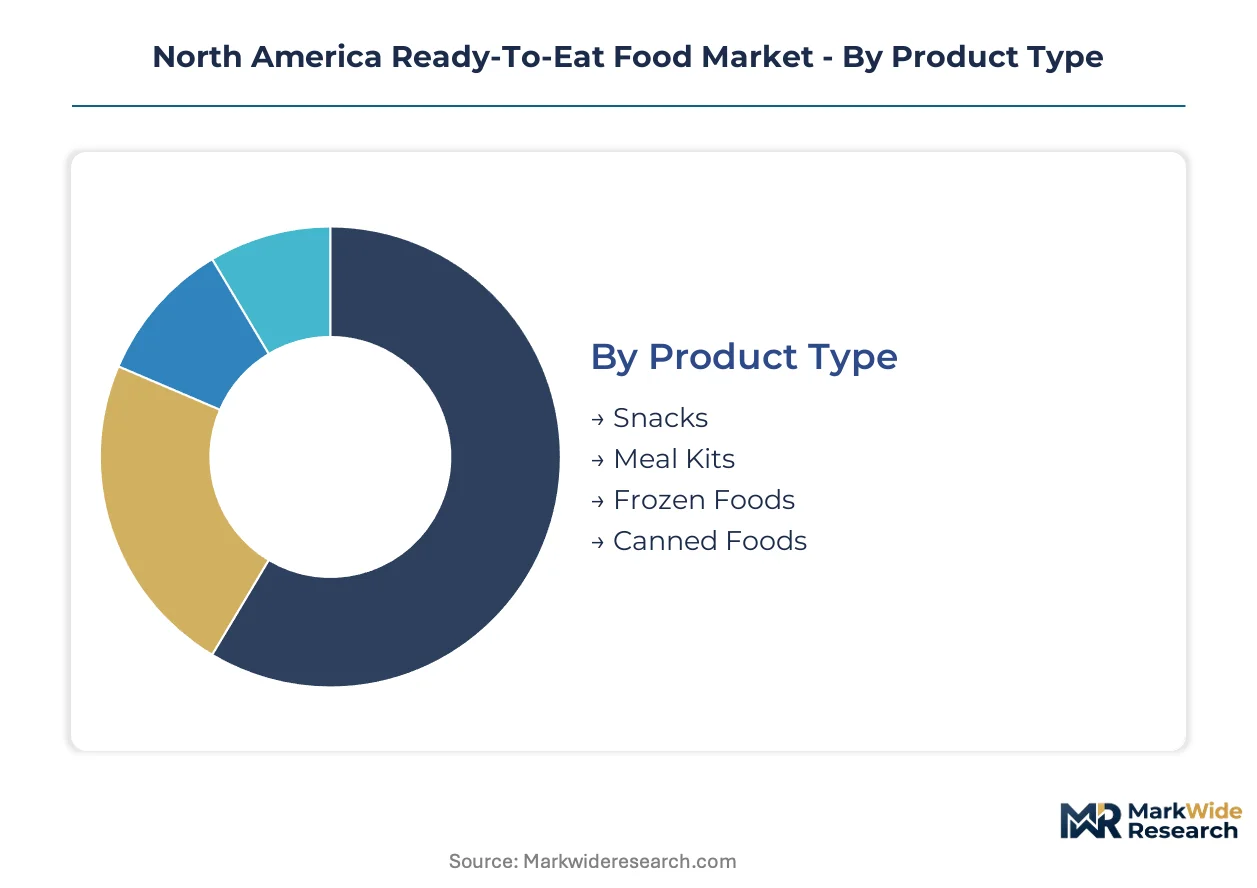
Segmentation in the North America ready-to-eat food market reveals how convenience expectations fragment across consumption occasions, packaging requirements, and procurement channels. Manufacturers configure production assets and cold-chain investments differently for each slice, with misalignment carrying immediate margin consequences.
Product Type:
Mature categories dominate refrigerated and frozen infrastructure, while emerging formats exploit subscription economics and direct-to-consumer fulfillment.
- Frozen Foods:Blast-frozen at minus 18 degrees Celsius to preserve sensory attributes across extended distribution radii. Demand concentrates in United States suburban households seeking protein-forward entrees with minimal preparation time, though locked annual retail pricing agreements compress margins during feed cost volatility.
- Meal Kits:Portion-controlled ingredient bundles with pre-prepped proteins narrow the convenience gap with scratch cooking. Subscription economics reduce customer acquisition costs over repeat purchase cycles, capturing margin expansion in Canadian suburban markets with children under twelve.
- Snacks:Ambient-stable protein formats occupy the broadest distribution footprint across convenience stores and vending channels.
- Canned Foods:Shelf-stable preservation via retort processing serves institutional buyers with extended inventory holding requirements.
Frozen foods handle the majority of throughput; meal kits are expanding most quickly on share.
Packaging Type:
Cost tiers separate commodity formats from engineered barrier solutions facing regulatory pressure on fluorinated chemistries.
- Trays:Rigid structures dominate frozen entree presentation, with converters migrating toward mono-material polypropylene to meet California extended producer responsibility targets ahead of 2030 compliance deadlines.
- Pouches:Flexible barrier formats capture ambient-stable protein snacks and shelf-stable bowls, enabling efficient cube utilization in e-commerce fulfillment.
- Plastic Containers:Refrigerated ready-to-eat meats rely on modified atmosphere sealing under FDA pathogen standards.
- Boxes:Fiber-based cartons serve meal-kit subscription bundles requiring printed branding surfaces and stack strength.
Trays absorb the largest packaging procurement spend; pouches are climbing the fastest as channel mix shifts toward convenience retail.
End User:
Volume concentrates in household procurement, while margin accrues to institutional buyers with centralized specification authority.
- Households:Dual-income density in United States urban coastal corridors drives premium pricing for protein-forward ready-to-eat meals requiring no further preparation beyond optional heating.
- Food Service:Restaurants and catering operations source refrigerated proteins under HACCP protocols, with high-pressure processing technology displacing thermal pasteurization among clean-label-positioned suppliers.
- Institutions:Healthcare and education facilities prioritize 12-month ambient shelf stability for inventory predictability.
- Retailers:Private-label development strains co-manufacturer qualification timelines as USDA FSIS facility approvals extend 18-24 months.
Households represent the largest addressable base; food service shows the steepest expansion trajectory as HPP adoption accelerates.
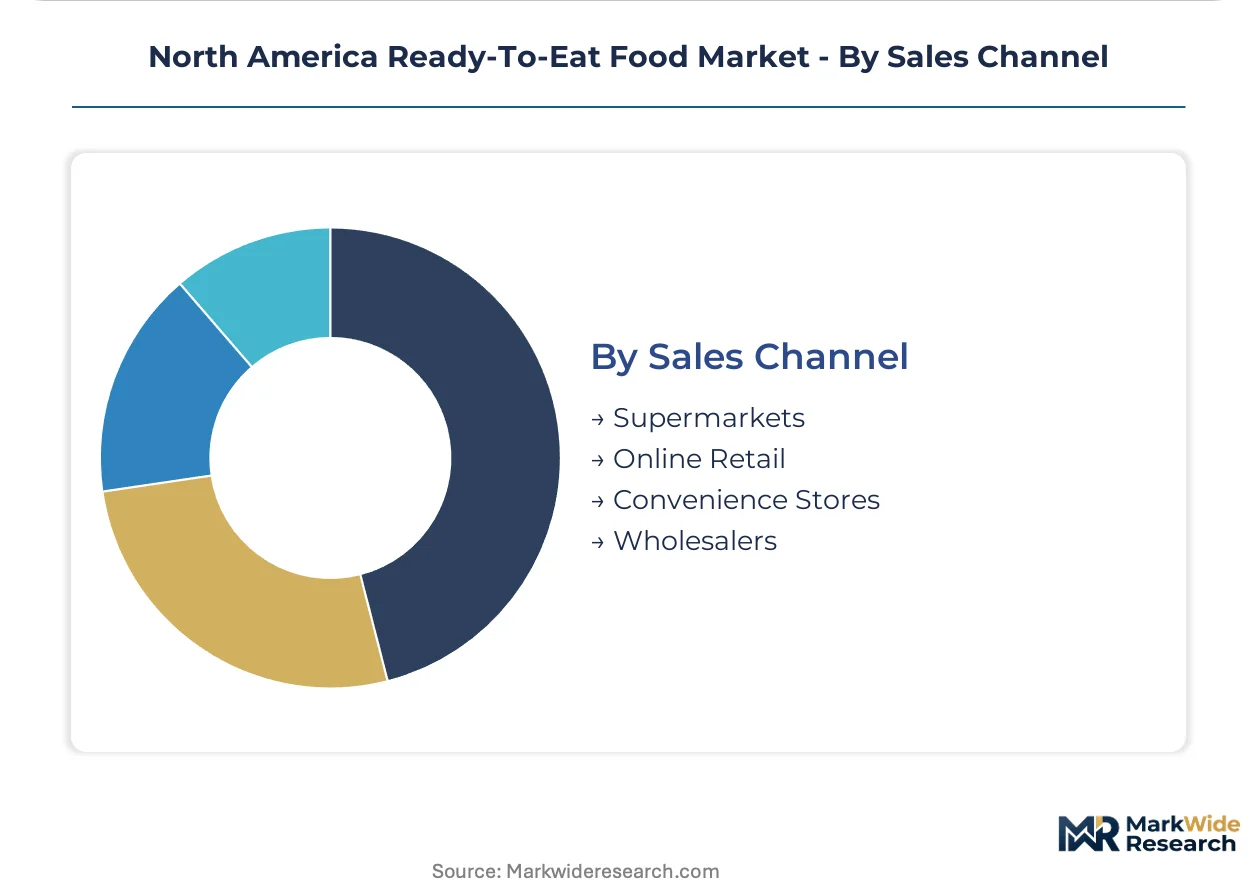
Sales Channel:
Geography dictates fulfillment economics, with refrigerated last-mile constraints concentrating viable delivery within top-20 metropolitan statistical areas.
- Supermarkets:Conventional retail shelf-space competition rewards frozen-food infrastructure scale, with legacy players leveraging existing cold-chain relationships to defend position.
- Online Retail:Temperature-controlled e-commerce fulfillment requires capital-intensive micro-fulfillment networks, limiting profitable operation to dense United States coastal corridors.
- Convenience Stores:Tobacco and beverage distribution networks enable ambient-stable protein snack penetration into rural and exurban locations underserved by full-service grocery.
- Wholesalers:Institutional procurement consolidation favors large-scale refrigerated supply chain operators with FSMA-compliant lot-traceability systems.
Supermarkets retain the dominant share of volume; online retail is gaining share fastest as subscription models capture pantry planning decisions before shopping begins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling mandates and extended producer responsibility laws in California and New York are accelerating facility upgrades and packaging conversions across the continent. Cold-chain infrastructure investments concentrate where dual-income household density supports premium pricing for protein-forward ready-to-eat meals.
United States
Urban coastal corridors from Boston to Seattle concentrate time-constrained consumers seeking minimal-preparation protein entrees. The FDA's updated Nutrition Facts rules are compressing sodium and sugar reformulation timelines for ambient and refrigerated portfolios. Chicago anchors frozen-food distribution networks that extend blast-frozen supply into secondary metropolitan markets.
Canada
Suburban households with children under twelve in Toronto and Vancouver drive meal-kit subscription adoption. Health Canada maintains pathogen standards aligned with FDA preventive controls under the Safe Food for Canadians Regulations. Montreal's refrigerated logistics hubs serve protein-centric ready-to-eat manufacturing for cross-border retail distribution.
Mexico
Middle-class expansion in Mexico City and Monterrey creates demand for shelf-stable protein snacks through convenience store channels. COFEPRIS governs nutrition labeling and food-contact material safety with increasing harmonization toward US standards. Guadalajara's manufacturing clusters supply pouched ambient meals for Central American export markets.
North America Ready-To-Eat Food Market Competitive Landscape
On the supply side, the industry is consolidating around large-scale refrigerated supply chain operators capable of absorbing FSMA compliance costs while smaller processors face qualification timeline bottlenecks. Strategic archetypes include frozen-food infrastructure defenders, meal-kit subscription specialists, and protein-centric refrigerated portfolio builders. Dominant competitive moves involve co-manufacturer capacity locking and direct-to-consumer channel bypass of conventional retail shelf-space competition.
Among diversified packaged food conglomerates, Nestle SA, Conagra Brands, and Tyson Foods exemplify contrasting scale-driven positions. Nestle SA occupies the ambient-stable multinational tier with global formulation expertise. Conagra Brands anchors frozen-food infrastructure defense through legacy retail relationships. Tyson Foods represents protein-centric vertical control from slaughter through refrigerated case-ready distribution. These three collectively illustrate how supply chain configuration determines competitive moat depth in a regulatory environment favoring preventive control investments.
| Leading Market Players |
|---|
| Nestle SA |
| Conagra Brands |
| The Kraft Heinz Company |
| General Mills |
| Tyson Foods |
| HelloFresh Group |
| Campbell Soup Company |
| Hormel Foods Corporation |
| Nomad Foods |
| Others |
Value Network & Pricing Analysis
Midwestern blast-freezing capacity concentration in Illinois and Wisconsin feeds directly into margin capture by legacy frozen-food operators with locked annual retail pricing agreements. Protein input volatility from climate-driven feed crop yields compresses gross margins for manufacturers without captive supply chain control.
Pricing Analysis
Volume-discount tiering structures dominate procurement between retailers and ready-to-eat manufacturers, with three-tier pricing separating premium clean-label SKUs from standard formulations and economy private-label lines. Price differentiation rests on sodium-reduction certification tiers and blast-freezing infrastructure scale, with the economy tier facing the steepest price erosion due to locked annual agreements during animal protein cost spikes. Premium-positioned refrigerated meals show the least price sensitivity among dual-income households in coastal corridors.
Supply Chain Analysis
Supplier-financing arrangements through extended payment terms and supply-chain finance facilities have become critical working capital tools for mid-tier processors facing FSMA compliance cost burdens. Geographic supply concentration draws from Midwestern grain belts, Southern poultry processing clusters, and Mexican vegetable production zones. Raw material dependencies center on corn and soybean feed inputs, specialty grain starches for clean-label binding, and fluorine-free barrier films. Single-source vulnerability in qualified co-manufacturer capacity for USDA FSIS meat and poultry approvals concentrates risk. Distribution runs through Chicago cold-chain hubs extending blast-frozen networks into secondary metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-platform economics are reshaping pantry planning decisions before in-store shopping begins, with direct-to-consumer interoperability between meal-kit operators and grocery delivery platforms creating new ecosystem control points.
For Market Incumbents: Harden frozen-food infrastructure defense through co-manufacturer capacity locking in USDA FSIS-approved facilities, extending 18-24 month qualification timelines as a competitive moat against emerging protein-centric entrants. Deepen backward integration into blast-freezing assets to absorb feed cost volatility without margin compression from locked annual retail pricing agreements.
For New Entrants and Emerging Players: Rural and exurban convenience store channels in the United States Mountain West and Canadian Prairie provinces remain structurally underserved by full-service grocery, offering ambient-stable protein snack penetration through existing tobacco and beverage distribution networks. Target fluorine-free barrier packaging qualification ahead of California extended producer responsibility deadlines as a first-mover compliance advantage.
For Investors and Strategic Acquirers: Capital is best deployed toward refrigerated supply chain operators with preventive control investments already amortized under FSMA, as consolidation pressure favors scale-driven compliance absorption over the next decade. Monitor meal-kit subscription churn rates as the signal indicating whether platform economics achieve sustainable repeat purchase economics or revert to conventional grocery displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Manufacturer Capacity Locking | USDA FSIS facility approvals extending 18-24 months throttle competitor expansion timelines. |
| Fluorine-Free Packaging Conversion | California's 30% recycled content mandate by 2030 forces converter qualification ahead of federal requirements. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models capture pantry planning decisions before conventional grocery trips begin. |
| High-Pressure Processing Adoption | HPP technology displaces thermal pasteurization among clean-label-positioned refrigerated protein suppliers. |
| Micro-Fulfillment Network Buildout | Temperature-controlled e-commerce fulfillment concentrates viable delivery economics within top-20 metropolitan statistical areas. |
Research Methodology
Cross-validation between primary interviews with industry stakeholders and secondary data sources anchors the qualitative findings in this study. Conversations with frozen-food plant managers, retail category buyers, refrigerated logistics operators, and food safety compliance officers were triangulated against FDA enforcement data, USDA FSIS facility inspection records, Nielsen retail audit data, and customs trade flows. Bottom-up volume modeling and top-down value reconciliation ensure internal consistency across segmentation dimensions.
Calibration against historical growth trajectories and input cost elasticity informs the analytical framework across the projection horizon. Segmentation dimensions include product type, packaging format, end-user category, and sales channel, with regional regulatory clusters modeled separately. CAGRs were derived from trend extrapolation adjusted for FSMA compliance cost absorption and cold-chain infrastructure expansion rates. Feed crop yield volatility and fluorine-free barrier film cost curves represent key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated protein processors or platform-native meal-kit operators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Packaged Salad Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Instant Soup Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Packaged Food Market
Packaged Foods
Spreads Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Canned Goods Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
North America Pasta and Noodles Market