
 Global Natural Gum Market | 2026-2036
Global Natural Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Global Natural Gum Market Outlook
Clean-label food manufacturers are rotating procurement toward plant-derived hydrocolloids with verified provenance. Cargill leverages its integrated supply chain from African acacia Belt harvesting to European refining. Kerry Group sustains application-specific R&D partnerships with bakery and beverage formulators. Nexira International dominates organic-certified gum arabic sourcing through direct farmer cooperatives in Chad and Sudan.
Natural gums comprise high-molecular-weight polysaccharides exuded from plant stems or seed endosperms, with gum arabic containing arabinogalactan-protein complexes that stabilize oil-in-water emulsions at concentrations below one percent. These biopolymers function as thickeners, stabilizers, film-formers, and controlled-release matrices across food, pharmaceutical, and industrial systems. Gum arabic retains the largest revenue pool in food and beverages due to its irreplaceable emulsification performance in soft drink concentrates. Guar gum exhibits the fastest volume trajectory, propelled by shale oil drilling fluid demand and gluten-free bakery expansion. Xanthan gum holds mature positioning in personal care rheology modification, where price competition from fermentation-derived alternatives constrains margin expansion.
The FDA governs natural gum food additive status through GRAS notifications and food-contact substance evaluations, while EFSA establishes purity specifications under food improvement agent regulations. REACH requires full toxicological dossiers for gum-derived substances imported above one-tonne thresholds into European Union member states. India's FSSAI mandates heavy-metal and microbial contamination limits for domestically processed guar destined for export. Stakeholders must monitor evolving EUDR deforestation-free supply chain verification requirements and their implementation timelines for African-origin gum arabic.
Market Dynamics
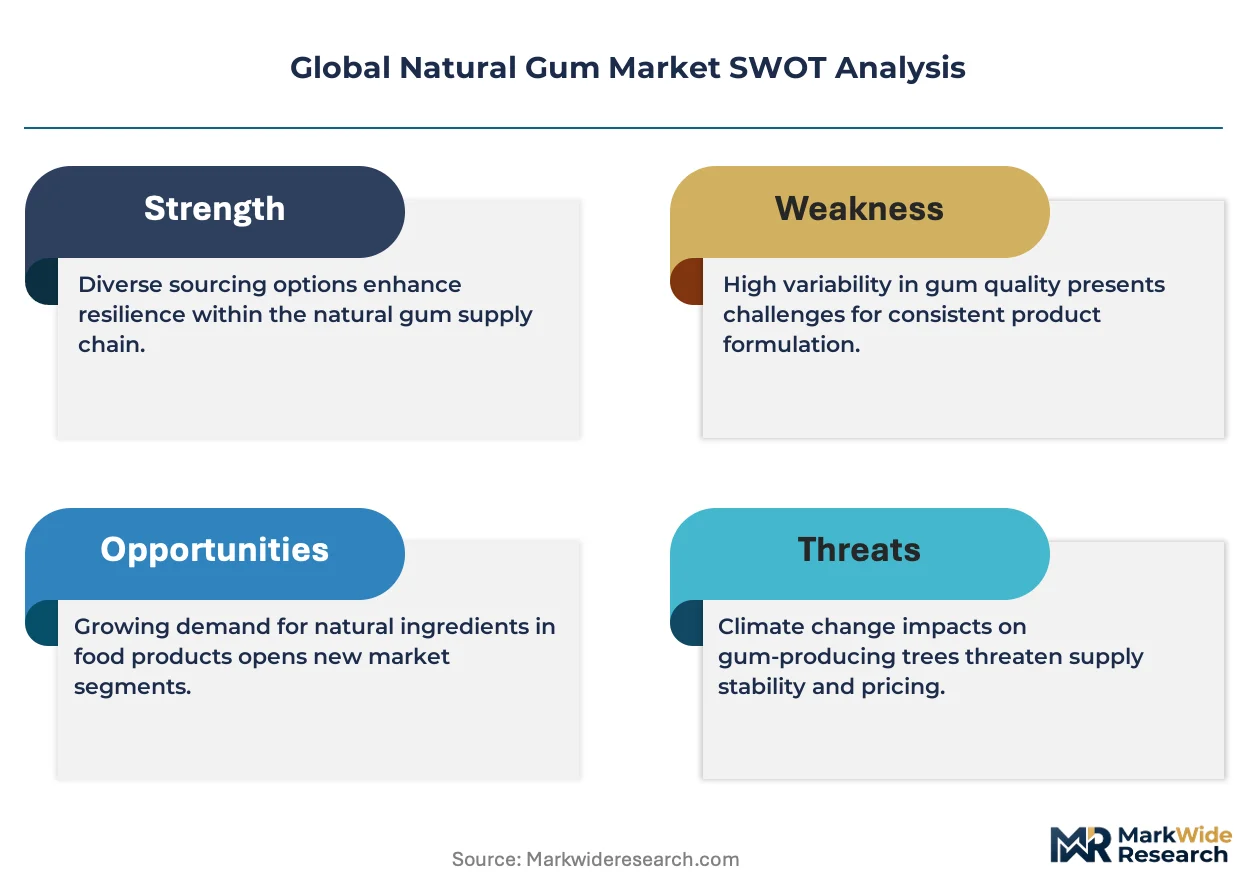
Clean-label formulation mandates from EU Green Deal traceability requirements are forcing food manufacturers to requalify entire gum supply chains, compressing procurement timelines and elevating certified-origin premiums.
Growth Catalysts
- EU Deforestation Regulation (EUDR):Mandatory geolocation verification for African-origin gum arabic is accelerating investment in farmer-level digital traceability systems across Sudan and Chad.
- Shale drilling fluid chemistry:Crosslinked guar derivatives maintain viscosity under high-salinity downhole conditions, sustaining replacement demand for synthetic polymers in Permian Basin operations.
- FSSAI export certification:India's tightened heavy-metal and microbial standards for processed guar are screening out informal processors, consolidating volume toward Rajasthan and Gujarat clusters.
Market Restraints
- Acacia senegal supply concentration:Over 70 percent of food-grade gum arabic originates from the Sudan-Chad Sahel corridor, exposing buyers to climate-induced harvest volatility and political risk.
- Fermentation-derived hydrocolloids:Xanthan and gellan gums produced via controlled bioprocesses offer batch-to-batch consistency that wild-harvested exudates cannot match, pressuring price positioning in personal care.
- REACH dossier costs:Full toxicological registration for gum-derived substances above one-tonne import thresholds imposes fixed compliance burdens that disadvantage smaller EU importers.
Strategic Opportunities
- Cell-cultured meat scaffolding:Plant-derived hydrogels from locust bean and tara gums demonstrate tunable gelation profiles for three-dimensional tissue engineering applications.
- Indian PLI scheme for food processing:Domestic value-addition incentives support backward integration into guar splitting and derivative manufacturing for export markets.
- Pharmaceutical controlled-release:Acacia and karaya gum matrices enable pH-dependent drug delivery formulations, opening prescription drug applications beyond over-the-counter nutraceuticals.
Industry Challenges
- Farmer cooperative digitization:Geolocation tagging and chain-of-custody documentation for EUDR compliance requires smartphone penetration and data infrastructure that remains uneven across Sahel harvesting zones.
- Derivative R&D scale-up:Carboxymethyl and hydroxypropyl guar modifications demand continuous reactor investment that regional Indian processors struggle to finance without offtake guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Natural Gum Market |
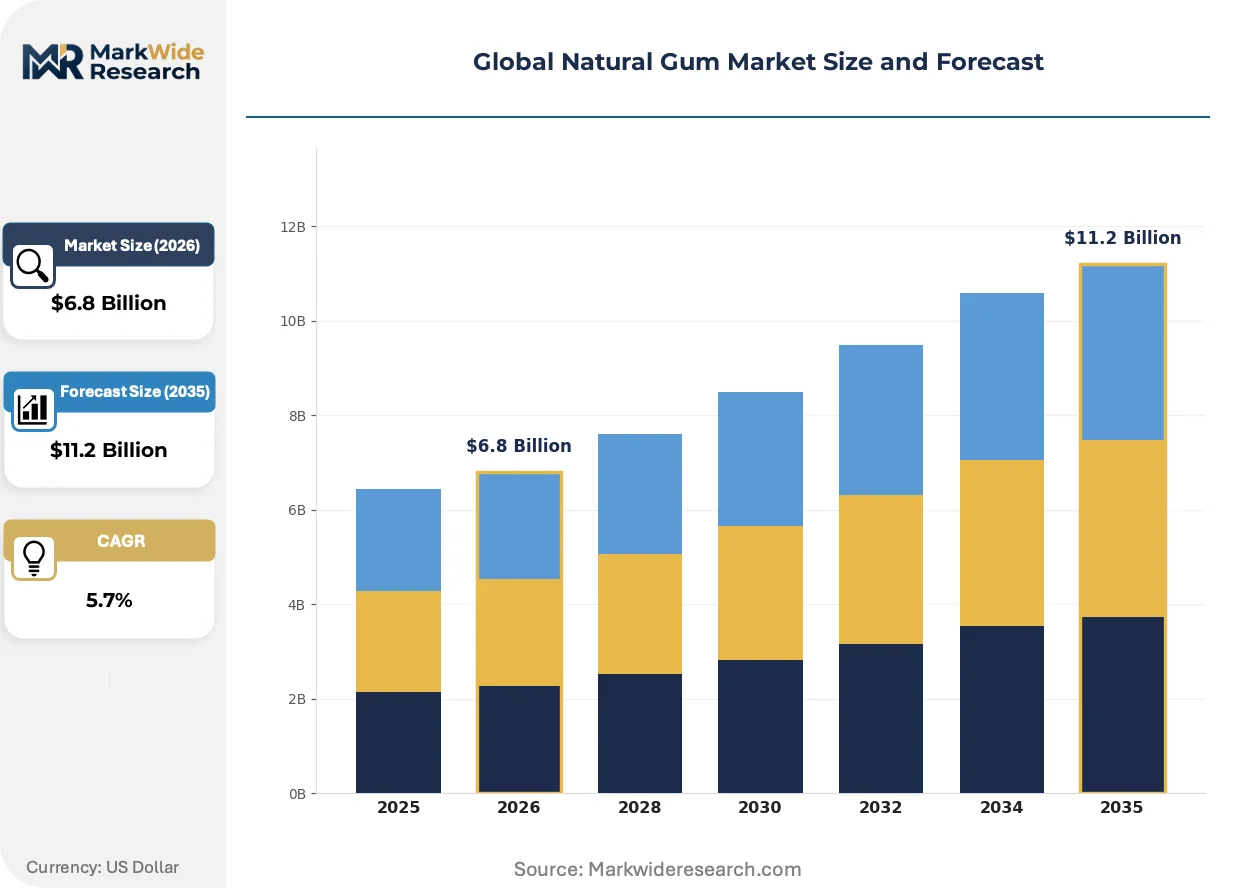
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gum Arabic, Guar Gum, Xanthan Gum, Gum Tragacanth Application: Food & Beverages, Pharmaceuticals, Personal Care, Textiles End User: Manufacturing, Retail, Healthcare, Food Service Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | Symrise, Cargill, CP Kelco, Ingredion Incorporated, Kerry Group, Nexira International, Archer Daniels Midland Company, Tate Lyle, Ashland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Natural Gum Market Strategic Shifts
Biopolymer functionality is fragmenting along performance-versus-sustainability axes, with formulators accepting trade-offs between rheological precision and regenerative sourcing credentials.
Enzymatically debranched guar variants are bifurcating the hydrocolloid specification landscape. These modified polysaccharides deliver cold-water solubility without hydration lag, attracting ready-to-drink beverage formulators who previously tolerated xanthan off-notes. The technology is compressing demand for conventional heat-hydrated guar in instant applications while creating premium tiers around enzymatic processing.
REACH Annex XV dossier expansion is tightening impurity thresholds for botanical extracts entering European Union member states. ECHA evaluations now demand full constituent disclosure for gum arabic oligosaccharide fractions, forcing refiners to invest in chromatographic purification capacity. Food additive and pharmaceutical excipient segments are responding by dual-sourcing from Sudanese and Senegalese origins to diversify regulatory risk.
Direct farmer contracting is displacing spot-market purchasing for certified-organic gum arabic. Specialty ingredient distributors are building exclusive supply relationships with Chad and Sudan cooperatives, bypassing traditional gum auction houses in Port Sudan. This channel restructuring concentrates procurement leverage with integrated handlers who control both harvesting networks and European refining assets.
Global Natural Gum Market Segmentation
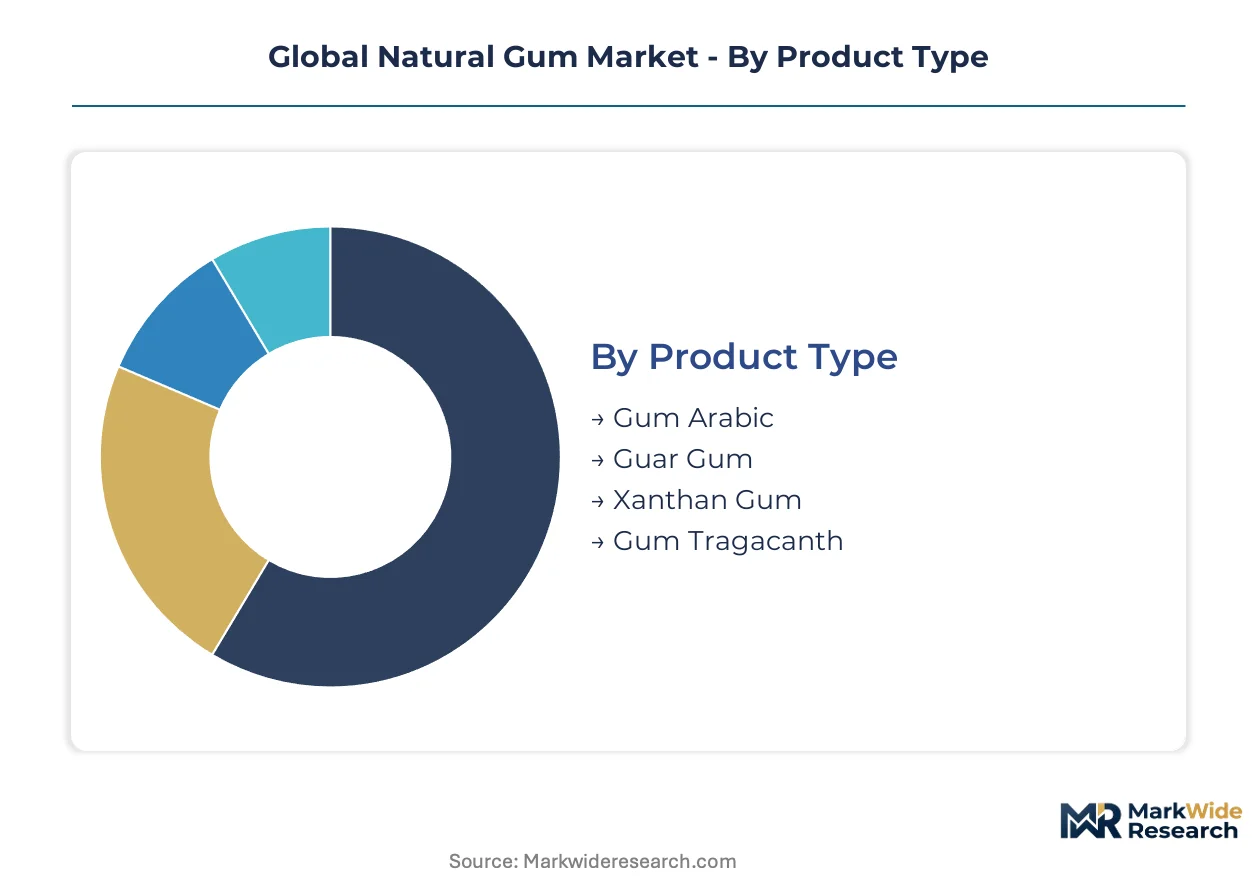
Natural gum procurement strategies diverge sharply across product categories, with regulatory purity specifications and end-use performance requirements dicting supplier qualification criteria. Food and pharmaceutical formulators maintain parallel sourcing channels to manage contamination risk and traceability mandates.
Product Type:
REACH Annex XV dossier requirements and FDA GRAS notification pathways create divergent compliance burdens across botanical hydrocolloid categories, reshaping competitive positioning between wild-harvested and fermentation-derived alternatives.
- Gum Arabic:Arabinogalactan-protein complexes from Acacia senegal and Acacia seyal exudates deliver irreplaceable emulsification at sub-one-percent concentrations in soft drink concentrates. Sudan and Chad supply chains dominate food-grade volumes, though EUDR geolocation mandates are accelerating farmer-level digital traceability investment.
- Guar Gum:High-molecular-weight galactomannan polysaccharides from Cyamopsis tetragonoloba seed endosperms function as thickeners and shale drilling fluid viscosifiers. Rajasthan and Gujarat processing clusters consolidate export volume under tightened FSSAI heavy-metal and microbial certification.
- Xanthan Gum:Fermentation-derived extracellular polysaccharides from Xanthomonas campestris bioprocesses offer batch-to-batch consistency that wild-harvested exudates cannot match.
- Gum Tragacanth:Complex water-soluble polysaccharides from Astragalus species root exudates serve niche pharmaceutical emulsion and suspension applications.
Established volume favors gum arabic; emerging adoption favors guar gum derivatives in oilfield chemistry.
Application:
End-use performance specifications determine hydrocolloid selection, with food emulsification demanding different rheological profiles than pharmaceutical controlled-release matrices.
- Food & Beverages:Clean-label formulation mandates from EU Green Deal traceability requirements are forcing manufacturers to requalify entire gum supply chains. Beverage emulsification relies on gum arabic; bakery and gluten-free applications favor guar for dough conditioning.
- Pharmaceuticals:Acacia and karaya gum matrices enable pH-dependent drug delivery formulations beyond over-the-counter nutraceuticals. EMA and FDA excipient monographs dictate heavy-metal and microbial purity thresholds that refiners must certify.
- Personal Care:Xanthan gum holds mature positioning in rheology modification for lotions and creams, though price competition from fermentation alternatives constrains margin expansion.
- Textiles:Guar derivatives function as sizing agents and printing thickeners, with carboxymethyl modifications improving dye affinity and wash-fastness properties.
Revenue concentration sits with food and beverage emulsification; steepest expansion trajectory appears in pharmaceutical controlled-release applications.
End User:
Procurement scale and specification control vary dramatically across buyer types, with integrated manufacturers capturing cost advantages unavailable to fragmented retail channels.
- Manufacturing:Food and beverage producers, pharmaceutical formulators, and oilfield chemical blenders purchase gum arabic and guar derivatives in bulk volumes with customized viscosity and hydration specifications.
- Retail:Specialty food stores and online direct-to-consumer channels move small-format organic-certified gum products for home baking and clean-label cooking.
- Healthcare:Hospital pharmacies and compounding facilities source pharmaceutical-grade acacia for extemporaneous formulation and tablet binding.
- Food Service:Restaurant chains and institutional caterers procure pre-hydrated gum blends through broadline distributors for sauce stabilization and texture modification.
Volume scale favors manufacturing procurement; specification complexity favors healthcare channel premiums.
Distribution Channel:
Channel selection reflects buyer technical capability, with direct relationships enabling custom derivative development that distributor intermediaries cannot support.
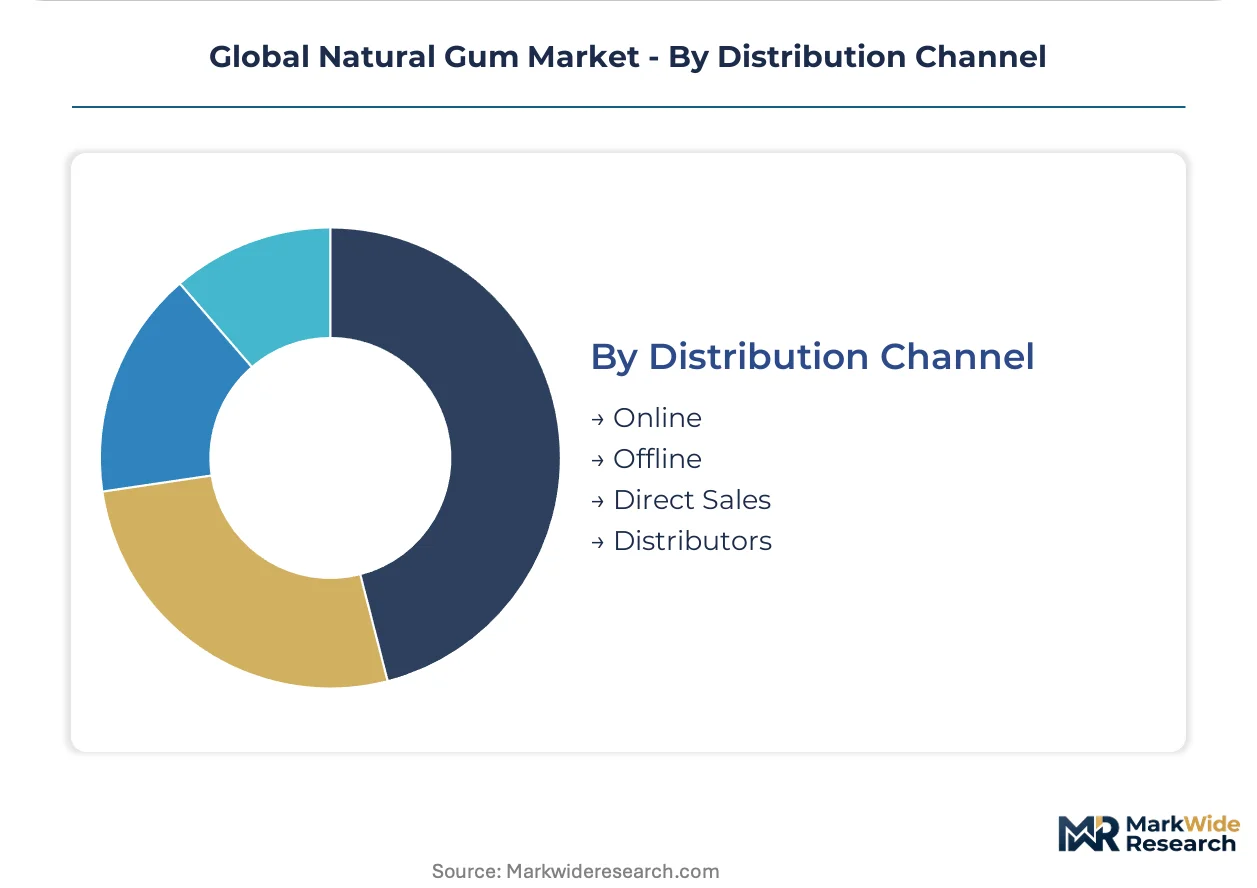
- Online:E-commerce platforms serve retail and small-scale food service buyers with standardized grades and rapid delivery, though technical support remains limited.
- Offline:Traditional brick-and-mortar distribution through ingredient wholesalers maintains relevance for bakeries and regional food manufacturers requiring immediate availability.
- Direct Sales:Integrated gum handlers like Nexira International and Cargill bypass auction houses to contract directly with Sudanese and Chadian farmer cooperatives, controlling both harvesting networks and European refining assets.
- Distributors:Specialty chemical distributors aggregate multiple hydrocolloid lines for personal care and textile formulators seeking single-source procurement efficiency.
Traceability control favors direct sales relationships; convenience and credit terms favor distributor channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sudan and Chad ship raw gum arabic through Port Sudan to European refiners in France and Germany, while Indian processors in Rajasthan and Gujarat export refined guar derivatives to North American oilfield operators.
United States
Shale operators in the Permian Basin consume crosslinked guar derivatives for high-salinity drilling fluids. The EPA oversees chemical disclosure requirements for hydraulic fracturing additives. Houston and Midland host blending facilities that formulate gum-based rheology modifiers for downhole applications.
India
Rajasthan and Gujarat clusters process guar splits for export to food and oilfield markets. The FSSAI mandates heavy-metal and microbial certification that screens out informal processors. Jodhpur and Ahmedabad refiners consolidate volume under tightened export standards.
Germany
REACH dossier requirements impose toxicological registration burdens on gum-derived substance importers above one-tonne thresholds. The ECHA evaluates full constituent disclosure for botanical extracts. Hamburg and Frankfurt house refiners investing in chromatographic purification capacity for gum arabic oligosaccharide fractions.
France
Food-grade gum arabic refiners serve soft drink concentrate manufacturers under EU Green Deal traceability mandates. The EUDR requires geolocation verification for African-origin imports. Rouen and Marseille facilities source directly from Chadian and Sudanese farmer cooperatives.
China
Personal care formulators import xanthan gum for rheology modification in lotions and creams. The SAMR governs food additive safety assessments under national standards. Shanghai and Guangzhou distributors aggregate hydrocolloid lines for domestic cosmetic manufacturers.
Global Natural Gum Market Competitive Environment
Listed leaders compete with private specialists across integrated supply chain control, with publicly traded agribusinesses leveraging balance sheet capacity for farmer-network investments while family-owned processors retain flexibility in specialty derivative batches. The vendor base organizes around three archetypes: integrated agricultural conglomerates with captive harvesting networks, regional processors with backward integration into splitting and milling, and application-focused formulators with technical service capabilities. Dominant competitive moves include direct farmer contracting to bypass traditional auction houses and capacity expansion in enzymatic modification for cold-water soluble grades.
Within the integrated agricultural tier, Cargill and Archer Daniels Midland Company exemplify supply chain control from African acacia Belt harvesting to European refining. Nexira International occupies a position among specialty distributors building exclusive cooperative relationships in Chad and Sudan. Kerry Group represents the application-focused archetype with sustained R&D partnerships across bakery and beverage formulators.
| Leading Market Players |
|---|
| Symrise |
| Cargill |
| CP Kelco |
| Ingredion Incorporated |
| Kerry Group |
| Nexira International |
| Archer Daniels Midland Company |
| Tate Lyle |
| Ashland |
| Others |
Value Chain & Pricing Dynamics
Fermentation-derived hydrocolloids replacing wild-harvested exudates in personal care formulations simultaneously shift procurement geography from Sahel harvesting zones to bioprocessing facilities and compress price premiums for batch-to-batch consistency. This substitution dynamic concentrates buyer leverage with fermentation specialists while fragmenting premium pricing power among traceability-certified gum arabic handlers.
Pricing Analysis
Technology-generation pricing gaps separate enzymatically modified cold-water soluble guar from conventional heat-hydrated grades and unmodified seed splits. Three-tier pricing structure across enzymatic premium, standard refined, and raw split economy levels reflects hydration performance and certification status. Price differentiation hinges on EUDR geolocation verification and organic certification tier. Cost compression in standard guar derivatives is intensifying because Indian FSSAI export standards screen out informal processors. Food and beverage manufacturers show least price sensitivity for gum arabic emulsification grades; personal care formulators exhibit highest sensitivity to xanthan alternatives.
Supply Chain Analysis
Sudan and Chad anchor gum arabic harvesting through farmer cooperatives, while Rajasthan and Gujarat cluster guar splitting and derivative manufacturing. Raw material flows draw from Acacia senegal exudates, Cyamopsis tetragonoloba seed endosperms, and Xanthomonas campestris fermentation feedstocks. Single-source vulnerability concentrates in the Sudan-Chad Sahel corridor where climate-induced harvest volatility and political risk disrupt food-grade supply. Distribution runs through integrated handlers controlling both African harvesting networks and European refining assets, bypassing traditional Port Sudan auction houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against fermentation-derived hydrocolloids that threaten wild-harvested exudate positioning in personal care and food applications. Incumbents must differentiate on traceability credentials that bioprocessed alternatives cannot replicate.
For Market Incumbents: Consolidate farmer-level digital traceability investment in Sudan and Chad to preempt EUDR compliance failures that would disqualify supply from EU food manufacturers. Deepen backward integration into enzymatic modification capacity for cold-water soluble guar derivatives that command premium positioning against xanthan in ready-to-drink beverages. Lock in long-term offtake agreements with Permian Basin shale operators to secure demand visibility for crosslinked guar derivatives. For New Entrants and Emerging Players: Anchor in pharmaceutical controlled-release applications where acacia and karaya gum matrices enable pH-dependent drug delivery beyond saturated food emulsification markets. Target cell-cultured meat scaffolding as a white-space application where locust bean and tara gum hydrogels demonstrate tunable gelation profiles that fermentation alternatives have not penetrated. Lead with technical service partnerships demonstrating three-dimensional tissue engineering performance to differentiate from commodity hydrocolloid suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated handlers with captive African harvesting networks and European refining assets over fragmented regional processors. Long-term viability over the next decade rests on regulatory compliance infrastructure that informal competitors cannot replicate. Acquisition target archetype: Indian guar processors with FSSAI-certified export capacity and underutilized derivative modification reactors. The signal to watch is EUDR implementation timelines accelerating farmer cooperative digitization investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Farmer Cooperative Digitization | EUDR geolocation compliance secures EU market access for Sudanese and Chadian gum arabic exporters. |
| Enzymatic Modification Capacity Expansion | Cold-water soluble guar variants capture ready-to-drink beverage share from xanthan formulations. |
| Direct Sales Channel Development | Bypassing Port Sudan auction houses concentrates procurement leverage with integrated handlers. |
| Pharmaceutical Excipient Certification | EMA and FDA monograph compliance opens prescription drug applications beyond nutraceuticals. |
| Backward Integration into Guar Splitting | Indian PLI scheme incentives support captive supply for export derivative manufacturing. |
Study Parameters
The analysis maps gum arabic harvesting and refining, guar processing and derivative manufacturing, and fermentation-derived hydrocolloid production, each validated through technical interviews with food formulation chemists, pharmaceutical excipient procurement managers, and oilfield chemical blenders. Primary fieldwork combined with secondary validation from EFSA food improvement agent regulations, ECHA REACH dossier evaluations, Indian FSSAI export certification standards, and US EPA hydraulic fracturing chemical disclosure requirements. Bottom-up volume modeling across product categories triangulated against top-down demand aggregation from end-use applications.
Consistency checks validated outputs against external benchmarks including customs trade data for gum arabic and guar gum shipments, SEC filings from integrated agricultural conglomerates, and industry association reports from regional processing clusters. The analytical framework modeled product type, application, and end-user segmentation dimensions across the projection horizon, with regional regulatory clusters as an additional cross-cutting variable. CAGRs derived from historical volume trajectories adjusted for substitution elasticity between wild-harvested and fermentation-derived alternatives. Forecast inputs incorporated EUDR implementation timelines and Indian PLI scheme uptake rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal traceability enforcement and stable shale drilling activity in North American basins; material deviation in either driver would warrant model refresh. Specific risks include accelerated fermentation hydrocolloid cost reduction, Sahel corridor political disruption, or pharmaceutical excipient regulatory rejection. Recalibration cycles align with material shifts in EUDR implementation deadlines and FSSAI certification standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Food Amino Acids Market
Ingredients
Liquid Feed Market
Ingredients
Asia-Pacific Whey Protein Ingredients Market
Ingredients
Europe Algae Omega-3 Ingredients Market
Ingredients
North America Prebiotic Ingredients Market
Ingredients
Fruit Powder Market
Ingredients
Confectionery Ingredients Market
Ingredients
North America Rice Protein Ingredients Market
Ingredients
Textured Soy Flour Market
Ingredients
Roasted Grain Ingredients Market
Ingredients
Textured Wheat Protein Market
Ingredients
Lupin Flour Market
Ingredients
Trait Enhanced Oils Market
Ingredients
Kairomones Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
Bean Pasta Market