
 Nutritive Sweeteners Market | 2026-2036
Nutritive Sweeteners Market Size, Share, and Industry Trends Forecast 2026-2036
Nutritive Sweeteners Market Analytics
Precision fermentation and enzymatic conversion is reshaping how starch-derived sweeteners achieve higher purity grades at lower energy intensity. Cargill leverages backward integration into corn wet milling to secure feedstock cost advantages across North American operations. Südzucker anchors its European position through beet sugar specialization and closed-loop agricultural partnerships. Ajinomoto competes in the high-purity glucose-fructose segment through amino acid process synergies at its Japanese manufacturing complexes.
Nutritive sweeteners are caloric carbohydrate additives derived from starch hydrolysis or sucrose extraction, typically specified by dextrose equivalence values ranging from below twenty for maltodextrins to above ninety for glucose syrups, functioning primarily to provide bulk, browning, and osmotic control in processed foods. Sucrose retains the largest value pool within product type segmentation due to its universal compatibility across bakery and dairy matrices, though maltodextrin is gaining share in sports nutrition and infant formula where low sweetness with high solids content is functionally critical. Liquid form dominates beverage manufacturing for ease of handling and dissolution, while powder and granule forms command premium positioning in pharmaceutical tableting and dry-mix applications.
The FDA enforces added sugars disclosure on Nutrition Facts panels, directly pressuring reformulation toward reduced-sucrose blends in US-manufactured products. EFSA evaluates glycemic response claims under the EU Health Claims Regulation, shaping how glucose syrup and fructose can be marketed to European food manufacturers. Stakeholders must monitor evolving WHO guidance on free sugars thresholds, as these recommendations cascade into national dietary guidelines and procurement specifications for healthcare and institutional food service channels.
Market Dynamics
Precision fermentation is compressing capital requirements for high-purity glucose-fructose production while FDA and EFSA added-sugar disclosure rules force simultaneous reformulation across beverage and confectionery supply chains.
Growth Catalysts
- Clean-Label Reformulation Mandates:Food manufacturers in the United States are accelerating procurement of maltodextrin and glucose syrup to replace sucrose in processed goods while maintaining bulk and mouthfeel.
- EFSA Glycemic Response Framework:European health claims evaluation under EU Health Claims Regulation is creating certified positioning for low-glycemic sweetener blends in sports nutrition and clinical nutrition segments.
- Enzymatic Conversion Advances:Immobilized enzyme systems are reducing energy intensity in starch hydrolysis, enabling smaller-scale producers to achieve dextrose equivalence grades previously requiring integrated wet-milling operations.
Market Restraints
- Corn Feedstock Volatility:Dextrose and glucose syrup producers face margin compression when corn futures spike, as wet-milling operations lack short-term feedstock flexibility.
- Beet Sugar Supply Concentration:European sucrose availability depends heavily on climatic yields in France and Germany, creating regional supply vulnerability during adverse growing seasons.
- WHO Free Sugars Thresholds:Cascading national dietary guidelines based on WHO recommendations are restricting institutional procurement specifications for healthcare and school foodservice channels.
Strategic Opportunities
- Infant Formula Fortification:Maltodextrin with controlled dextrose equivalence is penetrating pediatric nutrition as manufacturers seek carbohydrate sources with minimal sweetness contribution and high solids content.
- India FSSAI Labeling Alignment:India's Food Safety and Standards Authority is tightening added-sugar disclosure requirements, creating demand for reformulation expertise and alternative sweetener blends in processed dairy and beverages.
- Precision Fermentation Convergence:Integration of cell-free enzymatic systems with continuous chromatography is enabling novel glucose-fructose ratios unattainable through conventional starch hydrolysis.
Industry Challenges
- Enzyme Engineering Talent Scarcity:Protein design and immobilization chemistry expertise remains concentrated among academic centers and specialized biotechnology firms, constraining in-house process development.
- Dual Certification Burden:Manufacturers supplying both pharmaceutical tableting and food applications must maintain separate ISO and food-grade quality systems, extending compliance timelines.
- Legacy Dextrose Equipment Retrofit:Converting batch crystallization lines to continuous processing requires substantial capital redeployment with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutritive Sweeteners Market |
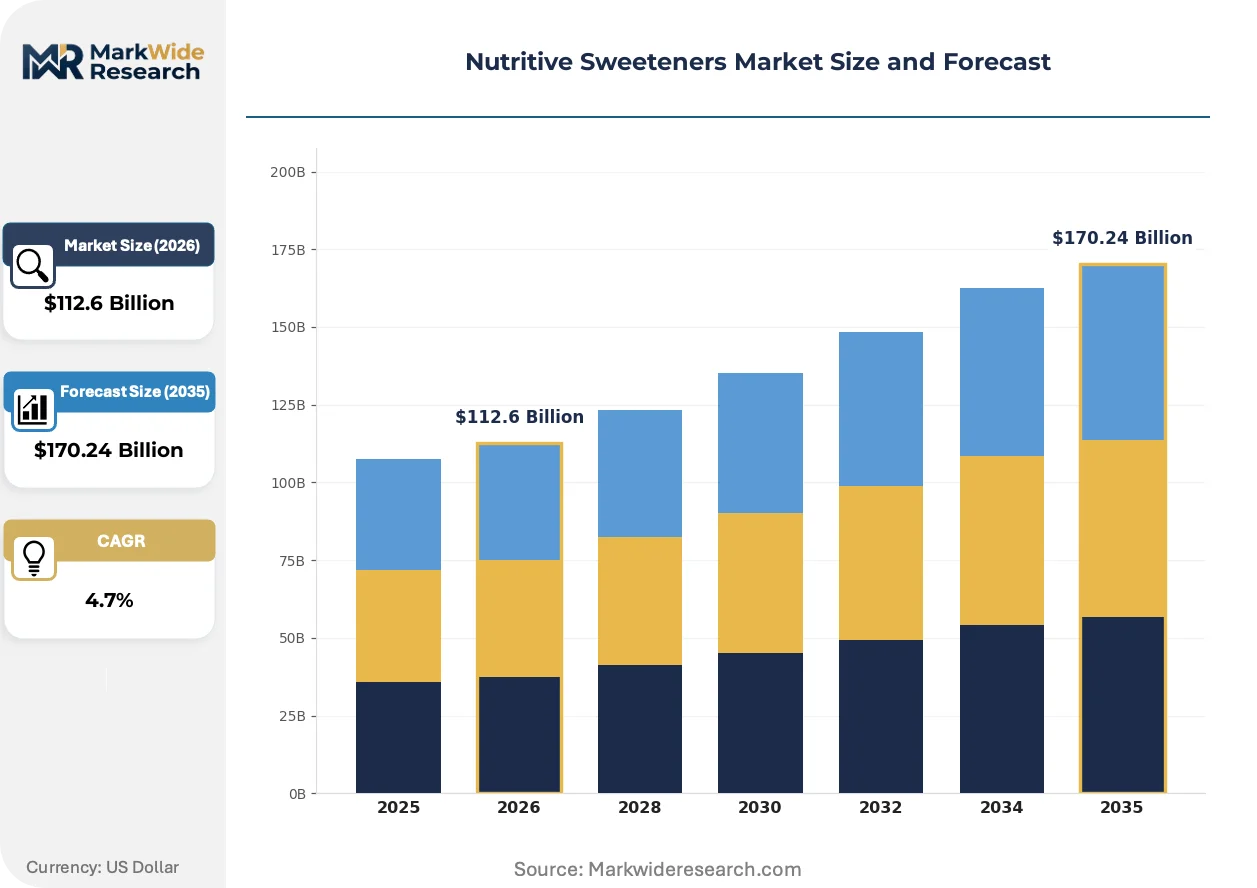
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $170.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sucrose, Glucose Syrup, Fructose, Maltodextrin Form: Liquid, Powder, Crystals, Granules Application: Food & Beverages, Pharmaceuticals, Bakery, Dairy End User: Retail Consumers, Food Manufacturers, Healthcare Facilities, Restaurants |
| Companies Covered | Cargill, Archer Daniels Midland Company, Ingredion, Tate & Lyle, Roquette Frères, Südzucker, Ajinomoto, Associated British Foods, International Flavors & Fragrances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutritive Sweeteners Market Evolving Landscape
Digital twin modeling of enzymatic conversion kinetics is compressing pilot-scale validation timelines while regulatory disclosure requirements fragment formulation strategies across major producing regions.
Continuous chromatographic separation is virtualizing the traditional crystallization step in high-purity glucose production. Pharmaceutical-grade dextrose manufacturers in Germany and Switzerland are adopting simulated moving bed systems to reduce solvent use and yield loss. This technology is virtualizing the capital-intensive fractionation infrastructure that previously anchored regional production economics.
EFSA's evolving position on nutrient profiling is tightening the criteria for glycemic response claims in glucose syrup marketing. European beverage formulators must now substantiate physiological effects through clinical trials to retain competitive positioning. Sports nutrition and medical food segments in Germany and the Netherlands are responding by commissioning dedicated glycemic index studies for reformulated product lines.
Contract manufacturing is displacing captive sweetener production among mid-sized food processors. North American bakery and dairy companies are outsourcing glucose syrup and maltodextrin blending to specialized toll processors with flexible dextrose equivalence adjustment capabilities. This pattern is most visible in the United States, where processor consolidation has reduced in-house R&D staffing levels.
Nutritive Sweeteners Market Segmentation
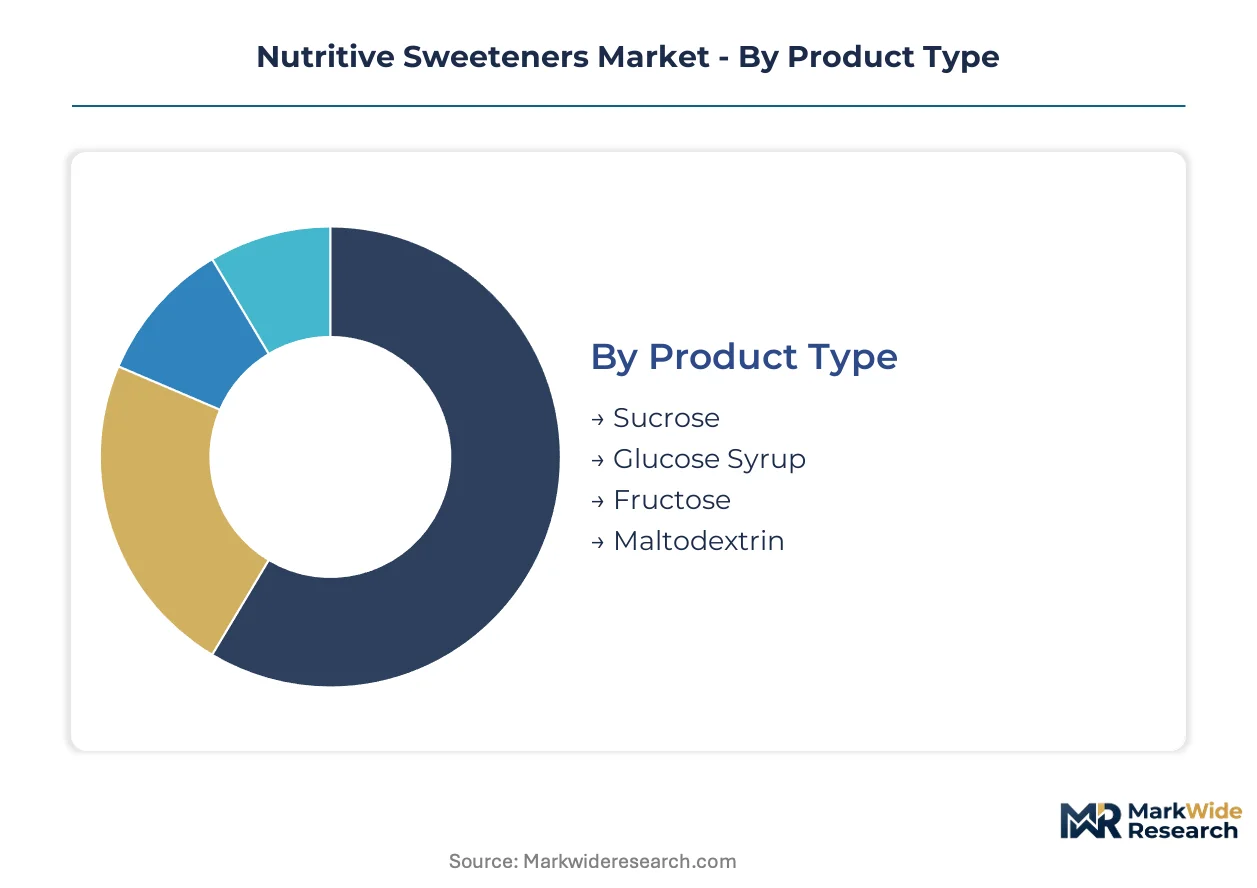
Segmentation in nutritive sweeteners reveals how functional specifications and procurement patterns fragment across end-use channels. Each dimension—product chemistry, physical form, application matrix, and buyer type—carries distinct margin structures and regulatory exposure that reshape competitive priorities.
Product Type:
Cost tier differentiation separates commodity sucrose from specialty hydrolyzed starches with premium dextrose equivalence specifications.
- Sucrose:Extracted from sugarcane or sugar beet through crystallization refining, this segment commands universal compatibility across bakery emulsions and dairy protein stabilization. Demand concentrates in Germany and France where beet sugar processing infrastructure anchors European supply security, though climatic yield volatility creates recurring procurement stress.
- Glucose Syrup:Produced via enzymatic starch hydrolysis with dextrose equivalence values spanning forty to ninety-five, this liquid sweetener enables controlled browning and viscosity in beverage manufacturing. United States corn wet-milling operations dominate capacity, with FDA added-sugar disclosure rules forcing beverage formulators toward reduced-sucrose blends that elevate glucose syrup procurement.
- Fructose:High-purity monosaccharide isolated through isomerization and chromatographic enrichment, prized for intense sweetness and low glycemic response positioning.
- Maltodextrin:Partially hydrolyzed starch with dextrose equivalence below twenty, delivering bulk solids with minimal sweetness contribution for sports nutrition and infant formula fortification.
Sucrose holds installed capacity. Maltodextrin is rotating up the share rankings.
Form:
Application handling requirements and dissolution kinetics drive form selection across liquid processing versus dry-mix manufacturing environments.
- Liquid:Pumpable glucose syrups and inverted sugar solutions eliminate dissolution steps in continuous beverage production lines. Demand concentrates in United States soft drink manufacturing clusters where tanker-truck delivery and automated dosing systems minimize handling labor.
- Powder:Spray-dried maltodextrin and crystalline fructose enable precise metering in dry-blend nutritional formulations. Sports nutrition manufacturers in Germany and the Netherlands specify powder forms for protein powder fortification where moisture control and flowability determine shelf stability.
- Crystals:Granular sucrose with defined particle size distribution for controlled dissolution in pharmaceutical tableting and confectionery panning.
- Granules:Agglomerated sweetener forms engineered for reduced dusting and improved dispersibility in institutional foodservice applications.
Liquid holds installed capacity. Powder is climbing the fastest.
Application:
Customer type maturity separates mass-market food processing from specialized clinical and pharmaceutical channels with divergent certification burdens.
- Food & Beverages:Largest consumption channel spanning carbonated drinks, confectionery, and savory sauces where bulk sweetness and humectancy prove essential. Reformulation pressure from FDA and EFSA added-sugar regulations is forcing procurement shifts toward lower-glycemic alternatives in United States and European manufacturing.
- Pharmaceuticals:Excipient-grade dextrose and compressible sugars for tablet binders and parenteral nutrition solutions. Swiss and German manufacturers maintain dedicated production lines with pharmaceutical-grade certification under EMA and Swissmedic oversight.
- Bakery:Fermentable sugars for yeast activation and Maillard browning control in crust formation.
- Dairy:Lactose-compatible sweetening in flavored milk and ice cream with freeze-thaw stability requirements.
Food & Beverages holds installed capacity. Pharmaceuticals is gaining share fastest.
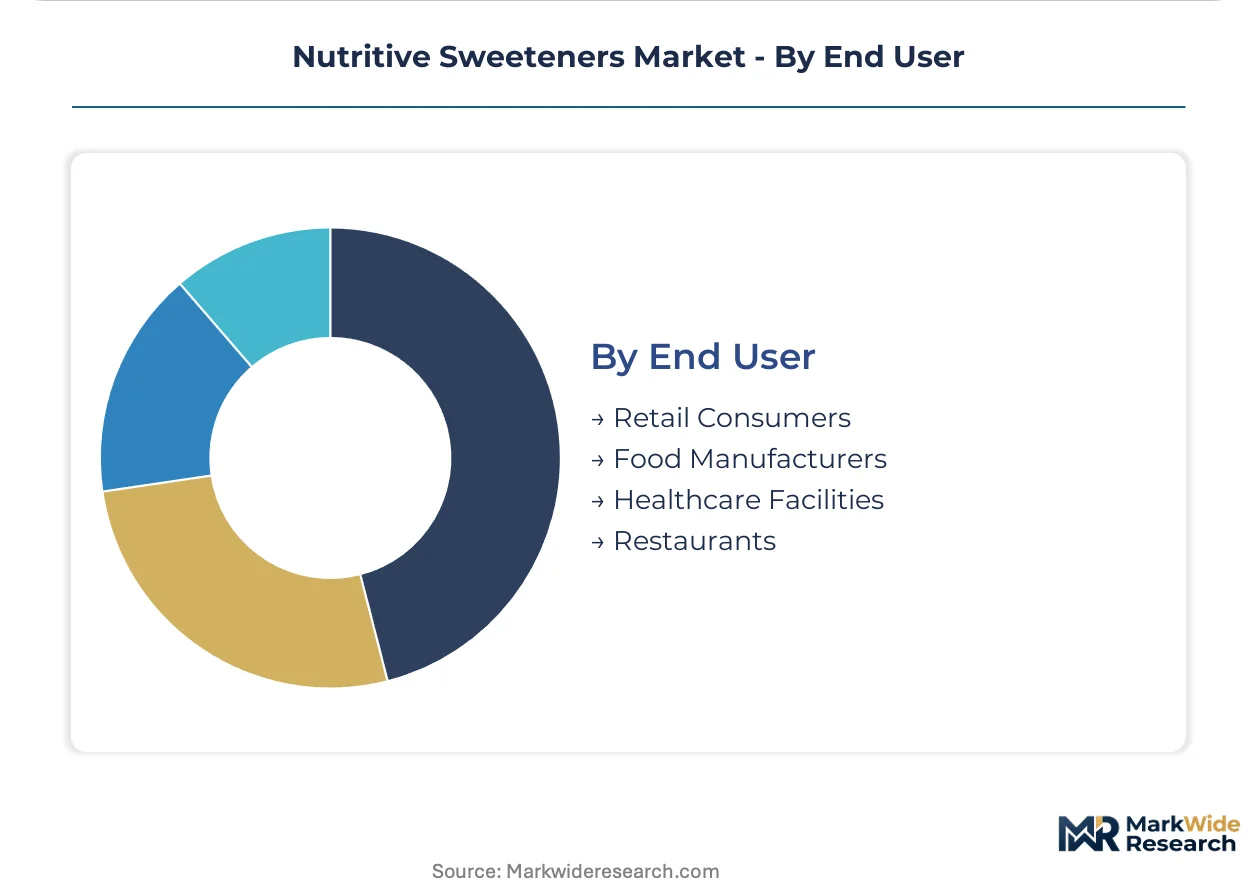
End User:
Volume concentration distinguishes industrial-scale procurement from fragmented retail and foodservice channels with opposing price sensitivity profiles.
- Food Manufacturers:Integrated beverage and confectionery producers purchasing glucose syrup and maltodextrin in bulk tanker quantities. Cargill and Südzucker negotiate long-term supply agreements with United States and European multinational processors seeking dextrose equivalence customization.
- Retail Consumers:Packaged sucrose and specialty sweeteners sold through grocery and e-commerce channels. Indian FSSAI labeling alignment is tightening added-sugar disclosure requirements, reshaping how domestic brands communicate sweetness content to health-conscious households.
- Healthcare Facilities:Clinical nutrition services specifying low-glycemic carbohydrate sources for diabetic and post-surgical patient feeding.
- Restaurants:Foodservice distributors supplying granulated and liquid sweeteners for recipe execution with cost-per-serving optimization.
Food Manufacturers holds installed capacity. Healthcare Facilities is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in nutritive sweeteners tilt toward surplus in major beet and cane sugar origins while starch-derivative importing economies absorb glucose syrup and maltodextrin flows. Corn wet-milling capacity in North America and beet processing infrastructure in Europe anchor outbound trade volumes. Asian markets exhibit structural deficits in high-purity glucose-fructose, driving procurement from integrated multinational suppliers.
United States
Corn wet-milling clusters in Iowa and Illinois supply glucose syrup to beverage manufacturers reformulating under FDA added-sugar disclosure mandates. The FDA's Nutrition Facts panel rules pressure CPG brands toward reduced-sucrose blends. Chicago-area toll processors now handle maltodextrin blending for mid-sized bakery and dairy companies outsourcing R&D functions.
Germany
Beet sugar processing in Lower Saxony and Bavaria anchors European sucrose supply security, though climatic yield volatility creates recurring procurement stress. EFSA's glycemic response framework under EU Health Claims Regulation shapes how glucose syrup marketers substantiate physiological effects. Swiss and German pharmaceutical-grade dextrose manufacturers in Baden-Württemberg adopt simulated moving bed chromatography to reduce solvent use.
China
Starch hydrolysis capacity expansion in Shandong and Jilin provinces targets domestic beverage and confectionery demand. SAMR nutritional labeling alignment with Codex standards tightens added-sugar disclosure requirements for processed dairy and beverages. Yangtze River Delta food manufacturers accelerate procurement of enzymatically converted glucose syrups for clean-label reformulations.
India
FSSAI labeling alignment is tightening added-sugar disclosure requirements, reshaping procurement specifications for domestic dairy and beverage processors. Maharashtra and Gujarat host concentrated confectionery and processed food manufacturing bases sourcing maltodextrin for bulk solids applications. Mumbai-based formulators seek low-dextrose-equivalence carbohydrates for infant formula fortification.
Brazil
Sugarcane-derived sucrose surplus from São Paulo state ethanol-sugar flex mills feeds export-oriented refined sugar flows. ANVISA nutritional labeling regulations cascade from Mercosur harmonization efforts, pressuring reformulation in domestic processed foods. Santos port infrastructure handles bulk liquid sweetener shipments to African and Middle Eastern markets.
Nutritive Sweeteners Market Competitive Landscape
On the supply side, the industry is consolidating around integrated agribusiness conglomerates with captive feedstock access and specialized fermentation technology houses. Tiered competitive positioning separates multinational wet-millers with backward integration into corn and beet supply chains from regional toll processors offering flexible dextrose equivalence customization. Dominant competitive moves include strategic partnerships between enzyme technology licensors and mid-scale processors, plus capacity expansion in pharmaceutical-grade dextrose certification.
Within the integrated agribusiness tier, Cargill and Archer Daniels Midland occupy positions defined by North American corn wet-milling scale and supply chain control. Südzucker exemplifies the beet sugar specialist archetype through European agricultural partnerships. Ajinomoto sits within the high-purity glucose-fructose segment leveraging amino acid process synergies at Japanese manufacturing complexes.
| Leading Market Players |
|---|
| Cargill |
| Archer Daniels Midland Company |
| Ingredion |
| Tate & Lyle |
| Roquette Frères |
| Südzucker |
| Ajinomoto |
| Associated British Foods |
| International Flavors & Fragrances |
| Others |
Value Network & Pricing Analysis
United States corn wet-milling concentration in Iowa and Illinois anchors feedstock cost advantages that concentrate margin pools with integrated processors possessing captive starch supply. Pricing power fragments downstream as beverage manufacturers reformulate under FDA added-sugar disclosure mandates, forcing procurement shifts that redistribute value across maltodextrin and glucose syrup tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with dextrose equivalence customization premiums. Price differentiation separates pharmaceutical-grade dextrose under EMA certification from commodity glucose syrup, with volume scale and geographic delivery cost as secondary drivers. Cost compression in standard-grade maltodextrin is intensifying because toll processors compete on flexible blending capabilities. Healthcare facilities demonstrate lowest price sensitivity due to clinical nutrition specification rigidity, while mid-sized bakery companies exhibit highest sensitivity as they outsource R&D functions.
Supply Chain Analysis
Corn feedstock supply concentrates in the United States, Brazil, and China, with beet sugar sourcing anchored in France and Germany. Wet-milling operations draw from corn futures markets, enzyme catalysts, and energy inputs, while chromatographic separation equipment feeds from German and Swiss precision manufacturing. Single-source vulnerability in European beet sugar crystallization infrastructure creates regional supply risk during adverse growing seasons. Distribution runs through bulk tanker networks for liquid glucose syrups and rail-served silos for crystalline sucrose, with toll processors increasingly interposing between integrated suppliers and mid-sized food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nutritive sweeteners market functions as a defensive-moat arena where regulatory entrenchment in FDA and EFSA labeling frameworks creates substantial switching costs for reformulating manufacturers.
For Market Incumbents: Harden backward integration into corn wet-milling and beet sugar processing to secure feedstock cost advantages against precision fermentation entrants. Expand pharmaceutical-grade dextrose certification capacity in Germany and Switzerland to capture EMA-tier margin premiums. Defensive consolidation through toll processor acquisition neutralizes flexible blending competitors threatening standard-grade pricing. For New Entrants and Emerging Players: Pursue white-space positioning in infant formula maltodextrin fortification, where controlled dextrose equivalence specifications command premium positioning with minimal incumbent specialization. Target India's FSSAI-aligned reformulation services market, where domestic dairy and beverage processors seek alternative sweetener blend expertise. Go-to-market through technical service partnerships with Mumbai-based formulators accelerates credibility building. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed toll processing platforms in North America, where contract manufacturing growth has outpaced organic R&D investment at mid-sized food companies. Long-term viability centers on enzyme engineering capability scarcity and regulatory certification moats. Watch precision fermentation cost curves as the inflection signal for starch-derivative substitution threat intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Wet-Milling | Cargill and ADM secure captive feedstock supply against commodity volatility in Iowa and Illinois processing clusters. |
| Pharmaceutical-Grade Dextrose Certification | Swiss and German manufacturers adopt simulated moving bed chromatography to meet EMA and Swissmedic excipient standards. |
| Precision Fermentation Capacity Buildout | Cell-free enzymatic systems with continuous chromatography enable novel glucose-fructose ratios unattainable through conventional starch hydrolysis. |
| Toll Processing Platform Acquisition | Consolidation of flexible dextrose equivalence blending capabilities captures outsourced R&D demand from mid-sized North American bakery and dairy companies. |
| EFSA Glycemic Response Clinical Investment | Sports nutrition manufacturers in Germany and Netherlands commission dedicated studies to substantiate physiological effects under EU Health Claims Regulation. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with corn wet-milling plant managers, beverage procurement leads, pharmaceutical excipient specialists, and toll processing operators; and secondary validation through FDA Nutrition Facts panel guidance documents, EFSA health claims evaluations, SEC 10-K filings from integrated agribusiness conglomerates, and customs trade data on starch derivative flows. Bottom-up capacity modeling and top-down consumption estimates were triangulated against regional production cluster analysis.
Forecast inputs span product chemistry tiers, physical form handling requirements, end-use application matrices, and buyer procurement scale across the projection horizon. CAGRs were derived from segment-level demand elasticity modeling and feedstock cost trajectory assumptions. Enzymatic conversion efficiency curves and regulatory disclosure timeline phasing served as industry-specific forecast inputs throughout the modeling period.
Macroeconomic conditions sit as an overlay; deviation in corn futures volatility, European beet sugar yields, or WHO free sugars guideline adoption would shift the trajectory. Cross-checking against EFSA nutrient profiling evolution and SAMR labeling alignment progress is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sweeteners
Liquid Sugar Market
Sweeteners
Global Brown Sugar Market
Sweeteners
Asia-Pacific Low-Calorie Sweeteners Market
Sweeteners
Global Alternative Sweeteners Market
Sweeteners
Sugar Alcohol Market
Sweeteners
Middle East and Africa Food Sweetener Market
Sweeteners
Sweet Modulator Market
Sweeteners
India Food Sweetener Market
Sweeteners
Australia Allulose Market
Sweeteners
Natural Malt Sweeteners Market
Sweeteners
Rare Sugar Market
Sweeteners
Muscovado Sugar Market
Sweeteners
Europe Natural Sweetener Market
Sweeteners
Allulose Powder Market
Sweeteners
High-Intensity Sweeteners Market
Sweeteners
Dextrates Market