
 Global Popping Candy Market | 2026-2036
Global Popping Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Popping Candy Market Foresight
The capital-intensity divergence between artisanal ingredient suppliers and multinational confectionery conglomerates is unwinding as scale advantages in carbonation technology reshape competitive dynamics. Nestlé SA leverages its integrated flavor development infrastructure to control proprietary popping formulations across multiple regional markets. Mars, Inc. sustains volume leadership through dedicated manufacturing lines optimized for high-throughput candy gasification. Ferrero Group differentiates via premium chocolate-coated popping candy extensions that command shelf space in European specialty retail channels.
Popping candy comprises sugar-based confectionery infused with pressurized carbon dioxide through a patented hot-melt extrusion process, creating an effervescent oral sensation upon moisture contact; the primary commercial purpose centers on delivering sensory novelty in confectionery, bakery, and frozen dessert applications. Fruit-flavored variants dominate mass-market volume given their compatibility with diverse application formats, while sugar-free formulations capture the fastest growth trajectory as FDA labeling requirements and EFSA health claims reshape consumer purchase criteria. Chocolate-coated popping candy anchors the highest margin pool due to ingredient complexity and premium positioning across gift and seasonal segments.
FDA food additive regulations and GRAS designation requirements govern carbon dioxide incorporation levels and labeling disclosures for U.S.-distributed products, while REACH compliance and EFSA food contact material standards constrain European formulation chemistries and packaging substrates. China's SAMR national food safety standards and GB labeling mandates create additional compliance layers for imported popping candy entering domestic retail channels. Stakeholders must monitor evolving front-of-package warning regulations across Brazil's ANVISA and Mexico's COFEPRIS frameworks, as Latin American sugar taxation policies increasingly influence product architecture decisions without explicit reference to forecast timelines.
Market Dynamics
The EU's F-Gas Regulation is forcing reformulation across pressurized confectionery manufacturing as carbon dioxide sourcing constraints intersect with REACH chemical compliance mandates, compressing supplier margins while accelerating clean-label ingredient transitions.
Growth Catalysts
- Confectionery mix applications:Bakery and frozen dessert manufacturers integrate popping candy into texture-differentiated product lines, expanding addressable consumption occasions beyond standalone candy formats.
- SAMR national food safety standards:China's streamlined import certification for carbonated confectionery reduces market entry friction for compliant foreign producers targeting domestic retail channels.
- Hot-melt extrusion process refinements:Equipment vendors deliver modular carbonation systems that lower minimum efficient scale thresholds for regional specialty producers.
Market Restraints
- Carbon dioxide feedstock volatility:Industrial gas supply concentration in Germany and the United States exposes manufacturers to fertilizer-industry production swings and energy-price pass-through effects.
- EFSA food contact material standards:Packaging substrate migration testing requirements extend product development timelines and disqualify incumbent film suppliers lacking European certification.
- Sugar taxation policy diffusion:Brazil's ANVISA front-of-package warning regulations and Mexico's COFEPRIS sugar disclosure mandates compplicate unified regional product architecture.
Strategic Opportunities
- Sugar-free formulation white space:FDA labeling requirements and EFSA health claims create first-mover advantage for polyol-based carbonated confectionery in pharmacy and wellness retail channels.
- Gift and seasonal segment premiumization:Chocolate-coated popping candy extensions command shelf space in European specialty retail, with margin pools exceeding mass-market fruit-flavored variants.
- Dual carbon goals alignment:China's MEE emissions intensity targets incentivize domestic producers to adopt renewable-sourced carbon dioxide, qualifying products for green procurement preferences.
Industry Challenges
- Flavor-chemist talent scarcity:Proprietary popping formulation development requires rare expertise in pressure-stable volatile compound engineering, concentrating R&D capability at integrated multinationals.
- GRAS designation timeline compression:FDA food additive petition review backlogs delay novel carbonation level introductions, freezing product pipeline decisions for U.S.-focused innovators.
- Legacy equipment retrofit complexity:Hot-melt extrusion line upgrades for higher-pressure carbonation conflict with existing plant layouts and utility infrastructure at mid-scale facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Popping Candy Market |
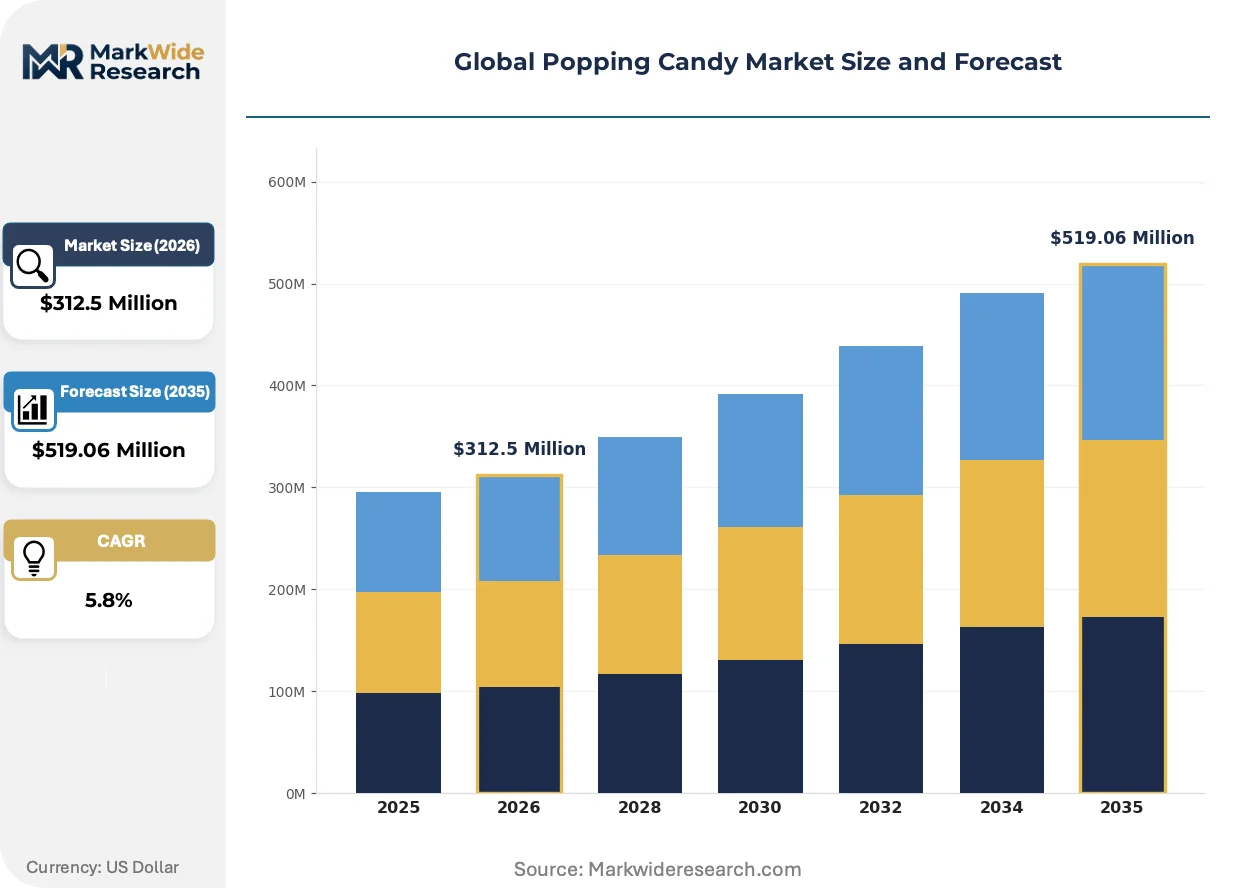
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavored, Chocolate Coated, Sour, Sugar-Free, Bubblegum, Others Packaging Type: Stick Packs, Sachets, Tins, Boxes, Pouches, Jars Application: Confectionery Mixes, Ice Cream Toppings, Beverage Mixes, Bakery Decoration, Yogurt Add-ins, Snacks Sales Channel: Supermarkets, Convenience Stores, Specialty Shops, Online Retailers, Vending Machines, Wholesalers |
| Companies Covered | Nestlé SA, DeMet's Candy Co., Mars, Inc., Haribo, Ferrara Candy Co., Mondelēz International, Hershey Company, Perfetti Van Melle, Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Popping Candy Market Shifts & Advancements
Carbonation technology is bifurcating the competitive landscape as proprietary process control separates integrated flavor developers from ingredient-dependent assemblers. Regulatory chemical frameworks and sensory novelty demands are simultaneously reshaping formulation priorities across manufacturing tiers.
Pressurized carbon dioxide infusion systems are bifurcating equipment procurement patterns. Artisanal producers adopt tabletop batch units for limited-run specialty lines while multinationals deploy continuous-flow carbonation arrays optimized for throughput. This technology split is compressing mid-scale manufacturer margins as they lack capital for industrial systems yet face unit-cost disadvantages against artisanal positioning.
REACH compliance constraints are reshaping European formulation chemistries. ECHA substance restriction updates disqualify legacy stabilizer compounds, forcing reformulation around bio-based alternatives with shorter stability windows. Specialty retail chocolate-coated segments absorb these input cost increases through premium positioning, while mass-market fruit-flavored products face private-label substitution pressure.
Clean-label purchase criteria are rotating demand toward ingredient transparency. Pharmacy and wellness channels displace conventional confectionery retail for sugar-free variants as FDA disclosure requirements elevate consumer scrutiny of artificial additive content. Germany and the United States exhibit the sharpest channel pivot, with drugstore chains expanding dedicated functional confectionery planograms.
Global Popping Candy Market Segmentation
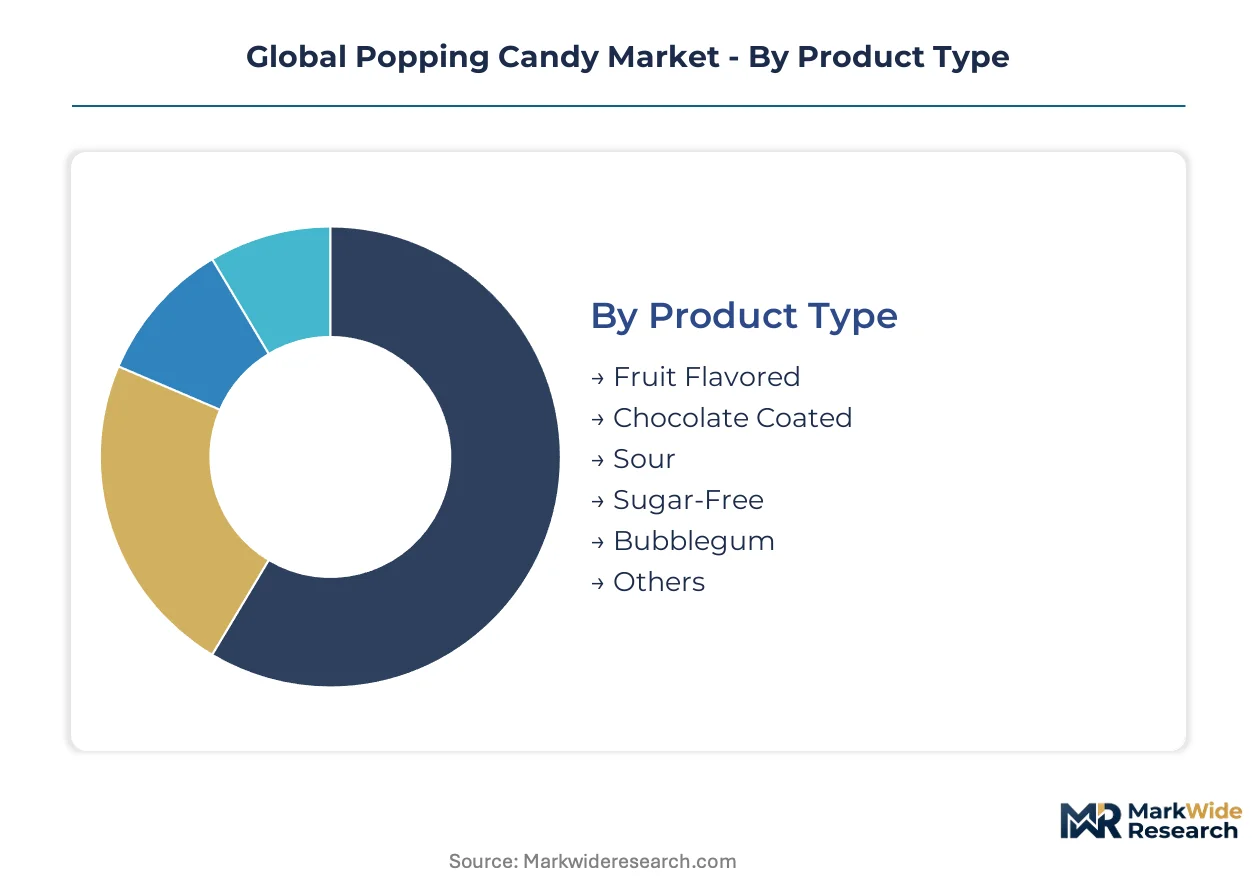
Segmentation in popping candy reveals how sensory novelty, regulatory pressure, and channel access fragment demand across distinct value pools. Product architecture decisions cascade through packaging formats, application integration, and retail placement, each tier carrying different margin profiles and compliance burdens.
Product Type:
Fruit-flavored and sugar-free variants face divergent substitution pressures—natural flavor positioning competes against clean-label confectionery alternatives, while polyol-based formulations confront stevia-sweetened functional candies in pharmacy channels.
- Fruit Flavored:Citric acid and natural flavor emulsions dominate mass-market formulations. Demand concentrates in Germany and the United States where convenience store impulse purchasing sustains volume; EFSA health claim scrutiny elevates artificial additive disclosure requirements.
- Sugar-Free:Isomalt and xylitol carbonation matrices deliver pressure-stable effervescence without sucrose. Pharmacy and wellness retail channels in the United States absorb the steepest volume climb as FDA labeling mandates reshape consumer scrutiny.
- Chocolate Coated:Compound coating layers protect carbonated cores from moisture ingress; European specialty gift segments absorb premium positioning.
- Sour:Malic acid blends intensify oral sensation; Latin American markets show concentrated adoption.
- Bubblegum:Synthetic ester flavor systems target children's confectionery segments; regulatory pressure from Brazil's ANVISA front-of-package warnings constrains formulation freedom.
- Others:Novelty flavor extensions including savory and spice-infused variants; limited-run artisanal production in clustered urban markets.
Fruit-flavored products retain volume leadership; sugar-free formulations hold the steepest expansion curve.
Packaging Type:
Packaging cost tiers separate mass-market accessibility from premium unboxing experiences, with substrate migration testing under REACH compliance redrawing supplier qualification boundaries.
- Stick Packs:Single-serve laminated film strips optimize vending machine compatibility and impulse checkout placement. China's SAMR streamlined import certification accelerates foreign brand entry through convenience retail channels.
- Sachets:Heat-sealed foil-paper laminates protect carbonation integrity across extended distribution cycles. Bakery and frozen dessert manufacturers in Germany specify sachet formats for production-line integration.
- Tins:Metal canisters with resealable lids command gift segment positioning; European specialty retail absorbs premium pricing.
- Boxes:Rigid paperboard with blister inserts targets seasonal and promotional segments.
- Pouches:Flexible stand-up bags with zip closures serve family-size and club channel formats.
- Jars:PET or glass containers enable bulk dispensing and refill retail models.
Stick packs dominate unit volume through vending and convenience penetration; sachets gain share fastest via foodservice and industrial ingredient channels.
Application:
Application maturity curves separate established confectionery integration from emerging texture-innovation frontiers in adjacent food categories.
- Confectionery Mixes:Bulk carbonated inclusions blended with chocolate, nuts, or dried fruit create texture-differentiated product lines. Mars and Ferrero manufacturing specifications drive ingredient standardization across European and North American production facilities.
- Ice Cream Toppings:Cryogenic-stable formulations resist moisture activation during frozen distribution. United States specialty ice cream chains specify custom flavor profiles for limited-edition menu items.
- Beverage Mixes:Instant powder systems release carbonation upon liquid contact; functional beverage startups in China experiment with vitamin-fortified variants.
- Bakery Decoration:Heat-resistant coatings protect popping candy through oven cycles; artisanal cupcake producers in clustered urban markets drive small-batch demand.
- Yogurt Add-ins:Separate-compartment packaging preserves effervescence until consumption; European dairy processors trial clean-label inclusions.
- Snacks:Trail mix and granola integrations target adult snacking occasions; sugar taxation policies in Mexico constrain mass-market rollout.
Confectionery mixes anchor revenue concentration; ice cream toppings expand most quickly through menu innovation partnerships.
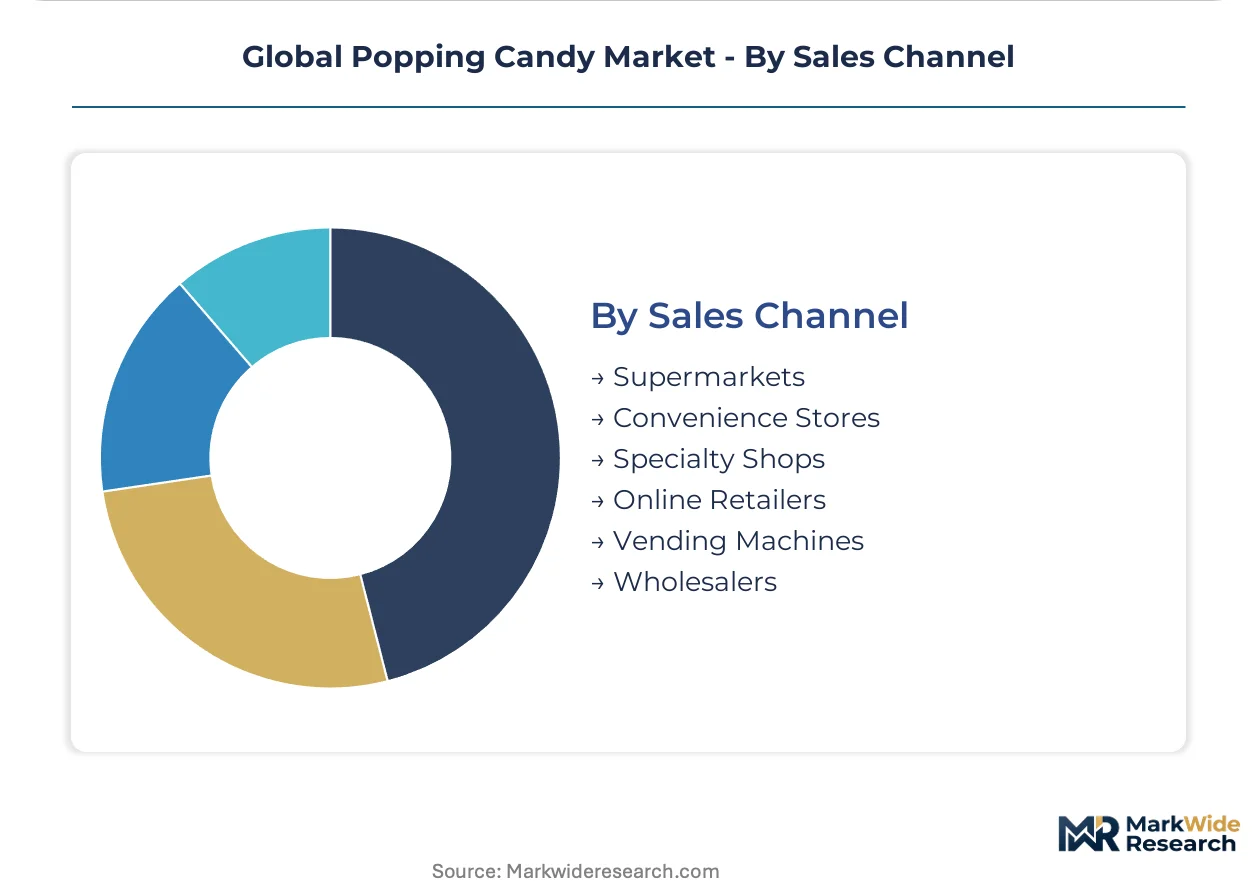
Sales Channel:
Channel control points separate high-frequency impulse purchasing from relationship-driven specialty access and algorithm-curated discovery.
- Supermarkets:Planogram placement in seasonal and checkout zones drives volume concentration. Walmart and Carrefour category management specifications determine packaging size and promotional calendar alignment.
- Online Retailers:Direct-to-consumer subscription models and marketplace algorithm visibility reshape brand discovery. China's Tmall and JD.com import certification pathways reduce foreign producer friction.
- Convenience Stores:Single-serve formats dominate impulse purchasing; 7-Eleven and Lawson chain specifications standardize stick pack dimensions.
- Specialty Shops:Curated assortments and gift-wrapping services absorb premium pricing; European chocolate boutiques drive chocolate-coated variant placement.
- Vending Machines:Automated retail placement targets transit and entertainment venues; cashless payment integration expands addressable locations.
- Wholesalers:Bulk distribution to foodservice and industrial users; minimum order quantities filter small-scale producers.
Supermarkets retain volume leadership; online retailers climb the fastest through algorithm-driven discovery and import streamlining.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's specialty retail channels while volume manufacturing margins compress in China's industrial clusters. The United States commands premium shelf-space economics through pharmacy and wellness channel migration. Japan and Brazil occupy intermediate positions shaped by distinct regulatory and taxation frameworks.
United States
Pharmacy channel expansion and FDA labeling mandates drive sugar-free formulation demand. GRAS designation requirements for novel carbonation levels extend product development timelines. Chicago and New Jersey manufacturing corridors host Mars and Hershey production facilities optimized for high-throughput candy gasification.
Germany
EFSA food contact material standards and REACH compliance reshape packaging substrate selection. Specialty chocolate boutiques in Cologne and Munich absorb premium pricing for gift-segment chocolate-coated variants. Industrial gas supply concentration exposes manufacturers to fertilizer-industry production swings.
China
SAMR streamlined import certification reduces market entry friction for compliant foreign producers. MEE emissions intensity targets incentivize renewable-sourced carbon dioxide adoption. Yangtze River Delta and Pearl River Delta clusters concentrate domestic popping candy manufacturing for regional distribution.
Japan
Convenience store impulse purchasing sustains stick pack format dominance through 7-Eleven and Lawson chain specifications. METI industrial standards govern food additive incorporation levels. Tokyo and Osaka metropolitan areas drive limited-edition flavor collaborations with specialty ice cream chains.
Brazil
ANVISA front-of-package warning regulations constrain bubblegum segment formulation freedom. Sugar taxation policies compplicate unified Latin American product architecture. São Paulo state anchors regional demand while import channels serve specialty segments in Rio de Janeiro.
Global Popping Candy Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the popping candy value chain. The market structure consolidates around integrated multinationals with captive flavor development infrastructure, while mid-scale manufacturers face margin compression from both artisanal positioning and industrial scale. Three archetypes dominate: integrated confectionery conglomerates with proprietary carbonation systems, premium chocolate specialists extending into coated variants, and regional sugar-free formulators targeting pharmacy channels. Competitive moves center on hot-melt extrusion equipment upgrades and strategic partnerships with industrial gas suppliers.
Among Switzerland-based integrated multinationals, Nestlé SA exemplifies technology leadership through integrated flavor development infrastructure. Mars, Inc. occupies a position representing volume manufacturing optimization through dedicated production lines. Ferrero Group anchors the premium-tier vector with chocolate-coated extensions commanding European specialty retail shelf space.
| Leading Market Players |
|---|
| Nestlé SA |
| DeMet's Candy Co. |
| Mars, Inc. |
| Haribo |
| Ferrara Candy Co. |
| Mondelēz International |
| Hershey Company |
| Perfetti Van Melle |
| Ferrero Group |
| Others |
Supply & Pricing Matrix
EFSA food contact material standards gate supplier qualification and price differentiation simultaneously, as REACH-compliant packaging substrates command certification premiums while disqualifying uncertified film vendors from European pharmaceutical and gift channels. This regulatory filtration compresses mid-tier margins and stratifies procurement pools across compliance tiers.
Pricing Analysis
Configured-to-order pricing for custom flavor-carbonation matrices spreads 40-60% above standard fruit-flavored SKUs, with three-tier pricing structure across premium, standard, and economy levels anchored by chocolate-coated gift variants, private-label fruit flavors, and bulk industrial inclusions respectively. Price differentiation rests on certification grade and customization depth. Cost compression in standard tiers is intensifying because industrial gas supply concentration exposes manufacturers to fertilizer-industry energy-price pass-through effects. Private-label buyers in German and U.S. mass channels exhibit highest price sensitivity; European specialty chocolate boutiques show lowest.
Supply Chain Analysis
Just-in-time carbon dioxide procurement dominates high-throughput manufacturers in Chicago and New Jersey corridors, while strategic stockpiling of pressure-stable polyol matrices characterizes sugar-free formulators facing raw material allocation constraints. Geographic supply concentrates in Germany, the United States, and China for industrial gas feedstock, with hot-melt extrusion equipment sourcing anchored in Germany and Japan. Raw material dependencies include food-grade carbon dioxide, isomalt and xylitol polyols, and compound chocolate coatings. Single-source vulnerability in German industrial gas production exposes continental European manufacturers to fertilizer-plant output swings. Distribution runs through wholesaler networks serving foodservice and industrial ingredient channels, with direct-to-retailer bypass expanding in pharmacy and wellness segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Popping candy markets reward service-attach strategies as formulation-development partnerships and co-manufacturing agreements expand faster than standalone product sales, with custom carbonation level design and regulatory compliance consulting emerging as recurring-revenue layers.
For Market Incumbents: Consolidate proprietary hot-melt extrusion capability through captive equipment upgrades or exclusive vendor arrangements, defending against modular carbonation system vendors lowering scale thresholds for regional entrants. Deepen backward integration into pressure-stable flavor compound engineering to offset flavor-chemist talent scarcity concentrating at integrated multinationals.
For New Entrants and Emerging Players: Clean-label sugar-free formulation services represent a service-layer gap where incumbents under-serve pharmacy and wellness channel buyers seeking rapid FDA labeling compliance. Target U.S. drugstore chain private-label programs as the most penetrable segment, leveraging co-development partnerships with regional polyol suppliers to bypass capital-intensive extrusion infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across sugar-free formulation sub-segments as modular carbonation equipment reduces minimum efficient scale thresholds. Five-to-ten year viability favors regional specialists with captive pharmacy channel relationships and renewable-sourced carbon dioxide credentials over undifferentiated mass-market fruit-flavored producers. Watch industrial gas supplier consolidation in Germany as the inflection signal for feedstock cost volatility.
| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Melt Extrusion Equipment Upgrade | Proprietary carbonation control separates integrated flavor developers from ingredient-dependent assemblers. |
| Renewable-Sourced Carbon Dioxide Adoption | China's MEE emissions targets qualify products for green procurement preferences in domestic channels. |
| Sugar-Free Formulation Pipeline Expansion | FDA labeling mandates and EFSA health claims reshape pharmacy channel purchase criteria fastest. |
| Packaging Substrate Certification Investment | REACH compliance disqualifies incumbent film suppliers lacking European food contact material approval. |
| Co-Manufacturing Partnership Development | Bakery and frozen dessert manufacturers integrate popping candy for texture-differentiated product lines. |
Research Methodology
Desk research of FDA GRAS petitions, EFSA food contact material guidance, and SAMR import certification databases preceded structured interviews with hot-melt extrusion equipment vendors, industrial gas procurement managers, and pharmacy channel category buyers. Secondary validation drew from customs trade records, confectionery industry association technical reports, and regulatory filing repositories. Bottom-up segment sizing triangulated against top-down market value estimates.
Variance decomposition across product type, packaging format, application integration, and sales channel dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic confectionery demand indicators. Industry-specific forecast inputs included industrial gas pricing indices and regulatory petition approval timelines.
Underlying assumptions cover stable REACH and FDA regulatory frameworks, with deviation risk concentrated in front-of-package warning regulation expansion across Latin American markets. Forecasts reflect these boundary conditions. Revision becomes warranted when industrial gas supply disruption crosses thresholds affecting minimum efficient scale economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Europe Food Spread Market
Packaged Foods
Morning Goods Market
Packaged Foods
Canned Food Market
Packaged Foods
US Packaged Food Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Sausage Casing Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Alginate Casings Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Ready Meal Trays Market
Packaged Foods
Cereal Flakes Market