
 Global Food Spread Market | 2026-2036
Global Food Spread Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Spread Market Analysis
The food spread category is pivoting between artisanal nut-based formulations and mass-market hydrogenated oil products. Unilever PLC leverages its global supply chain to sustain price-competitive margarine lines across emerging markets. Ferrero International S.A. anchors premium positioning through hazelnut-centric recipes that command shelf space in specialty retail channels.
Food spreads encompass semi-solid edible preparations formulated from fats, sugars, nuts, cocoa solids, or emulsified oils, typically containing 10-30% water content and stabilized through homogenization or pasteurization for bread and bakery applications. Nut spreads occupy the fastest-expanding margin pool as protein-fortified and reduced-sugar variants capture health-conscious buyers. Chocolate spreads dominate volume in European and Latin American households, while jar packaging retains preference for pantry storage despite pouch formats gaining traction in on-the-go channels.
The FDA enforces nutritional labeling and trans-fat restrictions that compel reformulation of legacy margarine recipes, while EFSA evaluates novel food claims for plant-based spread alternatives entering European commerce. India's FSSAI mandates fortification standards for edible fats, directly influencing how multinational suppliers adapt recipes for that market. Stakeholders must monitor evolving sugar-tax proposals and clean-label certification requirements as these frameworks increasingly determine which product architectures secure retail distribution.
Market Dynamics
Clean-label mandates from the FDA and EFSA are forcing simultaneous reformulation of legacy margarine recipes and accelerating plant-based spread development, compressing R&D timelines while opening premium positioning for verified low-trans-fat and reduced-sugar alternatives.
Growth Catalysts
- FSSAI Fortification Mandates:India's edible fat fortification standards compel multinational suppliers to adapt recipes for local distribution, creating compliant product lines that transfer to other emerging markets.
- Protein-Fortified Nut Spreads:Health-conscious households in Brazil and India are shifting from traditional cooking fats to branded nut-based alternatives with added protein content.
- Reduced-Sugar Labeling:EFSA evaluations of novel food claims for plant-based alternatives validate premium positioning in European specialty retail channels.
Market Restraints
- Palm Oil Price Volatility:Hydrogenated oil formulations remain cost-sensitive to Southeast Asian palm oil supply fluctuations, squeezing margin on mass-market margarine lines.
- Trans-Fat Phase-Out Deadlines:FDA restrictions on partially hydrogenated oils force capital-intensive recipe redevelopment for legacy spread portfolios.
- Artisanal Substitution:Small-batch nut butter producers in urban India and Brazil capture price-insensitive consumers seeking single-origin ingredient transparency.
Strategic Opportunities
- Pouch Format Expansion:On-the-go consumption channels in Brazil's metropolitan transit systems favor portable packaging over traditional jar formats.
- Clean-Label Certification:Third-party verified low-sugar and non-GMO claims command shelf space in European specialty grocers seeking differentiated assortment.
- Dual-Use Breakfast-Snacking Positioning:Urban Indian households increasingly deploy spreads across morning bread applications and afternoon snacking occasions.
Industry Challenges
- Homogenization Equipment Retrofit:Pasteurization line upgrades required for reduced-fat emulsions demand significant capital allocation from mid-tier manufacturers.
- Novel Food Claim Documentation:EFSA approval timelines for plant-based fat alternatives extend commercialization schedules by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Spread Market |
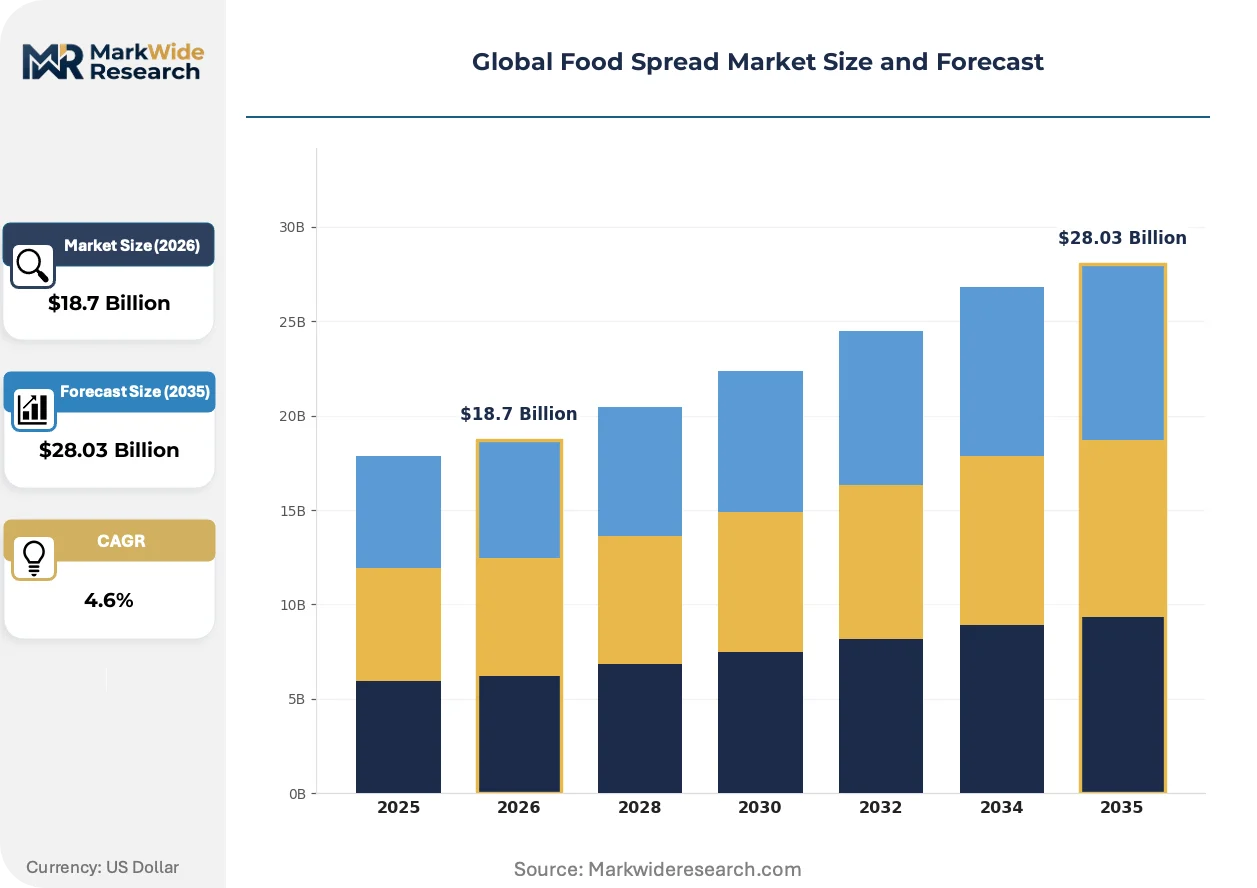
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butter, Margarine, Nut Spreads, Chocolate Spreads End User: Households, Restaurants, Cafés, Food Manufacturers Packaging Type: Jar, Tub, Sachet, Pouch Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores |
| Companies Covered | The J.M. Smucker Company, Unilever PLC, Ferrero International S.A., The Hershey Company, Hormel Foods Corporation, The Kraft Heinz Company, Conagra Brands, Inc., B&G Foods, Inc., Nestlé S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Spread Market Emerging Trajectories
Formulation science and packaging engineering are converging to reshape how spreads deliver convenience, nutrition claims, and shelf stability across divergent consumption occasions.
High-pressure processing technology is absorbing moisture-control functions previously handled by chemical preservatives in reduced-sugar nut spreads. Premium manufacturers in Germany and Switzerland are adopting HPP lines to extend ambient shelf life without synthetic additives. This compression of the preservative supply chain is absorbing value from ingredient suppliers into equipment vendors.
REACH chemical safety evaluations are tightening scrutiny on emulsifier additives used in chocolate spread formulations. The European Chemicals Agency's expanded authorization requirements are forcing reformulation of legacy recipes containing specific lecithin derivatives. Manufacturers serving the German and French retail markets are accelerating shift toward enzymatic emulsification systems.
Urban Indian consumers are fragmenting their purchase occasions between pantry-stock jars and single-serve sachets for workplace consumption. Modern trade channels in Mumbai and Bangalore are expanding chilled grab-and-go sections that displace traditional bulk purchasing. This behavioral pivot is most visible among dual-income households seeking portion-controlled snacking solutions.
Global Food Spread Market Segmentation
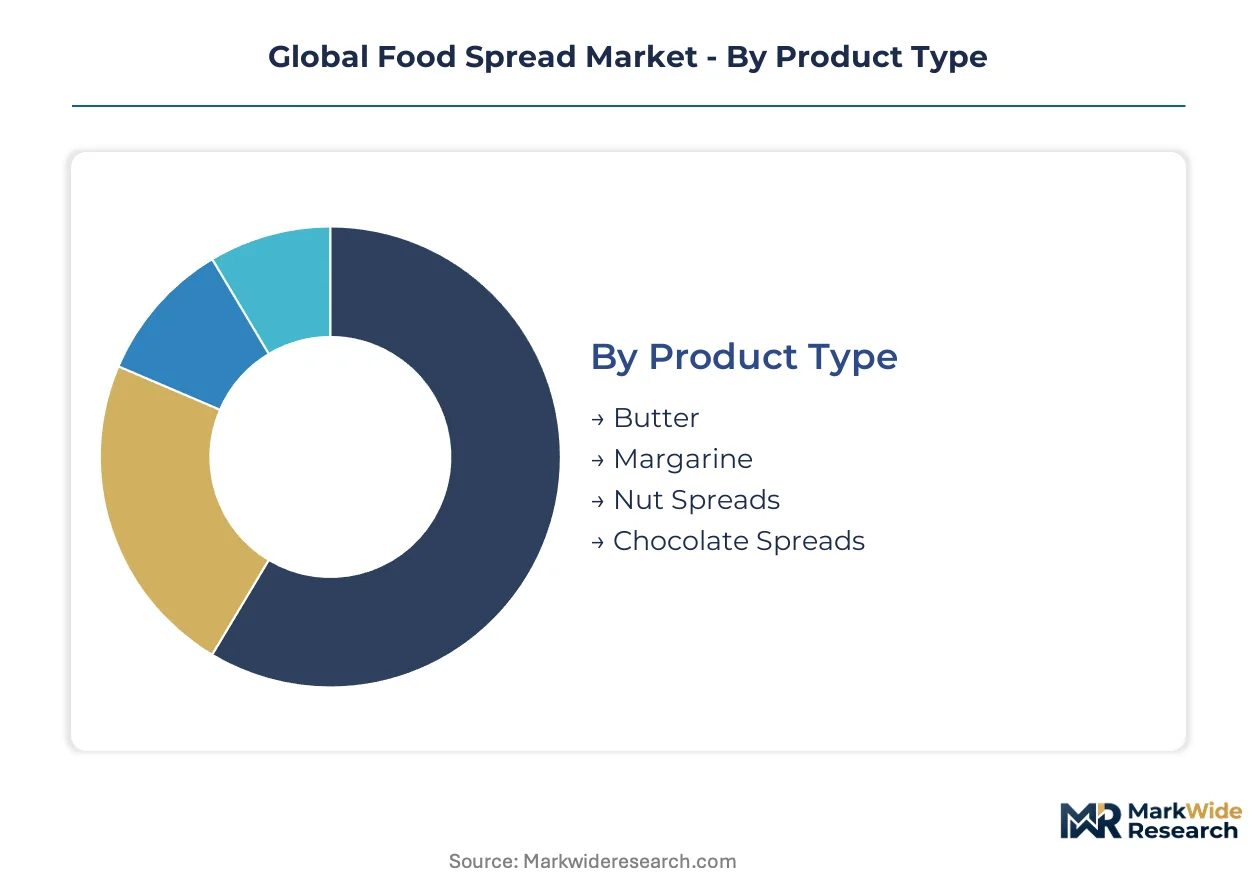
Food spread manufacturers architect product portfolios across four intersecting dimensions that determine pricing power, shelf placement, and reformulation priorities. Each segmentation axis carries distinct regulatory exposure and margin structures that shape investment allocation.
Product Type:
Upgrade cycles in this category track health-mandate compliance timelines, with legacy hydrogenated formulations facing forced replacement by clean-label alternatives.
- Butter:Traditional dairy-fat spreads with 80% milkfat content dominate premium breakfast applications in European and North American households. German and French retailers allocate expanded shelf space to grass-fed and cultured variants as EFSA clean-label claims validate premium positioning.
- Margarine:Emulsified vegetable oil formulations containing 10-30% water content serve as the primary replacement target for FDA trans-fat phase-out mandates. India's FSSAI fortification standards compel recipe adaptation for edible fat distribution, creating compliant lines that transfer to other emerging markets.
- Nut Spreads:Protein-fortified variants with reduced-sugar profiles capture health-conscious buyers in Brazil's metropolitan transit channels and India's modern trade.
- Chocolate Spreads:Cocoa-solid preparations stabilized through homogenization retain volume leadership in European and Latin American pantry stock.
Chocolate spreads sit at the top of the volume ranking, with nut spreads climbing the fastest.
End User:
Cost tier stratification separates commodity bulk purchasers from premium single-origin seekers, with procurement scale determining formulation flexibility.
- Households:Urban Indian dual-income families fragment purchases between pantry jars and workplace sachets, while Brazilian metropolitan consumers shift from traditional cooking fats to branded alternatives.
- Restaurants:Foodservice operators in Germany and Switzerland specify HPP-treated nut spreads to meet clean-label procurement mandates without synthetic preservatives.
- Cafés:Specialty coffee chains in Mumbai and Bangalore drive chilled grab-and-go format adoption for portion-controlled snacking applications.
- Food Manufacturers:Industrial buyers of chocolate spread inputs face REACH-mandated emulsifier reformulation as ECHA tightens lecithin derivative authorization.
Households anchor absolute volume, with cafés expanding most quickly.
Packaging Type:
Application context dictates format selection, with mobility requirements displacing traditional pantry storage in urban consumption clusters.
- Jar:Glass and PET containers retain preference for pantry storage in European and North American households, though shelf-space competition intensifies.
- Tub:Wider-mouth polypropylene containers serve foodservice portioning and family-size retail in German and French hypermarkets.
- Sachet:Single-serve foil laminates capture workplace and transit consumption in São Paulo and Mumbai metropolitan systems.
- Pouch:Flexible stand-up formats with resealable spouts gain traction in Brazilian on-the-go channels and Indian modern trade chilled sections.
Jar formats command the installed base, with pouches gaining share fastest.
Distribution Channel:
Geographic concentration of modern trade infrastructure determines which packaging and certification combinations achieve viable throughput.
- Supermarkets:Multi-brand hypermarkets in Germany and France enforce clean-label certification requirements that filter supplier eligibility.
- Online Retail:E-commerce platforms in India and Brazil enable direct-to-consumer subscription models for artisanal nut butter producers seeking single-origin transparency.
- Specialty Stores:European organic and health-food grocers command third-party verified low-sugar and non-GMO claims for shelf access.
- Convenience Stores:Urban Indian kirana modernization and Brazilian petrol-station retail favor sachet and pouch formats for immediate consumption.
Supermarkets dominate volume throughput, with online retail expanding most steeply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food processing talent clusters in Switzerland and Germany anchor European formulation science, while Brazilian agronomists and Indian food technologists drive emerging market recipe adaptation.
United States
Household breakfast and snacking applications sustain volume leadership in the food spread category. FDA trans-fat phase-out deadlines compel legacy margarine reformulation across domestic manufacturing lines. Chicago and Minneapolis metropolitan areas concentrate R&D facilities where clean-label emulsion testing accelerates.
Germany
Grass-fed butter variants capture premium shelf space in Berlin and Munich hypermarkets. EFSA clean-label claim evaluations validate positioning for reduced-sugar nut spreads. The Baden-Württemberg industrial corridor hosts homogenization equipment vendors supplying pasteurization line upgrades.
India
Urban dual-income households fragment purchases between pantry jars and workplace sachets in Mumbai and Bangalore. FSSAI edible fat fortification mandates force multinational recipe adaptation for compliant distribution. Modern trade chilled sections in Delhi-NCR expand grab-and-go pouch formats.
Brazil
Metropolitan transit channels in São Paulo favor portable packaging over traditional jars for on-the-go consumption. ANVISA nutritional labeling requirements shape chocolate spread formulation for domestic retail. Protein-fortified nut spreads displace traditional cooking fats in Rio de Janeiro households.
Switzerland
Premium chocolate spread manufacturing anchors export-oriented production in the Swiss Mittelland region. Swissmedic evaluations of novel food additives influence emulsifier selection across European formulations. High-pressure processing technology adoption in Geneva and Zurich extends ambient shelf life without synthetic preservatives.
Global Food Spread Market Vendor Landscape
Top-tier vendors anchor mass-market distribution, while mid-tier specialists and artisanal producers occupy differentiated niches. The market exhibits tiered concentration with multinational conglomerates controlling branded retail shelf space alongside regional private-label suppliers. Strategic archetypes include supply-chain-integrated margarine manufacturers, premium nut-based formulation specialists, and private-label co-packers serving discounter channels. Competitive moves center on clean-label certification acquisition and pouch-format packaging line investment.
Within the premium-tier vector, Ferrero International S.A. exemplifies hazelnut-centric recipe positioning, while Unilever PLC represents scale-driven margarine distribution across emerging markets. The J.M. Smucker Company occupies a position in fruit spread and peanut butter categories, anchoring North American household penetration.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Unilever PLC |
| Ferrero International S.A. |
| The Hershey Company |
| Hormel Foods Corporation |
| The Kraft Heinz Company |
| Conagra Brands, Inc. |
| B&G Foods, Inc. |
| Nestlé S.A. |
| Others |
Supply Flow & Price Mechanics
Captive palm oil sourcing through Southeast Asian plantation networks anchors both supply security and margin control for mass-market margarine manufacturers. Unilever PLC leverages backward integration into Indonesian and Malaysian feedstock operations to buffer against commodity volatility while sustaining price-competitive positioning in India's FSSAI-regulated edible fat markets.
Pricing Analysis
Ingredient-plus-certification bundling separates clean-label premium tiers from unverified commodity spreads. Three-tier pricing structure across premium, standard, and economy levels tracks fortification compliance and third-party certification status. Price differentiation centers on FSSAI fortification validation and EFSA novel food claim approval. Cost compression in economy margarine lines is intensifying because of palm oil price volatility and trans-fat phase-out capital requirements. Foodservice operators in Germany and Switzerland show least price sensitivity, while urban Indian kirana channels exhibit highest elasticity.
Supply Chain Analysis
EFSA novel food qualification and FDA trans-fat compliance certification gate supplier eligibility for European and North American retail placement. Raw material concentration centers on Indonesia and Malaysia for palm oil derivatives, Côte d'Ivoire and Ghana for cocoa solids, and California and Argentina for almond inputs. Formulation rests on hydrogenation equipment, homogenization systems, and high-pressure processing lines. Single-source vulnerability in Southeast Asian palm oil supply creates exposure to El Niño-driven production shortfalls. Distribution runs through modern trade hypermarkets in Germany and France, e-commerce platforms in India and Brazil, and convenience retail in São Paulo and Mumbai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between India's FSSAI fortification mandates and Brazil's ANVISA labeling requirements creates recipe adaptation leverage—multinationals can transfer compliant formulations across emerging markets at lower incremental cost than developed-market reformulation.
For Market Incumbents: Deepen backward integration into Indonesian palm oil plantations to secure feedstock cost stability against price volatility. Fortify clean-label certification portfolios with third-party non-GMO and reduced-sugar validations to defend shelf space against artisanal nut butter entrants capturing price-insensitive urban consumers in Mumbai and São Paulo.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models on Indian and Brazilian e-commerce platforms to bypass modern trade listing fees. Target protein-fortified nut spreads in Brazilian metropolitan transit channels where pouch format adoption outpaces incumbent jar-format legacy portfolios. Exploit white space in single-serve sachet distribution through workplace convenience retail in Bangalore and Rio de Janeiro.
For Investors and Strategic Acquirers: Roll-up economics work for regional private-label co-packers because supermarket consolidation in Germany and France concentrates procurement scale among fewer suppliers. Five-to-ten year viability hinges on clean-label equipment retrofit completion and pouch-format line investment. Target mid-tier manufacturers with FSSAI-compliant recipe libraries and established modern trade relationships. Watch EFSA approval timelines for plant-based fat alternatives as inflection signal—delays beyond standard evaluation windows indicate regulatory friction that compresses premium positioning windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | EFSA validation and third-party non-GMO claims unlock premium shelf placement in German and French specialty grocers. |
| Pouch Format Production Line Expansion | Flexible packaging capacity captures Brazilian transit consumption and Indian workplace snacking occasions. |
| Backward Integration into Feedstock | Captive palm oil supply from Indonesian plantations buffers margin against commodity price volatility. |
| High-Pressure Processing Technology Adoption | HPP lines in Swiss and German facilities extend ambient shelf life without synthetic preservatives. |
| Dual-Market Recipe Adaptation | FSSAI-compliant formulations transfer from India to Brazil at lower cost than developed-market redevelopment. |
Methodological Framework
Bottom-up household and foodservice consumption modeling reconciled against top-down manufacturing capacity and trade flow tracking forms the analytical core. Primary interviews with brand managers at multinational spread manufacturers, category buyers at German and French hypermarkets, FSSAI compliance officers, and supply planners at Indian modern trade distributors combined with secondary validation. Secondary sources include FDA trans-fat phase-out documentation, EFSA novel food claim registers, FSSAI fortification standards, Nielsen retail audit data for European and Latin American markets, and customs records for palm oil and cocoa derivative trade flows.
Input-output matrices map raw material flows through formulation stages to end-use consumption across product type, packaging format, distribution channel, and geographic market dimensions. CAGRs derive from segment-level volume trajectories calibrated against regulatory mandate timelines and consumer behavioral shifts. Industry-specific forecast inputs include FSSAI fortification compliance deadlines, EFSA evaluation pipeline status for plant-based alternatives, and modern trade expansion rates in Mumbai, Bangalore, São Paulo, and Rio de Janeiro.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated sugar-tax implementation or palm oil supply disruption scenarios. Projections reflect assumptions about clean-label adoption velocity and equipment retrofit capital availability. A model refresh is warranted upon material change in EFSA novel food claim approval timelines or FSSAI fortification standard expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Hummus Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Dried Honey Market
Packaged Foods
Morning Goods Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Cook-In-Bags Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Food and Beverages Market
Packaged Foods
Burritos Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Packaged Currants Market