
 Frozen Novelty Market | 2026-2036
Frozen Novelty Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Novelty Market Insights
Market Context with Strategic Players
China is tilting toward expanded cold-chain manufacturing for frozen novelties. Yili leverages domestic dairy sourcing to anchor its production network across Inner Mongolia and Hubei. Unilever competes through brand portfolio breadth spanning premium and mass-market tiers. Nestle sustains global scale advantages in formulation consistency and retail distribution density.
Technical Definition and Structural Segments
Frozen novelties comprise individually portioned, frozen dairy and non-dairy confections manufactured through continuous freezing, extrusion, or mold-filling processes at temperatures below -18°C, designed for immediate consumption without additional preparation. The category serves impulse-purchase occasions, seasonal refreshment demand, and portion-controlled indulgence across retail and foodservice channels. Ice cream bars occupy the dominant margin pool due to premium coating formulations and brand equity, while health-conscious consumer segments within customer type are shifting fastest toward low-sugar and plant-based alternatives. Distribution channel dynamics reveal foodservice recovery post-pandemic and vending machine expansion in transit hubs as incremental volume levers.
Regulatory Frame and Forward-Looking Close
FDA nutrition labeling requirements, EU food additive standards under EFSA, and China's GB national food safety standards collectively shape permissible ingredients, serving-size disclosures, and front-of-pack claims across major markets. These frameworks elevate reformulation costs for smaller producers while creating compliance barriers that favor scaled manufacturers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving clean-label thresholds and carbon-footprint disclosure mandates as determinants of market access and price positioning.
Market Dynamics
Reformulation pressures from FDA nutrition labeling and EU food additive standards are compressing formulation cycles while elevating R&D spend thresholds, favoring manufacturers with captive ingredient development and regulatory affairs scale.
Growth Catalysts
- Clean-label mandates:EFSA additive restrictions and FDA serving-size disclosure rules are accelerating reformulation investments. Reformulated portfolios now command shelf-space premiums in US and German retail channels.
- Plant-based ingredient platforms:Oat and coconut protein bases are displacing dairy in novelty bars. European and North American foodservice channels are expanding SKUs to capture lactose-intolerant and flexitarian households.
- Single-serve convenience formats:Impulse-purchase occasions in transit hubs and convenience stores are driving mold-filling line investments. China's vending machine network expansion in Tier-2 cities amplifies this format pull.
Market Restraints
- Cold-chain energy costs:Natural gas and electricity price volatility in Germany and the United States is compressing storage and distribution margins for frozen inventory.
- Dairy input concentration:Milk powder and butterfat supply concentrates in New Zealand and EU dairy cooperatives, exposing margin pressure from commodity futures swings.
- Technical shelf-life ceilings:Clean-label reformulations sacrifice stabilizer efficacy, shortening distribution windows and complicating export logistics to warm-climate markets.
Strategic Opportunities
- Transit-hub vending penetration:Airports and high-speed rail stations in China and Germany remain underpenetrated for premium novelty SKUs. Automated retail formats bypass traditional cold-case competition.
- Carbon-footprint disclosure mandates:EU CSRD and emerging US SEC climate rules will reward early adopters of scope-three tracking. Front-of-pack carbon labels are becoming a differentiation vector.
- Functional ingredient convergence:Probiotic and adaptogenic inclusions are merging with frozen confection formats. Wellness-oriented households in US coastal metros are piloting these hybrid positioning strategies.
Industry Challenges
- Reformulation talent scarcity:Food scientists with dual expertise in cryogenic stability and plant-based protein functionality command premium compensation. Recruitment friction delays clean-label SKU launches.
- Legacy ERP integration:Batch-level traceability requirements for FDA and EU additive compliance strain aging manufacturing execution systems. Upgrade cycles compete with capacity expansion capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Novelty Market |
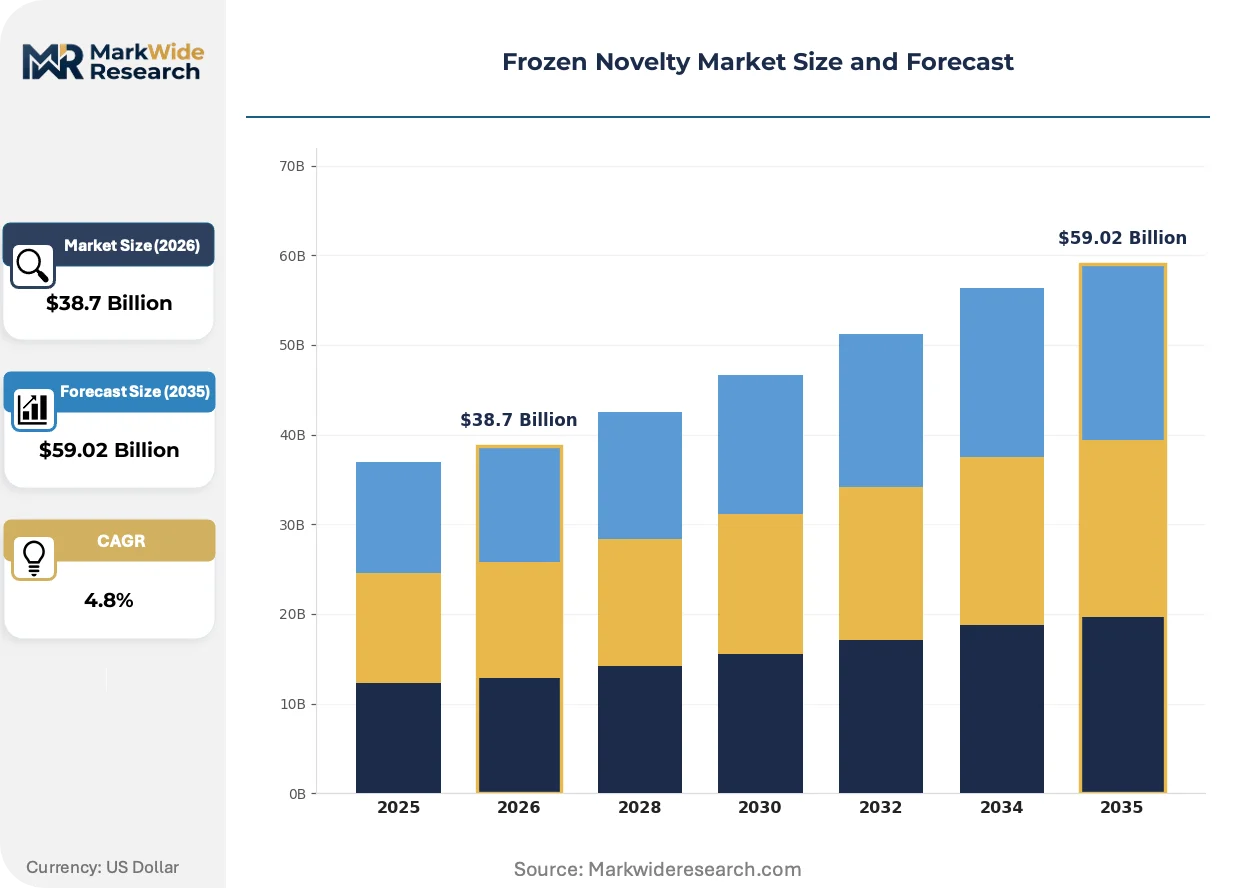
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream Bars, Frozen Desserts, Popsicles, Sorbet Customer Type: Families, Millennials, Children, Health-Conscious Consumers Flavor Profile: Chocolate, Vanilla, Fruit, Nut-Based Distribution Channel: Retail Stores, Online, Foodservice, Vending Machines |
| Companies Covered | Ben & Jerry's, Yili, The Magnum Ice Cream Company, General Mills, Mengniu, Unilever, Häagen-Dazs, GoodPop, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Novelty Market Trends and Innovations
Digital twin platforms are compressing pilot-scale testing timelines while regulatory disclosure mandates are reshaping ingredient sourcing transparency. Consumer demand for portion-controlled indulgence is fragmenting traditional family-pack formats.
Extrusion-based 3D structuring technology is virtualizing traditional mold-filling production for complex layered novelties. Premium manufacturers in Germany and the United States are deploying these systems to reduce tooling changeover downtime. The technology is virtualizing batch-size economics, enabling profitable production of seasonal limited-edition SKUs at sub-10,000-unit runs.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in industrial freezing equipment. Cold-chain operators face retrofit capex decisions with payback horizons extending past regulatory deadlines. Ice cream bar producers with captive freezing capacity in France and Italy are prioritizing ammonia-CO2 cascade systems to preempt compliance disruption.
Subscription-based replenishment models are capturing recurring revenue from household freezer-stocking routines. Direct-to-consumer channels in US metropolitan markets are disintermediating traditional grocery slotting fees. Younger demographics in coastal cities are consolidating brand discovery and purchase into curated monthly boxes, compressing traditional impulse-purchase dynamics at retail.
Frozen Novelty Market Segmentation
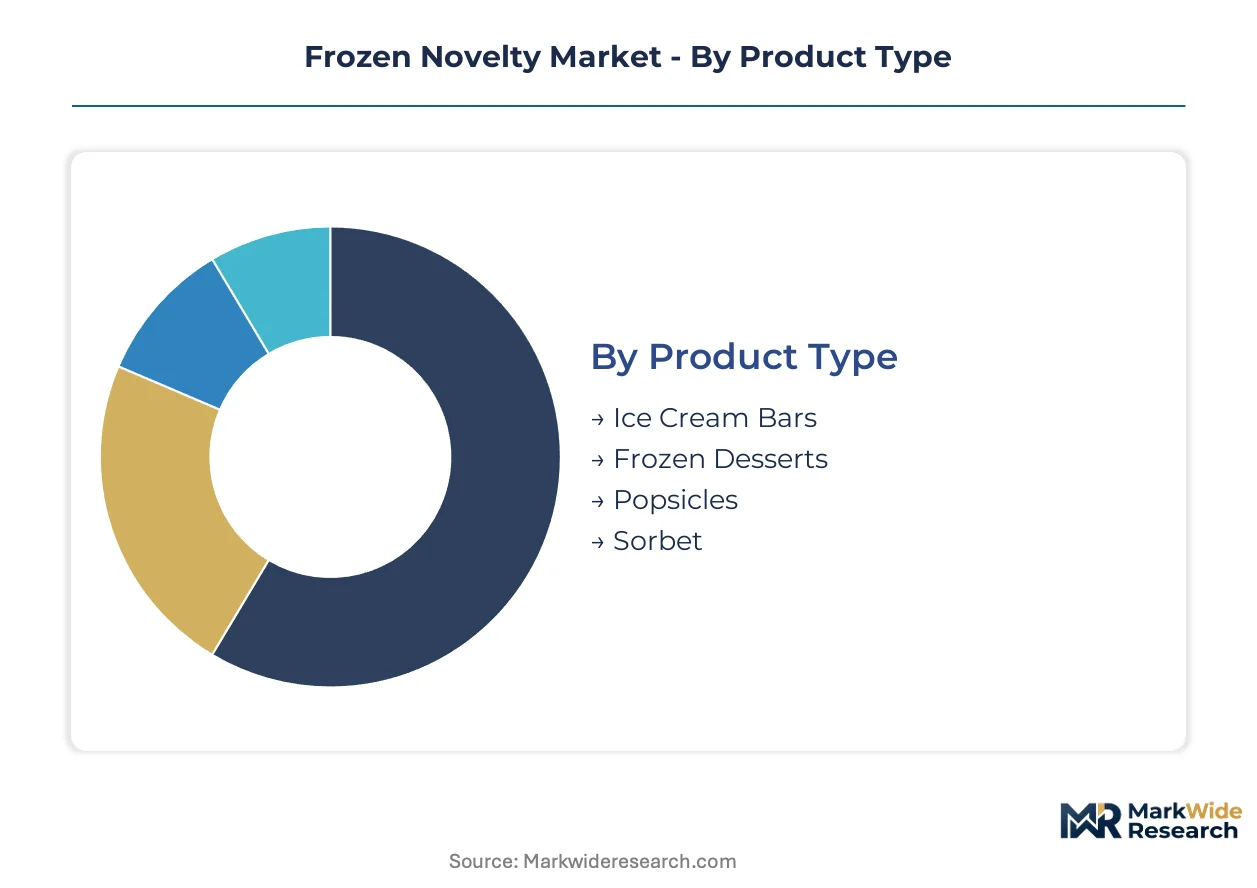
Frozen novelty manufacturers configure production lines around distinct consumption occasions, demographic targets, and channel economics. Segment-specific formulation requirements—coating integrity for ice cream bars, shelf stability for vending formats—determine capital allocation and margin architecture across the category.
Product Type:
Cost tier structures within frozen novelties separate premium coated formats from value-oriented water-based alternatives, with manufacturing complexity and ingredient intensity driving the stratification.
- Ice Cream Bars:Extruded or molded dairy cores receive chocolate, caramel, or nut-based coatings through enrobing tunnels. Demand concentrates in German and US retail channels where premium positioning justifies ingredient costs.
- Frozen Desserts:Non-dairy formulations using coconut, oat, or almond protein bases target lactose-intolerant and vegan households. European foodservice channels are expanding these SKUs fastest as flexitarian diets normalize.
- Popsicles:Water-fruit juice formulations with clean-label positioning serve children's refreshment occasions and seasonal impulse purchases.
- Sorbet:Dairy-free frozen fruit purees with higher overrun targets deliver lighter texture profiles for adult indulgence segments.
Ice cream bars hold installed capacity. Frozen desserts are rotating up the share rankings.
Customer Type:
Application-specific consumption contexts—household freezer stocking versus immediate gratification—shape packaging formats, portion sizes, and distribution channel selection.
- Families:Multi-pack configurations with value-tier pricing dominate household freezer replenishment cycles in suburban US and German retail environments.
- Millennials:Single-serve premium formats with Instagram-optimized aesthetics and exotic flavor profiles concentrate in urban convenience stores and direct-to-consumer channels.
- Children:Character-licensed packaging and vibrant color formulations drive impulse requests in retail and foodservice settings.
- Health-Conscious Consumers:Low-sugar, high-protein, and functional ingredient inclusions are expanding most quickly in coastal US metros and UK health-specialty retail.
Families anchor volume throughput. Health-conscious consumers are climbing the fastest.
Flavor Profile:
Volume concentration within mature flavor platforms creates procurement scale advantages for cocoa and vanilla suppliers, while emerging profiles test manufacturing flexibility.
- Chocolate:Cocoa butter and cocoa powder formulations command premium shelf placement through enrobed bar structures. German manufacturers maintain formulation leadership in coating stability.
- Vanilla:Bourbon and Tahitian extract sourcing distinguishes mass-market from premium tier positioning in US retail.
- Fruit:Strawberry, mango, and citrus purees serve seasonal refreshment demand and clean-label positioning across European markets.
- Nut-Based:Hazelnut, almond, and pistachio inclusions in praline layers or coating fragments target indulgence-oriented adult segments.
Chocolate holds installed capacity. Fruit is rotating up the share rankings.
Distribution Channel:
Margin architecture varies sharply by channel, with vending and foodservice formats bypassing traditional slotting fee structures while demanding specialized cold-chain logistics.
- Retail Stores:Supermarket and hypermarket freezer case placement requires trade spend investment for shelf-space allocation in US and German markets.
- Online:Direct-to-consumer and third-party marketplace fulfillment demands insulated packaging innovation and last-mile frozen logistics partnerships.
- Foodservice:Post-pandemic recovery in restaurants, cinemas, and amusement venues is expanding portion-controlled novelty SKUs for dessert menu integration.
- Vending Machines:Automated retail in Chinese Tier-2 city transit hubs and German rail stations represents the steepest expansion trajectory for impulse-format single-serve sales.
Retail stores hold installed capacity. Vending machines are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nutrition labeling requirements anchor the United States as the regulatory benchmark for frozen novelty compliance, with EFSA additive standards and China's GB national food safety standards creating parallel compliance corridors across major demand centers.
United States
Single-serve convenience formats drive impulse purchases in transit hubs and convenience stores. FDA serving-size disclosure rules and front-of-pack claim restrictions elevate reformulation costs for mid-tier producers. Chicago and New Jersey host concentrated cold-chain distribution clusters serving Northeast and Midwest retail density.
Germany
Premium coated ice cream bars command shelf-space premiums through enrobing technology leadership. EU F-Gas Regulation phase-down schedules accelerate ammonia-CO2 cascade system retrofits in industrial freezing equipment. Bavaria and North Rhine-Westphalia anchor manufacturing capacity for European export logistics.
China
Tier-2 city vending machine networks expand single-serve format penetration beyond traditional retail. GB national food safety standards and dual carbon goals shape permissible ingredients and energy efficiency mandates. Inner Mongolia and Hubei concentrate Yili's domestic dairy sourcing and production infrastructure.
France
Clean-label reformulations respond to EFSA additive restrictions and front-of-pack nutritional scoring systems. CSRD carbon-footprint disclosure mandates reward early scope-three tracking adopters. Paris and Lyon clusters specialize in seasonal limited-edition novelty development for European foodservice channels.
Japan
Portion-controlled indulgence formats align with aging household demographics and smaller household sizes. METI energy efficiency standards and JIS quality certifications structure equipment procurement decisions. Tokyo-Osaka corridor concentrates premium novelty R&D and retail innovation testing.
Frozen Novelty Market Competitive Landscape
Capability concentration sits with mid-tier specialists possessing cryogenic stability expertise; scale advantage sits with diversified confectionery conglomerates with captive regulatory affairs departments. The vendor base stratifies across three tiers: multinational CPG holding companies with portfolio breadth, regional dairy processors with backward integration into milk powder sourcing, and plant-based challengers with oat and coconut protein platform specialization. Dominant competitive moves include M&A activity targeting clean-label formulation capabilities and capacity expansion in Chinese Tier-2 city cold-chain infrastructure.
Within the scale-driven tier, Unilever and Nestle occupy positions exemplifying global distribution density and formulation consistency advantages. Among China-based dairy processors, Yili anchors domestic sourcing networks across Inner Mongolia and Hubei production zones. These three entities represent the archetype spectrum from multinational portfolio breadth to regional supply-chain control.
| Leading Market Players |
|---|
| Ben & Jerry's |
| Yili |
| The Magnum Ice Cream Company |
| General Mills |
| Mengniu |
| Unilever |
| Häagen-Dazs |
| GoodPop |
| Nestle |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Hamburg rail corridor's freight cost volatility compresses margin buffers for European-bound frozen novelty exports while amplifying price differentiation between premium enrobed bars and value-tier water-based alternatives. Supply concentration in Inner Mongolia dairy cooperatives and New Zealand milk powder auctions feeds directly into tiered pricing structures across US and German retail channels.
Pricing Analysis
Price spreads between German premium coated bars and Chinese mass-market alternatives have widened as cold-chain logistics costs diverge. Three-tier pricing structure across premium, standard, and economy levels reflects coating complexity, brand equity, and clean-label certification status. Pricing pressure stems from energy cost volatility in industrial freezing operations. Value-tier buyers in suburban US households exhibit highest price sensitivity; premium urban millennials demonstrate lowest.
Supply Chain Analysis
Upstream dairy feedstock concentrates in New Zealand, the Netherlands, and Inner Mongolia, with butterfat and milk powder auctions setting global cost benchmarks. Coconut and oat protein alternatives draw from Southeast Asian and Nordic processing hubs. Single-source vulnerability in New Zealand dairy cooperative supply creates margin exposure. Distribution runs through captive cold-chain networks in tier-one retail and expanding automated vending in Chinese transit corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in clean-label reformulation capabilities as health-conscious consumer segments splinter traditional family-pack demand into portion-controlled, functional ingredient niches.
For Market Incumbents: Entrench market position through captive regulatory affairs scale and ammonia-CO2 cascade freezing retrofits ahead of EU F-Gas deadlines. Acquire cryogenic stability expertise to offset reformulation talent scarcity threatening clean-label SKU velocity. Prioritize backward integration into domestic dairy sourcing to insulate against New Zealand milk powder futures volatility. For New Entrants and Emerging Players: Chinese Tier-2 city transit-hub vending networks represent the most penetrable entry point, bypassing incumbent-dominated retail freezer case slotting fees. European foodservice channels expanding plant-based dessert SKUs offer secondary white-space with lower capital barriers. Direct-to-consumer subscription models in US coastal metros provide go-to-market angle with disintermediated margin capture. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified confectionery conglomerates seeking to divest non-core frozen novelty portfolios amid energy cost pressures. Five-to-ten year viability hinges on regulatory compliance infrastructure and cold-chain asset ownership. Watch EU carbon-footprint disclosure mandate enforcement as inflection signal for scope-three tracking capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EFSA additive restrictions and FDA serving-size rules elevate compliance barriers favoring scaled R&D departments. |
| Transit-Hub Vending Expansion | Automated retail in Chinese Tier-2 cities and German rail stations bypass traditional grocery slotting fee structures. |
| Cold-Chain Energy Retrofit | Ammonia-CO2 cascade systems preempt EU F-Gas Regulation phase-down deadlines while reducing long-term operating costs. |
| Plant-Based Platform Development | Oat and coconut protein bases capture flexitarian household demand in European and North American foodservice channels. |
| Direct-to-Consumer Channel Launch | Subscription replenishment models in US metropolitan markets consolidate brand discovery and recurring revenue streams. |
Research Methodology
A standing panel of frozen novelty brand managers, retail category buyers, cold-chain logistics operators, and foodservice procurement directors provided ongoing calibration. Primary interviews combined with secondary validation from FDA GRAS filings, EFSA food additive opinions, Nielsen retail audit data, and customs trade records. Bottom-up SKU-level volume builds triangulated against top-down category spend estimates.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, customer archetype, flavor profile, and distribution channel. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption curves. Cryogenic equipment efficiency curves and dairy commodity futures spreads served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in energy prices, dairy commodity auctions, or cold-chain logistics costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and consumer clean-label threshold adoption. Cross-checking against external retail scanner data and foodservice volume indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Commercial Walk in Freezer Market
Processed and Frozen Foods
South America RTE Food Market
Processed and Frozen Foods
IQF Food Products Market
Processed and Frozen Foods
Taiyaki Ice Cream Market
Processed and Frozen Foods
Processed and Frozen Vegetables Market
Processed and Frozen Foods
Frozen Dumplings Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Frozen Potato Market
Processed and Frozen Foods
Europe Ice Cream Market
Processed and Frozen Foods
Frozen Meat Grinder Market
Processed and Frozen Foods
Frozen Baby Food Market
Processed and Frozen Foods
North America Dehydrated Food Market
Processed and Frozen Foods
Dry Mix Base for Frozen Desserts Market
Processed and Frozen Foods
North America Frozen Finger Chips Market
Processed and Frozen Foods
United States Frozen Yogurt Market
Processed and Frozen Foods
Frozen Tart Shells Market