
 India Instant Noodles Market | 2026-2036
India Instant Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
India Instant Noodles Market Foresight
FSSAI's mandatory micronutrient fortification standards for packaged foods is expanding the reformulation agenda across India's instant noodles sector. Nestle India Ltd. leverages its Maggi brand equity and extensive cold-chain distribution to sustain pantry-level visibility in tier-1 and tier-2 cities. Indo Nissin Foods Pvt. Ltd. anchors its competitive position through specialized wheat-flour processing capabilities and localized flavor development for South Indian palates. Patanjali Ayurved Limited differentiates with ayurveda-positioned ingredient narratives and controls significant shelf space in modern trade channels through its parent company's retail network.
Instant noodles comprise pre-cooked, dehydrated wheat-flour strands that undergo steaming, cutting, and flash-frying or air-drying before packaging with seasoning sachets; rehydration in boiling water yields an edible meal within three minutes, serving as a shelf-stable convenience food for time-constrained consumers and institutional feeding programs. Non-fried noodles command premium positioning among health-conscious buyers seeking reduced fat content, while fried noodles dominate volume throughput due to lower production costs and established taste preferences across rural and semi-urban markets. Pouch packaging occupies the mass-market tier through price accessibility, whereas cup formats capture travel and workplace consumption occasions with higher per-unit margins.
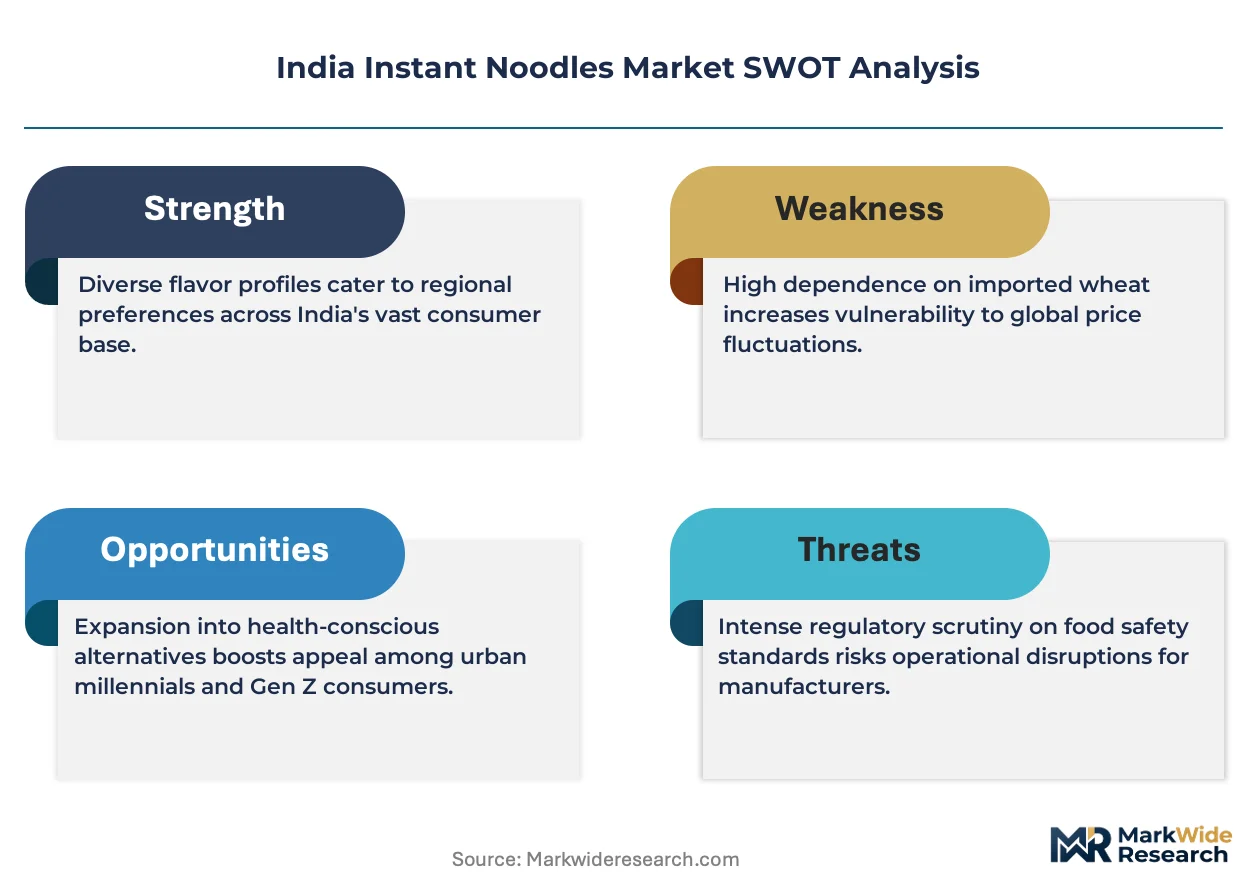
FSSAI labeling requirements and the Food Safety and Standards Act enforce compositional transparency and limit additive thresholds, compelling manufacturers to reformulate seasoning matrices and oil specifications. BIS packaging standards and state-level plastic waste management rules shape material selection for multi-layer laminate structures. Stakeholders must monitor evolving enforcement intensity at state food laboratories and anticipate fortification mandate expansion into additional micronutrient categories.
Market Dynamics
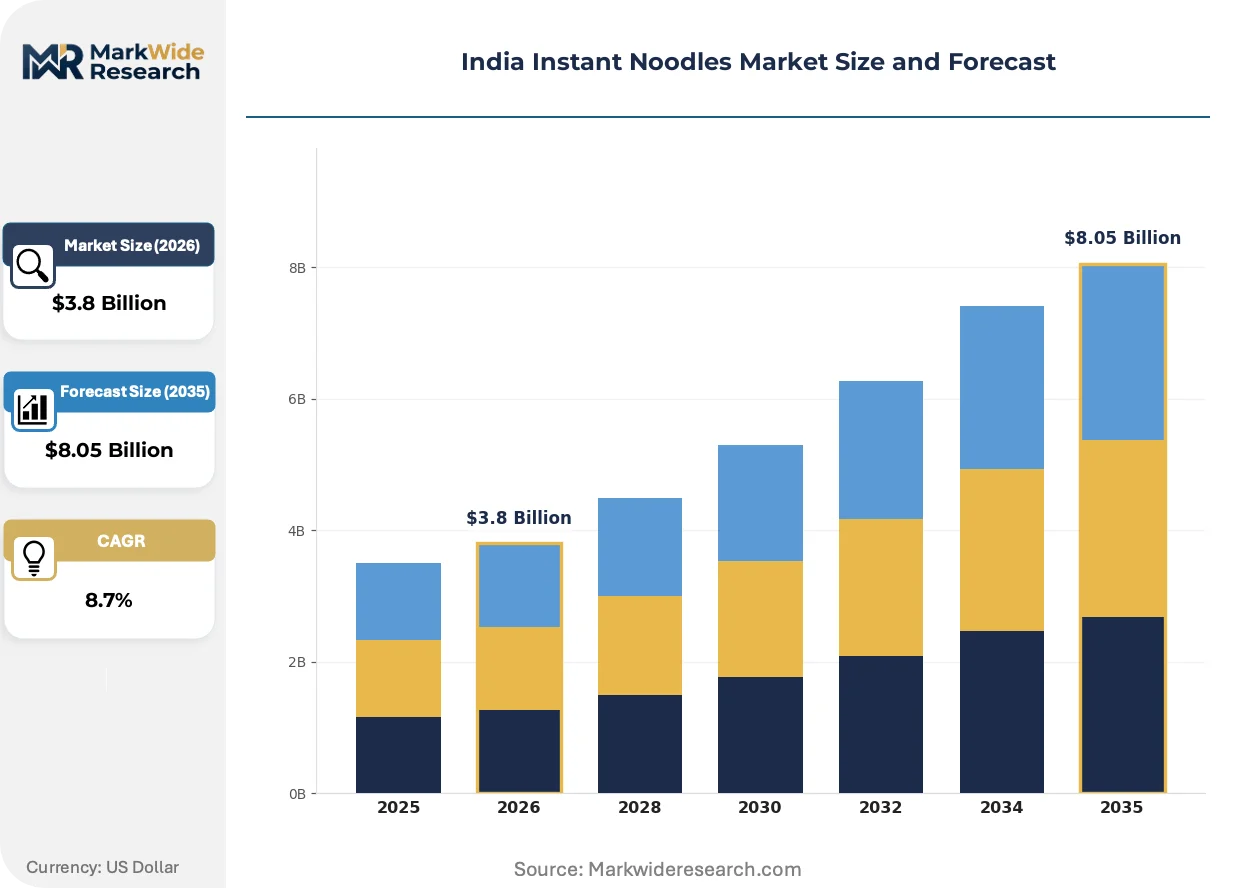
FSSAI fortification mandates and palm oil substitution protocols are compressing formulation timelines while tier-2 and tier-3 city expansion accelerates volume throughput beyond metro saturation points.
Growth Catalysts
- FSSAI Micronutrient Mandates:Mandatory iron and folic acid fortification in packaged foods is creating compliant product lines that qualify for institutional feeding tenders and school midday meal programs.
- Non-Fried Processing:Air-drying technology adoption among health-positioned brands is unlocking premium shelf space in modern trade channels and airport retail.
- Maharashtra-Karnataka-Tamil Nadu Corridor:Concentrated organized retail penetration in these states enables consistent replenishment cycles and promotional visibility for pouch formats.
Market Restraints
- Palm Oil Price Volatility:Import dependency on Malaysian and Indonesian crude palm oil exposes margin structures to currency fluctuation and biofuel diversion pressures.
- Multi-Layer Laminate Waste Rules:State-level plastic waste management regulations in Maharashtra and Tamil Nadu impose extended producer responsibility costs that pouch-format manufacturers must absorb.
- Wheat Flour Supply Concentration:Milling capacity clusters in Punjab and Haryana create geographic vulnerability to monsoon disruption and procurement price spikes.
Strategic Opportunities
- North Eastern States:Underpenetrated distribution in Assam and Manipur offers first-mover advantage for brands establishing cold-chain partnerships with local distributors.
- PLI Scheme for Food Processing:Production-linked incentive allocations for ready-to-eat manufacturing are subsidizing capital equipment upgrades for fortification-compatible production lines.
- E-Commerce Quick Commerce:Blinkit, Zepto, and Swiggy Instamart platforms are creating impulse-purchase occasions through sub-15-minute delivery promises in Bengaluru and Hyderabad.
Industry Challenges
- Food Technologist Scarcity:Specialized expertise in shelf-life extension for non-fried formats remains concentrated with legacy FMCG employers, constraining R&D velocity for mid-tier manufacturers.
- BIS Certification Timelines:Bureau of Indian Standards approval for modified packaging structures averages 8-12 months, delaying seasonal variant launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Instant Noodles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Noodles, Soupy Noodles, Fried Noodles, Non-Fried Noodles Flavor Profile: Spicy, Chicken, Vegetable, Curry Packaging Type: Bags, Cups, Pouches, Bowls Target Consumer: Students, Professionals, Families, Health-Conscious Individuals |
| Companies Covered | Patanjali Ayurved Limited, Indo Nissin Foods Pvt. Ltd., Nestle India Ltd., Tata Consumer Products Limited, CG Foods India Pvt. Ltd., ITC Limited, Capital Foods Pvt. Ltd., Haldiram Foods International Pvt. Ltd., Hindustan Unilever Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Instant Noodles Market Shifts & Advancements
Processing technology and distribution infrastructure are converging to compress product development cycles while reformulation pressures from health regulations accelerate ingredient substitution experiments.
Air-drying equipment is modularizing production floor layouts for manufacturers seeking to add non-fried capacity without greenfield facility investments. Tier-2 city processors in Gujarat and Rajasthan are adopting skid-mounted drying units that retrofit existing fried-noodle lines. This capital-efficient approach is modularizing entry barriers for regional brands testing health-positioned variants before national rollout.
FSSAI's proposed expansion of micronutrient categories beyond iron and folic acid is forcing seasoning matrix reformulations ahead of anticipated notification. Manufacturers are pre-approving vitamin premix suppliers and revising label artwork to accommodate additional nutritional claims. The branded packaged segment is responding fastest, while unorganized regional players face compliance cost disadvantages.
Quick-commerce platforms are fragmenting traditional wholesale-retail relationships by capturing pantry-stocking occasions previously served by kirana stores. Young urban professionals in Gurugram and Pune are substituting planned monthly purchases with on-demand single-unit orders. This behavior shift is most visible in cup-format consumption during office hours, where convenience premium tolerance exceeds traditional price sensitivity thresholds.
India Instant Noodles Market Segmentation
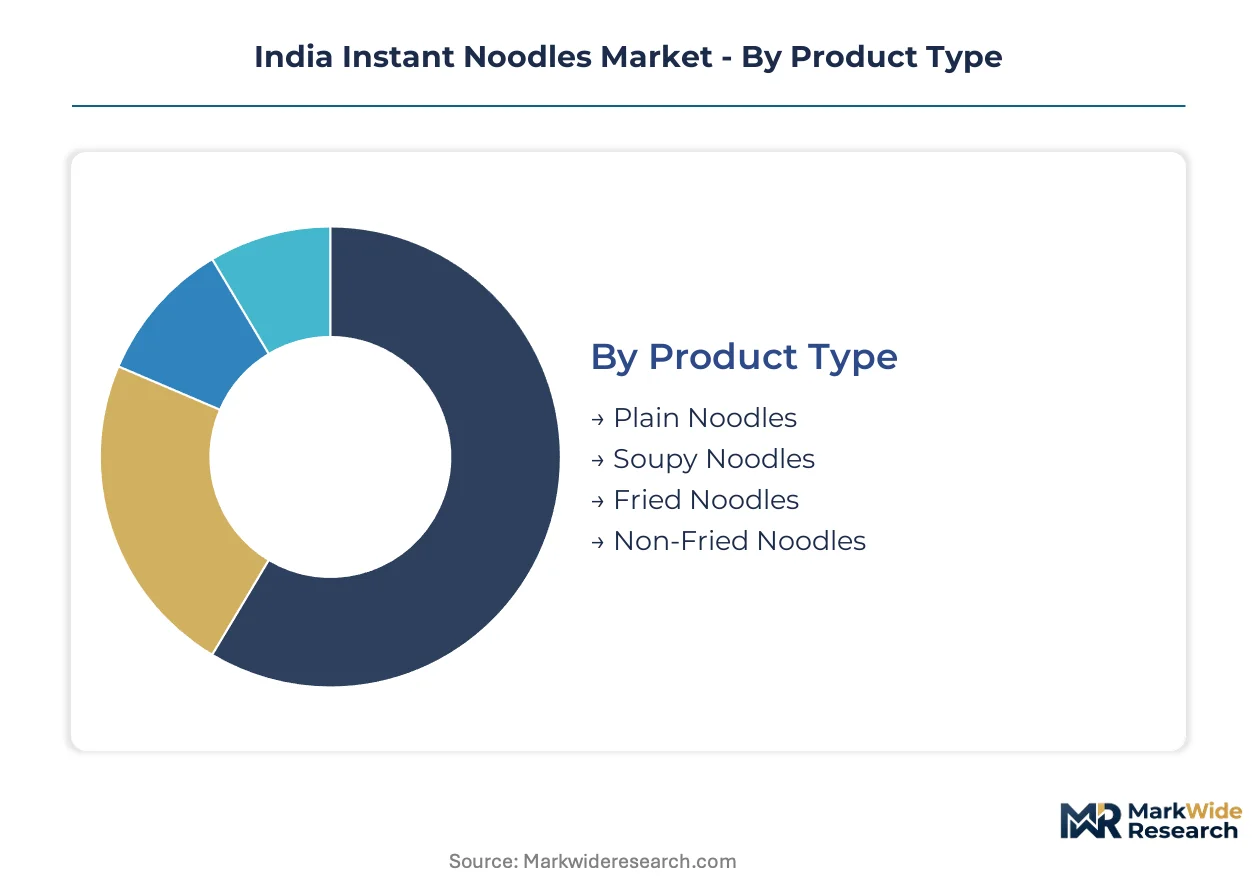
Segmentation in India's instant noodles market reveals distinct consumption occasions and price-elasticity profiles. Manufacturers calibrate formulation, packaging, and distribution intensity to match the upgrade cycles and pantry-stocking behaviors of each consumer cluster.
Product Type:
Upgrade cycles vary dramatically across processing methods, with health-conscious consumers trading up from fried to non-fried formats while value buyers remain anchored to traditional variants.
- Non-Fried Noodles:Air-dried wheat strands retain lower fat content through steam-drying rather than flash-frying. Demand concentrates in Bengaluru and Hyderabad among young professionals seeking permissible indulgence, with FSSAI fortification mandates accelerating compliant product launches.
- Fried Noodles:Palm oil-fried strands dominate mass-market throughput due to established taste preferences and lower unit economics. Volume concentrates in Maharashtra and Tamil Nadu kirana networks where price sensitivity limits format experimentation.
- Plain Noodles:Unseasoned base formats serve institutional feeding programs and custom recipe applications in Kerala and coastal Karnataka.
- Soupy Noodles:Broth-integrated variants with higher moisture sachets target monsoon-season consumption in Mumbai and Chennai.
Fried noodles sit at the top of the volume ranking, with non-fried formats climbing the fastest.
Flavor Profile:
Regional palate segmentation determines seasoning matrix investments, with manufacturers localizing spice intensity and protein positioning to match state-level consumption patterns.
- Spicy:Chili-forward formulations with Andhra and Telangana origin profiles command premium shelf space in modern trade. Maharashtra's urban corridors drive repeat purchase frequency for Schezwan-derivative variants.
- Curry:Turmeric-cumin base notes align with North Indian pantry staples, anchoring volume in Delhi-NCR and Punjab distributor networks.
- Chicken:Dehydrated poultry extract segments face FSSAI label scrutiny but retain traction in hostel and workplace canteen channels.
- Vegetable:Freeze-dried carrot and pea inclusions target midday meal program tenders in Karnataka and Tamil Nadu government schools.
Spicy variants capture the highest absolute volume, with curry-positioned products expanding most quickly in tier-2 city retail.
Packaging Type:
Format selection directly governs margin structure and distribution channel eligibility, with multi-layer laminate specifications varying by state-level plastic waste enforcement intensity.
- Pouches:Flexible laminate sachets with nitrogen flushing dominate kirana replenishment cycles. Tamil Nadu and Maharashtra impose extended producer responsibility levies that compress margins for this mass-market tier.
- Cups:Double-walled paper-plastic hybrids capture travel and workplace consumption with per-unit premiums. Quick-commerce platforms in Gurugram and Pune stock single-unit SKUs for impulse replacement purchases.
- Bags:Bulk family packs with zip-lock closures serve monthly pantry stocking in Gujarat and Rajasthan joint-family households.
- Bowls:Microwave-safe polypropylene formats target railway station and airport retail in Mumbai, Delhi, and Bengaluru.
Pouch formats lead volume throughput, with cup variants gaining share fastest through quick-commerce channel expansion.
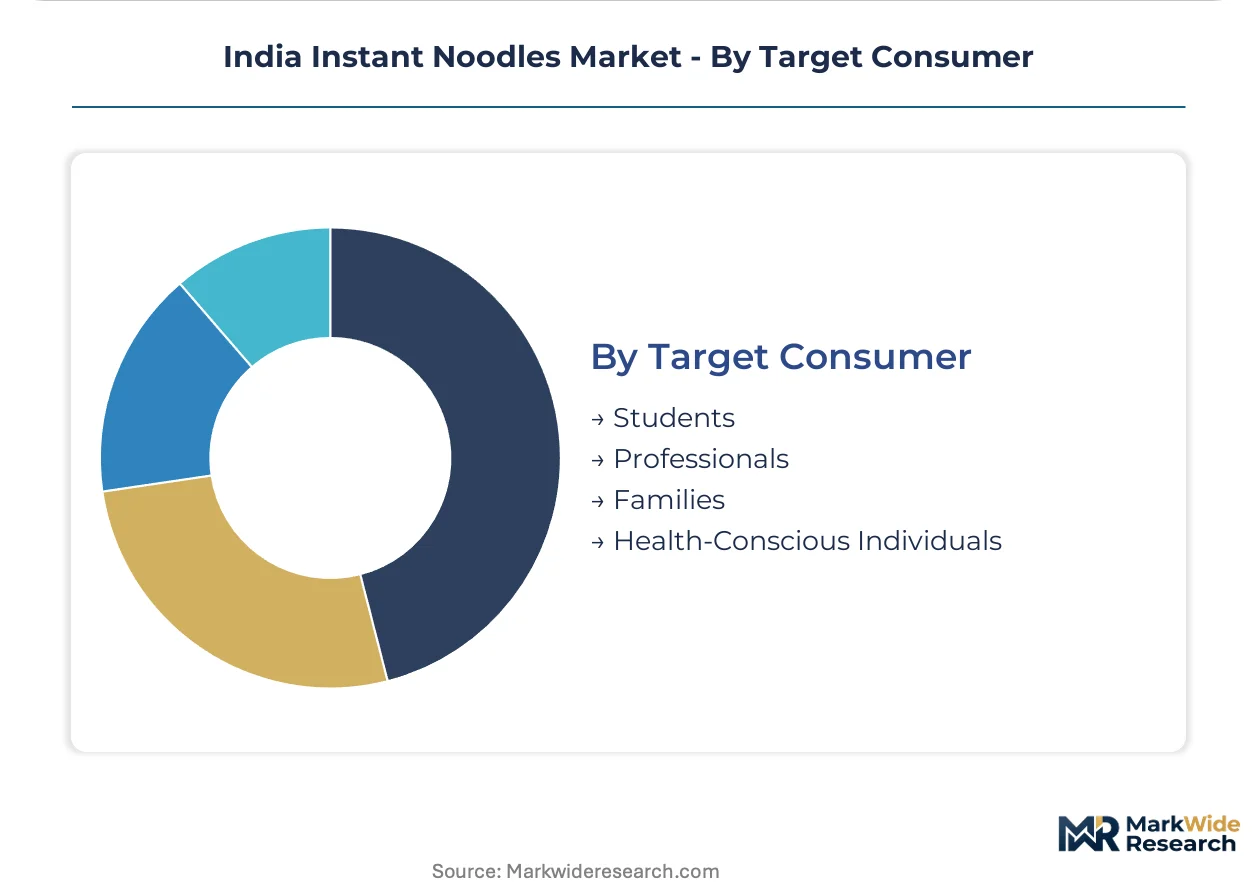
Target Consumer:
Demographic targeting shapes communication architecture and retail placement strategy, with each cluster exhibiting distinct trial-to-adoption velocity and brand loyalty patterns.
- Students:Hostel-dwelling consumers in Pune, Hyderabad, and Jaipur prioritize price-per-serving and preparation speed. Maggi's nostalgia positioning sustains pantry dominance despite competitor price undercutting.
- Health-Conscious Individuals:Fitness-oriented buyers in South Mumbai and Bengaluru's Koramangala cluster scrutinize sodium and palm oil disclosures, driving non-fried and reduced-salt line extensions.
- Professionals:Time-constrained office workers in Gurugram and Whitefield substitute lunch occasions with cup-format purchases through Blinkit and Zepto platforms.
- Families:Multi-person households in Ahmedabad and Lucknow favor large-format pouches for shared meal occasions, with children influencing flavor selection.
Students anchor absolute consumption volume, with health-conscious individuals showing the steepest expansion trajectory as reformulated products penetrate modern trade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young food technologists and supply chain specialists cluster in Maharashtra and Karnataka, anchoring India's instant noodles innovation pipeline. Their concentration shapes reformulation velocity and distribution network density across the country's most penetrated markets.
Maharashtra
Mumbai's young urban professionals drive cup-format demand through quick-commerce platforms, with Blinkit and Zepto capturing office-hour consumption. FSSAI fortification mandates accelerate compliant product launches from processors in Nashik and Pune. The Mumbai-Pune corridor hosts the deepest organized retail penetration, enabling consistent replenishment cycles for pouch formats.
Karnataka
Bengaluru's health-conscious consumers anchor non-fried noodle adoption, with Koramangala and Whitefield clusters showing premium tolerance. State-level plastic waste management rules impose extended producer responsibility costs on pouch manufacturers. The Bengaluru-Mysuru industrial belt concentrates air-drying equipment installations for regional brands testing health-positioned variants.
Tamil Nadu
Chennai's hostel-dwelling students sustain high-frequency spicy variant consumption, with Schezwan-derivative flavors commanding shelf space. FSSAI labeling requirements enforce compositional transparency for seasoning matrices manufactured in Coimbatore. The Chennai-Coimbatore corridor processes significant wheat flour volumes for South Indian palate localization.
Gujarat
Ahmedabad's joint-family households favor large-format bag packaging for monthly pantry stocking, with children influencing flavor selection. BIS packaging standards shape material selection for multi-layer laminate structures produced in Vadodara. The Ahmedabad-Surat cluster experiments with skid-mounted drying units retrofitting existing fried-noodle lines.
Delhi-NCR
Gurugram's time-constrained professionals substitute lunch occasions with on-demand cup purchases, tolerating convenience premiums. DGFT palm oil import protocols expose margin structures to currency fluctuation pressures. The Noida-Ghaziabad processing belt serves institutional feeding tenders and school midday meal programs.
India Instant Noodles Market Competitive Landscape
Capital-heavy producers with integrated milling and frying infrastructure compete with asset-light brands outsourcing manufacturing to third-party processors. The market consolidates around three tiers: multinational FMCG giants with cold-chain dominance, domestic Ayurveda-positioned challengers controlling modern trade shelf space, and regional specialists optimizing for state-level palate preferences. Dominant competitive moves include backward integration into wheat flour milling and strategic partnerships with quick-commerce platforms for last-mile velocity.
Within the multinational tier, Nestle India Ltd. anchors pantry-level visibility through extensive distribution networks. Indo Nissin Foods Pvt. Ltd. occupies a specialized position through wheat-flour processing capabilities. Patanjali Ayurved Limited exemplifies the Ayurveda-positioned archetype, leveraging its parent company's retail network for shelf space control. These three represent distinct strategic postures: legacy brand equity, technical specialization, and vertical retail integration.
| Leading Market Players |
|---|
| Patanjali Ayurved Limited |
| Indo Nissin Foods Pvt. Ltd. |
| Nestle India Ltd. |
| Tata Consumer Products Limited |
| CG Foods India Pvt. Ltd. |
| ITC Limited |
| Capital Foods Pvt. Ltd. |
| Haldiram Foods International Pvt. Ltd. |
| Hindustan Unilever Limited |
| Others |
Supply & Pricing Matrix
Premium-non-fried and commodity-fried format divergence in India's instant noodles sector manifests in divergent margin structures and sourcing configurations, with health-positioned brands absorbing air-drying equipment costs while mass-market processors optimize palm oil procurement through DGFT import protocols.
Pricing Analysis
Unbundled seasoning and base-noodle pricing dominates institutional tenders, while bundled cup-format premiums capture workplace consumption through quick-commerce platforms. Price differentiation rests on fortification certification tiers and palm oil substitution compliance costs. Pricing pressure intensifies in the pouch segment as FSSAI labeling mandates force reformulation investments. Students and hostel-dwelling consumers exhibit highest price sensitivity; health-conscious buyers in Bengaluru and South Mumbai tolerate significant premiums for reduced-fat positioning.
Supply Chain Analysis
FSSAI's local-content fortification mandates are reshaping sourcing toward domestic vitamin premix suppliers and Punjab-Haryana wheat milling clusters. Wheat flour supply concentrates in northern India, while palm oil draws from Malaysian and Indonesian import channels. Single-source vulnerability in crude palm oil exposes margin structures to currency fluctuation and biofuel diversion pressures. Distribution runs through kirana networks in Maharashtra and Tamil Nadu, with quick-commerce platforms fragmenting traditional wholesale-retail relationships in Gurugram and Pune.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's instant noodles market offers geographic-arbitrage potential between Maharashtra's saturated organized retail corridors and the underpenetrated North Eastern states, where distribution cost differentials create first-mover margin advantages.
For Market Incumbents: Anticipate quick-commerce platform consolidation by securing exclusive replenishment partnerships with Blinkit and Zepto in Bengaluru and Hyderabad. Defend against Patanjali's Ayurveda-positioned encroachment by accelerating FSSAI-compliant fortification line extensions. Backward integration into wheat flour milling in Nashik and Pune anchors supply security against monsoon-driven procurement spikes.
For New Entrants and Emerging Players: Quick-commerce impulse-purchase routes offer lowest customer-acquisition costs for cup-format specialists targeting Gurugram and Whitefield office corridors. North Eastern states present the most penetrable white space, with Assam and Manipur showing minimal organized retail saturation. Localized flavor development for South Indian palates unlocks shelf space in Chennai-Coimbatore distributor networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional brands face FSSAI compliance cost disadvantages against multinational fortification capabilities. Long-term viability favors processors with modular air-drying equipment enabling premium-format pivot without greenfield investment. Watch for BIS certification timeline delays as inflection indicators constraining seasonal variant velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wheat Milling | Punjab-Haryana milling capacity captures margin from concentrated flour supply. |
| Quick-Commerce Exclusive Partnership | Blinkit and Zepto platforms secure sub-15-minute replenishment velocity in metro corridors. |
| Non-Fried Production Line Retrofit | Skid-mounted air-drying units in Gujarat and Rajasthan test health-positioned variants. |
| FSSAI Fortification Pre-Compliance | Vitamin premix supplier pre-approval accelerates mandate-ready product launches. |
| North Eastern Distribution Buildout | Assam and Manipur cold-chain partnerships establish first-mover shelf presence. |
Research Methodology
Coverage spans Maharashtra, Karnataka, Tamil Nadu, Gujarat, and Delhi-NCR, with primary inputs from each state cluster. The analysis combines interviews with brand managers at leading FMCG houses, category buyers at modern trade retailers, supply planners at wheat milling operations, and channel sales heads at regional distributors. Secondary validation draws from FSSAI notification records, BIS packaging standard filings, DGFT palm oil import data, and organized retail audit databases. Bottom-up volume modeling and top-down value triangulation cross-check segment-level estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include processing method, flavor profile, packaging format, and target consumer archetype. CAGRs derive from trend-line extrapolation of historical consumption patterns adjusted for regulatory inflection points. Forecast inputs incorporate PLI scheme subsidy allocations for ready-to-eat manufacturing and quick-commerce platform expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for air-drying equipment modularization would alter the outlook for non-fried format penetration. Forecasts reflect assumptions about FSSAI enforcement intensity at state food laboratories and palm oil price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Tortilla Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Dried Soup Market
Packaged Foods
India Packaged Food Products Market