
 India Breakfast Cereals Market | 2026-2036
India Breakfast Cereals Market Size, Share, and Industry Trends Forecast 2026-2036
India Breakfast Cereals Market Foresight
Market Dynamics
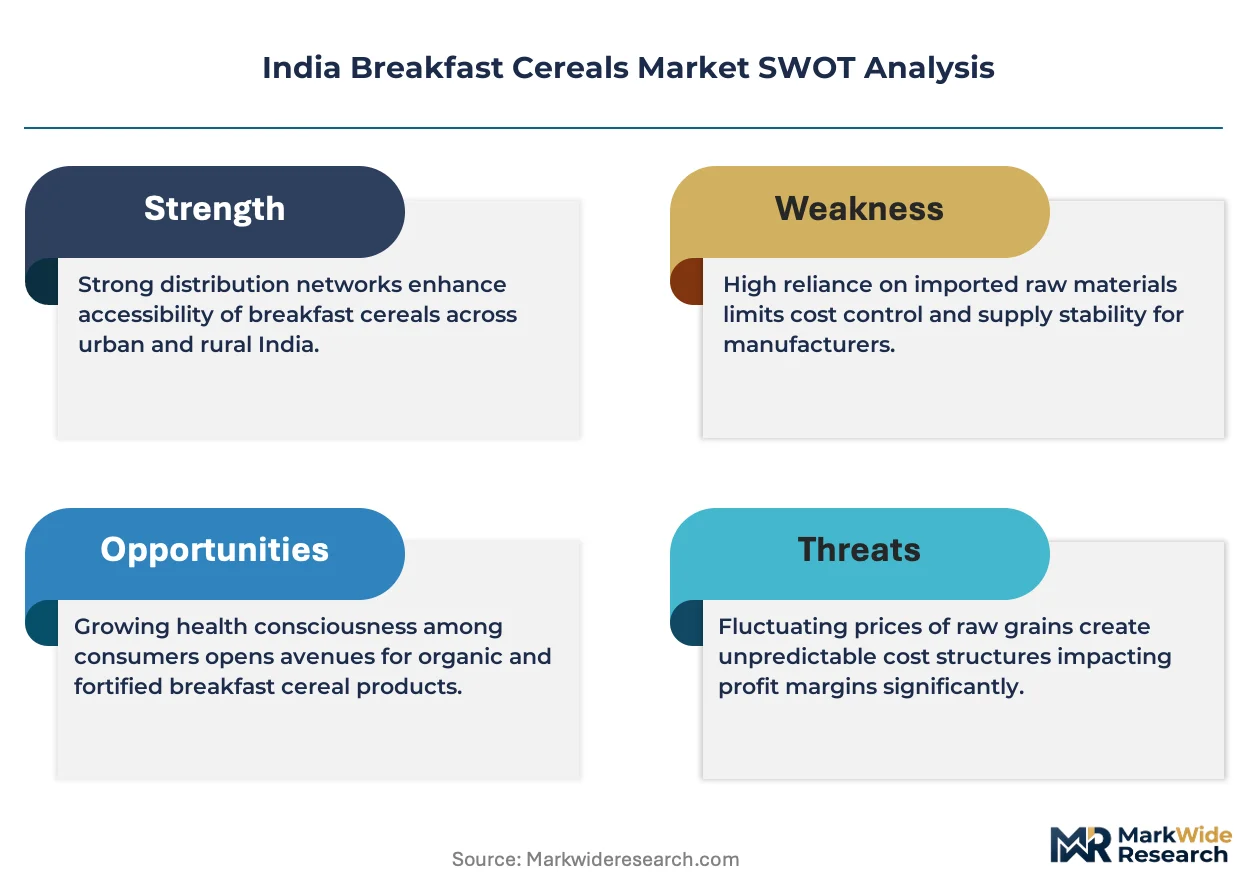
Gujarat is reshaping India's breakfast cereals manufacturing map through new processing facilities and grain-sourcing infrastructure. Bagrry's India Ltd leverages its Punjab grain-milling heritage to sustain premium positioning in the oats segment. Tata Consumer Products anchors its portfolio through Soulfull's millet-based innovations, competing directly with multinational incumbents. PepsiCo extends its Quaker brand distribution through kirana-store digitization, occupying shelf space that local challengers struggle to match.
Product Landscape
Breakfast cereals comprise processed grain formulations—typically oats, wheat, corn, or millets—often roasted, flaked, or puffed, then fortified with vitamins and minerals for rapid morning consumption without cooking. Manufacturing employs extrusion, flaking, and toasting at controlled moisture levels below 10% to ensure shelf stability and crunch retention. Instant Oats dominates volume due to price accessibility and familiar preparation rituals, while Muesli captures the fastest expansion among urban professionals seeking minimally processed options. Granola concentrates margin pools through premium positioning in metropolitan supermarkets, whereas Corn Flakes faces maturity pressure from private-label competition in hypermarkets.
Regulatory Environment
FSSAI fortification standards, BIS packaging norms, and the PLI scheme for food processing collectively shape product composition, label claims, and capital-access pathways for domestic manufacturers. These frameworks raise compliance costs for unorganized entrants while rewarding scale players with technical capabilities and laboratory infrastructure. Stakeholders must monitor evolving FSSAI thresholds for added-sugar disclosure, as reformulation timelines will separate prepared manufacturers from laggards.
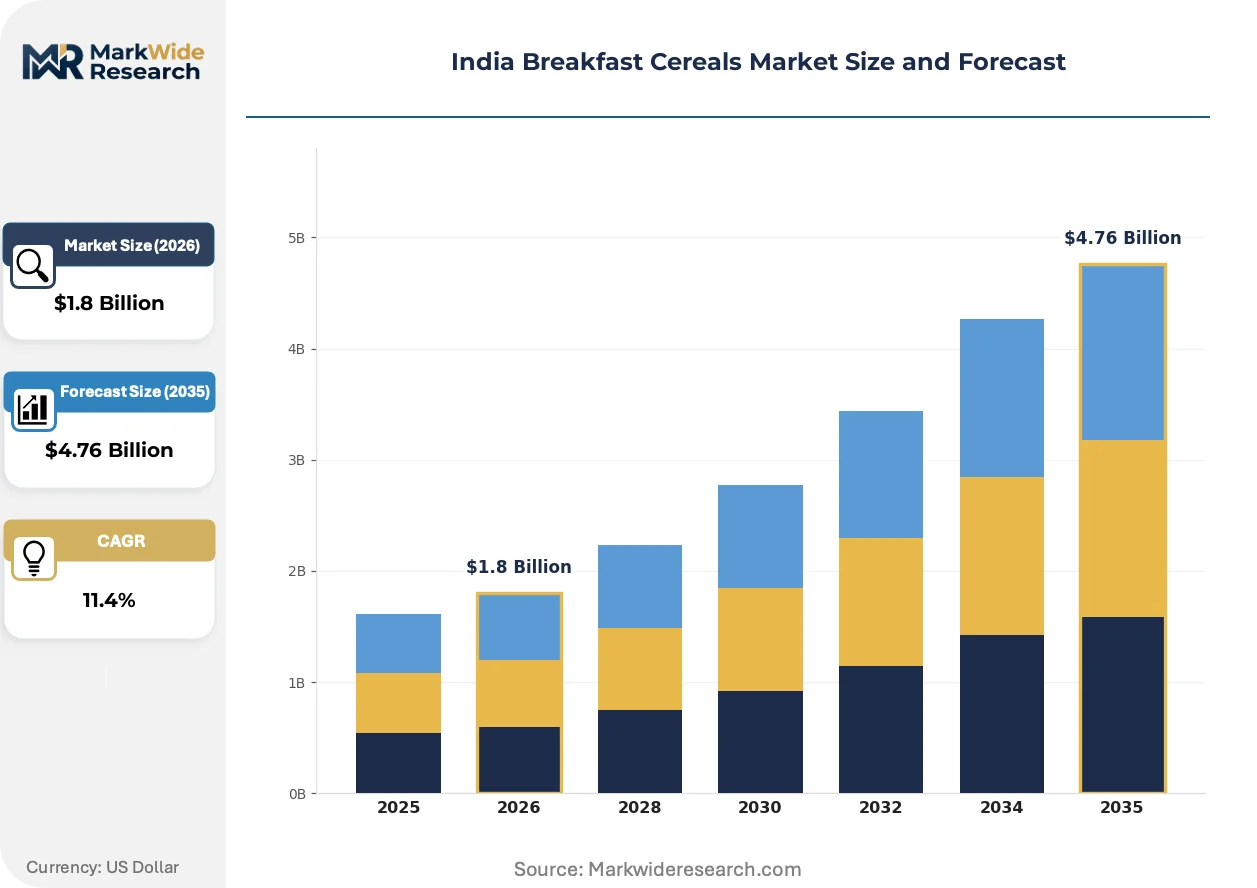
Market Dynamics
FSSAI fortification mandates and PLI scheme incentives are restructuring competitive entry barriers, favoring manufacturers with laboratory infrastructure and micronutrient formulation capabilities over unorganized processors.
Growth Catalysts
- Urban household time compression:Dual-income families in Maharashtra and Karnataka are adopting ready-to-eat morning formats, creating sustained volume pull for instant oats and muesli variants.
- FSSAI fortification guidelines:Mandatory micronutrient enrichment in packaged foods is accelerating product reformulation toward iron, folic acid, and vitamin D fortified offerings.
- Modern retail penetration:Hypermarket and supermarket expansion in Gujarat and Tamil Nadu is creating dedicated shelf space for premium granola and millet-based cereals.
Market Restraints
- Wheat and oat input volatility:Domestic grain procurement costs fluctuate with monsoon irregularities, compressing margin stability for flaked and puffed product lines.
- Kirana store distribution concentration:Traditional retail networks in tier-2 and tier-3 cities resist category education investments, limiting geographic expansion beyond metropolitan clusters.
- Fresh breakfast substitution:Hot idli, dosa, and paratha preparations retain strong cultural preference in South Indian and North Indian households, constraining daily consumption frequency.
Strategic Opportunities
- Uttar Pradesh and Bihar underpenetration:Low modern retail density in these northern states creates first-mover advantage for direct-to-consumer subscription models and e-commerce fulfillment.
- Millet-based innovation tailwind:FSSAI recognition of millets as nutri-cereals aligns with government promotion of sorghum, pearl millet, and finger millet formulations.
- Quick-commerce channel emergence:Delivery platforms promising sub-30-minute fulfillment are opening impulse purchase occasions for single-serve cereal packs in dense urban zones.
Industry Challenges
- Extrusion technologist scarcity:Specialized expertise in controlled moisture processing and texture optimization remains concentrated among legacy equipment operators, constraining new facility commissioning.
- BIS packaging compliance timelines:Migration to food-grade laminate structures with oxygen barrier properties requires capital-intensive line upgrades and extended validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Breakfast Cereals Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Oats, Muesli, Granola, Corn Flakes Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Hypermarkets End User: Children, Adults, Health-conscious Individuals, Fitness Enthusiasts Packaging Type: Bags, Boxes, Tubs, Pouches |
| Companies Covered | Bagrry's India Ltd, Tata Consumer Products, Nestle SA, GlaxoSmithKline Consumer Healthcare Ltd, Patanjali Ayurved Ltd, PepsiCo Inc, Marico Ltd, Manna Foods, Kellanova, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Breakfast Cereals Market Shifts & Advancements
Digital traceability systems and clean-label formulation pressures are redefining quality assurance and ingredient sourcing protocols across the value chain.
Blockchain-enabled grain provenance tracking is virtualizing supply chain transparency for premium oat and millet sourcing. Organized retailers in Mumbai and Bangalore are mandating lot-level traceability documentation. This technology is compressing supplier qualification timelines while elevating audit costs for uncertified processors.
FSSAI's evolving added-sugar disclosure thresholds are forcing reformulation of children's cereal portfolios toward reduced glycemic index alternatives. Manufacturers must retest sensory profiles and shelf stability under accelerated aging protocols. The breakfast cereal segment faces compressed product development cycles as label claim deadlines approach.
Subscription-based replenishment models are displacing traditional stock-up purchases among metropolitan working professionals. Direct-to-consumer platforms offer personalized flavor rotations and portion-controlled deliveries. This behavioral shift concentrates most visibly in Pune and Hyderabad's technology corridor residential clusters.
India Breakfast Cereals Market Segmentation
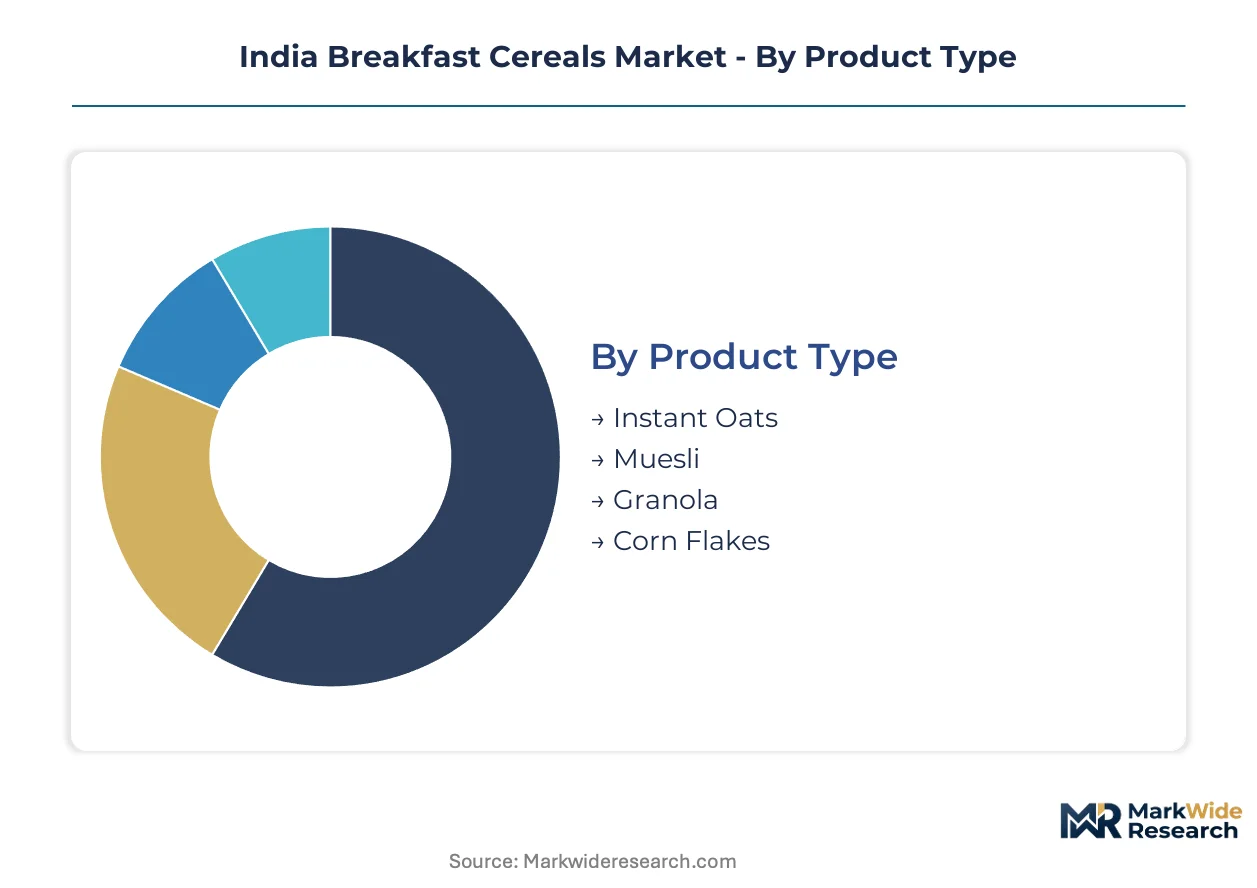
Breakfast cereals in India fragment across distinct consumption occasions, retail formats, and nutritional positioning strategies. Manufacturers calibrate formulation, fortification levels, and pack sizes to match divergent preparation rituals between metropolitan professionals and family households.
Product Type:
Cost tier determines ingredient sourcing, processing complexity, and margin structure across the four product formats.
- Instant Oats:Pre-cooked and flattened oat groats rehydrate in hot milk or water within two minutes. Maharashtra and Karnataka working households drive volume through daily convenience consumption, though price sensitivity constrains premium positioning.
- Muesli:Uncooked rolled oats blended with dried fruits, nuts, and seeds deliver minimally processed nutrition. Urban professionals in Bangalore and Pune adopt this format fastest, drawn by clean-label attributes and no-cook preparation rituals.
- Granola:Baked clusters of oats, sweeteners, and oils targeting premium metropolitan supermarkets.
- Corn Flakes:Mature flaked maize category facing private-label pressure in hypermarket channels.
Instant Oats commands the established base. The steepest expansion runs through Muesli.
Distribution Channel:
Channel selection shapes brand visibility, trial conversion rates, and working capital requirements for cereal manufacturers.
- Supermarkets:Organized retail chains in Gujarat and Tamil Nadu provide dedicated shelf space for premium granola and millet-based innovations. FSSAI-compliant fortification claims gain credibility through controlled temperature storage and standardized display protocols.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment and personalized flavor rotations among Pune and Hyderabad technology corridor residents. Quick-commerce integration is compressing delivery windows to under 30 minutes for impulse single-serve purchases.
- Convenience Stores:Kirana networks in tier-2 cities resist category education investments, limiting geographic expansion.
- Hypermarkets:Volume-driven formats where private-label corn flakes compete aggressively on price.
Supermarkets anchor premium positioning. Online Retail is climbing the fastest among emerging channels.
End User:
Demographic targeting dictates fortification protocols, portion sizing, and flavor development priorities.
- Children:Iron, folic acid, and vitamin D fortification respond to FSSAI mandates and parental nutritional anxiety. Reformulation pressures intensify as added-sugar disclosure thresholds tighten, forcing reduced glycemic index alternatives.
- Adults:Dual-income households in Mumbai and Delhi NCR seek time-compressed morning solutions without cooking requirements.
- Health-conscious Individuals:Millet-based and low-sugar variants attract preventive health-focused consumers.
- Fitness Enthusiasts:High-protein and portion-controlled formats align with macronutrient tracking behaviors.
Adults represent the volume foundation. Children is gaining share fastest as fortification compliance creates differentiation.
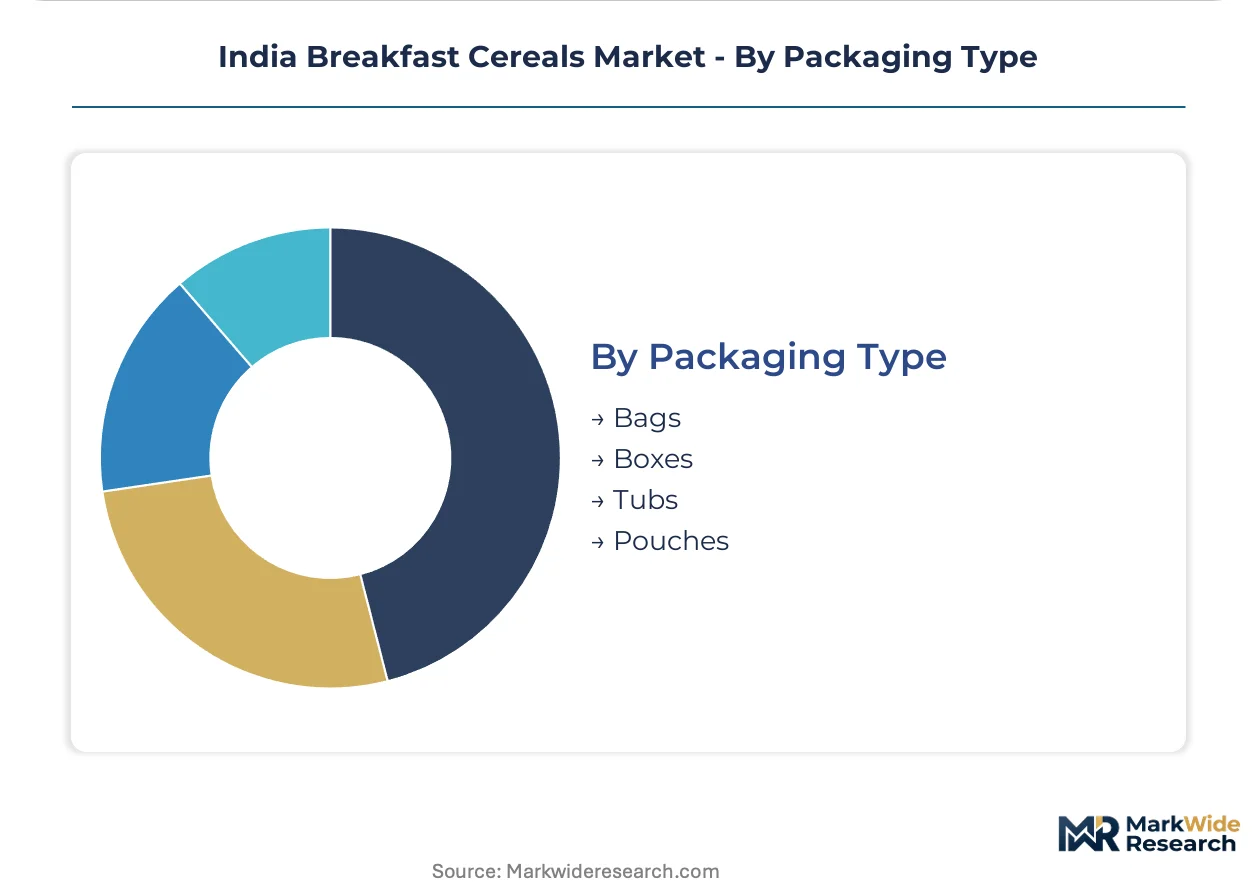
Packaging Type:
Packaging format selection reflects consumption frequency, household size, and shelf-life requirements across retail environments.
- Boxes:Paperboard cartons with inner liners dominate supermarket and hypermarket shelves, supporting brand billboard visibility and stacking efficiency. BIS migration to food-grade laminate structures with oxygen barrier properties is extending validation cycles for box-format suppliers.
- Pouches:Flexible laminate structures reduce material cost and shipping weight for e-commerce fulfillment. Single-serve and family-size variants adapt to quick-commerce impulse purchases and subscription replenishment models respectively.
- Bags:Bulk formats targeting price-sensitive household stock-up behavior in traditional retail.
- Tubs:Rigid containers for granola and premium muesli protecting fragile cluster integrity.
Boxes hold the established installed base. Pouches is expanding most quickly through digital channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI fortification mandates and PLI scheme incentives are anchoring manufacturing investments in western and southern states. Maharashtra and Karnataka retain demand concentration through working household density and modern retail penetration.
Maharashtra
Mumbai and Pune working professionals drive muesli and granola adoption through subscription replenishment models. FSSAI's micronutrient disclosure requirements accelerate label reformulation among Mumbai-based processors. Organized retail chains in Thane and Navi Mumbai dedicate expanded shelf space to fortified oat variants.
Karnataka
Bangalore's technology corridor residents exhibit the fastest clean-label cereal adoption in India. State-level food processing incentives complement central PLI scheme benefits for extrusion facility investments. Mysuru and Hubli-Dharwad emerging as secondary manufacturing nodes for millet-based formulations.
Gujarat
Surat and Ahmedabad processing facilities leverage port proximity for imported oat sourcing and export orientation. BIS packaging compliance timelines drive laminate structure upgrades across Gandhinagar industrial zones. Anand and Vadodara clusters attract grain-milling specialists expanding downstream into breakfast cereal production.
Tamil Nadu
Chennai supermarket expansion creates dedicated premium cereal sections for granola and millet innovations. State nutrition mission programs align with FSSAI fortification standards for school-adjacent retail. Coimbatore's engineering base supplies extrusion equipment to domestic manufacturers.
Delhi-NCR
Gurgaon and Noida dual-income households sustain volume for instant oats through quick-commerce impulse channels. FSSAI headquarters proximity accelerates compliance consultation access for label claim validation. Faridabad processing units serve as northern distribution hubs for e-commerce fulfillment networks.
India Breakfast Cereals Market Competitive Landscape
Capability concentration sits with domestic grain-heritage specialists; scale advantage sits with multinational FMCG incumbents. The market structures around three tiers: legacy milling companies with Punjab and Gujarat sourcing networks, diversified conglomerates leveraging consumer product distribution, and global brands occupying kirana shelf space through digitized reach. Strategic moves center on millet-based portfolio diversification and direct-to-consumer channel construction.
Within the heritage-milling tier, Bagrry's India Ltd exemplifies premium oat positioning sustained through Punjab grain-milling lineage. Tata Consumer Products anchors diversified conglomerate strategy through millet-based innovation portfolios. PepsiCo Inc occupies multinational scale advantage through kirana-store digitization programs. These three archetypes represent the competitive vectors reshaping shelf-space allocation and consumer trial conversion.
| Leading Market Players |
|---|
| Bagrry's India Ltd |
| Tata Consumer Products |
| Nestle SA |
| GlaxoSmithKline Consumer Healthcare Ltd |
| Patanjali Ayurved Ltd |
| PepsiCo Inc |
| Marico Ltd |
| Manna Foods |
| Kellanova |
| Others |
Supply & Pricing Matrix
The Delhi-Mumbai Industrial Corridor freight differentials compress margin structures for Gujarat-based processors while amplifying price spreads between Maharashtra supermarkets and Uttar Pradesh kirana networks. Grain procurement concentration in Punjab and Haryana feeds into this dynamic, as transport cost absorption separates premium oat formulations from economy corn flake variants. Downstream, quick-commerce fulfillment premiums in Bangalore and Hyderabad create distinct price bands that traditional retail cannot match.
Pricing Analysis
Price spreads between Mumbai supermarkets and Lucknow kirana stores reach three-to-one multiples for identical SKUs, reflecting distribution infrastructure gaps and cold-chain requirements. Three-tier pricing structure across premium, standard, and economy levels anchors on fortification compliance costs and packaging grade, with FSSAI-certified variants commanding shelf-space premiums. Cost compression in the corn flakes tier intensifies because private-label hypermarket competition erodes branded positioning. Kirana shoppers in tier-3 cities exhibit acute price sensitivity, while subscription-based professionals in Pune tolerate 40-60 percent premiums for convenience and personalization.
Supply Chain Analysis
Extended payment terms from organized retailers in Gujarat and Maharashtra strain working capital for upstream grain millers, forcing supply-chain finance facility adoption among mid-tier processors. Raw material sourcing draws from Canada and Australia for premium oat groats, domestic Punjab wheat for flaked products, and Ukrainian maize for puffed cereals. Single-source vulnerability concentrates in Canadian oat imports through Vancouver port routing. Distribution runs through a hybrid model: direct-store-delivery for supermarket chains, distributor-led stockist networks for kirana penetration, and platform-integrated fulfillment for quick-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's breakfast cereals sector is approaching a platform-economics inflection where quick-commerce integration and subscription APIs will determine which manufacturers capture household replenishment routines. The interoperability shift between kirana digitization and direct-to-consumer platforms is fragmenting traditional distributor control.
For Market Incumbents: Entrench millet-based formulation capabilities before FSSAI nutri-cereal labeling advantages dissipate, while securing exclusive quick-commerce slotting agreements in Bangalore and Hyderabad corridors. Bagrry's heritage positioning and Tata's conglomerate scale face erosion from platform-native brands with faster flavor iteration cycles. Backward integration into Punjab grain-milling assets preserves margin control against input volatility. For New Entrants and Emerging Players: Uttar Pradesh and Bihar's underpenetrated modern retail landscape represents the most penetrable entry point for direct-to-consumer subscription models bypassing kirana resistance. Millet-based clean-label variants targeting health-conscious households in tier-2 cities offer differentiation whitespace. A go-to-market angle anchored on FSSAI fortification compliance as a trust signal, delivered through WhatsApp-commerce onboarding, sidesteps incumbent shelf-space dominance. For Investors and Strategic Acquirers: Extrusion technology specialists with laboratory infrastructure and BIS-validated packaging lines present acquisition targets with defensible technical moats. Long-term viability hinges on whether portfolio companies can pivot from corn-flake commoditization toward muesli and granola premiumization. The signal to watch is quick-commerce platform private-label cereal launches, which would signal channel disintermediation acceleration and compress branded manufacturer valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Millet-Based Portfolio Extension | FSSAI nutri-cereal recognition opens formulation differentiation against oat-centric multinationals. |
| Quick-Commerce Channel Integration | Sub-30-minute fulfillment platforms capture impulse replenishment occasions in dense urban zones. |
| Direct-to-Consumer Subscription Launch | Personalized flavor rotations bypass kirana resistance in underpenetrated northern states. |
| Backward Integration into Grain Milling | Punjab sourcing assets stabilize input costs against monsoon-driven domestic volatility. |
| Blockchain Traceability Implementation | Lot-level documentation satisfies organized retailer mandates in Mumbai and Bangalore. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with category managers at modern retail chains, supply planners at grain-processing facilities, FSSAI compliance officers, and quick-commerce platform executives; alongside secondary validation through FSSAI fortification notifications, BIS packaging standards, PLI scheme disbursement records, and customs trade data for oat and wheat imports. Bottom-up SKU-level volume builds were cross-checked against top-down household penetration estimates from urban consumption surveys.
Forecast inputs considered product type segmentation across instant oats, muesli, granola, and corn flakes; distribution channel dynamics spanning supermarkets, hypermarkets, online retail, and convenience stores; and end-user targeting across children, adults, health-conscious individuals, and fitness enthusiasts. CAGRs were derived from trend-line extrapolation adjusted for regulatory compliance timelines and modern retail expansion trajectories. Industry-specific inputs included FSSAI added-sugar disclosure implementation schedules and PLI scheme capital subsidy absorption rates.
Practitioners should monitor FSSAI threshold revisions, monsoon irregularity patterns, and quick-commerce platform consolidation for early signals of forecast deviation. The analysis reflects assumptions regarding sustained urban dual-income household growth and modern retail shelf-space expansion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Dried Honey Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
US Canned Foods Market
Packaged Foods
Reduced Salt Packaged Foods Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Canned Soup Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Canned Tropical Fruit Market