
 United States Online Grocery Market | 2026-2036
United States Online Grocery Market Size, Share, and Industry Trends Forecast 2026-2036
United States Online Grocery Market Intelligence
Automated micro-fulfillment center technology is reconfiguring last-mile economics for perishable goods. Amazon leverages its robotics-heavy fulfillment network to compress picking times for fresh produce. Walmart anchors its competitive posture through a hybrid model combining supercenter inventory with dedicated dark stores. Kroger specializes in automated warehouse partnerships that reduce delivery-zone coverage costs.
United States online grocery comprises digitally ordered food and household consumables fulfilled through warehouse picking, store-based assembly, or dedicated dark facilities, with cold-chain integrity maintained via temperature-controlled totes and refrigerated vehicles throughout the delivery window. The category serves commercial purposes spanning household replenishment, meal-planning convenience, and accessibility for mobility-limited populations. Same-day delivery captures the highest customer lifetime value due to impulse-basket expansion and premium fee tolerance, while subscription models lock in predictable demand density that improves route economics. Product category segmentation shows produce and dairy commanding disproportionate fulfillment investment because of spoilage risk and narrow delivery windows.
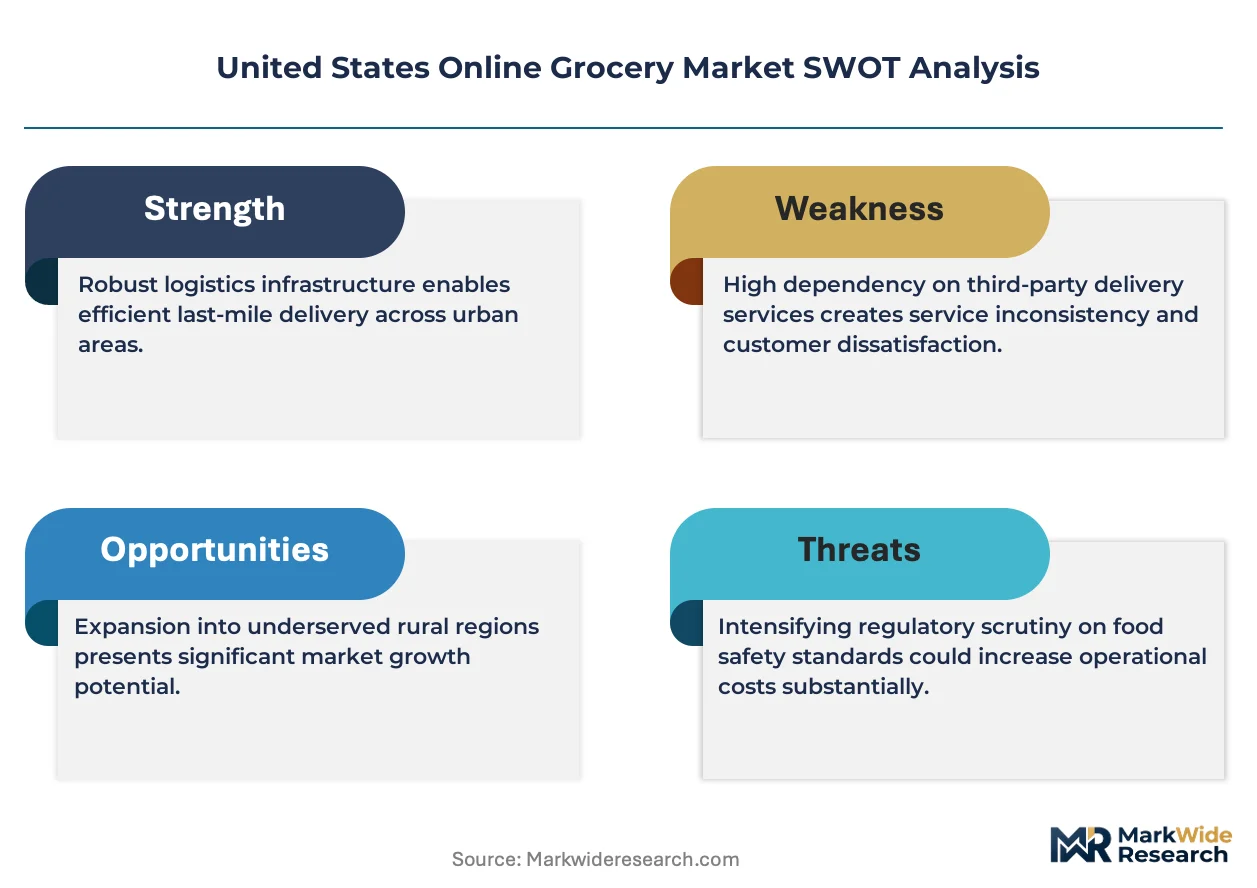
The USDA Food and Nutrition Service governs SNAP online eligibility, determining which retailers and platforms can serve low-income households. FDA food safety rules on traceability and temperature monitoring shape warehouse design and delivery packaging standards. State-level cottage food laws and alcohol shipping regulations fragment market access for certain product expansions. Stakeholders must monitor SNAP pilot expansion decisions and state-level delivery fee regulations as these will determine whether online grocery achieves genuine mass-market penetration or remains concentrated among affluent suburban households.
Market Dynamics
Automated micro-fulfillment centers are compressing last-mile delivery costs for temperature-sensitive goods, forcing traditional supermarket chains to retrofit legacy warehouses with robotics or surrender suburban density to platform operators with purpose-built cold-chain infrastructure.
Growth Catalysts
- USDA SNAP Online Purchasing Pilot:The program's state-by-state expansion unlocks digital grocery access for low-income households previously excluded from e-commerce participation.
- Dark store proliferation:Dedicated fulfillment facilities in dense suburban corridors enable 30-minute delivery windows that capture impulse purchases and premium fee tolerance.
- Working parents with children under twelve:This household segment exhibits the steepest adoption curve as time-constrained meal planning drives subscription model enrollment.
Market Restraints
- Perishable spoilage costs:Narrow delivery windows for produce and dairy compress route density economics and inflate labor scheduling complexity.
- State alcohol shipping regulations:Fragmented compliance requirements block basket expansion into high-margin beverage categories across multiple jurisdictions.
- Refrigerated last-mile infrastructure:Limited temperature-controlled vehicle availability in exurban zones constrains serviceable market geography.
Strategic Opportunities
- Meal-kit convergence:Integration of pre-portioned ingredient bundles with standard grocery SKUs captures weekly meal-planning spend from separate subscription services.
- Mobility-limited populations:Partnerships with Medicare Advantage plans and disability services organizations unlock addressable demand beyond working-age households.
- Texas-Arizona-Georgia suburban corridors:Population density growth in these Sun Belt metro peripheries outpaces incumbent fulfillment network coverage.
Industry Challenges
- Legacy warehouse management system integration:Supermarket operators struggle to synchronize real-time inventory visibility between store shelves and digital storefronts.
- Cold-chain certification timelines:FDA food safety traceability requirements demand multi-year warehouse retrofit investments that strain capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Online Grocery Market |
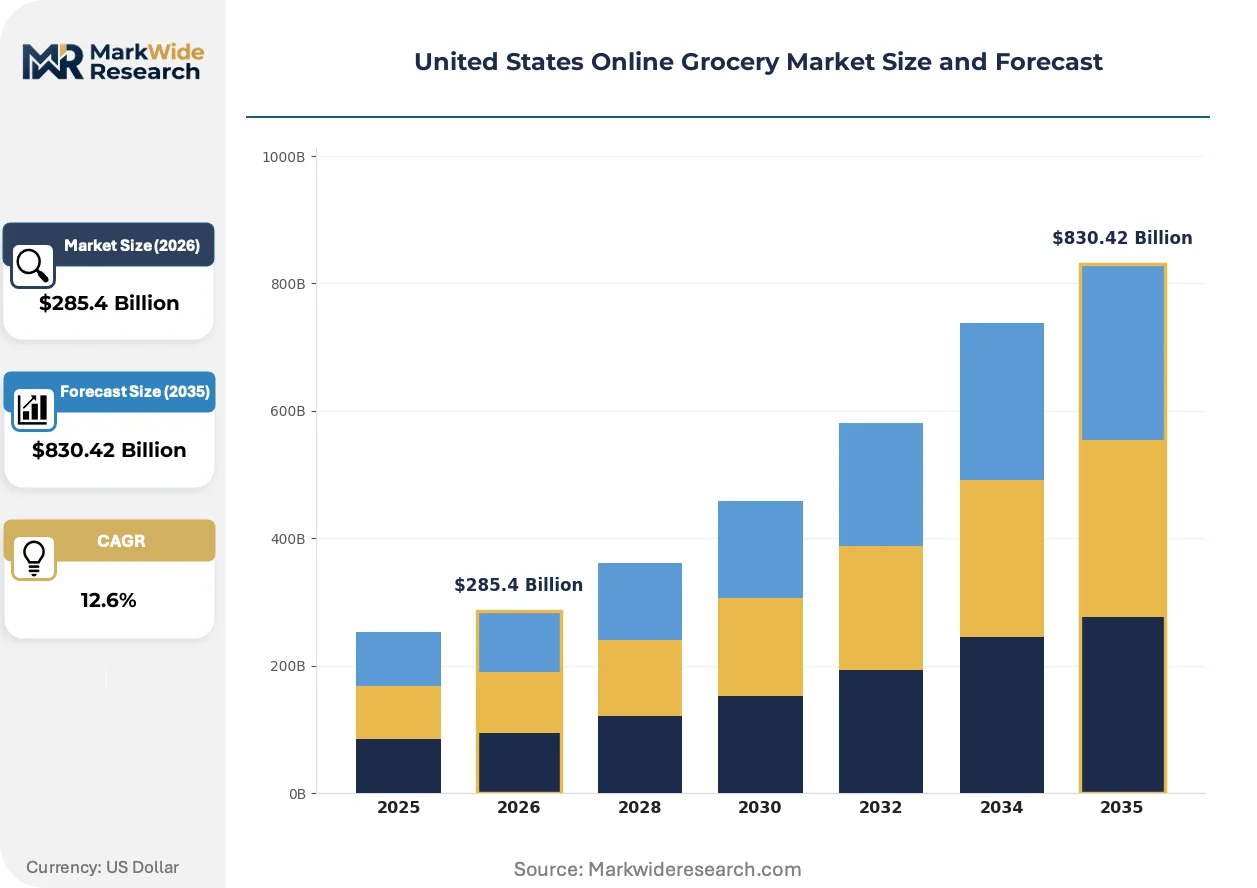
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $830.42 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Households, Singles, Families, Seniors Product Category: Fruits, Vegetables, Dairy, Snacks Delivery Model: Same-Day Delivery, Scheduled Delivery, In-Store Pickup, Subscription Order Size: Small Orders, Medium Orders, Large Orders, Bulk Orders |
| Companies Covered | Walgreens, Ahold Delhaize, Amazon, Costco, Target, Walmart, CVS, Albertsons Companies, Kroger, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Online Grocery Market Strategic Shifts & Innovations
Robotics and artificial intelligence are reconfiguring fulfillment economics while regulatory frameworks and household consumption patterns simultaneously reshape competitive entry points.
Automated micro-fulfillment technology is collapsing the cost gap between centralized warehouse picking and store-based assembly. Grocery retailers in Dallas and Phoenix suburbs are deploying vertical storage retrieval systems that compress picking labor hours by 60%. This automation shift is collapsing the historical advantage of supercenter inventory proximity for same-day delivery.
The USDA Food and Nutrition Service continues expanding SNAP online eligibility to additional retailers and platforms. This policy extension broadens addressable demand into price-sensitive segments previously served only by in-store shopping. Low-income households in newly eligible states are migrating basket share to digital channels at rates exceeding initial program projections.
Subscription-based replenishment models are displacing episodic ordering among suburban households with predictable consumption patterns. These programs lock in route density that improves driver utilization and reduces per-delivery cost. Working parents in Atlanta's northern suburbs exhibit the highest conversion rates from trial to annual subscription commitments.
United States Online Grocery Market Segmentation
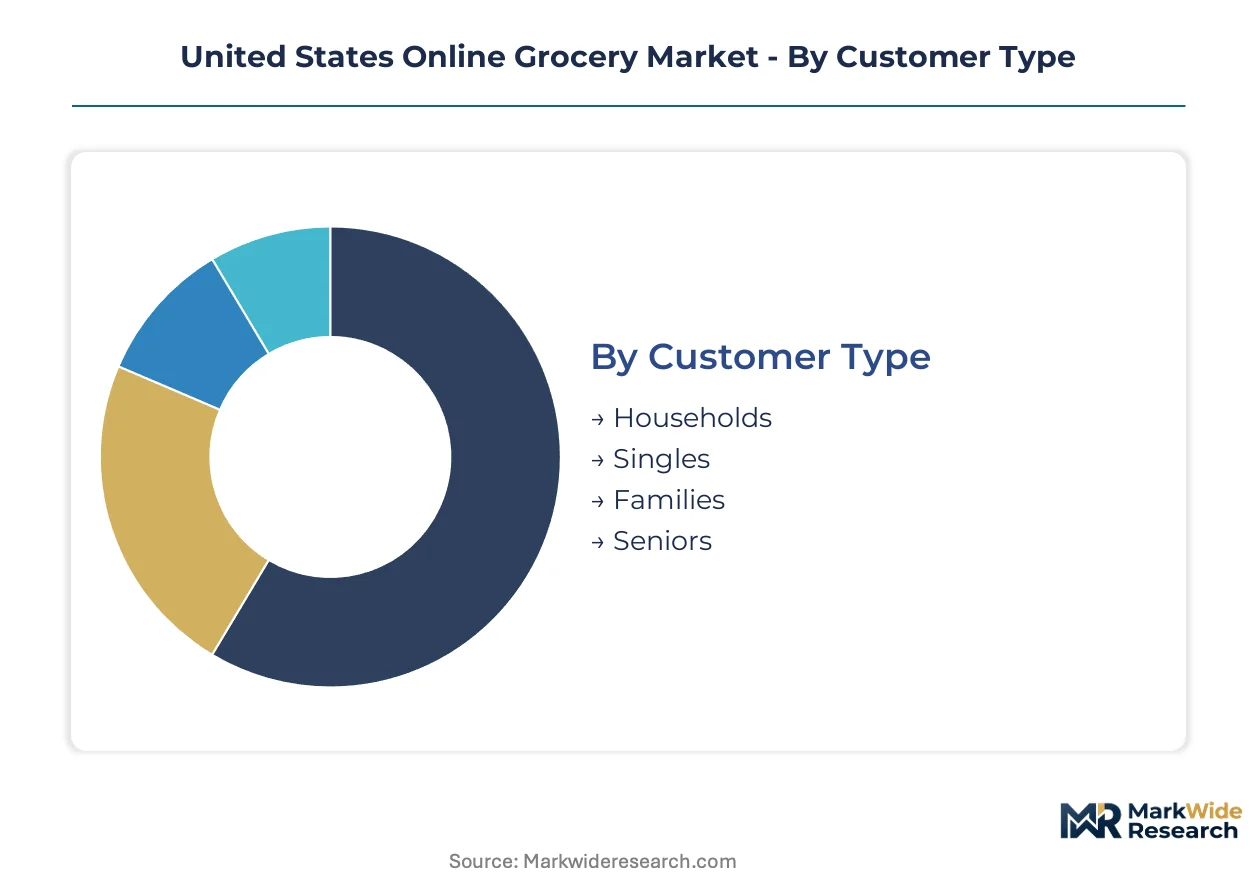
Segmentation in the United States online grocery market reveals distinct fulfillment economics and purchasing behaviors across household structures, product perishability, delivery urgency, and basket composition. Each dimension carries implications for cold-chain infrastructure investment, route density optimization, and platform monetization strategies.
Customer Type:
The maturity spectrum spans digitally native suburban families to emerging senior adoption, with household composition dictating subscription propensity and fee tolerance thresholds.
- Families:Households with children under twelve generate the highest order frequency and largest basket sizes. Working parents in Dallas and Atlanta suburbs convert to annual subscriptions at rates exceeding other segments due to time-constrained meal planning demands.
- Singles:Solo households concentrate in dense urban cores and exhibit preference for small-order, same-day delivery with premium fee acceptance. This segment drives dark store proliferation in metropolitan peripheries where apartment density supports 30-minute fulfillment windows.
- Seniors:Mobility-limited older adults represent emerging digital adoption through Medicare Advantage partnerships and accessibility-focused platform interfaces. USDA SNAP Online Purchasing Pilot expansion unlocks this price-sensitive cohort in newly eligible states.
- Households:General household category captures multi-generational and non-family residential units with variable consumption patterns and moderate subscription conversion rates.
Families retain volume leadership; seniors hold the steepest expansion curve.
Product Category:
Cost tier differentiation separates high-spoilage fresh categories from shelf-stable alternatives, with fulfillment investment intensity scaling directly with temperature sensitivity and delivery window compression.
- Dairy:Refrigerated milk, cheese, and yogurt demand continuous cold-chain integrity from warehouse to doorstep. Narrow delivery windows compress route economics and elevate labor scheduling complexity in Phoenix and Dallas corridors where summer heat intensifies spoilage risk.
- Vegetables:Leafy greens and delicate produce require temperature-controlled totes and rapid fulfillment cycles to maintain crispness. Automated micro-fulfillment centers deploy specialized vertical storage retrieval systems to reduce handling damage and picking labor hours.
- Fruits:Bananas, berries, and citrus categories face seasonal supply volatility and bruising sensitivity during last-mile transport. Regional sourcing partnerships with Texas and Arizona growers shorten farm-to-door timelines.
- Snacks:Shelf-stable packaged goods carry minimal spoilage risk and tolerate extended delivery windows, enabling batch consolidation and improved driver utilization across subscription routes.
Dairy commands the highest fulfillment cost per unit; vegetables are climbing the fastest in automation capital allocation.
Delivery Model:
Application-based segmentation distinguishes immediate gratification from planned replenishment, with each model imposing distinct requirements on inventory positioning, labor deployment, and fleet configuration.
- Same-Day Delivery:Orders fulfilled within hours capture impulse basket expansion and premium fee tolerance. Dark stores in Atlanta's northern suburbs enable 30-minute windows that displace convenience store trips for top-up purchases.
- Subscription:Recurring weekly or bi-weekly deliveries lock in predictable demand density that improves route economics and driver utilization. Working parents exhibit highest annual commitment rates following trial conversion.
- Scheduled Delivery:Customer-selected time slots balance convenience with operational predictability, allowing platforms to batch orders into efficient delivery waves while accommodating household presence requirements.
- In-Store Pickup:Curbside collection from supercenter inventory eliminates last-mile cost but sacrifices the convenience premium that drives digital adoption among time-constrained segments.
Subscription retains volume leadership; same-day delivery holds the steepest expansion curve.
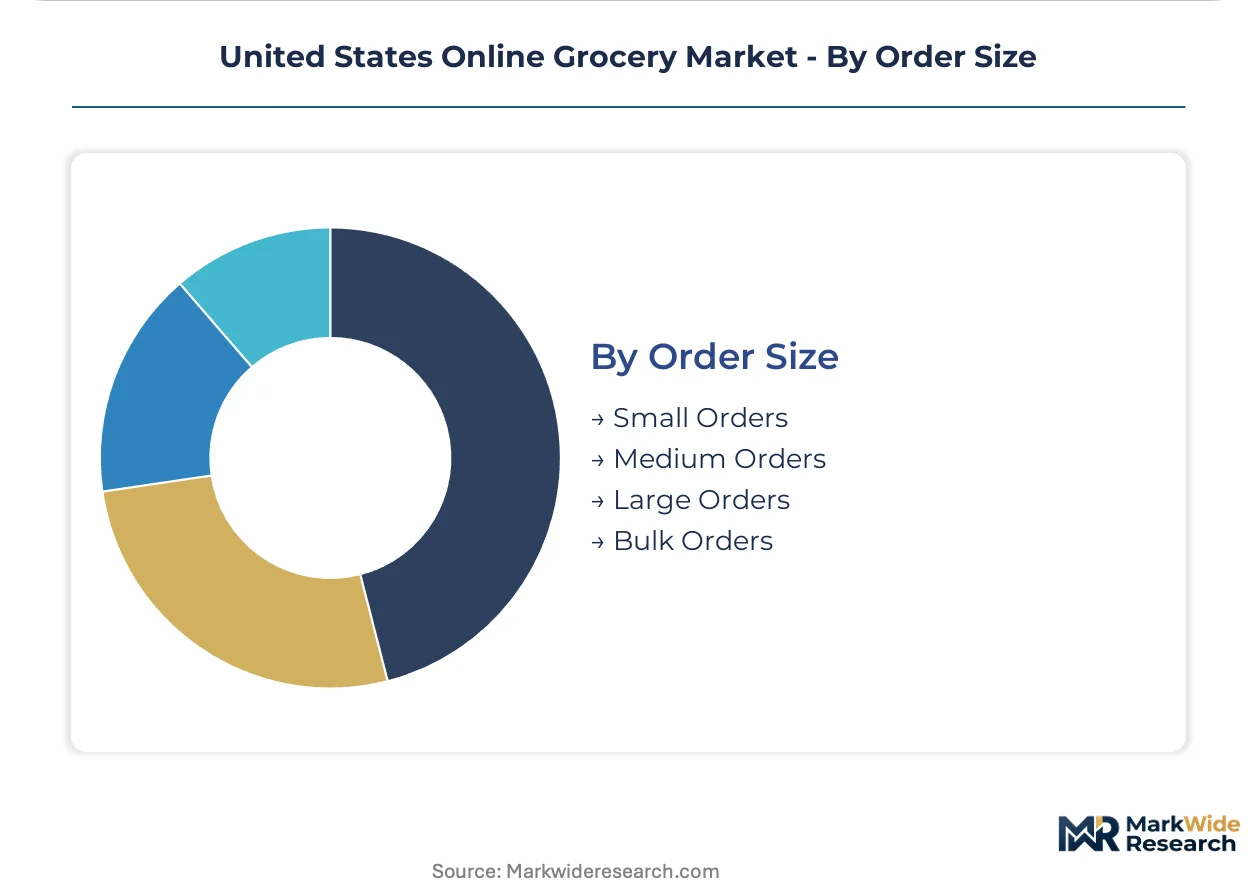
Order Size:
Volume-based segmentation correlates directly with route density economics, with large baskets subsidizing small-order fulfillment through minimum thresholds and tiered fee structures.
- Large Orders:Weekly replenishment baskets exceeding fifty items justify delivery fee waivers and anchor subscription program economics. Family households in suburban Phoenix generate disproportionate share of this segment.
- Bulk Orders:Pantry-loading purchases of non-perishable staples and household consumables reduce per-unit fulfillment cost and extend delivery window flexibility. This segment concentrates in warehouse club adjacent markets.
- Medium Orders:Mid-size baskets capture routine replenishment without the planning horizon of large weekly shops, representing the conversion battleground between episodic and subscription purchasing.
- Small Orders:Top-up and impulse purchases carry elevated per-unit delivery cost and drive platform investment in rapid fulfillment infrastructure to capture convenience-oriented spend.
Large orders retain volume leadership; small orders are gaining share fastest through dark store network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas exports fulfillment infrastructure expertise to Arizona and Georgia as Sun Belt population migration accelerates digital grocery penetration. Interstate cold-chain logistics networks now prioritize Dallas-Phoenix-Atlanta corridors over traditional Northeast density.
Texas
Dallas-Fort Worth suburban sprawl generates the densest dark store deployment in the nation. USDA SNAP Online Purchasing Pilot eligibility expansion unlocks low-income household demand in Houston's peripheral counties. Automated micro-fulfillment centers in Plano and Frisco compress picking labor hours through vertical storage retrieval systems.
Arizona
Phoenix metro population growth outpaces incumbent grocery fulfillment coverage. Summer heat intensity elevates refrigerated last-mile infrastructure requirements beyond national averages. Tempe and Scottsdale corridors host the highest concentration of 30-minute delivery dark stores serving working parent households.
Georgia
Atlanta's northern suburbs exhibit the steepest subscription model conversion rates among working parents with children under twelve. State alcohol shipping regulations fragment beverage category expansion across county jurisdictions. Alpharetta and Sandy Springs anchor the Southeast's most automated grocery fulfillment cluster.
California
Los Angeles and San Francisco Bay Area markets concentrate demand for same-day delivery among single-person urban households. FDA food safety traceability requirements drive multi-year warehouse retrofit investments in Central Valley distribution hubs. Sacramento's regulatory environment shapes statewide compliance standards for temperature-controlled delivery vehicles.
New York
New York City density supports small-order, rapid fulfillment economics unmatched in exurban zones. State-level cottage food laws constrain marketplace expansion for artisanal producer categories. Buffalo and Rochester corridors test hybrid supercenter-dark store models for Rust Belt demographic profiles.
United States Online Grocery Market Key Industry Players
Channel-controlling players compete with product-specialist players across fulfillment archetypes that separate inventory-heavy operators from platform intermediaries. The market structure consolidates around three strategic tiers: national supercenter chains with hybrid fulfillment networks, dedicated e-commerce platforms with robotics-heavy infrastructure, and regional grocery cooperatives with automated warehouse partnerships. Dominant competitive moves include dark store proliferation in dense suburban corridors and subscription model deployment to lock in predictable demand density.
Within the supercenter-dominant tier, Walmart anchors scale-driven fulfillment economics through hybrid inventory positioning. Amazon exemplifies robotics-first automation with its vertically integrated warehouse network. Kroger occupies a specialist position through automated warehouse partnerships that reduce delivery-zone coverage costs in Sun Belt expansion markets.
| Leading Market Players |
|---|
| Walgreens |
| Ahold Delhaize |
| Amazon |
| Costco |
| Target |
| Walmart |
| CVS |
| Albertsons Companies |
| Kroger |
| Others |
Cost & Logistics Intelligence
Dark store undercapacity in Atlanta's northern suburbs compresses delivery slot premiums while elevating subscription commitment rates among working parents. This utilization imbalance simultaneously pressures platform operators to expand refrigerated fleet capacity and rewards early movers with route density advantages that subsidize per-unit fulfillment economics.
Pricing Analysis
Legacy store-pick pricing models face compression from next-generation automated micro-fulfillment centers that collapse picking labor costs by sixty percent. Three-tier pricing structure across premium same-day, standard next-day, and economy scheduled delivery separates fee tolerance thresholds across household segments. Pricing pressure stems from perishable spoilage costs that narrow delivery windows and inflate cold-chain infrastructure requirements. SNAP-eligible households exhibit highest price sensitivity, while working parents with children under twelve demonstrate lowest fee resistance for convenience-tier services.
Supply Chain Analysis
Extended payment terms from California-based cold-chain equipment suppliers strain working capital for regional grocery cooperatives expanding automated warehouse partnerships. Geographic supply concentration centers on Texas, Arizona, and Georgia as Sun Belt population migration accelerates fulfillment infrastructure deployment. Raw material dependencies include refrigerated vehicle chassis, vertical storage retrieval systems, and temperature-controlled totes. Single-source vulnerability in automated robotics components creates procurement risk. Distribution runs through hybrid supercenter-dark store networks that balance inventory proximity with dedicated fulfillment capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as USDA SNAP Online Purchasing Pilot expansion normalizes low-income household digital adoption. Working parent time constraints sustain subscription model enrollment through economic fluctuations.
For Market Incumbents: Insulate route density advantages by accelerating dark store deployment in Dallas-Phoenix-Atlanta corridors before competitor saturation. Prioritize backward integration into automated micro-fulfillment technology to offset labor cost inflation. Lock in multi-year refrigerated fleet leases to secure capacity ahead of infrastructure constraints. For New Entrants and Emerging Players: Medicare Advantage partnership channels for mobility-limited seniors represent the most penetrable entry point with lowest incumbent saturation. Texas-Arizona-Georgia suburban corridors with SNAP pilot expansion offer addressable demand beyond affluent household concentration. Pursue white-label fulfillment partnerships with regional grocery cooperatives to bypass capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated warehouse technology deployment as robotics-heavy infrastructure replaces legacy store-pick models. Acquisition targets should profile regional grocery cooperatives with established automated partnerships but limited geographic coverage. Monitor SNAP pilot state expansion announcements as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Dark Store Network Expansion | Dedicated fulfillment facilities in Dallas and Phoenix suburbs enable 30-minute delivery windows that capture impulse purchases. |
| Automated Micro-Fulfillment Partnership | Vertical storage retrieval systems in Frisco and Alpharetta compress picking labor hours by sixty percent. |
| SNAP Online Eligibility Expansion | USDA pilot program unlocks price-sensitive household demand in Houston peripheral counties and emerging state markets. |
| Refrigerated Fleet Capacity Addition | Temperature-controlled vehicle procurement in Arizona addresses summer heat intensity that elevates spoilage risk. |
| Subscription Model Deployment | Recurring delivery commitments from Atlanta working parents lock in route density that improves driver utilization. |
Research Approach
Findings reconcile primary fieldwork against secondary review of USDA program documentation, FDA food safety filings, and refrigerated logistics trade data. Interviews with grocery operations executives, dark store facility managers, SNAP program administrators, and cold-chain equipment procurement leads informed demand-side validation. SEC filings from publicly traded supermarket operators and customs records for refrigerated vehicle imports provided supply-side triangulation. Bottom-up route density modeling and top-down addressable household estimation were cross-referenced.
Forecast inputs include household composition shifts, SNAP eligibility expansion timelines, and automation capital deployment cycles across the projection horizon. Segmentation dimensions modeled encompass customer type, product category perishability, delivery model urgency, and order size volume. CAGRs were derived from historical adoption curve analysis and infrastructure capacity constraints. Cold-chain certification timelines and state alcohol shipping regulatory fragmentation were incorporated as industry-specific forecast inputs.
Practitioners should monitor SNAP pilot expansion decisions, automated warehouse technology cost curves, and refrigerated fleet capacity constraints for early signals. Forecasts reflect assumptions regarding working parent time scarcity persistence and perishable spoilage cost trajectories. Macroeconomic deviation affecting household discretionary spending, regulatory shifts in food safety traceability requirements, or technological breakthroughs in last-mile automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Canned Mushroom Market
Packaged Foods
Japan Packaged Food Products Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Non-Fried Instant Noodles Market
Packaged Foods
Canned Goods Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Global Packed Food Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
North America Packaged Salad Market