
 CBD-Infused Ice Cream Market | 2026-2036
CBD-Infused Ice Cream Market Size, Share, and Industry Trends Forecast 2026-2036
CBD-Infused Ice Cream Market Analytics
Food science talent with dual expertise in cannabinoid stability and frozen dessert formulation is collapsing across North American manufacturing hubs. Ben & Jerry's leverages its parent company's dairy supply chain to anchor production scale in Vermont. Kiva Confections specializes in precision-dosed edibles and extends its extraction expertise into frozen formats. Sweet Leaf dominates dispensary distribution networks across multiple states.
CBD-infused ice cream combines hemp-derived cannabidiol with conventional frozen dessert bases, typically incorporating lipid-based emulsification to improve cannabinoid bioavailability in cold matrices. The product serves consumers seeking functional relaxation benefits through familiar food formats rather than tinctures or capsules. Dairy-based formulations occupy the largest revenue share due to fat solubility advantages for cannabinoid integration, while vegan alternatives represent the fastest-expanding segment as oat and coconut milk bases improve emulsion stability. Full-spectrum ingredient sourcing commands premium positioning, though isolate formats attract mainstream retailers wary of THC trace compliance.
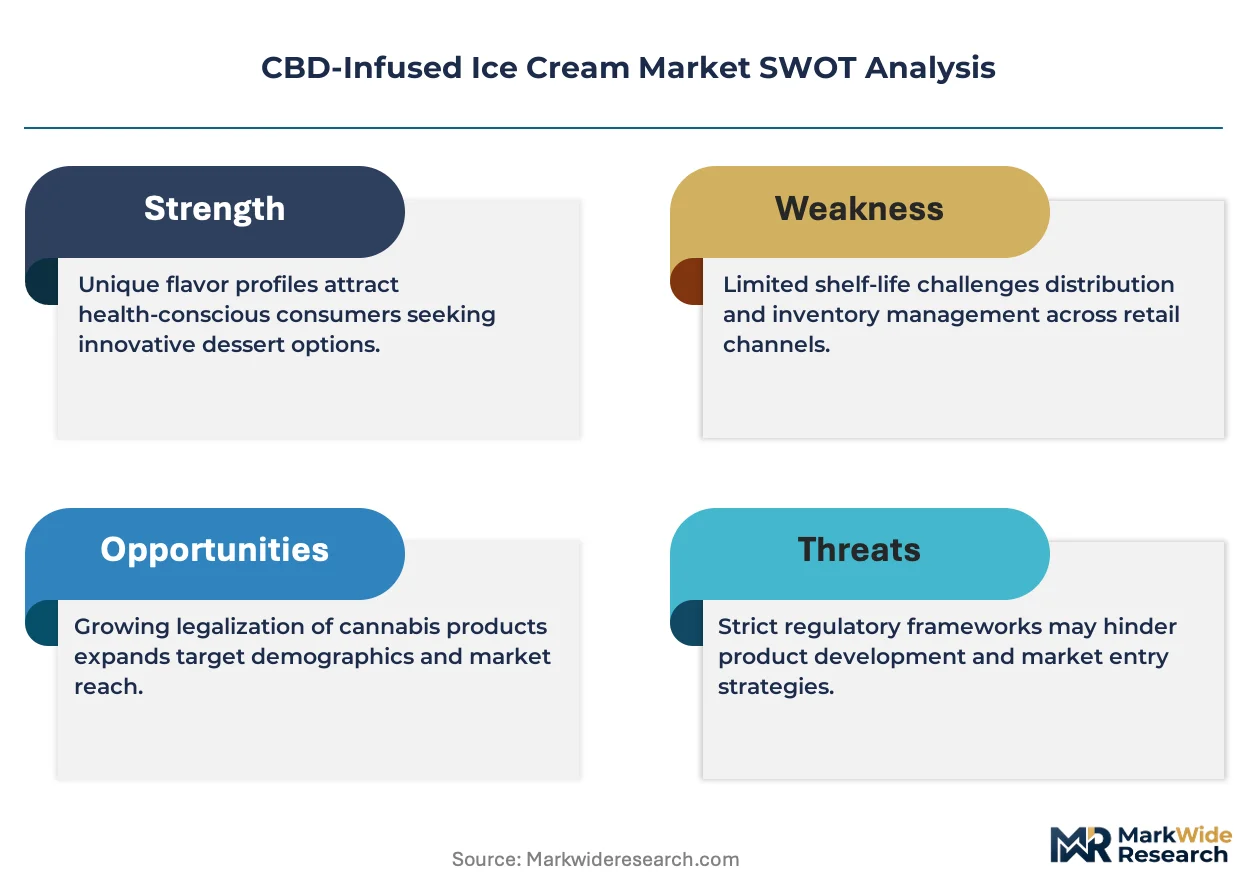
FDA prohibition on CBD as a food additive under the Federal Food, Drug, and Cosmetic Act conflicts with state-level permissiveness, creating jurisdictional fragmentation that shapes distribution strategy. The USDA's hemp cultivation rules and state cannabis boards collectively determine supply chain legality from farm to freezer. Stakeholders must monitor federal rescheduling deliberations and corresponding state alignment measures to anticipate channel expansion or contraction.
Market Dynamics
The FDA's prohibition on CBD as a food additive under the Federal Food, Drug, and Cosmetic Act creates a fundamental jurisdictional fracture that forces manufacturers to navigate conflicting federal and state authorities simultaneously.
Growth Catalysts
- State Cannabis Frameworks:California, Colorado, and Oregon have established permissive regulatory environments that allow licensed producers to manufacture and distribute hemp-derived frozen desserts through approved retail channels.
- Lipid-Based Emulsification:Advances in cold-matrix cannabinoid stabilization enable higher bioavailability in frozen formats, expanding the addressable consumer base beyond tincture users.
- Wellness Consumer Migration:Functional food seekers in specialty café and dessert shop channels are adopting cannabinoid-infused alternatives to alcohol and pharmaceuticals for relaxation.
Market Restraints
- FDA Additive Prohibition:The federal ban on CBD in interstate commerce blocks conventional grocery and mass retail distribution, constraining revenue scalability.
- Hemp Cultivation Volatility:USDA hemp rules and state agricultural inspections create input supply uncertainty from farm-level biomass through extraction.
- THC Trace Compliance:Full-spectrum ingredient sourcing carries contamination risk that triggers state cannabis board enforcement actions against non-compliant batches.
Strategic Opportunities
- Federal Rescheduling Pathway:DEA deliberations on cannabis reclassification could trigger FDA alignment measures that open conventional food retail channels.
- Vegan Base Convergence:Oat and coconut milk emulsion technologies are achieving parity with dairy for cannabinoid solubility, unlocking plant-based consumer segments.
- Direct-to-Consumer Subscription:Chilled logistics networks and state-compliant e-commerce platforms enable recurring revenue models outside dispensary dependence.
Industry Challenges
- Cannabinoid Stability Expertise:Food science programs lack integrated training in frozen dessert formulation and phytocannabinoid chemistry, creating recruitment bottlenecks for manufacturing scale-up.
- Batch-to-Batch Dosing Precision:Homogenization equipment capable of maintaining CBD uniformity across continuous freezer operations requires capital investment beyond conventional dairy infrastructure.
- Multi-Jurisdiction Labeling:State cannabis boards impose conflicting THC threshold declarations and health claim restrictions that complicate packaging standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD-Infused Ice Cream Market |
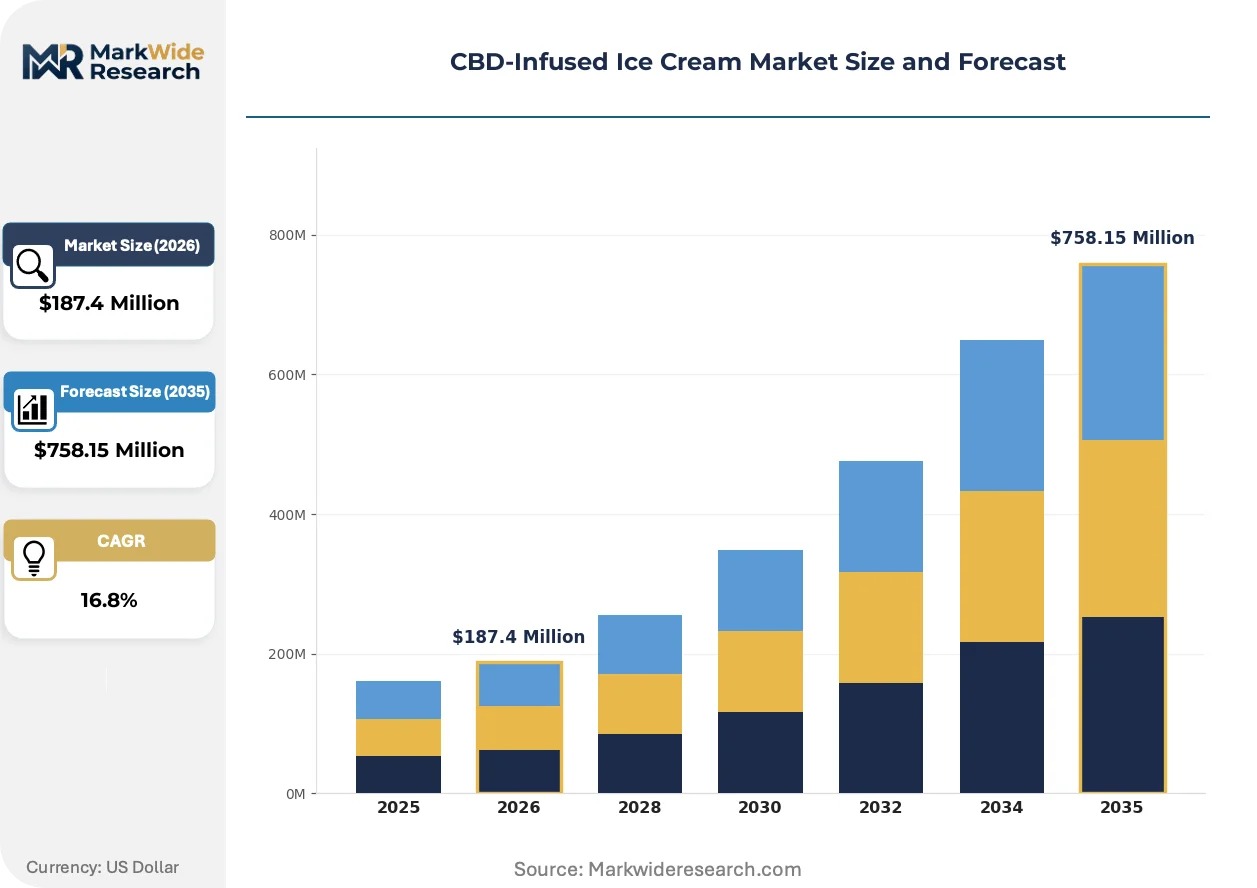
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegan, Dairy-Based, Low-Calorie, Organic Ingredient Source: Hemp Extract, Full-Spectrum, Broad-Spectrum, Isolate Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Cafés Target Demographic: Health-Conscious Consumers, Millennials, Athletes, Retirees |
| Companies Covered | Sweet Leaf, Kiva Confections, Ben & Jerry's, Hemp Haven, Dairy Farmers of America, Euphoria Ice Cream, Hemp Ice Cream, Emack & Bolio's, Canna Creamery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD-Infused Ice Cream Market Evolving Landscape
Formulation science and distribution infrastructure are converging to reshape how cannabinoid-infused frozen desserts reach consumers. Three developments are altering competitive positioning.
Nanoemulsion technology is decomposing the traditional lipid-delivery paradigm for cannabinoids in frozen matrices. Precision-dose edible manufacturers are adopting water-compatible CBD particles to improve cold-temperature stability and onset predictability. This shift is compressing the performance gap between infused ice cream and pharmaceutical-grade edible formats.
The USDA's hemp cultivation rules are tightening traceability requirements from seed-to-sale, forcing extraction partners to document chain-of-custody for every biomass lot. State cannabis boards are mirroring these standards for THC compliance. Small-batch producers in Vermont and Oregon are responding by integrating backward into licensed hemp farming to secure compliant supply.
Specialty cafés are displacing dispensaries as the primary trial channel for first-time CBD dessert consumers. Wellness-focused dessert shops in Los Angeles and Denver are building destination traffic through experiential tasting formats. This channel rotation is most visible in coastal metropolitan markets where stigma reduction has outpaced regulatory clarity.
CBD-Infused Ice Cream Market Segmentation
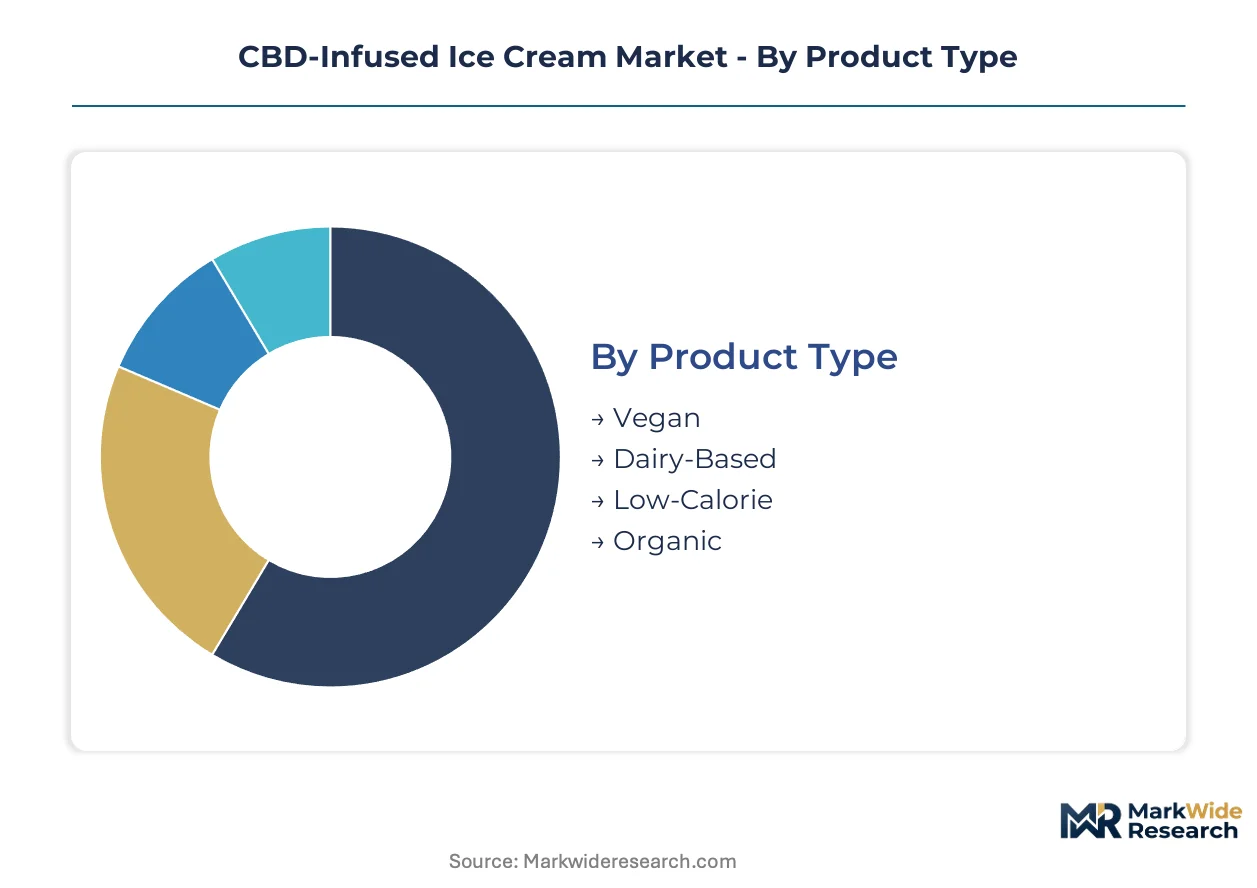
Segmentation in the CBD-infused ice cream market determines regulatory compliance pathways and channel accessibility. Product formulation choices directly trigger FDA jurisdiction or state-level permissiveness. Distribution channel selection separates mass-market ambition from controlled dispensary dependence.
Product Type:
FDA food additive prohibitions apply uniformly across all formulations, though dairy bases benefit from established GRAS designations for conventional ingredients that ease co-manufacturing negotiations.
- Dairy-Based:High-fat content optimizes cannabinoid bioavailability through lipid solubility. Demand concentrates in California and Colorado dispensaries where established dairy supply chains integrate with licensed extraction facilities. State cannabis frameworks in these jurisdictions permit the fat-based emulsion systems that conventional freezers already handle.
- Vegan:Oat and coconut milk matrices now achieve emulsion stability parity with dairy through modified lecithin systems. Specialty cafés in Los Angeles and Denver are driving trial adoption among wellness-focused consumers seeking plant-based functional desserts. This segment is expanding most quickly as stigma reduction outpaces regulatory clarity.
- Low-Calorie:Reduced-fat bases compromise cannabinoid integration efficiency, requiring nanoemulsion supplementation. Manufacturers target calorie-conscious millennials through online subscription channels that bypass retail shelf-space constraints.
- Organic:USDA organic certification intersects with state hemp cultivation rules to create dual compliance documentation requirements. Premium positioning attracts retirees in Oregon's mature cannabis markets.
Dairy-based formulations handle the majority of throughput; vegan alternatives are gaining share fastest.
Ingredient Source:
Cost tier differentiation separates pharmaceutical-grade precision from commodity hemp processing. Extraction method determines THC trace risk and corresponding state board enforcement exposure.
- Isolate:Crystalline CBD eliminates THC contamination risk entirely. Mass retailers in permissive states prefer this format for liability insulation. Isolate commands premium pricing but enables interstate commerce through hemp-derived legal clarity.
- Full-Spectrum:Whole-plant extraction retains minor cannabinoids and terpenes for entourage effect claims. Dispensary channels in Colorado and Oregon absorb the batch-to-batch testing burden that full-spectrum sourcing demands. Athletes seeking functional recovery benefits drive demand concentration here.
- Broad-Spectrum:THC-free whole-plant formulation balances entourage claims with compliance safety. Health-conscious consumers in California's wellness retail sector favor this middle-tier positioning.
- Hemp Extract:Crude or minimally processed biomass extract serves budget-tier private label production. Supermarket channel entry depends on this lowest-cost input category.
Isolate captures the highest margin tier; full-spectrum shows the steepest expansion trajectory.
Distribution Channel:
Customer type and purchase context determine channel viability under fractured federal-state jurisdiction. Direct relationships reduce compliance intermediation costs.
- Specialty Stores:Licensed dispensaries and wellness boutiques provide controlled environments for staff-educated selling. State cannabis boards regulate these channels explicitly, creating operational predictability for manufacturers.
- Cafés:Experiential tasting formats in metropolitan markets reduce consumer hesitation through immediate consumption context. Los Angeles and Denver operators build destination traffic around CBD dessert menus.
- Online Retail:State-compliant e-commerce platforms enable direct-to-consumer subscription models that bypass dispensary margin stacking. Chilled logistics networks serve health-conscious consumers seeking recurring delivery convenience.
- Supermarkets:Conventional grocery remains blocked by FDA interstate commerce prohibitions. Future channel opening depends on federal rescheduling alignment.
Specialty stores handle current volume concentration; cafés are climbing the fastest on share.
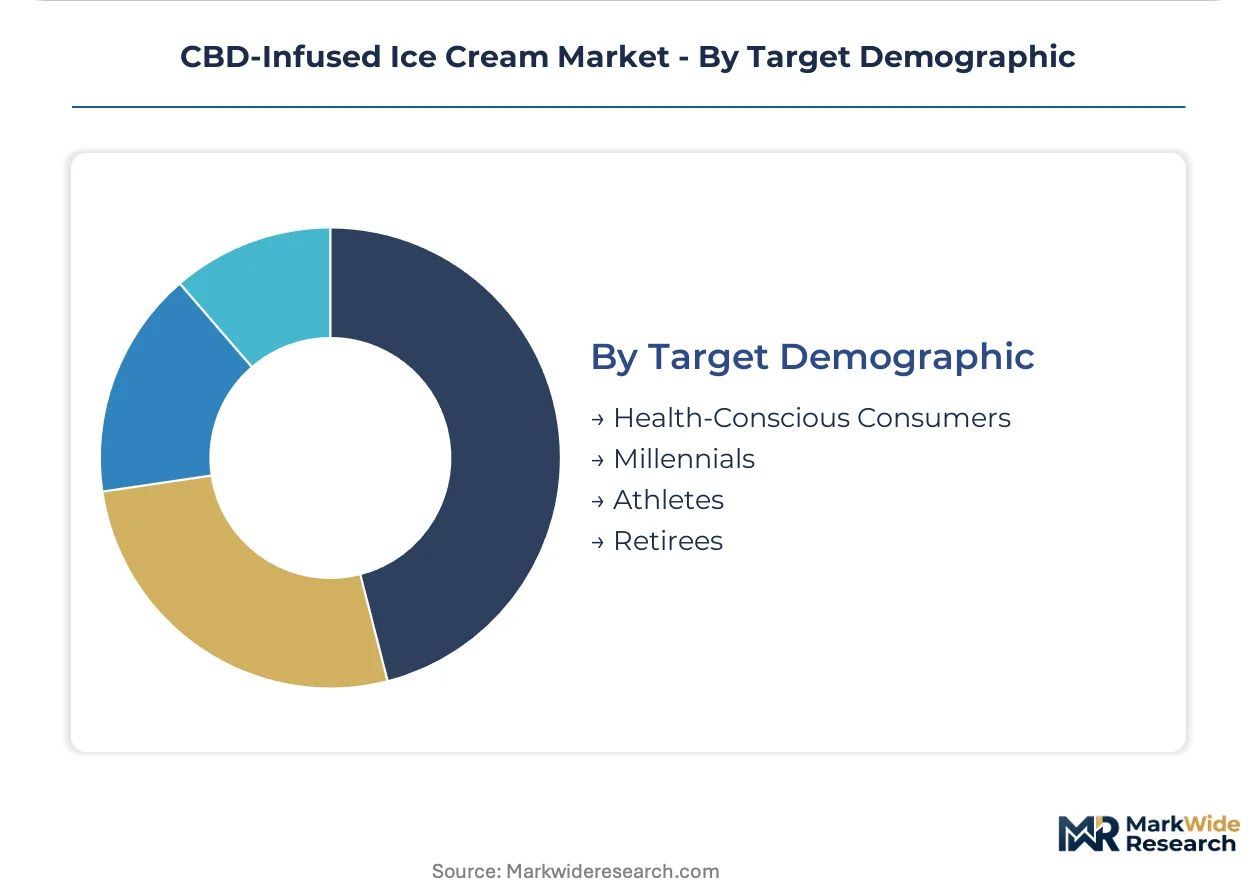
Target Demographic:
Application context and consumption occasion separate pharmaceutical-adjacent use from recreational wellness adoption. Age cohort determines messaging permissibility under state advertising restrictions.
- Health-Conscious Consumers:Functional food seekers substitute CBD desserts for alcohol or sleep aids. This segment spans multiple age brackets and concentrates in coastal metropolitan wellness retail.
- Millennials:Digital-native cohort drives online subscription adoption and social media amplification. Preference for vegan and low-calorie formulations shapes manufacturer R&D prioritization.
- Athletes:Recovery and inflammation management use cases attract this performance-oriented segment. Full-spectrum sourcing aligns with their tolerance for premium pricing and batch documentation.
- Retirees:Sleep and anxiety management applications drive adoption among older consumers. Oregon's mature market shows highest per-capita penetration in this demographic.
Health-conscious consumers represent the broadest addressable base; millennials are expanding most rapidly as a share of purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between permissive state-level frameworks and federal prohibition zones. California and Colorado consumers treat CBD ice cream as functional wellness retail, while jurisdictions lacking cannabis infrastructure remain effectively closed to distribution.
United States
California, Colorado, and Oregon concentrate dispensary channel volume through state cannabis board licensing. The FDA's prohibition on CBD food additives under the Federal Food, Drug, and Cosmetic Act blocks interstate grocery commerce. Los Angeles and Denver wellness cafés drive trial adoption through experiential tasting formats.
Canada
Health Canada regulates CBD as a cannabis product rather than food additive, requiring production within licensed facilities. Provincial distribution monopolies in Ontario and British Columbia control retail access. Vancouver and Toronto clusters integrate extraction with frozen dessert manufacturing under single-site licensing.
Germany
Novel Food authorization under EFSA guidelines classifies CBD extracts as requiring pre-market safety assessment. The BfArM maintains strict THC thresholds for hemp-derived products. Berlin's wellness retail sector imports compliant isolate formulations through Dutch distribution hubs.
Switzerland
Swissmedic permits CBD with THC content below 1% in ordinary food products, creating Europe's most permissive regulatory environment. Zurich and Geneva specialty retailers stock full-spectrum frozen desserts without pharmacy licensing. Domestic hemp cultivation in Ticino supplies extraction partners serving dessert manufacturers.
United Kingdom
The FSA requires Novel Food authorization for CBD extracts, with validated applications limited to isolate formats. THC traces above 0.01% trigger controlled substance classification. London wellness boutiques source compliant products through Irish manufacturing intermediaries.
CBD-Infused Ice Cream Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages separating dairy supply chain owners from extraction-dependent entrants. The market structures around three archetypes: legacy confectioners leveraging parent-company infrastructure, precision-dose edible specialists extending format expertise, and hemp-cultivation-integrated pure-plays controlling input supply. Competitive moves concentrate on backward integration into licensed farming and nanoemulsion technology licensing.
Among North American market participants, Ben & Jerry's represents the legacy confectioner archetype through its Vermont-based dairy supply chain integration. Kiva Confections exemplifies the precision-dose specialist segment, extending extraction expertise into frozen matrices. Sweet Leaf occupies the distribution-integrated position, anchoring dispensary network coverage across multiple state jurisdictions.
| Leading Market Players |
|---|
| Sweet Leaf |
| Kiva Confections |
| Ben & Jerry's |
| Hemp Haven |
| Dairy Farmers of America |
| Euphoria Ice Cream |
| Hemp Ice Cream |
| Emack & Bolio's |
| Canna Creamery |
| Others |
Value Network & Pricing Analysis
Sixty-day frozen inventory cycles in CBD ice cream manufacturing tether pricing power directly to licensed hemp biomass availability and state-compliant cold-chain capacity. Manufacturers holding captive extraction relationships in Colorado and Oregon command premium positioning against spot-market dependent competitors in constrained jurisdictions.
Pricing Analysis
Long-term offtake contracts with licensed hemp cultivators anchor input cost predictability for scaled producers, while spot-market sourcing exposes smaller operators to biomass price volatility. Three-tier pricing structure across premium, standard, and economy levels separates full-spectrum dispensary formats from isolate-based wellness retail and private-label supermarket entries. Cost compression in the economy tier is intensifying because hemp extract oversupply in Oregon and California has compressed crude input margins. Dispensary buyers show lowest price sensitivity due to staff-educated selling environments, while supermarket channel entrants face acute margin pressure from conventional frozen dessert benchmarks.
Supply Chain Analysis
USDA hemp cultivation licensing bottlenecks in Colorado, Oregon, and California concentrate compliant biomass supply among vertically integrated operators with seed-to-sale traceability systems. Manufacturing draws from lipid-based emulsion inputs, nanoemulsion stabilization compounds, and conventional dairy or oat milk bases. Single-source vulnerability in licensed extraction capacity creates supply disruption risk when state cannabis board inspections trigger temporary facility closures. Distribution runs through chilled logistics networks serving dispensary channels and direct-to-consumer subscription platforms, bypassing conventional grocery cold-chain infrastructure blocked by FDA prohibition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against functional beverage and pharmaceutical-grade edible substitutes that capture wellness consumers through faster onset formats and clearer regulatory pathways.
For Market Incumbents: Consolidate backward into licensed hemp farming in Oregon and Colorado to secure compliant biomass supply and insulate against USDA cultivation rule volatility. Deepen channel control through exclusive café partnerships in Los Angeles and Denver that build destination traffic and reduce dispensary margin stacking. Nanoemulsion technology licensing represents the critical R&D lever to compress onset time gaps with pharmaceutical-grade edible substitutes. For New Entrants and Emerging Players: Differentiate on vegan base convergence by targeting oat and coconut milk formulations where emulsion stability now achieves dairy parity and stigma reduction outpaces regulatory clarity. The most penetrable white space sits in online subscription channels serving health-conscious millennials seeking recurring delivery convenience outside dispensary dependence. A direct-to-consumer go-to-market angle with state-compliant e-commerce platforms enables margin capture without retail shelf-space constraints. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory optionality play because federal rescheduling deliberations could trigger FDA alignment measures that open conventional grocery channels and revalue licensed manufacturing assets. Acquisition targets should display integrated extraction-to-freezer capabilities with multi-state cannabis board licensing. The signal to watch is DEA scheduling announcements and corresponding state alignment legislation that would indicate channel expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Licensed Hemp Farming | Captures USDA-compliant biomass supply and insulates against state cultivation rule volatility. |
| Nanoemulsion Technology Licensing | Enables water-compatible CBD particles that improve cold-matrix stability and onset predictability. |
| Direct-to-Consumer Subscription Launch | Bypasses dispensary margin stacking through state-compliant e-commerce and chilled logistics networks. |
| Café Channel Partnership Expansion | Builds destination traffic in Los Angeles and Denver wellness retail through experiential tasting formats. |
| Multi-State Cannabis Board Licensing | Secures operational predictability across California, Colorado, and Oregon jurisdictional frameworks. |
Research Methodology
A standing panel of frozen dessert formulation scientists, licensed extraction facility operators, state cannabis board regulators, and specialty café procurement managers provided ongoing calibration across the research window. Primary interviews with these stakeholders combined with secondary validation against FDA guidance documents, USDA hemp cultivation rule filings, state cannabis board enforcement records, and dispensary sales databases. Bottom-up volume triangulation from licensed facility throughput data and top-down market sizing from channel revenue estimates were reconciled to produce consistent outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product formulation type, ingredient source purity tier, distribution channel regulatory pathway, and target demographic consumption occasion. CAGRs were derived from trend extrapolation of licensed facility capacity expansion and channel penetration rates, with specific inputs including hemp biomass yield forecasts and nanoemulsion technology adoption curves.
The analysis sits within stated boundaries; outcomes outside federal rescheduling alignment or sustained state-level permissiveness would require recalibration. Forecasts reflect documented assumptions regarding FDA enforcement posture, USDA hemp rule stability, and state cannabis board licensing continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Truffle Market
Specialty Foods
Areca Bowl Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Natural Honey Market
Specialty Foods
Global Freeze-Dried Pet Food Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Asia-Pacific Hummus Market
Specialty Foods
Carbonic Maceration Market