
 North America Pasta Market | 2026-2036
North America Pasta Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pasta Market Intelligence
Multi-source durum wheat procurement is pivoting toward vertically integrated supply chains as millers and pasta manufacturers seek price stability against commodity volatility. Barilla Holding SpA leverages its North American milling assets to secure consistent semolina quality across its portfolio. Ebro Foods SA sustains competitive positioning through specialized durum varieties grown under contract in the northern Great Plains. New World Pasta anchors its cost structure by operating dedicated grain elevators near its Midwest production facilities.
Pasta comprises unleavened dough formed from durum wheat semolina or alternative flours, extruded or laminated into shapes, then dried to moisture levels below 12.5 percent for shelf stability or distributed fresh with refrigerated logistics. Its primary commercial purpose is to deliver affordable, energy-dense meal foundations for both retail preparation and food service assembly. Dried pasta occupies the dominant volume position due to extended shelf life and lower logistics burden, while gluten-free pasta represents the fastest-expanding product type as cassava, lentil, and chickpea formulations improve textural parity. Fresh pasta commands premium placement in supermarket refrigerated cases and direct-to-restaurant channels where shorter cook times justify higher unit economics.
The FDA governs nutritional labeling and allergen declarations for pasta sold across the United States, while the USDA administers school nutrition standards that create institutional demand for whole-grain formulations. Health Canada and the Canadian Food Inspection Agency enforce parallel labeling and grain grading rules that shape cross-border product standardization. Stakeholders must monitor evolving whole-grain threshold requirements and alternative protein labeling pathways as regulators respond to dietary guidance shifts and consumer preference diversification.

Market Dynamics
Food service operators across the United States and Canada are accelerating pasta menu expansion as labor shortages and cost pressures drive demand for rapid-assembly carbohydrate platforms that minimize kitchen skill requirements.
Growth Catalysts
- USDA school nutrition standards:Federal whole-grain mandates for institutional feeding programs create guaranteed offtake for reformulated pasta SKUs in K-12 cafeterias.
- Quick-service restaurant chains:Drive-thru and fast-casual operators are adding pasta bowls and mac-and-cheese platforms to capture dinner daypart traffic.
- Chickpea and lentil flour milling:Alternative protein extrusion technology is improving the al dente texture of gluten-free pasta to near-wheat parity.
Market Restraints
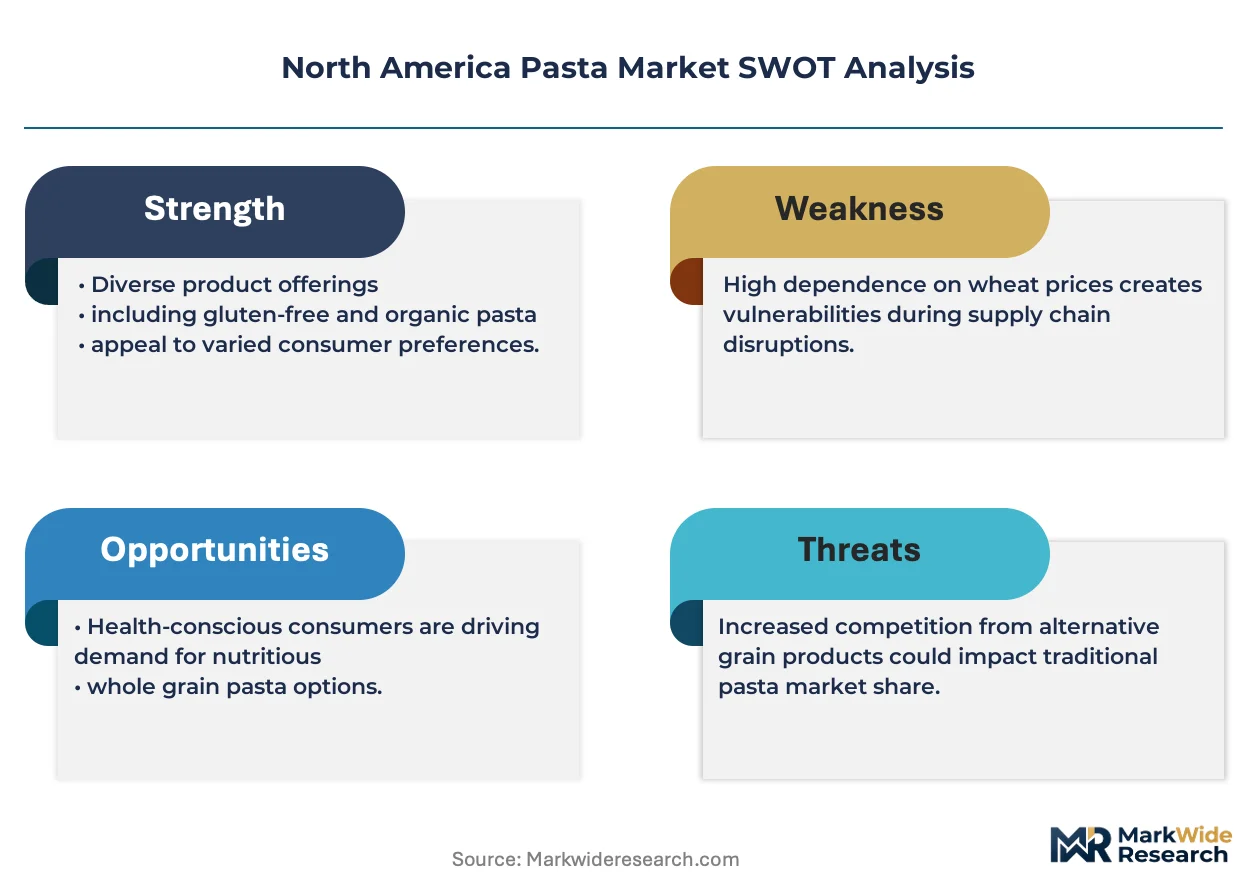
- Durum wheat price volatility:North American semolina costs fluctuate with drought cycles in the northern Great Plains and Canadian prairie provinces.
- Refrigerated logistics concentration:Fresh pasta distribution depends on cold-chain capacity that clusters around Chicago, Toronto, and Los Angeles metropolitan hubs.
- Gluten-free formulation limits:Rice and corn-based pastas exhibit inferior freeze-thaw stability, constraining food service batch preparation.
Strategic Opportunities
- Mexican market penetration:Underdeveloped retail pasta aisles in northern Mexican states present white-space expansion for shelf-stable imports.
- Health Canada front-of-package labeling:New sodium and sugar warning symbols create first-mover advantage for clean-label pasta positioned in Canadian supermarkets.
- Direct-to-restaurant e-commerce:Specialty fresh pasta producers are bypassing broadline distributors to capture margin through chef-facing digital platforms.
Industry Challenges
- Whole-grain extrusion engineering:Pasta manufacturers lack sufficient process engineers capable of maintaining die throughput when semolina substitution rates exceed 51 percent.
- Allergen segregation protocols:Facilities producing both wheat and legume-based pastas face FDA inspection scrutiny over cross-contact prevention validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pasta Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $21.43 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Pasta, Dried Pasta, Instant Pasta, Gluten-Free Pasta Packaging Type: Bags, Boxes, Pouches, Cans Distribution Channel: Supermarkets, Convenience Stores, E-Commerce, Restaurants End User: Households, Food Service, Retail, Industrial |
| Companies Covered | Ebro Foods SA, Unilever PLC, Barilla Holding SpA, Toyo Suisan Kaisha Ltd, New World Pasta, Nestlé SA, Nissin Foods Holdings Co Ltd, Samyang Foods Co Ltd, Campbell Soup Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pasta Market Strategic Shifts & Innovations
Extrusion technology and regulatory labeling requirements are converging to reshape how pasta manufacturers formulate, position, and distribute products across retail and food service channels.
High-pressure extrusion systems with precision temperature control are integrating into mid-scale pasta plants to enable continuous production of whole-grain and alternative-flour shapes without batch interruption. Regional restaurant groups in the Northeast and Pacific Northwest are adopting these lines to supply private-label fresh pasta to their own locations. The technology is integrating formerly separate mixing, extrusion, and drying stages into unified continuous processing that reduces labor headcount and improves moisture consistency.
The FDA's updated Nutrition Facts panel requirements and serving-size rationalization rules are forcing reformulation of "enriched" pasta claims and dual-column labeling for multi-serving packages. Manufacturers must now consolidate vitamin and mineral fortification statements while recalculating daily value percentages against revised reference intakes. Retail pasta SKUs targeting health-conscious consumers in California and New York metropolitan areas are responding fastest with simplified ingredient decks and prominent protein callouts.
Food service procurement departments are consolidating supplier rosters from fragmented regional pasta distributors toward national broadline contracts with guaranteed volume tiers and consolidated delivery schedules. Casino and stadium concessionaires are replacing multiple local fresh pasta vendors with single-source frozen pasta suppliers capable of cross-country logistics. This concentration is most visible in the Las Vegas and Atlantic City entertainment corridor, where property-level procurement autonomy has eroded in favor of corporate purchasing mandates.
North America Pasta Market Segmentation
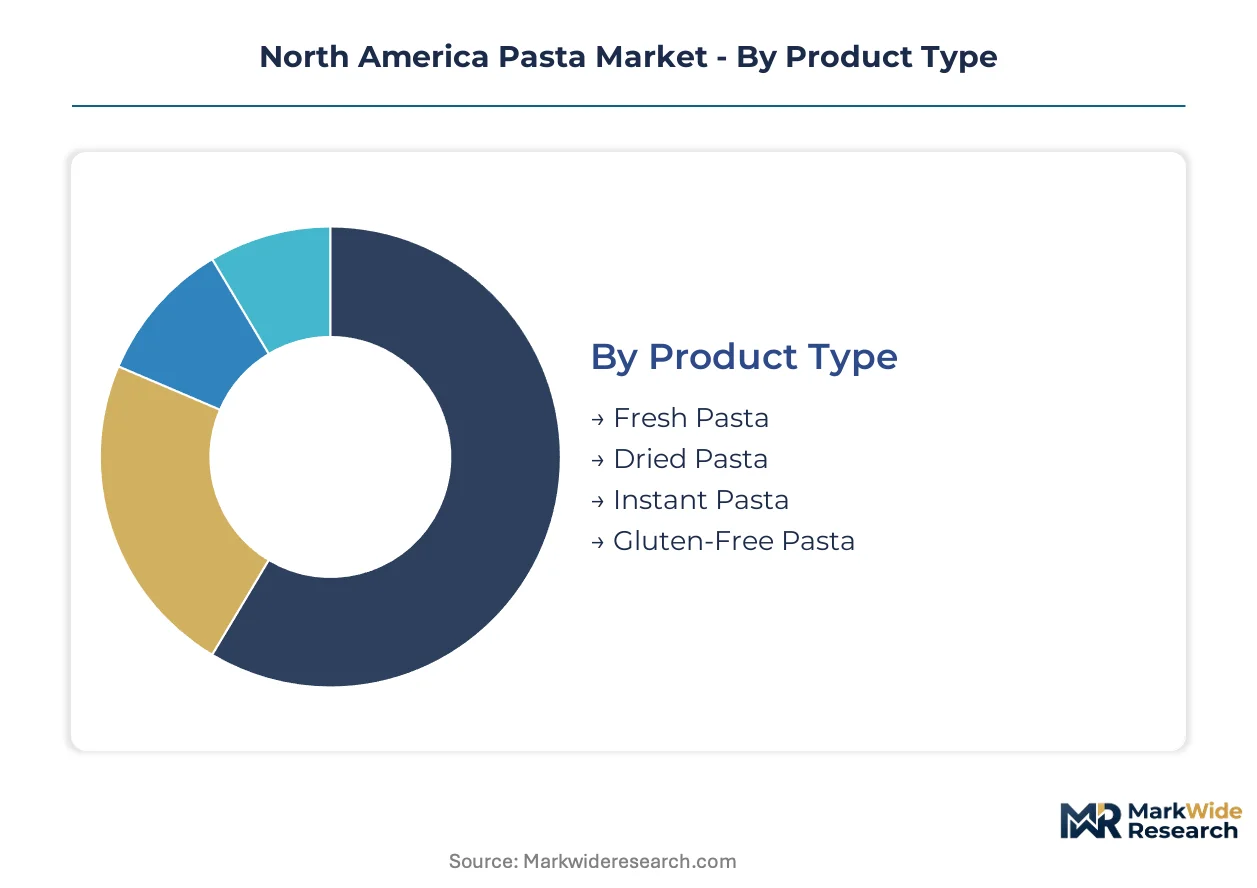
Pasta manufacturers configure production lines and inventory strategies around distinct product formats, packaging economics, channel requirements, and end-user specifications. Each segmentation dimension carries implications for shelf-life engineering, logistics investment, and margin structure across the United States, Canada, and Mexico.
Product Type:
Supply concentration in semolina milling and extrusion capacity shapes competitive dynamics across pasta formats, with capital intensity varying dramatically by moisture content and processing technology.
- Dried Pasta:Extruded semolina shapes dried below 12.5 percent moisture occupy the dominant production footprint across Midwest manufacturing corridors. USDA school nutrition contracts and broadline food service distribution in Texas and California sustain volume throughput for standard and whole-grain formulations.
- Gluten-Free Pasta:Chickpea, lentil, and cassava flour extrusions are displacing rice-based alternatives as equipment suppliers refine high-pressure processing for legume doughs. Health Canada labeling requirements and FDA allergen protocols are accelerating facility segregation investments for dedicated gluten-free lines in Ontario and Minnesota.
- Fresh Pasta:Refrigerated distribution networks concentrated around Chicago, Toronto, and Los Angeles metropolitan hubs constrain geographic reach despite premium positioning in restaurant and retail channels.
- Instant Pasta:Pre-cooked and dehydrated formats target camping, military, and emergency preparedness segments with extended shelf-life specifications requiring specialized retort or freeze-dry equipment.
Dried pasta absorbs the bulk of installed capacity; gluten-free pasta is expanding most quickly.
Packaging Type:
Packaging format selection directly determines shelf appeal, logistics cube efficiency, and compliance with FDA nutritional labeling real estate requirements for multi-serving declarations.
- Boxes:Folding carton formats dominate premium retail placement in Northeast and Pacific Coast supermarkets, supporting dual-column Nutrition Facts panels and prominent whole-grain callouts required by revised FDA serving-size rules.
- Bags:Flexible film pouches minimize freight cost for value-tier SKUs distributed through dollar store and warehouse club channels in the southeastern United States.
- Pouches:Stand-up and flat pouch configurations serve single-serve and microwave-ready pasta segments with modified atmosphere sealing for refrigerated and shelf-stable applications.
- Cans:Metal packaging persists in institutional and food service bulk formats where portion control and stackability outweigh material cost premiums.
Boxes command the highest unit margins; pouches are climbing fastest as fresh pasta and ready-meal formats proliferate.
Distribution Channel:
Channel selection dictates cold-chain requirements, promotional cadence, and the granularity of demand forecasting as e-commerce and food service procurement patterns diverge from traditional retail.
- Supermarkets:Regional grocery banners in Illinois, Pennsylvania, and British Columbia are consolidating pasta category management under centralized buyers, reducing slotting fee negotiation leverage for mid-tier suppliers.
- Restaurants:Independent and chain food service operators from quick-service pasta bowls to white-tablecloth Italian concepts specify custom shapes and cook times that drive co-manufacturing arrangements.
- E-Commerce:Direct-to-consumer and third-party marketplace fulfillment is reshaping packaging for parcel durability, with subscription models emerging for specialty gluten-free and fresh pasta deliveries.
- Convenience Stores:Grab-and-go microwave pasta cups and shelf-stable mac-and-chease formats target travel plaza and urban convenience locations with limited preparation equipment.
Supermarkets still transact the largest volume; e-commerce is gaining share fastest as specialty producers bypass traditional distribution.
End User:
End-user segmentation determines formulation priorities, from USDA-mandated whole-grain thresholds in institutional feeding to clean-label ingredient decks for premium household positioning.
- Households:Retail purchasers in metropolitan New York, Los Angeles, and Toronto markets are driving demand for protein-fortified and alternative-flour pastas with simplified ingredient statements.
- Food Service:Casino, stadium, and chain restaurant operators are consolidating supplier rosters toward national broadline contracts with frozen pasta specifications that reduce labor and skill requirements.
- Industrial:Prepared meal manufacturers and soup processors purchase bulk pasta as an input ingredient, requiring precise dimensional tolerances for automated portioning and rehydration stability.
- Retail:Private-label and branded retail channels encompass both shelf-stable and refrigerated cases, with distinct margin structures and promotional calendars.
Food service captures the majority of production volume directed outside retail; household demand for premium formats is accelerating most sharply.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Durum wheat cultivation in the northern Great Plains and Canadian prairie provinces anchors North American pasta manufacturing, with milling infrastructure concentrated along rail corridors connecting grain elevators to Midwest processing plants.
United States
USDA school nutrition standards mandate whole-grain thresholds in K-12 cafeterias, creating institutional demand for reformulated pasta SKUs. FDA updated Nutrition Facts labeling requirements force serving-size rationalization and dual-column declarations on multi-serving packages. Metropolitan food halls in New York and Los Angeles drive premium fresh pasta uptake through chef-facing direct distribution channels.
Canada
Health Canada front-of-package labeling rules with sodium warning symbols create first-mover positioning for clean-label pasta in Toronto and Vancouver supermarkets. The Canadian Food Inspection Agency enforces grain grading standards that shape cross-border product standardization with US manufacturers. Prairie province durum production supplies semolina mills in Ontario and Manitoba with price-competitive feedstock.
Mexico
Underdeveloped retail pasta aisles in Nuevo León and Chihuahua present white-space expansion opportunities for shelf-stable imports from US manufacturers. Mexican consumer preferences favor longer pasta shapes in regional cuisines, influencing SKU localization requirements. Northern border states integrate with Texas and California distribution networks through maquiladora logistics corridors.
North America Pasta Market Key Industry Players
Global majors compete with regional champions across milling assets and food service distribution networks, producing a tiered structure where vertically integrated semolina producers hold cost advantages over brand-dependent importers. The vendor base clusters around three archetypes: multinational consumer goods conglomerates with diversified carbohydrate portfolios, specialized pasta manufacturers with captive grain supply, and private-label co-manufacturers serving retail banners. Dominant competitive moves include backward integration into durum wheat procurement and consolidation of food service distribution through national broadline contracts.
Within the multinational tier, Nestlé SA and Unilever PLC exemplify diversified food conglomerates balancing pasta against broader pantry staple portfolios. Barilla Holding SpA and Ebro Foods SA represent specialized manufacturers with pronounced vertical integration into North American milling infrastructure. New World Pasta occupies a position as a regional-scale operator with dedicated Midwest production facilities.
| Leading Market Players |
|---|
| Ebro Foods SA |
| Unilever PLC |
| Barilla Holding SpA |
| Toyo Suisan Kaisha Ltd |
| New World Pasta |
| Nestlé SA |
| Nissin Foods Holdings Co Ltd |
| Samyang Foods Co Ltd |
| Campbell Soup Company |
| Others |
Cost & Logistics Intelligence
Family-owned durum wheat cooperatives in the northern Great Plains and Canadian prairie provinces anchor upstream supply, transmitting commodity volatility directly into semolina pricing while constraining margin compression for downstream pasta manufacturers locked into long-term offtake contracts with food service operators.
Pricing Analysis
Warranty and freshness-guarantee bundling separates premium fresh pasta sold through chef-facing direct channels from unbundled shelf-stable formats moving through broadline distributors. Three-tier pricing structure across premium, standard, and economy levels stratifies by whole-grain content and alternative-flour formulation, with USDA-certified whole-grain SKUs commanding measurable premiums in K-12 institutional procurement. Pricing pressure stems from durum wheat drought cycles in North Dakota and Saskatchewan squeezing semolina input costs. Quick-service restaurant chains exhibit highest price sensitivity due to fixed-menu pricing constraints, while white-tablecloth restaurant groups absorb premiums for custom extruded shapes.
Supply Chain Analysis
Durum wheat supply rests on cultivation concentrated in the United States, Canada, and Mexico, with prairie province harvests feeding cross-border milling infrastructure along rail corridors connecting grain elevators to Midwest processing plants. Semolina flour, chickpea and lentil protein isolates, and modified atmosphere packaging films constitute critical input dependencies. Single-source vulnerability in northern Great Plains durum production exposes manufacturers to climate-driven supply interruptions. Distribution runs through national broadline food service contracts consolidating formerly fragmented regional distributor networks, with refrigerated logistics clustering around Chicago, Toronto, and Los Angeles metropolitan hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over durum wheat procurement and captive semolina milling capacity determines cost structure resilience against commodity volatility.
For Market Incumbents: To counter margin compression from durum wheat price volatility, Barilla Holding SpA and Ebro Foods SA should deepen backward integration into prairie province grain elevator networks while expanding dedicated gluten-free production lines in Ontario and Minnesota to capture Health Canada labeling-driven demand. Capacity addition in captive durum milling assets represents the critical defensive lever. For New Entrants and Emerging Players: Capture underdeveloped retail pasta aisles in northern Mexican states through shelf-stable import partnerships leveraging Texas and California distribution corridors, with Nuevo León and Chihuahua presenting the most penetrable white-space. Direct-to-restaurant e-commerce platforms targeting chef-facing specialty fresh pasta sales offer the strongest go-to-market angle against established broadline distributors. For Investors and Strategic Acquirers: FDA updated Nutrition Facts labeling implementation is the leading indicator that clean-label reformulation capabilities will separate viable acquisition targets from stranded legacy assets. Over the coming decade, vertically integrated mid-scale operators with captive grain supply and certified gluten-free facility segregation command superior long-term viability. Watch for Health Canada front-of-package sodium warning symbol adoption as the signal triggering accelerated clean-label pasta repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Durum Milling | Captive semolina supply from prairie province grain elevators insulates Barilla and Ebro against commodity price swings. |
| Gluten-Free Facility Segregation | Dedicated chickpea and lentil extrusion lines in Ontario and Minnesota satisfy FDA allergen protocols and Health Canada labeling requirements. |
| Direct-to-Restaurant E-Commerce | Chef-facing digital platforms bypass broadline distributors to capture margin in metropolitan New York and Los Angeles food halls. |
| Whole-Grain Extrusion Engineering | Process engineering talent capable of maintaining die throughput above 51 percent semolina substitution addresses USDA school nutrition contract requirements. |
| Mexican Market Distribution Partnerships | Shelf-stable import alliances through maquiladora logistics corridors penetrate underdeveloped retail pasta aisles in Nuevo León and Chihuahua. |
Research Approach
USDA school nutrition procurement databases, FDA labeling guidance documents, and Canadian Grain Commission trade statistics formed the secondary backbone, supplemented by primary interviews with pasta manufacturing plant managers, broadline food service procurement directors, semolina mill operations heads, and Health Canada regulatory affairs specialists. Bottom-up volume modeling from installed extrusion capacity and top-down value triangulation from retail scanner data were cross-validated against trade flow records.
Historical trendline analysis of durum wheat acreage, semolina price indices, and pasta production volumes established baseline growth patterns across the analysis window. Segmentation modeling incorporated product format, packaging type, distribution channel, and end-user specifications with geographic production cluster and regulatory framework overlays. CAGRs were derived from slope analysis of normalized volume and value trajectories, with alternative-flour extrusion technology adoption curves and whole-grain threshold compliance timelines serving as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to drought frequency in the northern Great Plains, evolving FDA whole-grain definition revisions, and refrigerated logistics capacity expansion in secondary metropolitan markets. Forecasts reflect documented assumptions regarding durum yield stability and institutional procurement continuity. A small set of named triggers—Health Canada front-of-package labeling enforcement timing, quick-service pasta bowl menu expansion rates, and gluten-free texture parity breakthroughs—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Instant Noodles Market