
 Global Dessert Mixes Market | 2026-2036
Global Dessert Mixes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dessert Mixes Market Foresight
Commercial bakeries and foodservice operators is collapsing as a share of total volume while home baking enthusiasts and small-batch catering operations gain ground in the post-pandemic demand rotation. General Mills Inc. leverages its manufacturing scale to dominate the cake mix segment across North American grocery channels. Dr. Oetker KG anchors European demand through specialized brownie and pudding formulations with deep distribution in German and Austrian retail networks. Mondelez International Inc. competes on brand strength in cookie mixes, extending its snack portfolio into home-prepared desserts through controlled shelf placement in supermarkets.
Dessert mixes comprise pre-formulated dry blends of flour, sugar, leavening agents, flavoring compounds, and stabilizers that require the addition of wet ingredients such as water, eggs, or oil before baking or setting. These formulations typically specify precise hydration ratios and thermal profiles to ensure consistent texture and shelf stability across batch sizes. Cake mixes occupy the largest revenue pool within product type segmentation, though brownie mixes generate premium margins in specialty and online channels. The hospitality and catering application segment shows the fastest trajectory as hotels and event venues outsource dessert preparation to reduce kitchen labor costs. Pouch packaging is displacing traditional box formats in online retail channels due to lower shipping weights and reduced breakage rates.
The FDA governs ingredient disclosure and allergen labeling for dessert mixes sold in the United States, while the EFSA enforces additive limits and nutritional claim standards across European markets. Japan's Ministry of Health, Labour and Welfare applies positive-list requirements for food additives that constrain formulation options for exporters targeting Japanese consumers. Stakeholders must monitor evolving sugar taxation regimes and front-of-pack labeling mandates that threaten conventional formulations while creating openings for repositioned clean-label products.
Market Dynamics
Clean-label mandates from FDA and EFSA are forcing simultaneous reformulation of stabilizer systems and sugar-reduction architectures across all major producing regions, compressing R&D timelines while opening premium positioning for compliant entrants.
Growth Catalysts
- EFSA Additive Limits:Tightened emulsifier thresholds in European markets accelerate demand for enzyme-based texturizers that bypass conventional stabilizer categories entirely.
- Home Baking Retention:Post-pandemic hobbyist bakers in the United States maintain elevated purchase frequency of specialty brownie and pudding formats through direct-to-consumer channels.
- Pouch Packaging Conversion:E-commerce fulfillment economics favor flexible film structures over rigid boxes, reducing dimensional weight charges for cross-border shipments from German manufacturing hubs.
Market Restraints
- Wheat Flour Price Volatility:Drought cycles in Black Sea sourcing regions transmit directly to base mix cost structures without viable short-term substitution.
- Japanese Positive-List Constraints:MHLW additive approvals require 18-24 month evaluation windows that freeze formulation innovation for exporters targeting Japanese retail.
- Scratch Baking Resurgence:Social media recipe distribution and stand-mixer ownership growth present persistent substitution pressure in premium consumer segments.
Strategic Opportunities
- Indian Urban Penetration:Tier-1 and Tier-2 city modern trade expansion creates shelf access for Western-format cake mixes among time-constrained dual-income households.
- Hospitality Outsourcing:Hotel and banquet kitchen labor cost pressures drive contracted dessert preparation to external commissaries using high-yield institutional mix formats.
- EU Green Deal Packaging:Mandatory recycled content thresholds for single-use packaging incentivize compostable film development with first-mover advantage in Scandinavian markets.
Industry Challenges
- Clean-Label Reformulation Complexity:Removing phosphate-based leavening while maintaining volume and crumb structure demands extended pilot-scale testing cycles.
- Allergen Segregation Infrastructure:Dedicated production lines for gluten-free and nut-free variants require capital deployment that smaller regional blenders cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dessert Mixes Market |
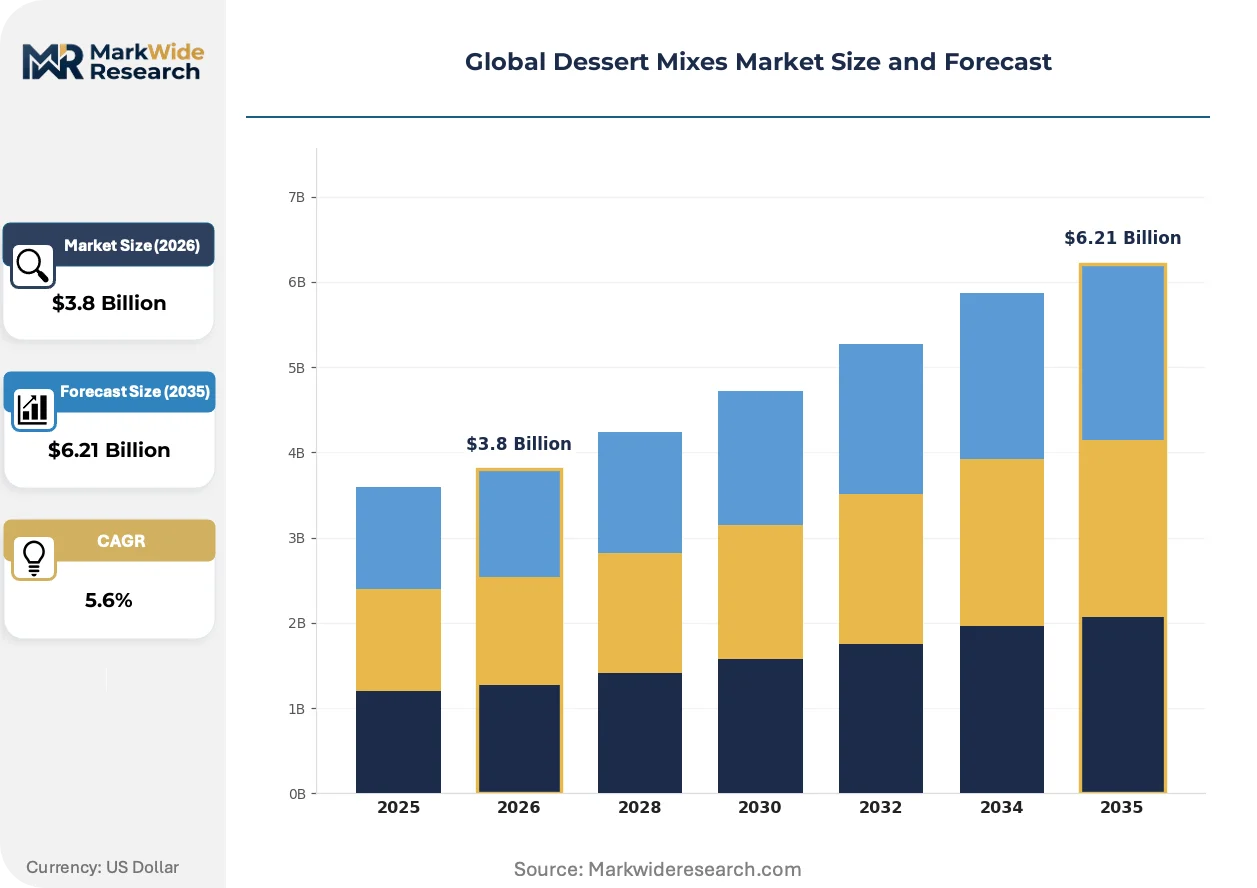
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cake Mixes, Pudding Mixes, Brownie Mixes, Cookie Mixes, Pie Mixes Application: Home Baking, Commercial Bakeries, Foodservice, Hospitality, Catering Packaging Type: Box, Pouch, Canister, Tray, Bulk Bags Customer Type: Supermarkets, Specialty Stores, Online Retailers, Wholesalers, Convenience Stores |
| Companies Covered | Chelsea Milling Co., Chocoladefabriken Lindt & Sprüngli AG, General Mills Inc., Sovos Brands, European Gourmet Bakery, Dr. Oetker KG, Mondelez International Inc., Duncan Hines, Conagra Brands Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dessert Mixes Market Shifts & Advancements
Reformulation science and packaging engineering are converging to reshape how dessert mixes reach end-users, with regulatory pressure and channel economics jointly determining which innovations achieve commercial scale.
Enzyme-based texturizer platforms are decomposing the traditional stabilizer stack in premium mix formulations. Specialty millers in Germany and Austria pilot amylase and lipase systems that replace modified starches and gums. This transition is decomposing established supplier relationships between mix manufacturers and hydrocolloid producers.
Front-of-pack nutritional labeling mandates from FDA and EFSA are compressing permissible sugar declarations without sacrificing sensory performance. Manufacturers deploy bulking fibers and high-intensity sweetener blends to maintain sweetness perception. Cake mix segments in the United States and United Kingdom face the most immediate reformulation deadlines as retail buyers delist non-compliant SKUs.
Direct-to-subscription purchasing is consolidating repeat buying patterns among enthusiast home bakers. Specialty retailers and brand-owned storefronts displace conventional grocery replenishment with curated flavor rotations and limited releases. This behavioral shift concentrates most visibly in Japanese and German markets where pantry stocking norms already favor planned rather than impulse acquisition.
Global Dessert Mixes Market Segmentation
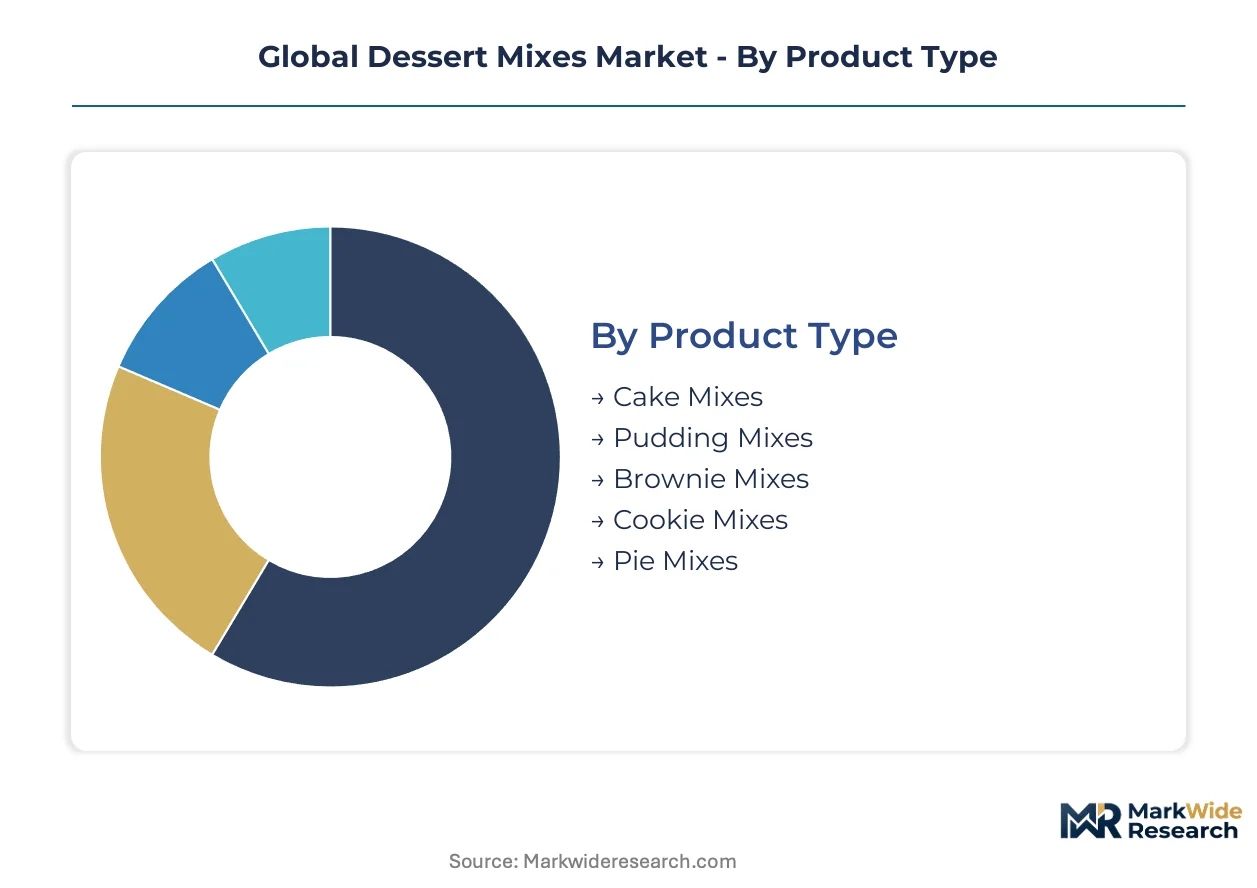
Dessert mixes fragment across four distinct taxonomies that govern procurement economics and regulatory exposure. Product type determines formulation complexity and clean-label compliance burden. Application and packaging choices channel volume toward divergent margin structures.
Product Type:
FDA and EFSA diverge on leavening agent classifications, forcing cake and brownie formulations toward enzyme-based alternatives while pudding mixes face distinct stabilizer scrutiny.
- Cake Mixes:Dry blends combine flour, sugar, and chemical leavening with precise hydration specifications for oven spring and crumb structure. Demand concentrates in United States supermarkets where home bakers prioritize one-bowl convenience; EFSA phosphate limits accelerate reformulation toward organic acid-leavening systems.
- Brownie Mixes:Higher fat-to-flour ratios with cocoa powder bases require specialized emulsifier packages to prevent syneresis during cooling. German and Austrian specialty retailers command premium shelf positioning; clean-label mandates drive substitution of propylene glycol esters with natural lecithin blends.
- Pudding Mixes:Starch-thickened or gelatin-based formulations setting via refrigeration or stovetop heating.
- Cookie Mixes:Lower hydration blends with distributed fat particles for spread control during baking.
- Pie Mixes:Filling bases requiring separate crust preparation, concentrated in seasonal purchasing windows.
Established volume favors Cake Mixes; emerging adoption favors Brownie Mixes.
Application:
Cost tier stratification separates commodity institutional purchasing from enthusiast premium channels.
- Home Baking:Individual consumers executing small-batch preparation with variable equipment quality. United States direct-to-subscription channels show steepest expansion trajectory as curated flavor rotations displace grocery replenishment.
- Commercial Bakeries:High-throughput operations demanding consistent hydration tolerance across batch scale variation. Japanese hotel commissaries outsource dessert preparation to reduce kitchen labor costs; MHLW additive approvals constrain supplier selection.
- Foodservice:Restaurant and cafeteria operators with limited pastry staffing.
- Hospitality:Hotel banquet operations prioritizing portion consistency and holding stability.
- Catering:Event-based volume with irregular demand patterns and menu customization requirements.
Volume concentrates in Home Baking; margin expansion concentrates in Commercial Bakeries.
Packaging Type:
Channel economics and EU Green Deal compliance reshape material selection across shipment distances.
- Pouch:Flexible film structures with reduced dimensional weight for e-commerce fulfillment. German manufacturing hubs favor pouch conversion for cross-border shipments; recycled content mandates under EU Green Deal accelerate compostable film pilot programs in Scandinavian markets.
- Box:Rigid paperboard with structural integrity for retail shelf display. United States supermarkets maintain box preference for planogram compliance; breakage rates in parcel shipping disadvantage this format for online channels.
- Canister:Reclosable rigid containers for multi-use storage.
- Tray:Molded pulp or plastic for portion-controlled institutional formats.
- Bulk Bags:Industrial-scale flexible intermediate bulk containers for foodservice and manufacturing.
Legacy share resides with Box; fastest conversion occurs in Pouch.
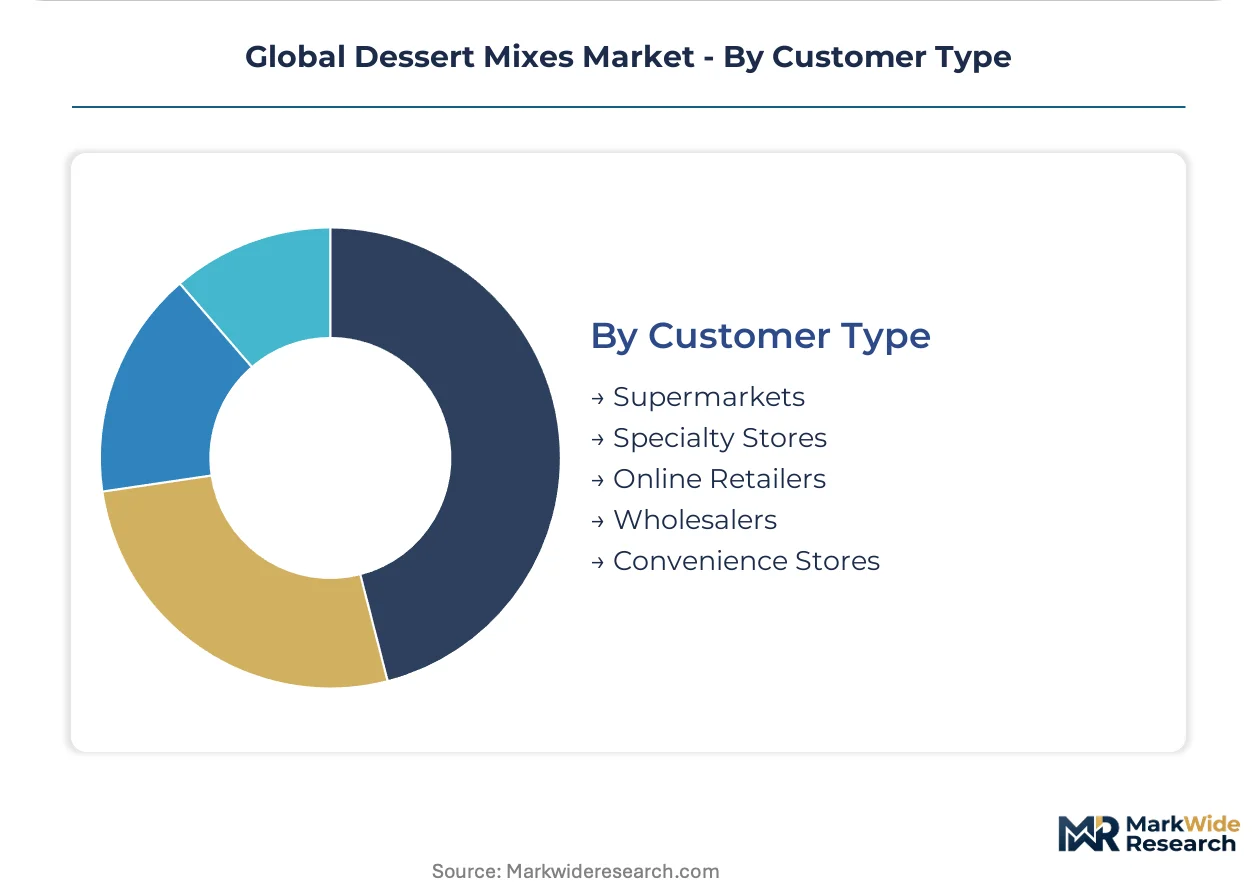
Customer Type:
Geographic penetration patterns in India and Japan determine channel prioritization for Western-format entrants.
- Supermarkets:Full-assortment grocery operators with dedicated baking aisles and promotional calendar integration. Tier-1 and Tier-2 Indian cities expand modern trade shelf access for cake mixes among time-constrained dual-income households.
- Specialty Stores:Curated retailers emphasizing premium import positioning and staff expertise. Japanese pantry stocking norms favor planned acquisition through specialty channels over impulse supermarket purchase.
- Online Retailers:Third-party marketplace and direct brand storefronts.
- Wholesalers:Distributors serving institutional and foodservice accounts with volume pricing.
- Convenience Stores:Limited-assortment urban outlets for emergency replenishment.
Primary volume flows through Supermarkets; premium positioning concentrates in Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient sourcing and manufacturing scale concentrate in the United States, Germany, and Japan, where established milling infrastructure and retail channel density support premium mix production. Regulatory divergence across FDA, EFSA, and Japan's MHLW creates distinct compliance environments that shape regional formulation strategies.
United States
Home baking enthusiasts sustain elevated purchase frequency through direct-to-subscription channels, displacing conventional grocery replenishment. FDA allergen labeling mandates and front-of-pack nutritional disclosure requirements compress permissible sugar declarations. Chicago and Minneapolis-St. Paul anchor North American manufacturing, with General Mills leveraging regional milling infrastructure to dominate supermarket cake mix shelf space.
Germany
Specialty brownie and pudding formats command premium positioning in Austrian and German retail networks through curated flavor expertise. EFSA additive limits and phosphate-based leavening restrictions accelerate reformulation toward enzyme-based texturizers. Bavaria and North Rhine-Westphalia host Dr. Oetker KG's specialized production facilities, with flexible pouch packaging pilot programs advancing under EU Green Deal recycled content thresholds.
Japan
Pantry stocking norms favor planned acquisition through specialty channels over impulse supermarket purchase, concentrating volume in curated retail. MHLW positive-list requirements for food additives impose 18-24 month evaluation windows that constrain formulation innovation for imported mixes. Tokyo and Osaka metropolitan areas drive hospitality outsourcing demand as hotel commissaries reduce kitchen labor costs through contracted dessert preparation.
India
Tier-1 and Tier-2 city modern trade expansion creates shelf access for Western-format cake mixes among time-constrained dual-income households. FSSAI food safety standards and labeling requirements govern domestic manufacturing while imported products face additional customs scrutiny. Maharashtra and Karnataka urban clusters show fastest adoption curves as specialty retailers introduce premium brownie formats to metropolitan consumers.
United Kingdom
Front-of-pack labeling mandates from EFSA-aligned domestic regulations drive sugar-reduction reformulation across cake and cookie mix segments. London and Southeast England concentrate specialty retail demand, with curated online storefronts displacing conventional grocery for enthusiast home bakers. Scottish and Northern English manufacturing hubs supply institutional formats to hospitality outsourcing contracts.
Global Dessert Mixes Market Competitive Landscape
Concentration sits with diversified food conglomerates possessing integrated milling and distribution infrastructure. Three to five multinational operators control North American and European grocery channel shelf space through scale-driven manufacturing and promotional calendar integration. Strategic archetypes separate conglomerate-owned brands with backward flour milling integration from specialty European chocolatiers and private-label contract manufacturers. Dominant competitive moves include portfolio diversification into clean-label sub-lines and geographic licensing partnerships to bypass MHLW approval delays in Japan.
Among conglomerate-tier operators, General Mills Inc., Dr. Oetker KG, and Mondelez International Inc. exemplify distinct regional anchoring strategies. General Mills represents North American scale dominance through supermarket channel control. Dr. Oetker KG occupies the European specialist position with brownie and pudding formulation expertise. Mondelez International sits within the snack-brand extension archetype, leveraging cookie mix portfolios to bridge prepared and home-baked dessert occasions.
| Leading Market Players |
|---|
| Chelsea Milling Co. |
| Chocoladefabriken Lindt & Sprüngli AG |
| General Mills Inc. |
| Sovos Brands |
| European Gourmet Bakery |
| Dr. Oetker KG |
| Mondelez International Inc. |
| Duncan Hines |
| Conagra Brands Inc. |
| Others |
Supply & Pricing Matrix
Capacity utilization at integrated milling facilities in Minnesota and Bavaria sets price floors across standard and premium tiers, with scale advantages compressing margin recovery for regional blenders lacking backward flour integration. This concentration of milling infrastructure in the United States and Germany creates divergent procurement economics for pouch versus box formats, as dimensional weight advantages in e-commerce channels reshape downstream price positioning.
Pricing Analysis
Volume-discount tiering structures separate institutional foodservice contracts from direct-to-consumer subscription pricing, with hospitality buyers capturing 15-25% unit reductions against single-pouch retail. Three-tier pricing structure across premium, standard, and economy levels reflects clean-label certification status and enzyme-based texturizer adoption rather than base ingredient quality alone. Cost compression in standard-tier cake mixes is intensifying because wheat flour volatility transmits directly to base mix economics without viable short-term substitution. Home baking enthusiasts through specialty channels show least price sensitivity, while commercial bakeries and foodservice operators exhibit acute responsiveness to volume-adjusted unit economics.
Supply Chain Analysis
Inventory lead-times for enzyme-based texturizers extend 8-12 weeks longer than conventional hydrocolloid stocks, constraining reformulation agility under EFSA phosphate limits. Manufacturing concentrates in the United States, Germany, and Japan, with raw material dependencies spanning Black Sea wheat, Malaysian palm oil derivatives, and Brazilian sugar. Single-source vulnerability sits with modified starch suppliers transitioning production lines to amylase systems. Distribution runs through supermarket direct-store-delivery networks in North America and wholesaler-consolidated routes in European specialty retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through MHLW positive-list compliance creates defensive moats for established Japanese market participants, as 18-24 month additive approval windows freeze formulation innovation for new entrants. This structural barrier compounds with EFSA clean-label mandates to privilege incumbents with existing pilot-scale testing infrastructure.
For Market Incumbents: Compound regulatory compliance advantages by accelerating enzyme-based texturizer platform deployment ahead of EFSA phosphate deadlines, while extending backward integration into specialty milling to capture margin from wheat price volatility. Channel control through direct-to-subscription portals in Japan and Germany defends against specialty retailer private-label encroachment. For New Entrants and Emerging Players: Differentiate on clean-label certification velocity by targeting Indian Tier-1 and Tier-2 modern trade expansion, where FSSAI standards are less constraining than MHLW or EFSA frameworks. White-space concentration in hospitality outsourcing contracts for hotel commissaries offers penetrable volume with lower brand equity barriers than supermarket shelf placement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors enzyme-based formulation specialists with existing EFSA compliance documentation over conventional stabilizer-dependent assets. Long-term viability across the analysis window rests on regulatory adaptation capability rather than manufacturing scale alone. Acquisition targets should demonstrate completed clean-label SKU transitions with validated sensory performance. The signal to watch is delisting velocity of non-compliant cake mixes by United States and United Kingdom retail buyers.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label SKU Transition | EFSA phosphate limits and FDA sugar-reduction mandates compress reformulation timelines for cake and brownie portfolios. |
| Pouch Packaging Conversion | EU Green Deal recycled content thresholds and e-commerce dimensional weight economics favor flexible film over rigid box formats. |
| Direct-to-Subscription Channel Buildout | Japanese and German pantry stocking norms concentrate repeat purchase patterns through curated online storefronts. |
| Hospitality Outsourcing Contract Capture | Hotel commissary labor cost pressures in Tokyo and Osaka drive contracted dessert preparation to external mix suppliers. |
| Indian Modern Trade Shelf Access | Tier-1 and Tier-2 city expansion creates entry points for Western-format cake mixes among time-constrained dual-income households. |
Research Methodology
The analysis maps cake, brownie, pudding, cookie, and pie mix sub-sectors, each validated through interviews with brand managers, category buyers at supermarkets, supply planners, and channel sales heads. Primary fieldwork combined with secondary validation from Nielsen retail audit data, customs records, FDA filings, EFSA additive registers, and FSSAI labeling guidelines. Bottom-up volume triangulation against top-down value estimates anchored regional split consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling across product type, application, packaging format, and customer channel dimensions. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel shift elasticity. Forecast inputs incorporated wheat futures price corridors, enzyme texturizer adoption curves, and e-commerce penetration rates by geography.
The analysis sits within stated boundaries; outcomes outside sustained EFSA enforcement intensity or accelerated MHLW approval streamlining would require recalibration. Forecasts reflect documented assumptions regarding home baking retention rates and hospitality outsourcing contract velocity. Black Sea supply disruption or sugar taxation regime expansion present revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Convenience Food Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Tortilla Market
Packaged Foods
Packaged Food Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Chewing Gum Market