
 Saudi Arabia Ready Meals Market | 2026-2036
Saudi Arabia Ready Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Ready Meals Market Analytics
Supermarket shelf allocation is tilting toward chilled and frozen ready meal facings as grocers respond to changing household purchasing patterns. Americana Group leverages its integrated food production network to sustain margin control across multiple price tiers. Almarai Company anchors dairy-forward ready meal innovation through its captive cold chain infrastructure. Sunbulah Group competes via specialized Arabic cuisine formats that differentiate against Western-style entrants.
Ready meals comprise pre-cooked, portioned food products requiring minimal preparation before consumption, typically manufactured through blast chilling, retort processing, or flash-freezing to achieve shelf stability or extended refrigerated life. These products serve commercial and residential buyers seeking time-efficient meal solutions without scratch cooking. Frozen meals dominate volume throughput due to established cold chain penetration, while chilled meals capture expanding margin pools as freshness positioning commands price premiums. Meal kits represent the fastest-growing format as subscription mechanics and cooking involvement attract younger demographics. Tray packaging leads across retail channels for its microwave compatibility and visual presentation.
SFDA enforces halal certification mandates and nutritional labeling standards that shape product formulation and import eligibility for all ready meal categories. SASO technical regulations govern packaging materials and shelf-life claims, creating compliance thresholds that filter market entrants. Municipal food safety inspections in Riyadh, Jeddah, and Dammam add localized enforcement layers. Stakeholders must monitor evolving shelf-life extension technologies against tightening additive restrictions.
Market Dynamics
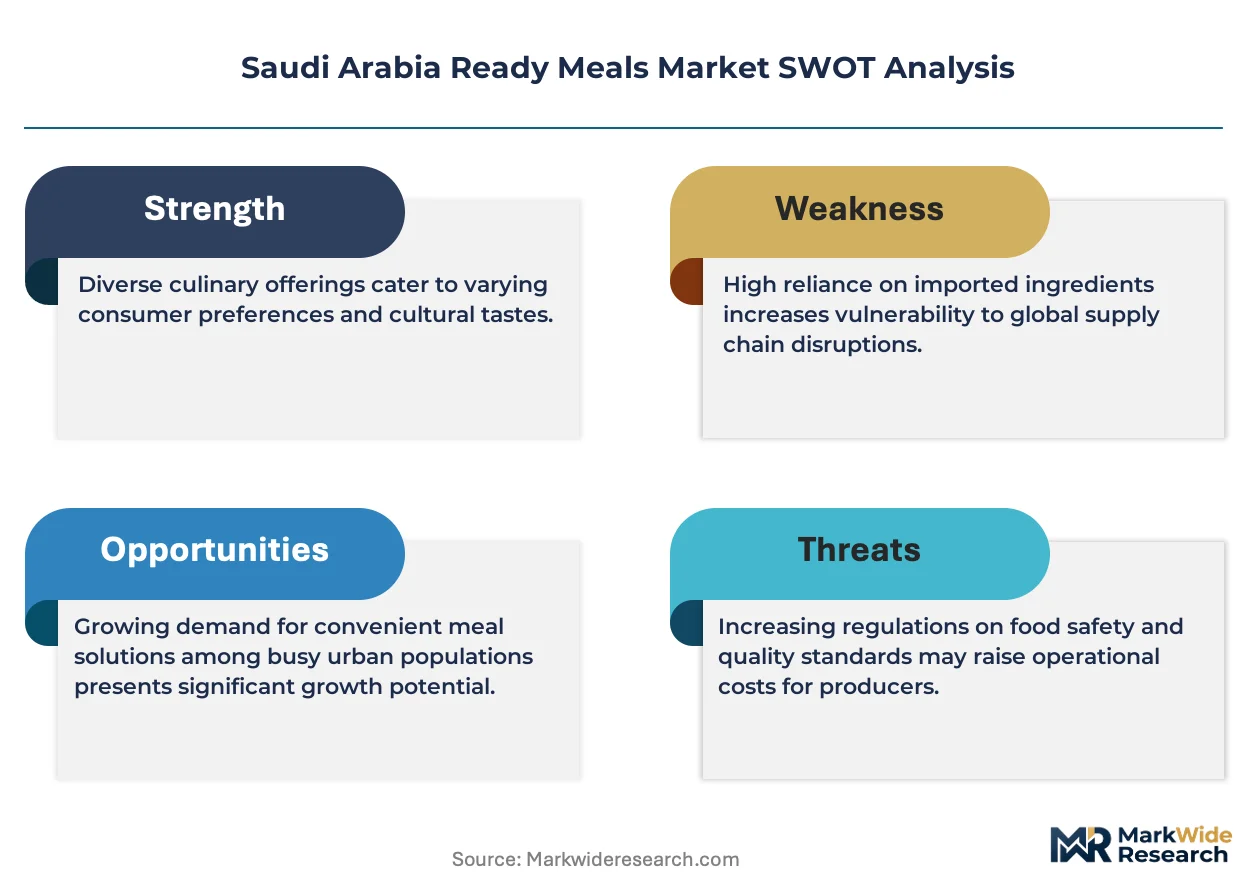
Dual-income household proliferation in Riyadh and Jeddah is compressing meal preparation windows and forcing retail shelf reallocation toward convenience formats. This demand compression intersects with SFDA halal certification mandates and municipal food safety enforcement layers to reshape competitive entry barriers.
Growth Catalysts
- SFDA Labeling Mandates:Tightened nutritional disclosure requirements for processed foods are accelerating product reformulation toward cleaner ingredient decks that command retail premium facings.
- Chilled Cold Chain Expansion:Captive refrigeration infrastructure deployment by dairy-forward producers is enabling margin capture in freshness-positioned ready meal segments.
- Urban Professional Clustering:Young dual-income households in Riyadh and Jeddah are consolidating purchasing power in hypermarket and convenience channels.
Market Restraints
- Halal Certification Friction:SFDA enforcement of slaughter and processing standards creates import eligibility barriers that limit supplier diversification for Western-style entrants.
- Input Concentration Risk:Wheat and palm oil supply dependence on regional traders exposes margins to commodity volatility and currency fluctuation.
- Shelf-Life Extension Limits:Tightening additive restrictions under SASO technical regulations constrain retort processing options for ambient-stable formats.
Strategic Opportunities
- Meal Kit Subscription Mechanics:Younger demographics in Jeddah and Dammam are demonstrating willingness to trade cooking involvement for perceived freshness and customization.
- Arabic Cuisine Format Specialization:Traditional dish portfolios that Western-style producers cannot replicate offer differentiated positioning in retail and foodservice channels.
- Municipal Inspection Harmonization:Convergence of Riyadh, Jeddah, and Dammam enforcement protocols is reducing compliance fragmentation for multi-city distribution.
Industry Challenges
- Cold Chain Talent Scarcity:Refrigerated logistics and blast chilling operations require specialized technicians that the Saudi vocational pipeline currently undersupplies.
- Reformulation Timeline Compression:SFDA additive restriction evolution forces accelerated R&D cycles that strain smaller producers with limited formulation capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Ready Meals Market |
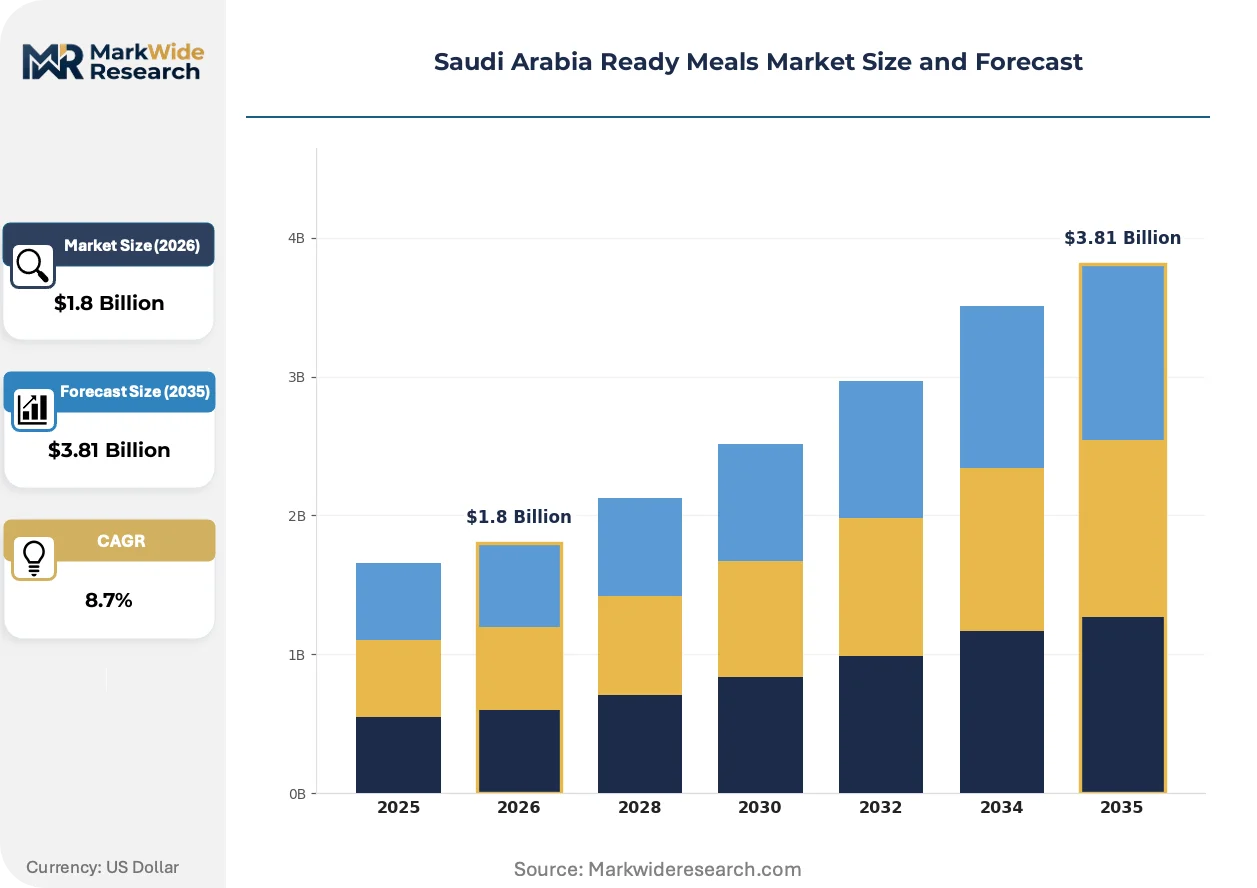
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Chilled Meals, Ambient Meals, Meal Kits Packaging Type: Tray, Bowl, Pouch, Can Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service Price Tier: Premium, Mid-Range, Economical, Value |
| Companies Covered | Sunbulah Group, Americana Group, Almarai Company, Almunajem Foods, Al Kabeer Group, Al Watania, JBS Foods SA, Al Karamah Dough Production Co. Ltd, Supreme Foods Processing Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Ready Meals Market Evolving Landscape
Freshness signaling and convenience compression are reshaping how ready meals reach Saudi households. Technology convergence, regulatory tightening, and channel experimentation are redefining competitive differentiation.
High-pressure processing is hybridizing traditional retort and blast chilling methods to extend refrigerated shelf life without chemical preservatives. Premium retail channels in Riyadh are adopting HPP-treated Arabic cuisine formats at accelerating rates. This technology compression is enabling chilled meals to capture margin pools previously reserved for frozen alternatives.
SFDA nutritional labeling enforcement is mandating front-of-pack disclosure for sodium, sugar, and saturated fat content. Reformulation costs are falling disproportionately on ambient-stable tray formats that rely on salt and fat for shelf stability. Chilled and frozen segments are responding faster due to existing clean-label positioning and shorter ingredient decks.
Young professionals are consolidating weekly meal purchasing into hypermarket destination trips supplemented by convenience store top-up visits. Traditional daily wet market purchasing is contracting in Jeddah and Riyadh urban cores. This channel rotation is forcing producers to optimize packaging formats for both bulk refrigerator stocking and single-serve immediate consumption.
Saudi Arabia Ready Meals Market Segmentation
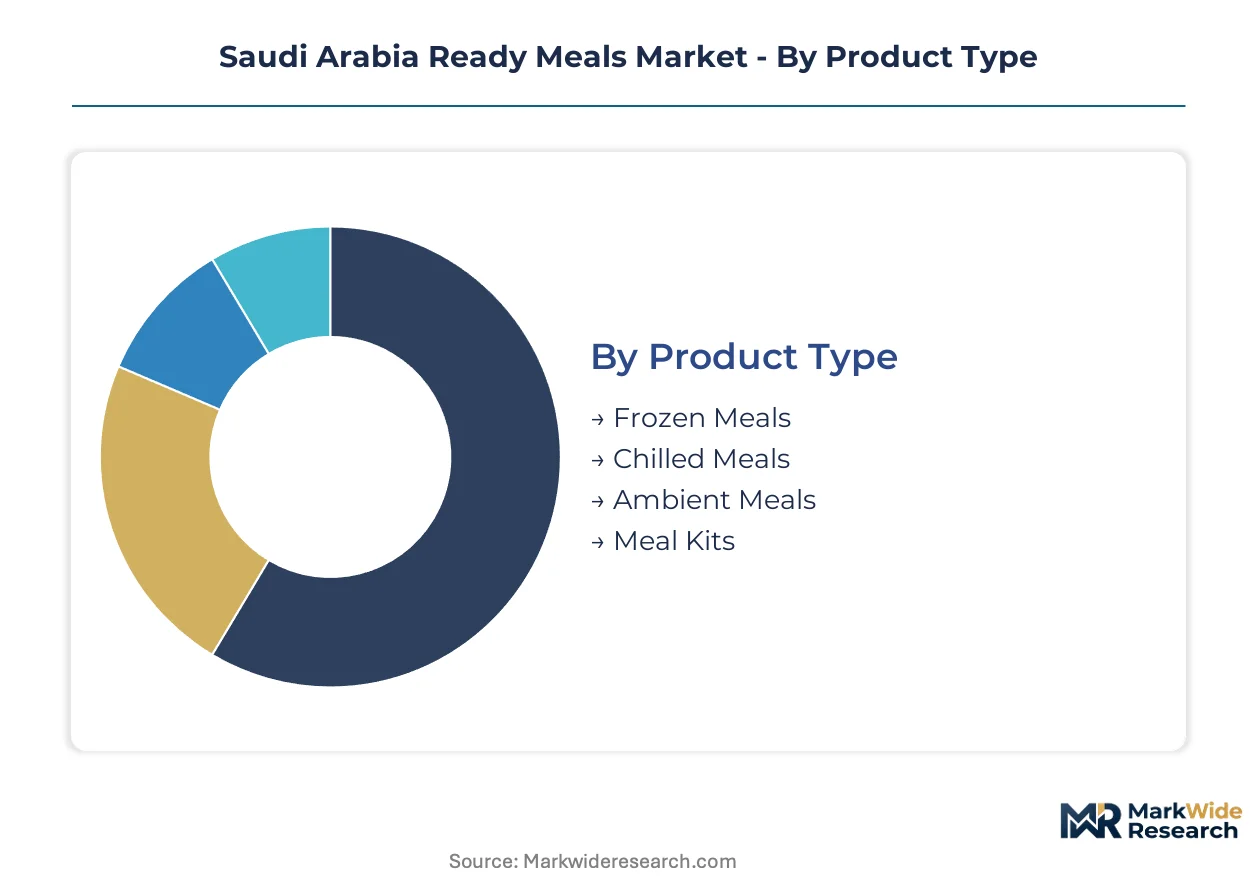
Ready meal segmentation in Saudi Arabia reflects divergent consumption velocities across product formats and channel tiers. Cycle-time variations between frozen inventory turns and chilled freshness windows create distinct margin profiles that shape producer investment priorities.
Product Type:
Chilled formats rotate through retail channels fastest while frozen stock turns slowest due to extended shelf stability and bulk purchasing patterns.
- Frozen Meals:Blast-chilled and flash-frozen products achieve 12-18 month stability through sub-zero cold chain maintenance. Riyadh hypermarkets move the highest frozen volumes as dual-income households stockpile protein-centric formats for weekday deployment.
- Chilled Meals:Refrigerated products with 7-14 day shelf life command freshness premiums through HPP treatment and clean-label positioning. Jeddah convenience channels are absorbing expanding chilled facings as young professionals prioritize perceived quality over extended storage.
- Ambient Meals:Retort-processed shelf-stable trays operate without refrigeration through thermal sterilization protocols. SFDA additive restrictions are compressing formulation flexibility for this segment.
- Meal Kits:Portioned ingredient bundles with recipe cards require consumer cooking involvement. Subscription mechanics in Dammam are attracting digitally native demographics seeking customization without full scratch preparation.
Frozen meals anchor the volume base while meal kits gain share at the steepest rate.
Packaging Type:
Cost tier stratification separates premium-positioned formats from commodity vessels, with material specifications directly determining retail channel eligibility and price realization.
- Tray:Microwave-compatible rigid containers dominate retail shelf presence through visual product visibility and stackability. Riyadh supermarkets allocate prime facing space to tray formats across all temperature states.
- Bowl:Round vessels suit soup, curry, and rice-based Arabic cuisine applications. Chilled bowl adoption is climbing fastest in Jeddah urban convenience networks.
- Pouch:Flexible retort pouches reduce shipping cube and material cost for ambient-stable formats. SASO technical regulations govern seal integrity standards for this packaging class.
- Can:Metal containers persist in institutional and emergency stockpiling applications with minimal retail presence.
Tray formats capture the broadest retail distribution while bowl configurations expand most quickly in premium chilled applications.
Distribution Channel:
Volume concentration clusters in high-throughput retail while customer type fragmentation drives online and foodservice experimentation.
- Supermarkets:Hypermarket and supermarket chains control the majority of ready meal throughput through destination shopping trips. Riyadh and Jeddah retail infrastructure supports extensive chilled and frozen facing allocation.
- Convenience Stores:Small-format urban outlets serve immediate consumption and top-up purchasing with single-serve and grab-and-go positioning. Jeddah convenience penetration is deepening through 24-hour operations.
- Online Retail:E-commerce platforms and subscription services aggregate demand from dispersed households. Meal kit logistics require specialized cold chain fulfillment that concentrates in major metropolitan zones.
- Food Service:Hotels, corporate catering, and airline meal programs procure bulk ready meal formats. SFDA halal certification mandates apply uniformly across institutional procurement.
Supermarkets anchor the volume base while online retail gains share at the steepest rate.
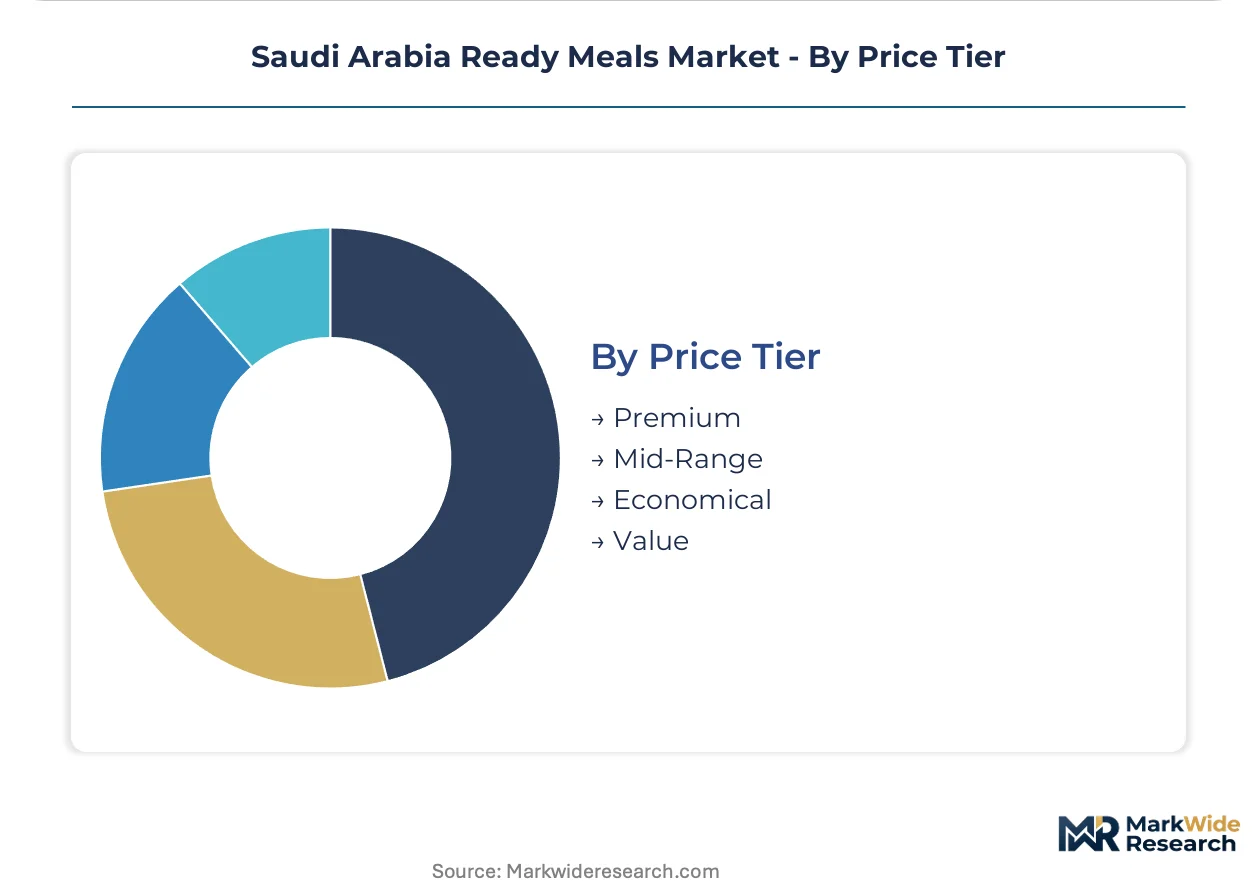
Price Tier:
Margin stratification across certification grades and ingredient sourcing intensity separates positioning tiers rather than simple quality gradation.
- Premium:Organic, imported, or specialty diet formats command shelf space through clean-label credentials and premium protein sourcing. Chilled premium facings are expanding fastest in Jeddah high-income districts.
- Mid-Range:Branded mainstream products balance convenience and familiarity for routine household purchasing. This tier absorbs the most competitive pressure from private label expansion.
- Economical:Value-positioned formats prioritize caloric density and shelf stability over ingredient complexity. Frozen economical trays dominate bulk purchasing in Riyadh suburban hypermarkets.
- Value:Deep-discount and promotional formats serve price-sensitive segments through simplified recipes and reduced packaging cost.
Economical tiers anchor the volume base while premium positioning gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Abdullah Port on the Red Sea anchors Western Region distribution networks, while the Gulf railway corridor underwrites Eastern Province supply chain integration with Riyadh consumption centers.
Riyadh
Dual-income household density in the capital generates the highest frozen meal throughput among Saudi cities. SFDA enforcement protocols here set the national standard for halal certification documentation. Hypermarket chains in Riyadh's northern districts allocate expanding chilled facings to capture premium-seeking professionals.
Jeddah
The Red Sea port infrastructure positions Jeddah as the primary entry node for imported ingredient streams and processing equipment. Municipal food safety inspections here operate with stricter documentation requirements than inland jurisdictions. Convenience store networks in Jeddah's urban core are absorbing the fastest chilled meal penetration rates nationally.
Eastern Province
Industrial city concentrations around Dammam and Jubail host food manufacturing clusters serving institutional procurement channels. SASO technical regulation updates for packaging materials originate from testing facilities in this region. Aramco employee housing compounds generate concentrated demand for Western-style ready meal formats.
Makkah Region
Pilgrimage-driven foodservice demand creates seasonal spikes in bulk ready meal procurement that outpace residential consumption patterns. Religious tourism regulations administered by the Ministry of Hajj and Umrah shape catering supply chain requirements. Taif's agricultural processing facilities supply ingredient streams to Riyadh and Jeddah manufacturers.
NEOM Northwest
The giga-project zone is incubating cold chain infrastructure specifications that may diffuse to national standards upon completion. Regulatory sandboxes here allow experimental shelf-life extension technologies under SFDA monitoring. Trojena and The Line construction sites currently represent concentrated institutional ready meal demand nodes.
Saudi Arabia Ready Meals Market Competitive Landscape
On the supply side, the industry is consolidating around integrated food conglomerates with captive cold chain assets and dairy-forward production networks. Three strategic archetypes dominate: vertically integrated agribusiness operators controlling upstream ingredient supply, specialized Arabic cuisine processors leveraging traditional recipe portfolios, and multinational protein processors adapting global formats to local halal requirements. Competitive moves center on backward integration into ingredient sourcing and portfolio diversification across temperature states.
Within the integrated conglomerate tier, Almarai Company exemplifies the dairy-forward archetype through its captive refrigeration infrastructure, while Americana Group anchors multi-brand portfolio strategies across price tiers. Sunbulah Group occupies a specialized position representing Arabic cuisine format expertise that Western-style entrants struggle to replicate.
| Leading Market Players |
|---|
| Sunbulah Group |
| Americana Group |
| Almarai Company |
| Almunajem Foods |
| Al Kabeer Group |
| Al Watania |
| JBS Foods SA |
| Al Karamah Dough Production Co. Ltd |
| Supreme Foods Processing Company |
| Others |
Value Network & Pricing Analysis
The King Abdullah Port freight corridor on the Red Sea anchors logistics cost dynamics that concentrate supply power among integrated producers while enabling downstream price differentiation across freshness-positioned tiers. SFDA halal certification mandates and SASO packaging regulations compound entry costs, allowing incumbent cold chain operators to sustain margin capture against fragmented import competition.
Pricing Analysis
Volume-discount tiering separates premium chilled formats from frozen economy trays, with price differentiation resting on halal certification grade and captive cold chain ownership. Three-tier pricing structure across premium, standard, and economy levels is compressing mid-range margins as private label expansion intensifies. Cost compression in ambient-stable segments stems from reformulation expenses under tightening additive restrictions. Institutional foodservice buyers exhibit lowest price sensitivity, while suburban hypermarket shoppers in Riyadh drive volume through promotional economy stockpiling.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated agribusiness operators like Almarai and Americana that control captive blast chilling and HPP treatment capacity. Geographic supply concentration draws from Saudi domestic wheat processing, Malaysian palm oil streams, and Brazilian protein imports. Raw material dependencies hinge on regional grain traders, Red Sea shipping lanes, and specialized halal slaughter facilities. Single-source vulnerability concentrates in chilled logistics networks where qualified technician scarcity constrains capacity expansion. Distribution runs through hypermarket destination channels with convenience store top-up layering in Jeddah and Riyadh urban cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against scratch cooking resurgence and foodservice delivery platforms that capture convenience-oriented households. Incumbents must fortify freshness positioning and channel control to retain wallet share against these alternatives.
For Market Incumbents: Entrench halal certification barriers by deepening captive cold chain infrastructure in Riyadh and Jeddah distribution nodes. Accelerate HPP technology deployment to extend chilled shelf life without chemical preservatives, creating defendable margin pools that import-dependent entrants cannot replicate. Prioritize convenience store facing expansion in Jeddah's 24-hour urban networks before Western-style competitors establish shelf presence.
For New Entrants and Emerging Players: Eastern Province industrial compounds around Dammam represent underpenetrated institutional demand clusters where Aramco employee housing generates concentrated Western-format appetite. Target meal kit subscription mechanics in Dammam's digitally native professional demographic, leveraging subscription lock-in to bypass entrenched retail shelf allocation. Pursue co-manufacturing partnerships with established cold chain operators to circumvent SFDA compliance timeline disadvantages.
For Investors and Strategic Acquirers: Specialized Arabic cuisine processors with traditional recipe portfolios and regional brand equity present acquisition targets with replication moats against multinational entrants. Long-term viability hinges on cold chain infrastructure ownership rather than brand licensing alone. Watch for municipal inspection protocol harmonization across Riyadh, Jeddah, and Dammam as inflection signal for multi-city distribution scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Protein Sourcing | Captive halal slaughter capacity secures SFDA compliance and insulates margins from import volatility. |
| HPP Technology Deployment | High-pressure processing extends chilled shelf life without preservatives, unlocking premium retail facings. |
| Meal Kit Subscription Launch | Subscription mechanics in Dammam and Jeddah attract younger demographics seeking customization without full preparation. |
| Convenience Channel Expansion | 24-hour urban outlet penetration in Jeddah captures top-up purchasing from time-compressed professionals. |
| Arabic Cuisine Format Specialization | Traditional dish portfolios differentiate against Western-style entrants in both retail and foodservice channels. |
Research Methodology
Initial hypotheses were tested against primary input from ready meal brand managers, hypermarket category buyers, cold chain logistics directors, and SFDA regulatory affairs specialists and refined through secondary validation. Saudi customs trade records, SFDA halal certification registries, SASO technical regulation filings, and Nielsen retail audit data anchored quantitative baselines. Bottom-up volume modeling across temperature states and packaging formats triangulated against top-down consumption expenditure estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product temperature state, packaging configuration, distribution channel tier, and price positioning. CAGRs were derived from installed cold chain capacity expansion trajectories and household formation velocity in Riyadh and Jeddah metropolitan zones. Urban professional clustering patterns and municipal enforcement protocol convergence served as industry-specific forecast inputs.
Practitioners should monitor SFDA additive restriction evolution, wheat import tariff adjustments, and HPP equipment deployment rates for early signals of margin compression or technology disruption. Forecasts reflect assumptions about sustained dual-income household formation and continued cold chain infrastructure investment. Quarterly review of municipal inspection harmonization progress and meal kit subscription cancellation rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Alginate Casings Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Tortilla Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Fat Free Pasta Market