
 Private Label Food and Beverage Market | 2026-2036
Private Label Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Private Label Food and Beverage Market Outlook
AI-powered demand forecasting is rewriting how retailers anticipate category-level purchasing patterns and optimize private-label assortment depth. Kroger leverages proprietary consumer data analytics to calibrate store-brand innovation pipelines against regional taste preferences. Costco sustains exceptional private-label loyalty through Kirkland Signature's quality parity with national brands at sustained price advantages. Trader Joe's differentiates through curated, exclusive product architectures that occupy a distinct market position between conventional and specialty retail.
Private label food and beverage encompasses retailer-owned brands spanning formulated, processed, and packaged consumables, typically manufactured through third-party co-packers or captive production facilities using specifications set by the retail brand owner. These products serve commercial purposes centered on margin capture, customer retention, and price-tier segmentation within retail portfolios. Beverages and dairy products represent mature, high-volume segments where margin pools remain attractive despite intense competitive pressure from established national brands. Snacks and frozen foods present faster growth trajectories as retailers invest in flavor innovation and clean-label reformulations to compete with PepsiCo and Nestlé offerings.
The FDA governs ingredient safety, nutritional labeling, and health claim substantiation for private-label products sold in the United States, while the USDA oversees organic certification and meat and poultry inspection standards that many store brands now pursue. State-level bottle deposit laws and emerging extended producer responsibility frameworks in California and New York are adding compliance layers that reshape packaging procurement decisions. Stakeholders must monitor how FDA enforcement priorities around sodium reduction and added-sugar disclosure evolve, as these standards will determine which private-label formulations retain shelf space and promotional support.
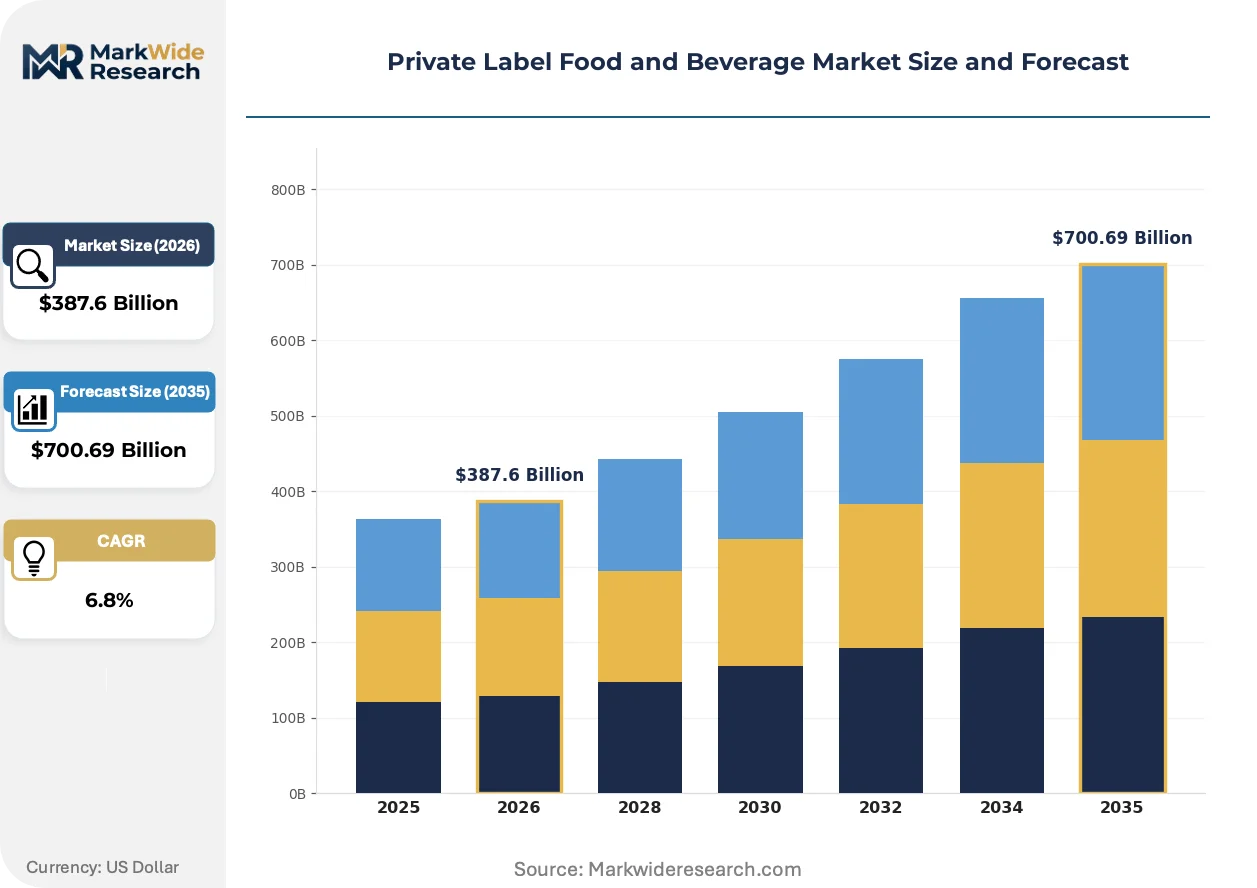
Market Dynamics
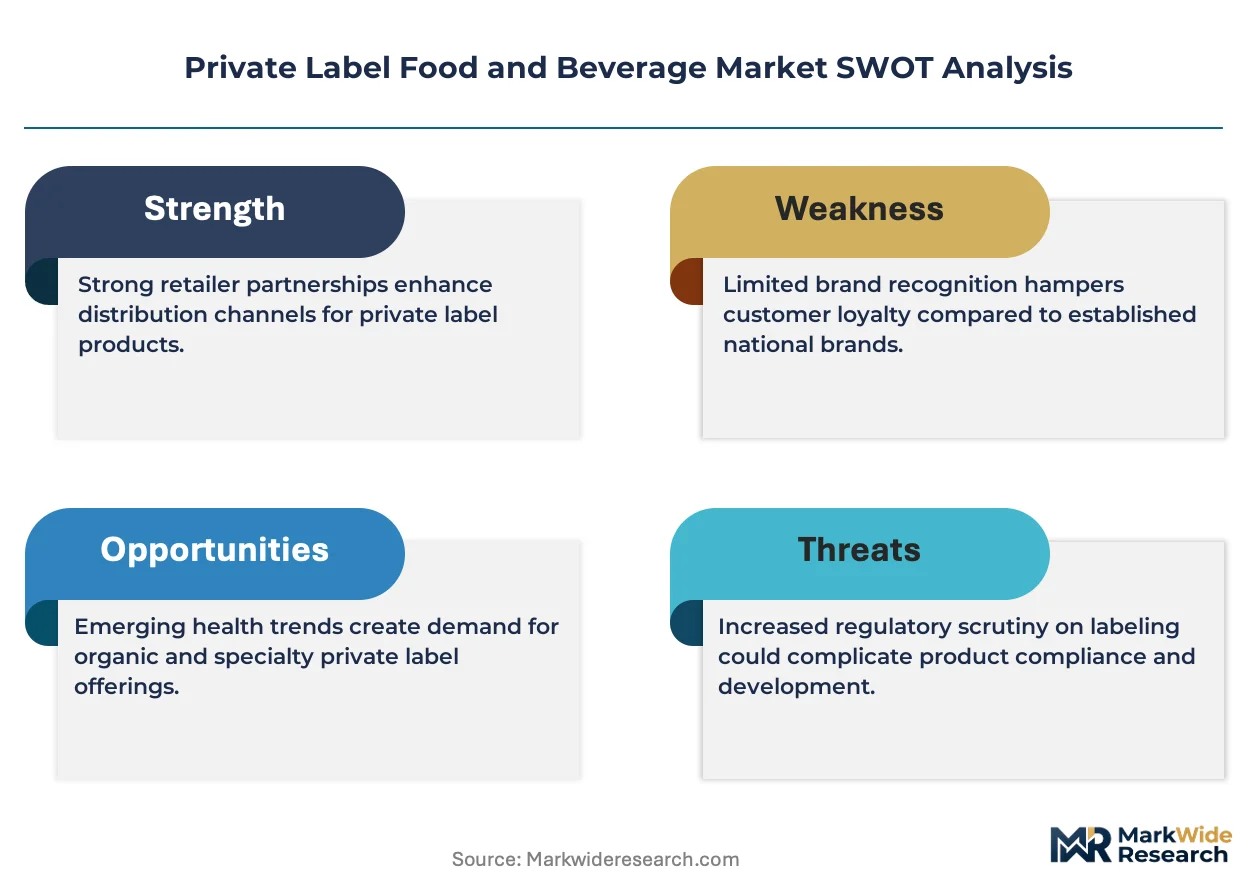
Supermarket chains are weaponizing first-party consumer data to compress product development cycles and displace national brands through predictive demand modeling. This data advantage is hybridizing with co-packer networks to accelerate private-label innovation velocity.
Growth Catalysts
- USDA Organic Certification:Federal organic standards create premium tier differentiation that captures margin expansion in dairy and packaged goods categories.
- Clean-label enzyme technologies:Novel processing methods enable shorter ingredient declarations that satisfy FDA disclosure requirements without sacrificing shelf stability.
- India:Modern retail penetration and FSSAI standardization are unlocking private-label development in food and beverage categories previously dominated by unorganized sector production.
Market Restraints
- Input cost volatility:Wheat and dairy commodity swings compress private-label margin buffers that lack national brand pricing power to pass through increases.
- Co-packer concentration:North American contract manufacturing capacity clusters with a limited supplier base, creating bottleneck risk during demand surges.
- Technical limitation:Clean-label reformulation struggles to replicate the extended shelf life and texture stability of conventional additive-dependent formulations.
Strategic Opportunities
- Brazil:ANVISA regulatory harmonization and modern trade expansion create white space for private-label penetration in beverages and frozen foods.
- Direct-to-retailer import channels:Bypassing traditional distributor layers enables margin recapture and exclusive SKU development for warehouse club formats.
- EU Green Deal packaging mandates:Extended producer responsibility frameworks incentivize retailer investment in recyclable mono-material packaging that national brands delay adopting.
Industry Challenges
- Reformulation talent scarcity:Food scientists capable of clean-label product development command premium compensation that strains private-label R&D budgets.
- Co-packer qualification timelines:FDA facility registration and third-party audit requirements extend supplier onboarding cycles that delay speed-to-market targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Private Label Food and Beverage Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Frozen Foods, Dairy Products Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Warehouse Clubs Customer Type: Cost-Conscious Shoppers, Health-Conscious Consumers, Families, Millennials Packaging Type: Flexible Packaging, Rigid Packaging, Bulk Packaging, Glass Containers |
| Companies Covered | CVS Health, Costco Wholesale, Walmart, Kroger, Amazon Fresh, Target, Family Dollar, Trader Joe's, Aldi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Private Label Food and Beverage Market Strategic Shifts
Artificial intelligence is compressing the gap between consumer insight and product launch, while regulatory pressure on ingredient transparency forces simultaneous investment in reformulation science and supply chain traceability infrastructure.
Machine learning demand forecasting is hybridizing with real-time sales data streams to enable micro-batch production scheduling. Mid-size grocery chains deploy these tools to calibrate store-brand assortment depth against hyperlocal purchasing patterns. The technology is hybridizing category management functions that previously required national brand scale to execute profitably.
REACH chemical restriction expansions in Europe are forcing reformulation of flavor systems and packaging adhesives used in private-label products. Manufacturers face substance substitution timelines that compress product development windows. Frozen food and ready-meal categories bear disproportionate compliance burden as these segments rely heavily on affected processing aids.
Buyer concentration among dollar-store and limited-assortment discounters is reshaping procurement specifications toward extreme price-point engineering. These retailers specify ingredient cost ceilings that dictate supplier selection and formulation compromises. Mexico and Southeast Asian manufacturing clusters capture disproportionate volume as sourcing shifts to meet these constraints.
Private Label Food and Beverage Market Segmentation
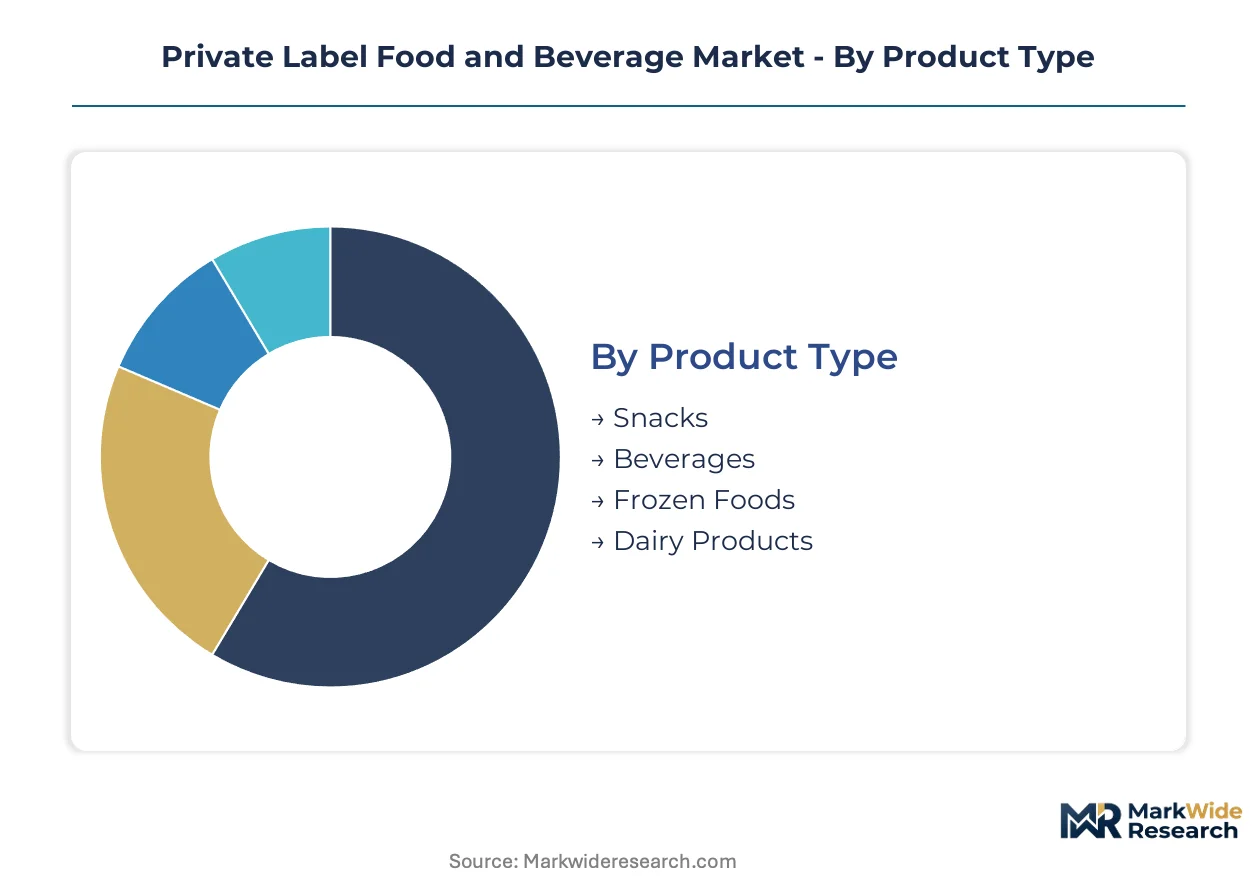
Private-label food and beverage segmentation reveals how retailers architect margin capture across distinct consumption occasions and purchasing contexts. Each dimension—product format, channel access, buyer motivation, and packaging specification—creates tiered pricing power that national brands struggle to replicate.
Product Type:
Retailers deploy distinct formulation strategies across consumption occasions, from impulse snacking to planned meal preparation.
- Beverages:High-velocity categories including carbonated soft drinks, bottled water, and functional drinks dominate private-label volume. Costco's Kirkland Signature and Kroger's Simple Truth capture repeat purchases through quality parity with Coca-Cola and PepsiCo offerings at sustained price advantages.
- Dairy Products:Milk, cheese, and yogurt represent mature margin pools where USDA Organic certification creates premium tier differentiation. Clean-label enzyme technologies enable shorter ingredient declarations that satisfy FDA disclosure requirements without sacrificing shelf stability.
- Snacks:Private-label chip and cracker innovation accelerates as retailers invest in flavor development to compete with PepsiCo and Nestlé portfolios.
- Frozen Foods:Ready meals and vegetable platforms present faster growth trajectories through clean-label reformulations targeting health-conscious households.
The dominant share belongs to Beverages, while Frozen Foods is closing the gap fastest through innovation investment in convenience-oriented formats.
Distribution Channel:
Channel economics dictate assortment depth, pricing architecture, and supplier qualification requirements for private-label programs.
- Supermarkets:Kroger, Albertsons, and regional chains leverage first-party consumer data to compress product development cycles and calibrate store-brand innovation against regional taste preferences. Predictive demand modeling enables micro-batch production scheduling previously requiring national brand scale.
- Warehouse Clubs:Costco sustains exceptional private-label loyalty through Kirkland Signature's quality parity with national brands at sustained price advantages. Bulk specifications and exclusive SKU development create defensible margin structures.
- Online Retailers:Amazon and Instacart deploy recommendation algorithms to surface private-label alternatives during search and replenishment workflows.
- Convenience Stores:Dollar General and Family Dollar concentrate procurement toward extreme price-point engineering, shifting sourcing to Mexico and Southeast Asian manufacturing clusters.
Supermarkets command the largest revenue footprint, though Warehouse Clubs extract superior per-unit margins through membership-driven volume commitments.
Customer Type:
Buyer motivation segments determine formulation investment, certification pursuit, and marketing communication strategy.
- Cost-Conscious Shoppers:Inflation-weary households trade down from national brands without compromising core quality expectations, expanding private-label addressable market.
- Health-Conscious Consumers:Clean-label and organic certification requirements drive supplier selection and ingredient cost premiums that reshape margin architecture.
- Families:Multi-person households prioritize value-oriented pack sizes and predictable quality for repeat purchase categories.
- Millennials:Digital-native buyers respond to transparent sourcing narratives and sustainability credentials that influence retailer ESG investment priorities.
Cost-Conscious Shoppers generate the highest transaction frequency, yet Health-Conscious Consumers deliver premium margin expansion through certification-driven tiering.
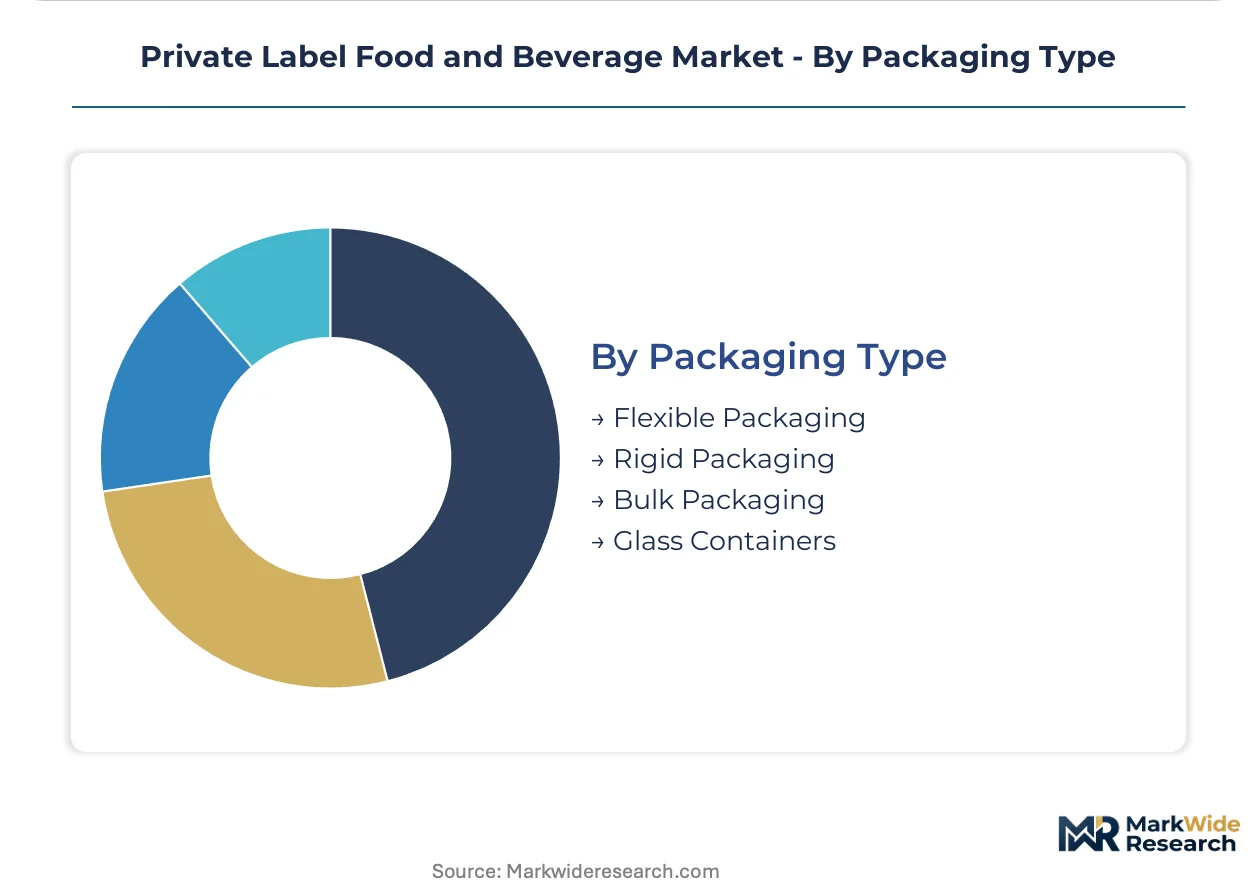
Packaging Type:
Material specifications increasingly reflect regulatory pressure and circular economy commitments rather than purely cost optimization.
- Flexible Packaging:Pouches and films dominate snack and frozen food applications where lightweight logistics create distribution cost advantages.
- Rigid Packaging:Bottles and cartons serve beverage and dairy categories requiring structural integrity and shelf presence.
- Glass Containers:Premium positioning in sauces and specialty beverages leverages perceived quality and infinite recyclability, though logistics costs constrain geographic distribution.
- Bulk Packaging:Warehouse club and foodservice formats minimize per-unit material cost while maximizing volume throughput efficiency.
Flexible Packaging maintains volume leadership, while Glass Containers expands most quickly among sustainability-positioned premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States private-label exporters supply warehouse club and supermarket formats across Canada and Mexico, while European retailers source Mediterranean and Eastern European manufacturing clusters to serve price-sensitive consumer bases.
United States
Kroger and Costco anchor North American private-label volume through billion-dollar store-brand ecosystems spanning beverages, dairy, and frozen foods. FDA updated Nutrition Facts labeling requirements and sodium reduction enforcement priorities reshape formulation decisions for products sold across state lines. Chicago and Cincinnati metropolitan areas concentrate retailer headquarters and co-packer qualification facilities where predictive demand modeling accelerates product development cycles.
Germany
Discounters Aldi and Lidl drive European private-label penetration through extreme price-point engineering and quality parity positioning against national brands. EU Green Deal packaging mandates and REACH chemical restrictions force reformulation of flavor systems and adhesives in frozen food segments. The Rhine-Ruhr industrial corridor hosts co-packer networks serving private-label programs across Central European markets.
India
Modern retail expansion by Reliance Retail and D-Mart unlocks private-label development in beverages and packaged snacks previously dominated by unorganized sector production. FSSAI standardization of food safety requirements creates compliance frameworks that enable branded store-tier differentiation. Maharashtra and Karnataka states concentrate manufacturing capacity where clean-label enzyme technologies enable shorter ingredient declarations.
Brazil
Supermarket chains GPA and Carrefour Brasil expand private-label portfolios as inflation-weary households trade down from multinational brands in beverages and frozen foods. ANVISA regulatory harmonization with Mercosur standards reduces cross-border formulation complexity for regional product lines. São Paulo state anchors co-packer networks serving Southeast Brazilian metropolitan demand clusters.
United Kingdom
Tesco and Sainsbury's deploy first-party consumer data to compress private-label innovation cycles against regional taste preferences in dairy and ready-meal categories. Extended producer responsibility frameworks and plastic packaging taxes reshape procurement specifications toward recyclable mono-material formats. The Midlands region concentrates food manufacturing facilities where clean-label reformulation investments compete with Nestlé and PepsiCo offerings.
Private Label Food and Beverage Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market structures where scale advantages fragment against curation-based differentiation. Supermarket chains and warehouse clubs leverage first-party data and membership-driven volume commitments to capture margin pools. Three archetypes dominate: data-integrated retail ecosystems, quality-parity warehouse club operators, and curated-assortment specialty retailers. Competitive moves concentrate on predictive analytics deployment and exclusive SKU development through direct-import channels.
Among North American retail ecosystems, Costco Wholesale, Kroger, and Walmart exemplify scale-driven private-label architectures. Costco Wholesale anchors membership-based loyalty through sustained price advantages. Kroger represents data-integrated innovation velocity calibrated against regional preferences. Walmart occupies a position spanning extreme value tiers through Family Dollar integration and premium-adjacent lines via Walmart private brands. CVS Health and Target sit within health-and-wellness-positioned tiers where store-brand portfolios capture pharmacy and grocery crossover demand.
| Leading Market Players |
|---|
| CVS Health |
| Costco Wholesale |
| Walmart |
| Kroger |
| Amazon Fresh |
| Target |
| Family Dollar |
| Trader Joe's |
| Aldi |
| Others |
Value Chain & Pricing Dynamics
Co-packer undercapacity in North America during seasonal demand surges drives both supplier qualification backlogs and pricing volatility for private-label buyers. This utilization squeeze compresses margin buffers as retailers compete for limited contract manufacturing slots.
Pricing Analysis
Clean-label enzyme technology pricing gaps separate current-generation formulations from conventional additive-dependent alternatives and next-generation bioengineered platforms. Three-tier pricing structure across premium organic, standard clean-label, and economy conventional levels dominates private-label portfolios. Price differentiation rests on USDA Organic certification tier and volume scale commitments. Pricing pressure stems from wheat and dairy commodity swings that outpace retailer pricing power. Dollar-store buyers exhibit extreme price sensitivity, while warehouse club members accept modest premiums for quality parity.
Supply Chain Analysis
FDA facility registration requirements function as export-control-style barriers limiting co-packer qualification velocity for new market entrants. Supply concentrates in the United States, Mexico, and Southeast Asian manufacturing clusters for cost-engineered tiers. Raw material dependencies include wheat derivatives, dairy proteins, and clean-label stabilizers. Single-source vulnerability pervades North American contract manufacturing where limited suppliers create bottleneck risk. Distribution runs through retailer-controlled direct-import channels that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-powered demand forecasting is reshaping private-label food and beverage as a high-growth disruption. FDA sodium reduction enforcement priorities create regulatory inflection points that determine which formulations retain shelf space.
For Market Incumbents: Entrench data-integrated innovation pipelines by deepening proprietary consumer analytics capabilities against regional taste preferences. Expand captive co-packer relationships in underutilized manufacturing corridors to secure capacity ahead of seasonal surges. Vertical integration into clean-label enzyme technology sourcing mitigates reformulation talent scarcity threatening speed-to-market targets. For New Entrants and Emerging Players: Build out white-space positions in Brazil's beverage and frozen food segments where ANVISA regulatory harmonization reduces cross-border complexity. Target India's modern retail expansion zones where FSSAI standardization enables branded store-tier differentiation against unorganized sector production. Direct-to-retailer import channel development unlocks margin recapture and exclusive SKU access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across clean-label reformulation infrastructure as FDA disclosure requirements tighten. Five-to-ten-year viability favors platforms with integrated data analytics and co-packer network control. Acquisition target archetype: mid-size grocery chains with underutilized private-label development capabilities. Signal to watch: FDA enforcement priority shifts around added-sugar disclosure timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Novel enzyme technologies enable shorter ingredient declarations satisfying FDA disclosure without sacrificing shelf stability. |
| Direct-to-Retailer Import Channel Development | Bypassing distributor layers captures margin and enables exclusive SKU architectures for warehouse club formats. |
| Co-Packer Network Expansion | Qualifying underutilized manufacturing capacity mitigates bottleneck risk during seasonal demand surges. |
| AI-Powered Demand Forecasting Deployment | Machine learning hybridized with real-time sales data enables micro-batch production scheduling against hyperlocal patterns. |
| Recyclable Mono-Material Packaging Transition | EU Green Deal mandates and extended producer responsibility frameworks incentivize retailer investment ahead of national brand delays. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with retail category managers, co-packer operations directors, food science R&D leads, and regulatory affairs specialists. Secondary validation drew from FDA enforcement guidance documents, USDA organic certification databases, FSSAI standardization notices, ANVISA regulatory harmonization filings, and customs trade flow records. Bottom-up SKU-level demand modeling and top-down retailer revenue triangulation anchored market sizing.
Calibration approached volume and value outputs through segment-level elasticity modeling across product type, distribution channel, customer motivation, and packaging specification dimensions. CAGRs were derived from trend extrapolation against historical volume inflection points. Forecast inputs incorporated co-packer capacity utilization rates, commodity price trajectory assumptions, and regulatory enforcement timeline scenarios.
Stress conditions across wheat and dairy commodity volatility bands, FDA sodium reduction enforcement intensity, and co-packer concentration scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean-label technology adoption curves and modern retail penetration rates. Material shifts in FDA disclosure requirement timelines or extended producer responsibility framework implementations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Ready Meals Market
Packaged Foods
Fruit Filling Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Canned Soup Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Sausage Casing Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Canned Food Market