
 Chemotherapy Induced Peripheral Neuropathy Treatment Market | 2026-2036
Chemotherapy Induced Peripheral Neuropathy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy Induced Peripheral Neuropathy Treatment Market Intelligence
A strategic shift from single-source API contracts to multi-source procurement is decoupling drug formulation from raw material dependency for many pharmaceutical manufacturers. Takeda Pharmaceutical Company Limited leverages its extensive global oncology portfolio to effectively cross-promote its supportive care treatments. Vertex Pharmaceuticals Incorporated differentiates by specializing in novel mechanisms that target the underlying pathways of neuropathic pain. Sanofi sustains its significant market presence through a broad distribution network reaching both specialty clinics and major hospitals worldwide.
Chemotherapy induced peripheral neuropathy treatment encompasses interventions to manage nerve damage resulting from cytotoxic agents like taxanes and platinum compounds. The primary therapeutic goal is to alleviate debilitating symptoms, including neuropathic pain and motor dysfunction, which can limit the effectiveness of cancer treatment. Analgesics and anticonvulsants represent the largest product segments, forming the first line of defense against neuropathic pain. Oncology centers remain the principal end-user setting, where CIPN management is a core component of comprehensive cancer care.
The US FDA's framework for drug approval prioritizes clear evidence of symptomatic relief, which heavily influences clinical trial design. Global standards from the WHO on pain management also inform treatment guidelines adopted by many national health systems. Concurrently, the European Medicines Agency (EMA) and Japan's PMDA mandate comprehensive safety data before granting market access. Future investment will concentrate on novel therapeutic targets that can demonstrate clinical superiority in biomarker-defined patient groups.
Market Dynamics
The imperative to validate therapeutic efficacy through patient-reported outcomes is the central force shaping the market. Regulatory bodies, led by the US FDA, are prioritizing symptomatic relief and quality of life metrics, compelling a redesign of clinical trial endpoints for CIPN therapies.
Growth Catalysts
- Supportive Care Integration:Oncology centers are expanding their service lines to include dedicated supportive care units, making CIPN management a standard component of comprehensive cancer treatment protocols and increasing prescription volumes.
- Regulatory Frameworks:The FDA's guidance emphasizing patient-reported outcomes in clinical trials accelerates the development pathway for drugs that can demonstrate clear symptomatic relief, attracting investment into novel analgesics.
- High Cancer Prevalence:Sustained high incidence rates of cancer in developed nations, particularly the United States, ensure a large and consistent patient population requiring treatment for chemotherapy side effects like peripheral neuropathy.
Market Restraints
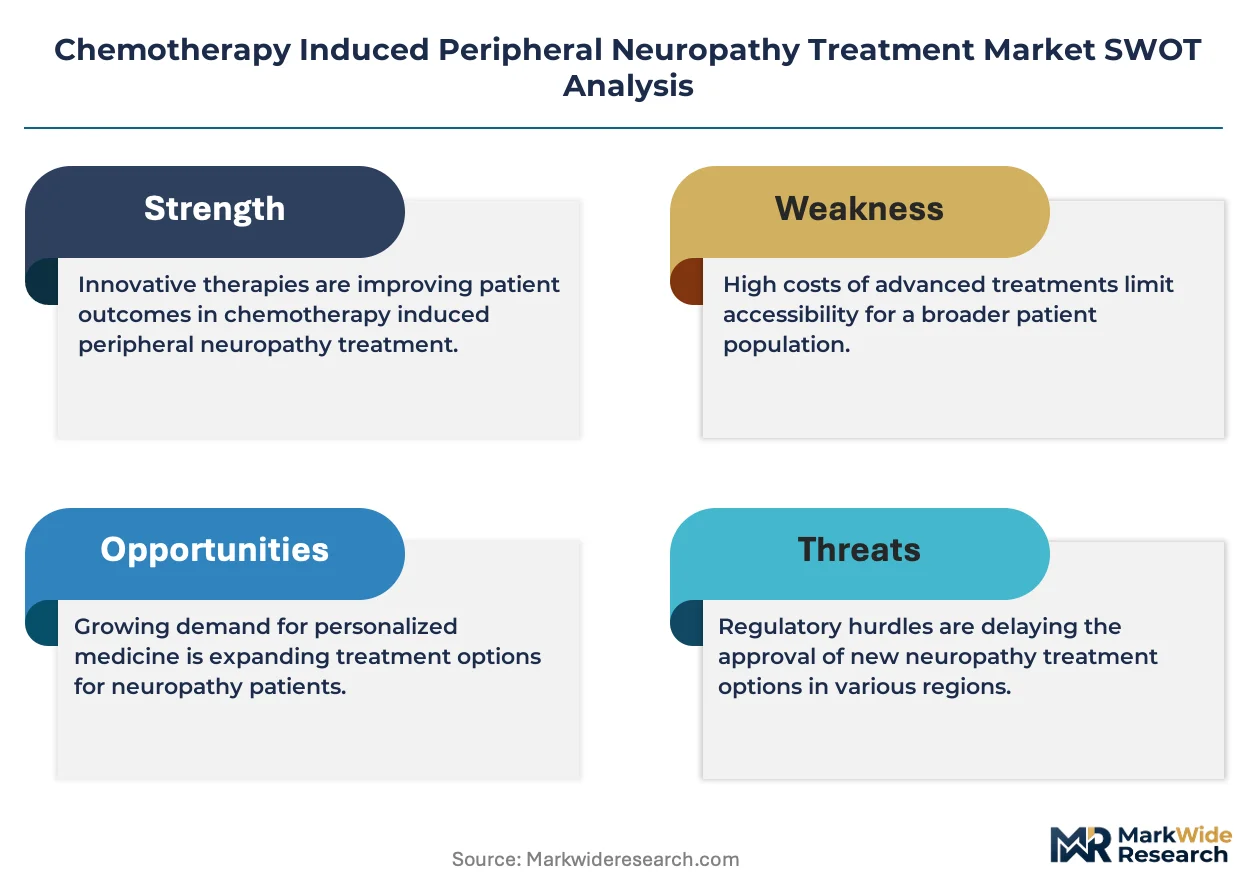
- Diagnostic Ambiguity:The absence of definitive biomarkers to predict or objectively measure CIPN severity complicates patient stratification for clinical trials and hinders the development of targeted therapies.
- Generic Competition:Widespread off-label use of inexpensive, generic anticonvulsants and antidepressants as first-line treatments for neuropathic pain limits market penetration for newer, premium-priced specialty drugs.
- Stringent Safety Hurdles:Regulators like the European Medicines Agency (EMA) and Japan's PMDA require extensive long-term safety data, creating significant barriers and timelines for market authorization of new CIPN treatments.
Strategic Opportunities
- Neuroprotective Agents:A significant opportunity exists in developing and marketing neuroprotective agents that can be administered prophylactically with chemotherapy to prevent or mitigate nerve damage from occurring.
- Biomarker Discovery:Investment in genomic and proteomic research to identify predictive biomarkers for CIPN can unlock the development of personalized therapies tailored to specific patient profiles and chemotherapy regimens.
- Emerging Market Expansion:Increasing healthcare expenditure and improving access to advanced cancer care in large markets, including China and Brazil, present untapped geographic expansion opportunities for established CIPN therapies.
Industry Challenges
- Subjective Clinical Endpoints:The reliance on subjective patient-reported pain scales complicates clinical trial execution, often requiring larger sample sizes and longer durations to establish statistically significant efficacy.
- Reimbursement Negotiation:Securing favorable reimbursement status from public and private payers for symptomatic treatments is a persistent challenge, as payers often prioritize therapies with proven survival benefits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy Induced Peripheral Neuropathy Treatment Market |
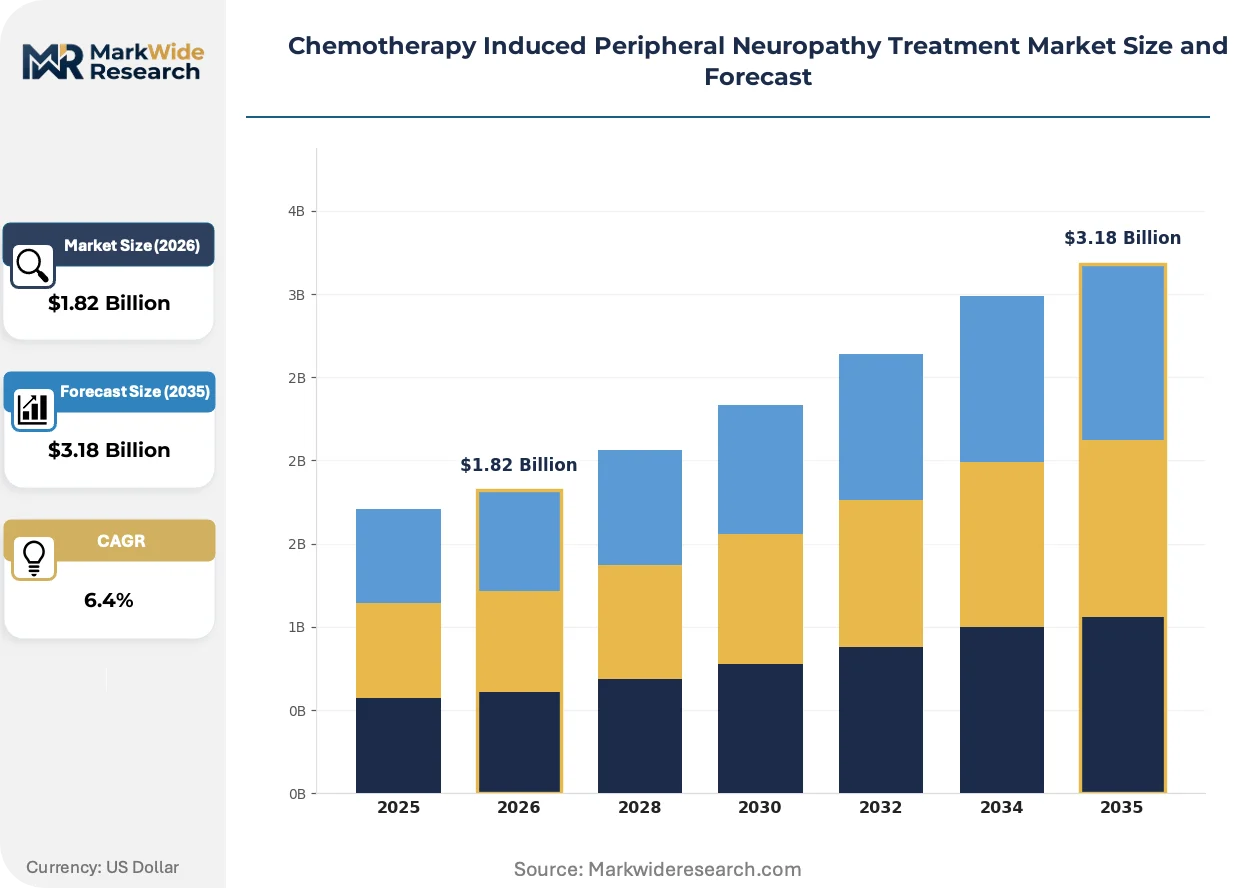
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Anticonvulsants, Antidepressants, Topical Agents, Nutraceuticals Therapy Area: Neuropathic Pain, Sensory Dysfunction, Motor Dysfunction, Autonomic Dysfunction End User: Oncology Centers, Specialty Clinics, Home Healthcare Providers, Rehabilitation Facilities Delivery Mode: Oral, Transdermal, Intravenous, Sublingual |
| Companies Covered | Sanofi, Takeda Pharmaceutical Company Limited, F. Hoffmann-La Roche Ltd, Amgen Inc., Abbott Laboratories, Vertex Pharmaceuticals Incorporated, Sun Pharmaceutical Industries Ltd, Teva Pharmaceuticals, Aurobindo Pharma Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy Induced Peripheral Neuropathy Treatment Market Strategic Shifts & Innovations
The evolution of CIPN treatment is defined by a move toward biologically targeted interventions. This shift is driven by a deeper understanding of the underlying pathophysiology of nerve damage, steering research away from generalized pain management toward mechanism-based therapies.
Biomarker-guided patient selection represents a pivotal technological evolution. This approach uses genetic or proteomic markers to identify patient subgroups most likely to develop CIPN or respond to a specific neuroprotective or therapeutic agent. Clinical research organizations and pharmaceutical firms are increasingly embedding these strategies into trial designs, which is consolidating R&D focus toward precision medicine and away from one-size-fits-all symptomatic treatments.
Global regulatory harmonization efforts, influenced by guidelines from the WHO, are impacting clinical development. These standards encourage the use of consistent measurement tools and endpoints for pain and neuropathy across international trials. The anticonvulsant and analgesic segments are most affected, as companies must now generate data that satisfies the distinct evidence requirements of the FDA, EMA, and PMDA simultaneously to achieve global market access.
A significant change in care delivery is the formal integration of CIPN management into long-term cancer survivorship plans. This trend shifts the locus of care from being exclusively within acute oncology settings to a collaborative model involving primary care providers and specialized neurology clinics. This integrated pathway is most developed in countries with robust primary care systems, such as Canada and the United Kingdom, ensuring continued management of chronic neuropathic symptoms post-chemotherapy.
Chemotherapy Induced Peripheral Neuropathy Treatment Market Segmentation
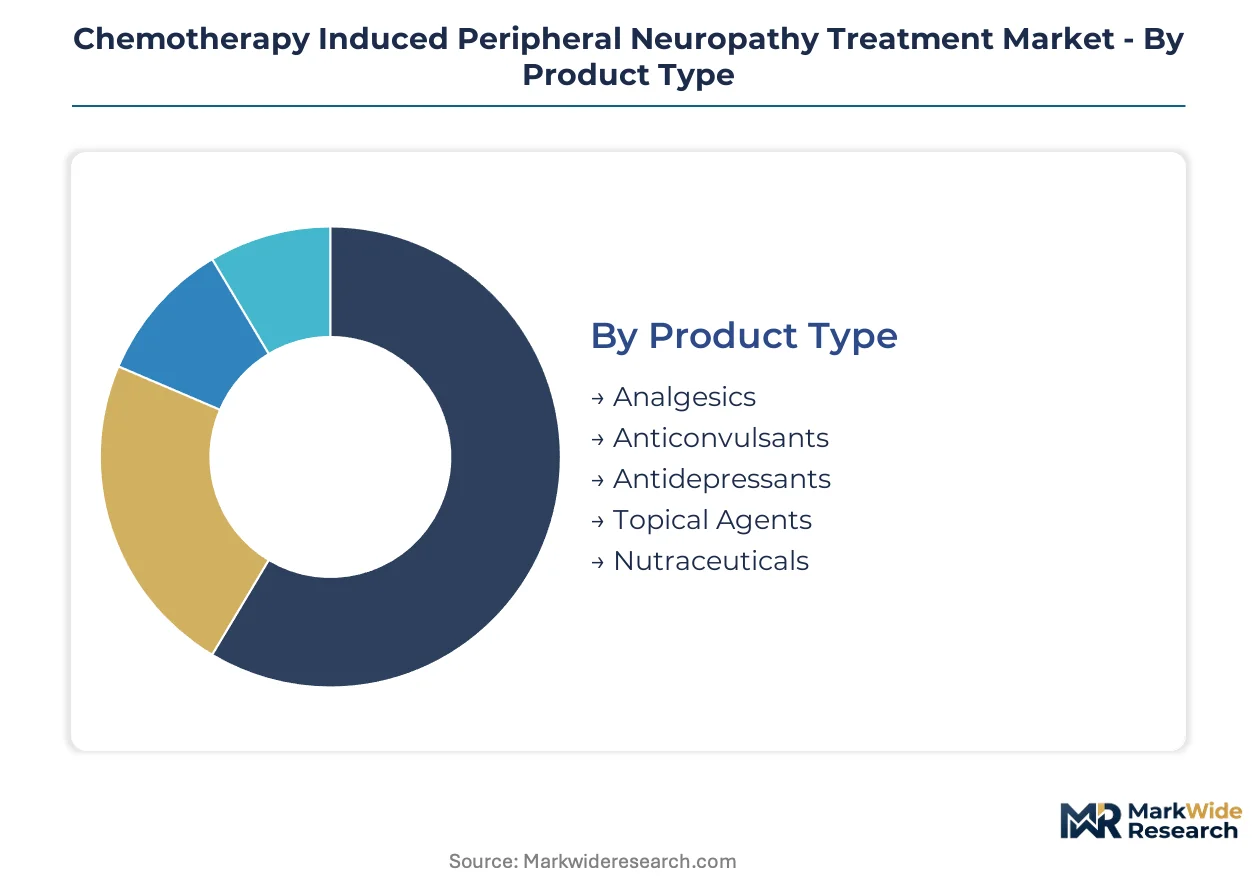
Segmentation within the chemotherapy-induced peripheral neuropathy treatment market is crucial for understanding diverse patient needs and tailoring therapeutic interventions. This detailed breakdown illuminates where demand concentrates, how treatment modalities are evolving, and which end-user settings drive market expansion for supportive care.
Product Type:
Buyer decisions in product type are heavily influenced by the specific symptom profile and severity of chemotherapy-induced peripheral neuropathy.
- Analgesics:These pharmaceutical agents primarily target pain relief, often serving as the first line of defense against neuropathic discomfort. Demand concentrates in oncology centers where immediate symptomatic relief is prioritized to maintain patient quality of life during cancer treatment.
- Anticonvulsants:Originally developed for epilepsy, these drugs are widely used off-label to manage neuropathic pain by modulating nerve activity. Their widespread use and established efficacy drive significant prescription volumes across various clinical settings.
- Antidepressants:Certain antidepressants alleviate neuropathic pain by influencing neurotransmitter pathways involved in pain perception.
- Topical Agents:These localized treatments deliver pain relief directly to affected areas, minimizing systemic side effects for patients.
- Nutraceuticals:Comprising vitamins, minerals, and herbal extracts, these agents aim to support nerve health and mitigate damage.
Analgesics lead volumes today; Nutraceuticals are gaining share fastest.
Therapy Area:
Treatment strategies are directly tailored to the specific type of nerve damage and its manifestation within the therapy area.
- Neuropathic Pain:This segment encompasses interventions specifically designed to alleviate chronic nerve pain, a debilitating symptom that can severely impact patient adherence to chemotherapy. The US FDA's emphasis on symptomatic relief heavily influences clinical trial design for new therapies targeting this area.
- Motor Dysfunction:Therapies in this area address issues like muscle weakness, gait instability, and loss of fine motor skills, which can limit daily activities and treatment effectiveness. Research into novel mechanisms targets the underlying pathways of nerve damage to restore motor function.
- Sensory Dysfunction:This involves treatments for symptoms such as numbness, tingling, and altered sensations in the extremities.
- Autonomic Dysfunction:Management focuses on issues affecting involuntary bodily functions, including blood pressure regulation and digestive problems.
Neuropathic Pain management remains the primary focus for R&D investment, while treatments for Motor Dysfunction are attracting increased clinical attention.
End User:
The end-user setting dictates the scope of services and the integration of CIPN management into broader patient care pathways.
- Oncology Centers:These facilities are the principal end-user setting, integrating CIPN management as a core component of comprehensive cancer care. Their expansion into dedicated supportive care units drives consistent demand for treatments.
- Specialty Clinics:These clinics provide specialized care for neuropathy and pain management, offering advanced diagnostic tools and tailored therapeutic regimens. They serve as referral centers for complex CIPN cases requiring expert intervention.
- Home Healthcare Providers:These providers deliver ongoing symptom management and supportive care directly to patients in their homes.
- Rehabilitation Facilities:These facilities focus on restoring function and improving quality of life through physical and occupational therapy alongside pharmacological treatments.
Oncology Centers represent the broadest point of patient access, with Specialty Clinics expanding their reach for complex cases.
Delivery Mode:
Patient adherence and symptom management efficacy are significantly influenced by the chosen delivery mode of CIPN treatments.
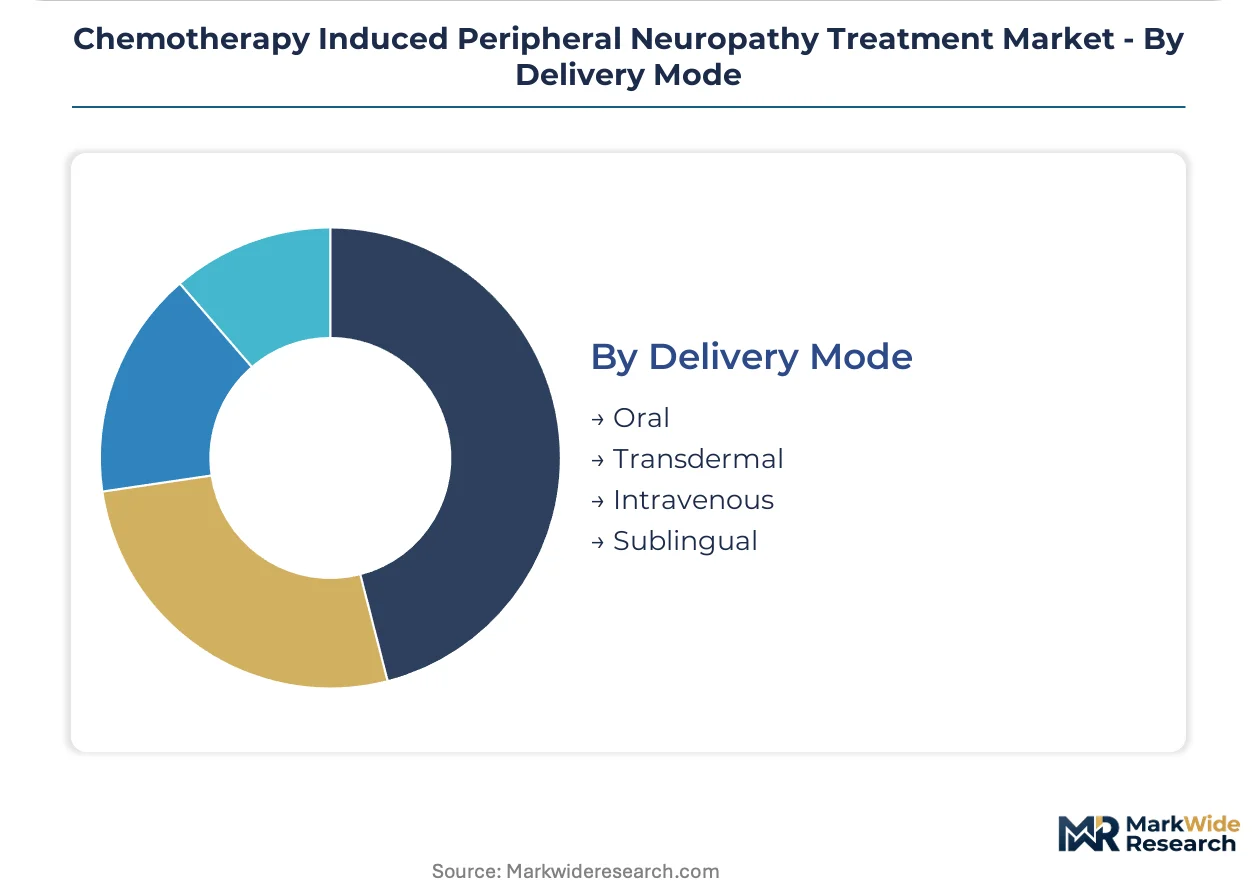
- Oral:This mode offers convenience and ease of administration, making it the most common method for systemic drug delivery in CIPN treatment. Patients often prefer oral medications due to their non-invasive nature and flexibility in dosing schedules.
- Transdermal:This delivery method involves applying medication through the skin, providing localized relief and potentially reducing systemic side effects. Topical agents are administered transdermally, offering targeted action for specific areas of neuropathic pain.
- Intravenous:This mode is typically reserved for acute symptom management or specific agents requiring direct entry into the bloodstream.
- Sublingual:This method allows for rapid absorption of medication through the mucous membranes under the tongue, bypassing first-pass metabolism.
Oral delivery remains the most preferred method for patients, while Transdermal applications show promise for localized relief.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech cluster, alongside other major pharmaceutical hubs, drives significant research and development in chemotherapy-induced peripheral neuropathy treatments. High cancer prevalence and advanced healthcare infrastructure create consistent demand for these therapies. Regulatory support for patient-reported outcomes further shapes market dynamics.
United States
High cancer prevalence and a strong focus on comprehensive cancer care propel demand for CIPN treatments in the United States. The US FDA's emphasis on patient-reported outcomes directly influences clinical trial design for novel analgesics. Major pharmaceutical companies in New Jersey and California continue to invest in advanced CIPN therapy research.
Germany
Germany's robust healthcare system and an aging population contribute to a steady demand for effective CIPN management. The European Medicines Agency (EMA) requires comprehensive safety and efficacy data, influencing drug development for the European market. Pharmaceutical research centers in Bavaria and North Rhine-Westphalia explore new treatment modalities.
Japan
Japan experiences a growing need for CIPN therapies due to its high cancer incidence and advanced oncology practices. The Pharmaceuticals and Medical Devices Agency (PMDA) mandates rigorous clinical evidence for market approval. Research institutions in Tokyo and Osaka are at the forefront of developing targeted therapies for neuropathic pain.
China
Increasing healthcare expenditure and expanding access to cancer care facilities across China drive demand for supportive CIPN treatments. China's National Medical Products Administration (NMPA) streamlines approval processes for innovative drugs. Biotechnology parks in Shanghai and Beijing are emerging as key centers for CIPN drug development.
India
India's rising cancer burden and improving oncology infrastructure create a significant market for CIPN therapies. The Central Drugs Standard Control Organization (CDSCO) regulates drug approvals, influencing the availability of both generic and novel treatments. Pharmaceutical manufacturing hubs in Hyderabad and Ahmedabad contribute to the supply of affordable CIPN medications.
Chemotherapy Induced Peripheral Neuropathy Treatment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue novel neuroprotective agents and biomarker-guided therapies. The market exhibits a tiered structure, with large pharmaceutical companies dominating the established analgesic and anticonvulsant segments, ensuring widespread availability. Smaller biotech firms specialize in advanced research for targeted interventions, focusing on underlying pathophysiology and precision medicine. Portfolio diversification into supportive care and strategic partnerships for co-development are dominant competitive moves among key players seeking to expand their market footprint.
Major pharmaceutical companies like Sanofi and Takeda Pharmaceutical Company Limited exemplify the diversified approach, leveraging extensive global oncology portfolios to address various treatment needs. These entities often anchor the market through broad distribution networks reaching both specialty clinics and major hospitals worldwide. Vertex Pharmaceuticals Incorporated represents a specialized archetype, focusing on novel mechanisms that target underlying neuropathic pain pathways, thereby differentiating its market presence. These companies collectively shape market direction through their distinct strategic orientations and investment in R&D.
| Leading Market Players |
|---|
| Sanofi |
| Takeda Pharmaceutical Company Limited |
| F. Hoffmann-La Roche Ltd |
| Amgen Inc. |
| Abbott Laboratories |
| Vertex Pharmaceuticals Incorporated |
| Sun Pharmaceutical Industries Ltd |
| Teva Pharmaceuticals |
| Aurobindo Pharma Limited |
Cost & Logistics Intelligence
Captive supply strategies for Active Pharmaceutical Ingredients anchor the supply position for major pharmaceutical firms, directly influencing their pricing power in the chemotherapy-induced peripheral neuropathy treatment market. This integration choice often dictates the ability to maintain competitive pricing for established treatments while investing in novel therapies.
Pricing Analysis
Input cost pass-through remains a critical factor for manufacturers, particularly for specialized Active Pharmaceutical Ingredients used in novel CIPN treatments. Pricing models often adopt a value-based approach for innovative therapies, while contract-based transactional pricing dominates for generic anticonvulsants and analgesics. Price differentiation stems from demonstrated clinical efficacy and superior safety profiles. Pricing softness runs through the generic segments due to widespread off-label use and intense competition. Public and private payers represent the most price-sensitive buyer segments, scrutinizing cost-effectiveness, while specialty clinics prioritize advanced therapeutic options.
Supply Chain Analysis
Certification requirements for pharmaceutical-grade raw materials rigorously gate entry for many suppliers, particularly for Active Pharmaceutical Ingredients. Geographic supply concentration for these critical inputs centers on India, China, and specialized manufacturing hubs in the United States and Germany. The supply chain relies on a stable flow of Active Pharmaceutical Ingredients, specialized excipients, and sterile packaging components. Single-source vulnerability for novel APIs represents a significant structural risk. Distribution runs through broad hospital networks and specialized pharmacy channels for established treatments, with more targeted specialty pharmacy models for advanced therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chemotherapy-induced peripheral neuropathy treatment market is evolving into a late-cycle quality story, driven by a pronounced demand-shift toward premium specifications for biomarker-guided therapies. This shift prioritizes interventions demonstrating superior efficacy and improved patient quality of life metrics.
For Market Incumbents:Lock in existing market share by diversifying product portfolios beyond symptomatic relief, focusing on neuroprotective agents and regenerative therapies. Invest in robust clinical trials that demonstrate clear symptomatic relief and improved quality of life, leveraging established global distribution networks. This strategy helps counter the threat posed by generic competition and emerging entrants with targeted therapies. Deepen regulatory expertise to navigate complex approval pathways across multiple geographies.
For New Entrants and Emerging Players:The FDA's guidance on patient-reported outcomes in the United States opens a window for novel analgesics and neuroprotective agents with clear symptomatic relief. Target biomarker-defined patient groups and specialized pain management clinics where unmet needs are highest. Focus go-to-market strategies on demonstrating clinical superiority through compelling patient-reported outcomes. Explore opportunities in underserved patient populations, such as pediatric CIPN, with tailored therapeutic approaches.
For Investors and Strategic Acquirers:Consolidation pressure builds where R&D costs are high and regulatory pathways for novel mechanisms are complex, favoring well-capitalized entities. Long-term viability is underpinned by sustained demand driven by high cancer prevalence and the imperative for comprehensive supportive care. Target biotech firms with strong intellectual property in neuroprotection, biomarker discovery, or non-opioid pain management. A signal to watch is successful Phase 2/3 trial data for targeted therapies demonstrating significant improvements in motor or sensory function.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for Neuroprotective Agents | This initiative validates novel therapies capable of preventing nerve damage, reducing long-term patient burden. |
| Regulatory Approval Pathway Optimization | Streamlining submissions accelerates market access for innovative CIPN treatments across key global regions. |
| Licensing Agreements for Biomarker Technologies | Securing access to predictive biomarkers enables precision medicine approaches for patient selection. |
| Manufacturing Scale-Up for Novel APIs | Expanding production capacity ensures reliable supply of critical components for new therapeutic options. |
| Pipeline Diversification into Regenerative Medicine | Exploring nerve regeneration therapies addresses underlying damage, offering curative potential beyond symptom management. |
Research Approach
Coverage spans the United States, Germany, Japan, China, and India, with primary inputs from each key market through extensive stakeholder interviews. This involved engaging R&D directors, regulatory affairs specialists, clinical oncologists, and hospital pharmacy directors. Primary insights were rigorously validated against secondary data sources, including FDA, EMA, and PMDA databases, clinical trial registries, and peer-reviewed medical journals. The methodology employed both bottom-up and top-down triangulation to ensure data accuracy and market sizing integrity.
Rate-of-change decomposition forms the core of the analytical framework, disaggregating market growth drivers across the analysis window. The study models market evolution across key segmentation dimensions including product type, therapy area, end-user settings, delivery mode, and regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from a comprehensive analysis of historical data and future projections. Key industry-specific forecast inputs included global cancer incidence rates and evolving chemotherapy regimen trends.
Revisions become necessary when unexpected clinical trial outcomes or significant policy shifts in drug reimbursement materialize, impacting market trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory stability within the pharmaceutical sector. A model refresh is warranted upon material change in global cancer treatment protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Epidermal Nevus Syndrome Market
Specialty Medicine
Toxic Shock Syndrome Treatment Market
Specialty Medicine
Chemotherapy Induced Thrombocytopenia Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Primary Ciliary Dyskinesia Market
Specialty Medicine
Coagulation Disorders Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Hyperuricemia Market
Specialty Medicine
Global Anal Fistula Treatment Market