
 Recto-Vaginal Fistula Market | 2026-2036
Recto-Vaginal Fistula Market Size, Share, and Industry Trends Forecast 2026-2036
Recto-Vaginal Fistula Market Analytics
The EU Medical Device Regulation is rebalancing procurement criteria for pelvic floor implants toward biocompatibility certification and post-market surveillance. Johnson & Johnson Services Inc. leverages its broad surgical portfolio to sustain hospital system contracts across integrated delivery networks. Pfizer Inc. anchors its position through urogynecology-focused pharmaceutical adjacencies that complement surgical intervention workflows.
Recto-vaginal fistula denotes an abnormal epithelialized tract connecting the rectal and vaginal walls, typically arising from obstetric trauma, radiation injury, or inflammatory bowel disease, with surgical repair requiring tension-free layered closure often reinforced with biologic or synthetic mesh. The product type dimension shows surgical mesh commanding the deepest margin pools due to material complexity and regulatory barriers, while robotic assistance within the technology dimension represents the fastest-growing category as capital equipment penetration deepens in tertiary hospitals. Delivery mode insights reveal laparoscopic surgery maturing into the standard of care for complex recurrent cases, whereas the transvaginal approach dominates initial repairs in resource-constrained settings.
FDA 510(k) clearance pathways and the EU MDR's Class III implantable device requirements shape market access timelines and clinical evidence burdens for mesh manufacturers. Health Canada's Medical Devices Directorate and Japan's PMDA impose additional jurisdiction-specific biocompatibility testing protocols that fragment regulatory strategy. Stakeholders must monitor evolving litigation trends around synthetic mesh complications alongside emerging health technology assessment frameworks that increasingly predicate reimbursement on comparative effectiveness data.
Market Dynamics
The EU Medical Device Regulation's Class III implantable device requirements are compressing market access timelines for synthetic mesh manufacturers while accelerating biologic mesh development pipelines.
Growth Catalysts
- Robotic-Assisted Surgical Protocols:Academic medical centers in the United States are standardizing da Vinci-assisted layered closure techniques, driving capital equipment refresh cycles and specialized training program investments.
- Biocompatibility Certification Mandates:The EU MDR's reinforced post-market surveillance obligations for implantable pelvic floor devices is elevating entry barriers for low-quality suppliers and concentrating procurement toward certified manufacturers.
- Rising Tertiary Care Surgical Volumes:Integrated delivery networks are consolidating complex fistula repair referrals into high-volume centers, creating dedicated urogynecology service lines with standardized mesh utilization protocols.
Market Restraints
- Synthetic Mesh Litigation Exposure:Product liability settlements in transvaginal mesh cases have chilled venture capital appetite for novel polypropylene formulations in pelvic floor applications.
- Biologic Mesh Supply Concentration:Porcine and human-derived graft sourcing depends on a limited number of accredited tissue banks, creating batch-to-batch variability risks and procurement bottlenecks.
- EU MDR Technical Documentation Burden:The notified body capacity shortage has extended conformity assessment timelines to 18-24 months for Class III pelvic floor implants, freezing product line extensions.
Strategic Opportunities
- Japan PMDA Fast-Track Pathway:The Sakigake designation for breakthrough surgical devices offers expedited review for robotic-assisted fistula repair systems, opening Asia-Pacific's second-largest medical device market.
- Resorbable Synthetic Polymer Convergence:Combining polycaprolactone scaffolding with platelet-rich plasma delivery creates differentiated repair kits for radiation-induced fistulas with poor vascular beds.
- Telemedicine-Enabled Preoperative Planning:Virtual urogynecology consultations are expanding referral catchment areas for academic centers, compressing diagnostic delays and accelerating surgical scheduling.
Industry Challenges
- Robotic Surgery Credentialing Complexity:Hospital privileging committees require 50+ supervised cases for independent robotic fistula repair practice, constraining specialist supply expansion.
- Mesh-Related Infection Surveillance:The FDA's 522 post-market surveillance orders mandate decade-long patient registries, imposing sustained data infrastructure costs on manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recto-Vaginal Fistula Market |
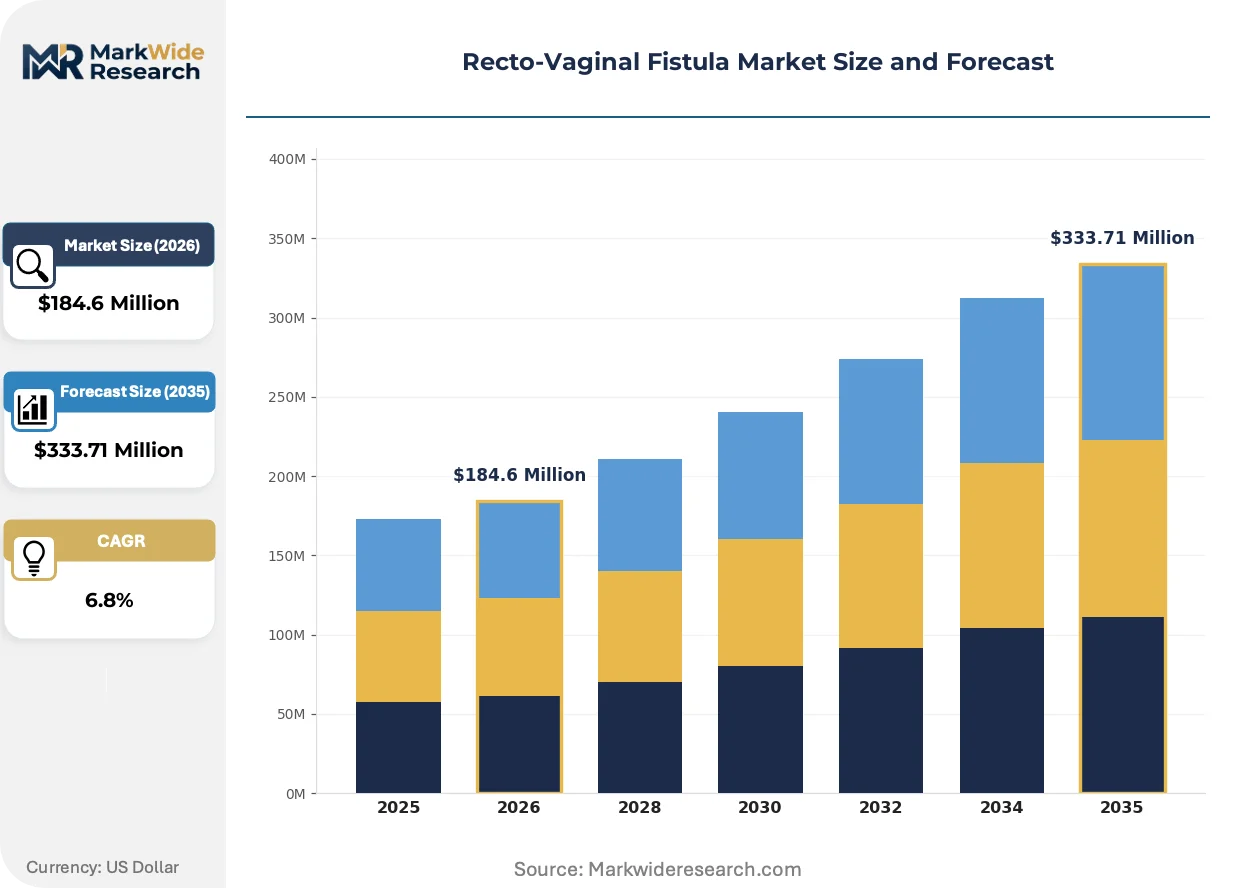
| Market Size in 2026 | $184.6 Million |
| Market Size in 2035 | $333.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Mesh, Fistula Clips, Catheters, Sutures Delivery Mode: Open Surgery, Laparoscopic Surgery, Endoscopic Procedure, Transvaginal Approach End User: Hospitals, Clinics, Specialized Fistula Centers, Home Care Technology: Laser Surgery, Traditional Surgery, Minimally Invasive Techniques, Robotic Assistance |
| Companies Covered | Johnson & Johnson Services Inc., Pfizer Inc., Takeda Pharmaceutical Company, Cook Medical, Sanofi S.A., GlaxoSmithKline plc, AbbVie Inc., W. L. Gore & Associates, Inc., Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recto-Vaginal Fistula Market Evolving Landscape
Digital surgical planning tools and advanced biomaterials are converging to reshape procedural workflows, with regulatory frameworks simultaneously tightening evidence requirements and accelerating novel device pathways.
Biologic mesh formulations incorporating extracellular matrix scaffolding are unifying structural support with host tissue integration. Tertiary care networks in Germany and the Netherlands are adopting these platforms for recurrent radiation fistula cases. The technology is unifying previously separate repair stages into single-procedure protocols, compressing total hospitalization duration.
The EU MDR's enhanced clinical evidence requirements for Class III implantable devices are forcing manufacturers to conduct prospective registry studies rather than retrospective case series. Notified bodies in Ireland and Germany are rejecting submissions lacking five-year follow-up data. Synthetic mesh suppliers are responding by divesting marginal product lines and concentrating R&D budgets on resorbable alternatives.
Hospital procurement committees are consolidating fistula repair supply contracts under value-based frameworks that bundle mesh, fixation devices, and postoperative surveillance. Integrated delivery networks in Texas and California are replacing physician preference item purchasing with standardized protocol-driven kits. This shift is most visible in academic medical centers where service line administrators now control 70% of implant selection decisions.
Recto-Vaginal Fistula Market Segmentation
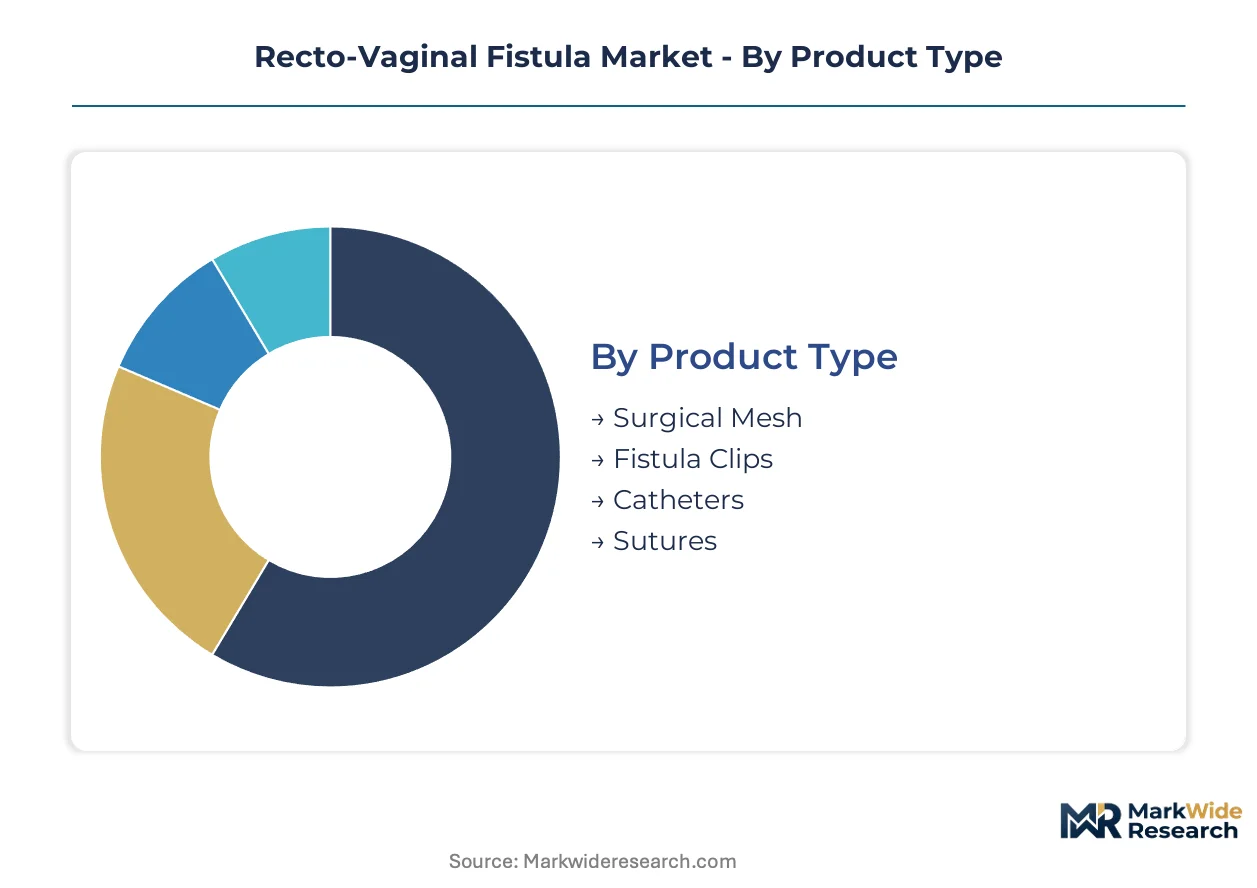
Segmentation in the recto-vaginal fistula market reveals distinct procurement patterns across product categories and care settings. Surgical mesh specifications and robotic platform compatibility increasingly determine contract awards within integrated delivery networks.
Product Type:
Surgical mesh functions as a standalone implant requiring separate sterilization protocols and inventory management, while fistula clips and catheters embed into procedure kits with bundled pricing.
- Surgical Mesh:Synthetic polypropylene and biologic porcine-derived formulations provide tension-free reinforcement for layered rectovaginal wall closure. Demand concentrates in tertiary academic centers across the United States where robotic-assisted protocols mandate specific mesh dimensions and fixation compatibility. FDA 510(k) clearance timelines and EU MDR biocompatibility certification requirements create procurement bottlenecks for non-specialized suppliers.
- Fistula Clips:Titanium and absorbable polymer designs enable rapid mechanical approximation of fistula edges without suture placement. German and Dutch university hospitals are standardizing clip-based protocols for radiation-induced fistulas with poor tissue vascularity, driven by compressed operative time targets and same-day discharge mandates.
- Catheters:Silicone and latex drainage systems manage preoperative sepsis and postoperative decompression across emergency departments and outpatient clinics.
- Sutures:Braided synthetic and monofilament absorbable threads complete layered closure techniques in resource-constrained settings lacking mesh inventory.
Surgical mesh leads volumes today; robotic-compatible mesh kits are gaining share fastest.
Delivery Mode:
Cost tiering separates high-complexity laparoscopic and robotic procedures reimbursed at premium rates from transvaginal approaches dominant in emerging markets.
- Open Surgery:Abdominal perineal resection with primary repair remains the fallback for recurrent, irradiated, or malignant fistulas. Volume concentrates in Indian and Brazilian public hospital systems where capital equipment constraints limit minimally invasive adoption.
- Laparoscopic Surgery:Multiport and single-incision techniques enable transabdominal rectovaginal dissection with magnified visualization. Academic medical centers in California and Texas are consolidating complex recurrent repairs into dedicated minimally invasive service lines, driven by reduced length-of-stay metrics and bundled payment incentives.
- Endoscopic Procedure:Transanal and transvaginal endoscopic microsurgery offers organ-sparing alternatives for select low-lying fistulas.
- Transvaginal Approach:Direct vaginal wall incision with layered repair dominates initial obstetric trauma repairs in sub-Saharan African and South Asian district hospitals.
Transvaginal approaches dominate procedure counts; laparoscopic volumes are climbing the fastest.
End User:
Customer type determines purchasing authority, with hospital supply chains controlling implant selection versus physician-directed ordering in independent clinics.
- Hospitals:Tertiary care networks with dedicated urogynecology service lines standardize mesh and fixation device protocols through value-based contracting. Integrated delivery networks in the United States now mandate 70% of implant decisions through service line administrators rather than individual surgeons.
- Specialized Fistula Centers:High-volume referral hubs in Ethiopia, Nigeria, and Bangladesh perform hundreds of repairs annually with simplified suture-based techniques.
- Clinics:Private urogynecology practices in Germany and Switzerland maintain physician preference item purchasing for biologic mesh selections.
- Home Care:Postoperative catheter management and wound care services extend recovery monitoring beyond acute settings.
Hospitals command the largest revenue pool; specialized fistula centers are expanding most quickly.
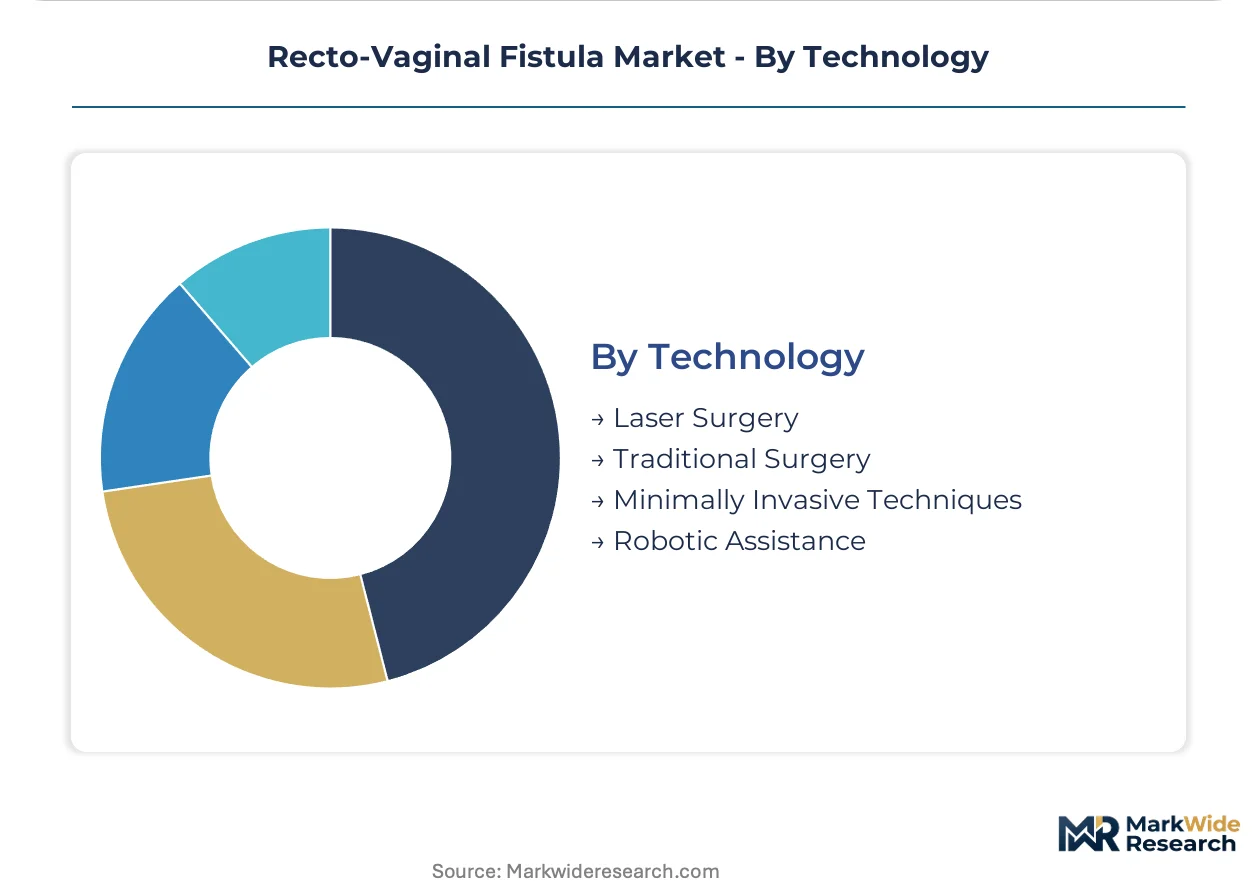
Technology:
Maturity curves separate established traditional surgery from capital-intensive robotic platforms requiring dedicated training pathways and maintenance contracts.
- Robotic Assistance:da Vinci surgical systems enable wristed suturing in deep pelvic spaces with three-dimensional visualization. Adoption concentrates in United States academic centers where 50-case credentialing requirements and proctored training programs create specialist supply constraints.
- Minimally Invasive Techniques:Laparoscopic and endoscopic platforms without robotic arms offer intermediate cost positioning for regional hospitals.
- Traditional Surgery:Open transabdominal, transperineal, and transvaginal repairs without optical magnification remain standard in low-resource settings.
- Laser Surgery:Carbon dioxide and diode laser applications for fistula edge preparation and hemostasis occupy niche indications in European aesthetic gynecology practices.
Traditional surgery maintains procedure volume leadership; robotic assistance shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surgical repair protocols for recto-vaginal fistula originated in European academic centers during the mid-20th century, with layered closure techniques later refined through North American adoption of tension-free mesh reinforcement. Contemporary demand patterns now reflect divergent healthcare infrastructure maturity across major economies.
United States
Tertiary academic medical centers in California and Texas drive robotic-assisted repair adoption through dedicated urogynecology service lines. FDA 510(k) clearance pathways and post-market surveillance orders under Section 522 shape manufacturer evidence requirements. The Cleveland Clinic and Mayo Clinic anchor high-volume referral networks that standardize biologic mesh protocols.
Germany
University hospitals in Baden-Württemberg and Bavaria consolidate complex radiation-induced fistula repairs through laparoscopic expertise centers. EU MDR Class III implantable device requirements and notified body capacity constraints in Ireland and Germany extend conformity assessment timelines. The Heidelberg and Munich surgical clusters pioneer extracellular matrix scaffolding adoption.
Japan
Metropolitan Tokyo and Osaka medical centers leverage PMDA Sakigake fast-track designation for breakthrough surgical device review. METI reimbursement frameworks for robotic-assisted pelvic floor procedures accelerate capital equipment procurement. The National Center for Child Health and Development anchors specialized obstetric trauma repair volumes.
India
Public hospital systems in Maharashtra and Tamil Nadu perform high-volume open repairs where capital constraints limit minimally invasive adoption. CDSCO medical device registration requirements and state-level procurement tenders shape implant availability. Tamil Nadu's government medical college hospitals train surgeons in simplified suture-based techniques for district-level dissemination.
Brazil
São Paulo and Minas Gerais state hospital networks manage obstetric fistula burdens through public surgical camps and academic partnerships. ANVISA medical device registration pathways and import tariff structures influence mesh affordability. The Federal University of São Paulo anchors subspecialty training programs that feed regional referral capacity.
Recto-Vaginal Fistula Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification depth and biocompatibility evidence portfolios. The vendor base stratifies between diversified surgical conglomerates with integrated delivery network contracts and specialized mesh manufacturers dependent on single-product revenue concentration. Three archetypes dominate: diversified medical device conglomerates, pharmaceutical-adjacent surgical supply platforms, and focused biomaterial specialists. Competitive dynamics center on M&A consolidation of mesh technology assets and strategic partnerships with academic medical centers for clinical evidence generation.
Within the diversified conglomerate tier, Johnson & Johnson Services Inc. and Medtronic occupy positions sustained through hospital system contract breadth and robotic platform compatibility portfolios. Pfizer Inc. exemplifies pharmaceutical-adjacent positioning where urogynecology-focused drug portfolios complement surgical intervention workflows. Cook Medical represents the specialized fabricator archetype with concentrated expertise in interventional radiology and pelvic floor device categories.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Pfizer Inc. |
| Takeda Pharmaceutical Company |
| Cook Medical |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| AbbVie Inc. |
| W. L. Gore & Associates, Inc. |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Porcine-derived extracellular matrix sourcing costs cascade through biologic mesh pricing tiers, with accredited tissue bank certification premiums separating hospital-grade implants from simplified suture-based alternatives in district hospital procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with EU MDR biocompatibility certification and robotic platform compatibility serving as the primary price differentiation drivers. Cost compression in economy-tier synthetic polypropylene meshes is intensifying because of litigation-driven venture capital retreat from novel formulations. Academic medical centers in the United States exhibit the lowest price sensitivity due to bundled reimbursement frameworks, while specialized fistula centers in sub-Saharan Africa face acute budget constraints.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biologic graft shipments is reshaping regional inventory strategies, with manufacturers maintaining dual cold-chain distribution hubs in Germany and the Netherlands to serve EU hospital networks. Raw material sourcing draws from accredited porcine tissue banks in the United States and human-derived graft repositories in regulated European jurisdictions. Single-source vulnerability concentrates in the limited number of certified tissue processors meeting FDA and EU MDR standards. Distribution runs through integrated delivery network contracting offices in the United States and government procurement tenders in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU MDR compliance costs and Japan's PMDA Sakigake fast-track incentives, with regulatory timeline differentials creating 12-18 month market access gaps for identical device platforms.
For Market Incumbents: Cement hospital system contracting dominance by deepening robotic platform compatibility portfolios and accelerating resorbable polymer R&D pipelines before biologic mesh supply concentration triggers procurement bottlenecks. Prioritize backward integration into accredited tissue processing to secure porcine-derived graft supply chains against batch-to-batch variability risks. For New Entrants and Emerging Players: Telemedicine-enabled preoperative planning platforms offer the most penetrable entry vector, targeting academic medical center referral network expansion in the United States and Germany. Focus initial commercialization on radiation-induced fistula repair kits combining polycaprolactone scaffolding with platelet-rich plasma delivery, leveraging specialty distributor partnerships rather than direct hospital contracting. For Investors and Strategic Acquirers: Roll-up economics work for specialized biomaterial fabricators because EU MDR technical documentation burdens are freezing product line extensions and forcing divestitures from diversified conglomerates. Target firms with existing FDA 510(k) clearances and five-year clinical follow-up data portfolios. Watch for notified body capacity expansion in Ireland and Germany as the inflection signal for accelerated M&A activity.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class III Certification Pathway | Accelerated conformity assessment unlocks procurement access in German and Dutch university hospital networks. |
| Hospital System Partnership | Integrated delivery network contracting replaces physician preference items with standardized protocol-driven implant kits. |
| Biologic Mesh Supply Agreement | Long-term tissue bank accreditations reduce batch-to-batch variability risks for radiation fistula repair platforms. |
| Robotic Platform Integration | da Vinci compatibility certification enables access to high-margin academic medical center service lines. |
| Reimbursement Strategy | CMS and METI coding alignment accelerates capital equipment refresh cycles in tertiary care networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with urogynecology service line administrators, biomedical engineers, GPO contracts managers, and hospital purchasing committees with secondary validation against FDA 510(k) filings, EU MDR notified body decisions, CMS Medicare reimbursement data, and hospital procurement databases. Bottom-up surgical volume modeling and top-down market sizing triangulated segment-level estimates.
Segment-weighting approaches applied differential growth assumptions across product type, delivery mode, end user, and technology dimensions throughout the forecast period. CAGRs derived from procedure volume trajectories, capital equipment penetration curves, and regulatory approval timeline modeling. Forecast inputs incorporated EU MDR notified body capacity constraints, robotic surgery credentialing requirements, and biologic mesh supply concentration indices.
The model assumes a particular technology adoption path; alternative pathways for resorbable synthetic polymers would alter the outlook if polycaprolactone scaffolding demonstrates superior vascular bed integration in radiation-induced fistula cases. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Osteomyelitis Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Overt Hepatic Encephalopathy Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Wet Age-Related Macular Degeneration (Wet AMD) Market
Specialty Medicine
Intraductal Papilloma Market
Specialty Medicine
Global Appendiceal Cancer Treatment Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Global Lupus Market
Specialty Medicine
Anophthalmia and Microphthalmia Market
Specialty Medicine
Neurodegenerative Disease Market
Specialty Medicine
Cryptococcosis Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Postmenopausal Osteoporosis Treatment Market
Specialty Medicine
Meningitis Treatment Market