
 Transthyretin (TTR) Amyloidosis Market | 2026-2036
Transthyretin (TTR) Amyloidosis Market Size, Share, and Industry Trends Forecast 2026-2036
Transthyretin (TTR) Amyloidosis Market Analytics
Specialty pharmacy and hospital infusion networks is reconfiguring how RNA interference and antisense therapies reach patients with transthyretin amyloidosis. Alnylam Pharmaceuticals leverages its established intravenous and subcutaneous delivery infrastructure to sustain first-mover positioning in the hereditary segment. Pfizer Inc. anchors the competitive landscape through its small molecule portfolio, while Ionis Pharmaceuticals competes via differentiated antisense oligonucleotide mechanisms.
Transthyretin amyloidosis encompasses a family of progressive deposition diseases caused by misfolded transthyretin protein aggregating in cardiac tissue, peripheral nerves, and other organs, with disease severity quantified by biomarkers such as N-terminal pro-brain natriuretic peptide and troponin levels. The primary commercial purpose of therapies in this space is to halt or reverse organ dysfunction by silencing TTR production, stabilizing the tetrameric protein structure, or editing the underlying genetic defect. Small molecules currently occupy the most accessible delivery position due to oral bioavailability, while gene therapy represents the fastest-growing segment as one-time dosing protocols advance through clinical validation. Antibodies targeting fibril clearance command premium positioning where tissue burden already exists.
FDA accelerated approval designations and orphan drug exclusivity frameworks shape development economics and commercial timelines for sponsors targeting this indication. EMA's parallel scientific advice pathways and Japan's PMDA sakigake designation system create comparable access structures in Europe and Japan, conditioning how companies sequence geographic filings. Stakeholders must monitor evolving biomarker-based diagnostic criteria and payer willingness to fund one-time gene therapies against chronic administration models.
Market Dynamics
RNA-targeted therapeutic modalities are restructuring competitive positioning in transthyretin amyloidosis, as intravenous and subcutaneous delivery infrastructure investments determine which sponsors capture patient volume in specialty clinic networks.
Growth Catalysts
- FDA Accelerated Approval Pathways:Orphan drug designation frameworks compress development timelines for rare disease biologics, enabling sponsors to reach commercialization faster than traditional review cycles permit.
- Biomarker-Guided Diagnostics:N-terminal pro-brain natriuretic peptide and troponin quantification protocols are expanding addressable patient populations through earlier disease detection in cardiac and neuropathic variants.
- Specialty Clinic Infrastructure:Hospital infusion networks and dedicated amyloidosis centers are building captive patient funnels that streamline therapy initiation and long-term monitoring.
Market Restraints
- Gene Therapy Manufacturing Concentration:Viral vector production capacity bottlenecks in North American and European contract manufacturing organizations limit scalable supply for one-time dosing protocols.
- Reimbursement Friction:Payer uncertainty regarding value-based benchmarks for single-administration gene therapies versus chronic RNA interference creates coverage determination delays.
- Diagnostic Access Disparities:Tissue biopsy requirements and genetic testing availability gaps in rural and underserved regions prolong time-to-diagnosis for hereditary variant carriers.
Strategic Opportunities
- Wild-Type Cardiac Penetration:Aging demographics in Japan and the United States are expanding the eligible population for TTR stabilizers beyond hereditary mutation carriers into sporadic disease forms.
- Antibody-Fibril Clearance Convergence:Monoclonal antibodies targeting established amyloid deposits represent a complementary mechanism to production-silencing approaches in advanced disease stages.
- EMA Parallel Scientific Advice:Coordinated regulatory engagement pathways enable synchronized development strategies across European national health technology assessment bodies.
Industry Challenges
- Genetic Counseling Workforce Scarcity:Insufficient certified counselors to support family screening protocols for hereditary variant carriers creates patient identification bottlenecks.
- Longitudinal Outcome Data Requirements:Payer demands for extended follow-up evidence to justify premium pricing for disease-modifying therapies strain post-marketing surveillance infrastructure.
- Multidisciplinary Care Coordination:Integration of cardiology, neurology, and hematology expertise within single treatment centers requires organizational redesign of academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transthyretin (TTR) Amyloidosis Market |
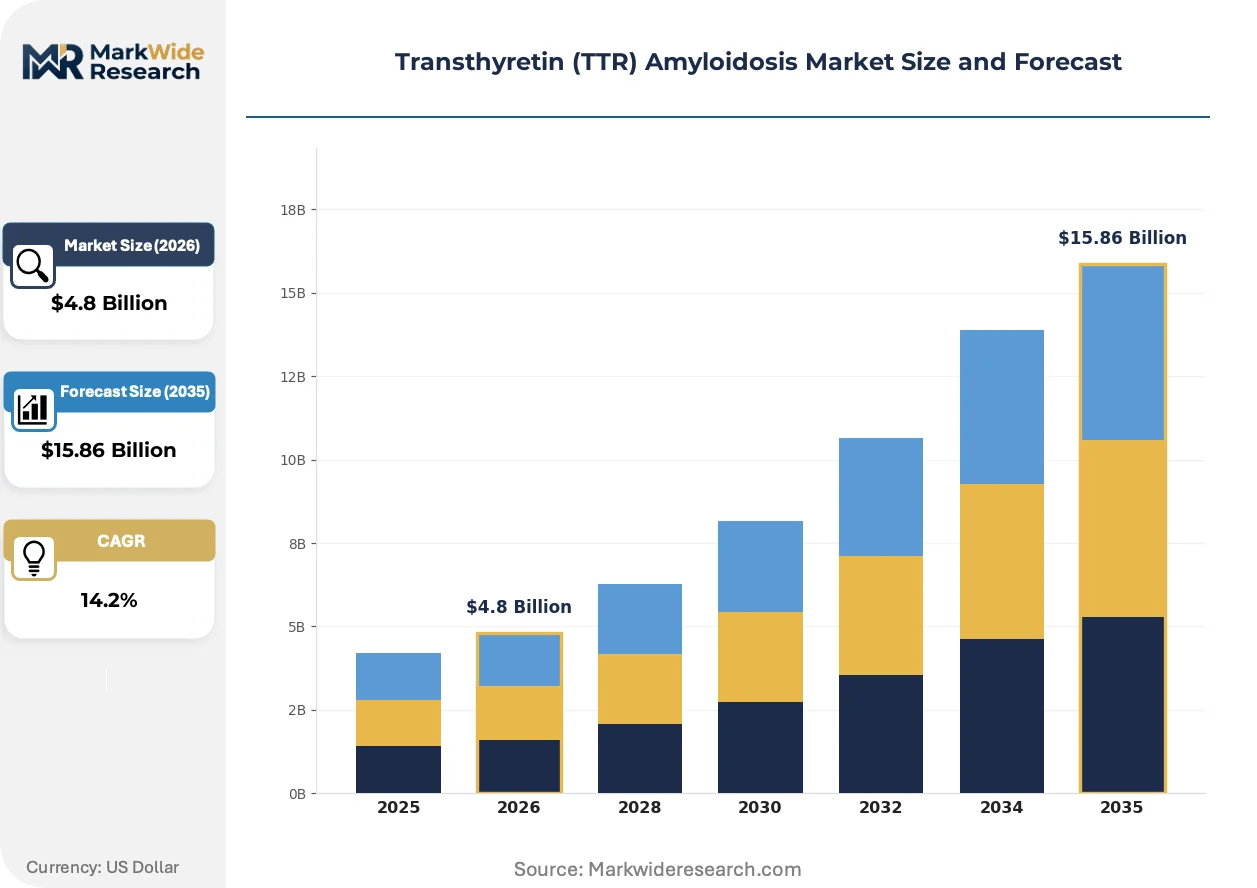
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibodies, Small Molecules, Gene Therapy, Enzyme Replacement Indication: Hereditary TTR Amyloidosis, Wild-Type TTR Amyloidosis, Cardiac Amyloidosis, Peripheral Neuropathy Delivery Mode: Intravenous, Oral, Subcutaneous, Intraosseous End User: Hospitals, Specialty Clinics, Homecare, Long-term Care Facilities |
| Companies Covered | Pfizer Inc., Alnylam Pharmaceuticals, Inc., Ionis Pharmaceuticals, Inc., AstraZeneca PLC, BridgeBio Pharma Inc., Intellia Therapeutics, Inc., Akcea Therapeutics, Eidos Therapeutics, Inc., Prothena Biosciences Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transthyretin (TTR) Amyloidosis Market Evolving Landscape
Delivery modality diversification is fragmenting patient routing patterns, as oral small molecules, subcutaneous RNA therapeutics, and one-time gene editing protocols compete for overlapping indication spaces with distinct value propositions.
CRISPR-based gene editing is migrating from early-stage clinical validation toward registrational trials for hereditary transthyretin amyloidosis, with sponsors targeting liver-directed in vivo delivery to achieve permanent TTR production cessation. Academic medical centers in the United States and United Kingdom are establishing dedicated gene therapy units to manage patient selection and post-procedure monitoring. This modality is compressing the addressable window for chronic administration therapies by positioning one-time intervention as a functional cure alternative.
PMDA's sakigake designation system in Japan is creating priority review pathways for first-in-class therapies targeting rare diseases, compressing regulatory timelines for sponsors willing to conduct bridging studies with Japanese patient cohorts. The framework conditions commercial sequencing decisions, with several sponsors filing Japan ahead of European markets to capture early revenue in the world's fastest-aging population. Cardiology-focused hospital networks are responding by building amyloidosis-specific diagnostic and treatment pathways aligned with reimbursement pre-approval.
Specialty pharmacy networks are displacing traditional hospital outpatient departments as the primary administration site for subcutaneous RNA interference therapies, with home health nursing services emerging as an extension channel for stable patients. This channel migration reduces site-of-care costs while shifting inventory and cold-chain responsibilities to pharmacy benefit managers. The United States exhibits the most advanced channel fragmentation, with comparable models developing in Germany and Switzerland through outpatient clinic partnerships.
Transthyretin (TTR) Amyloidosis Market Segmentation
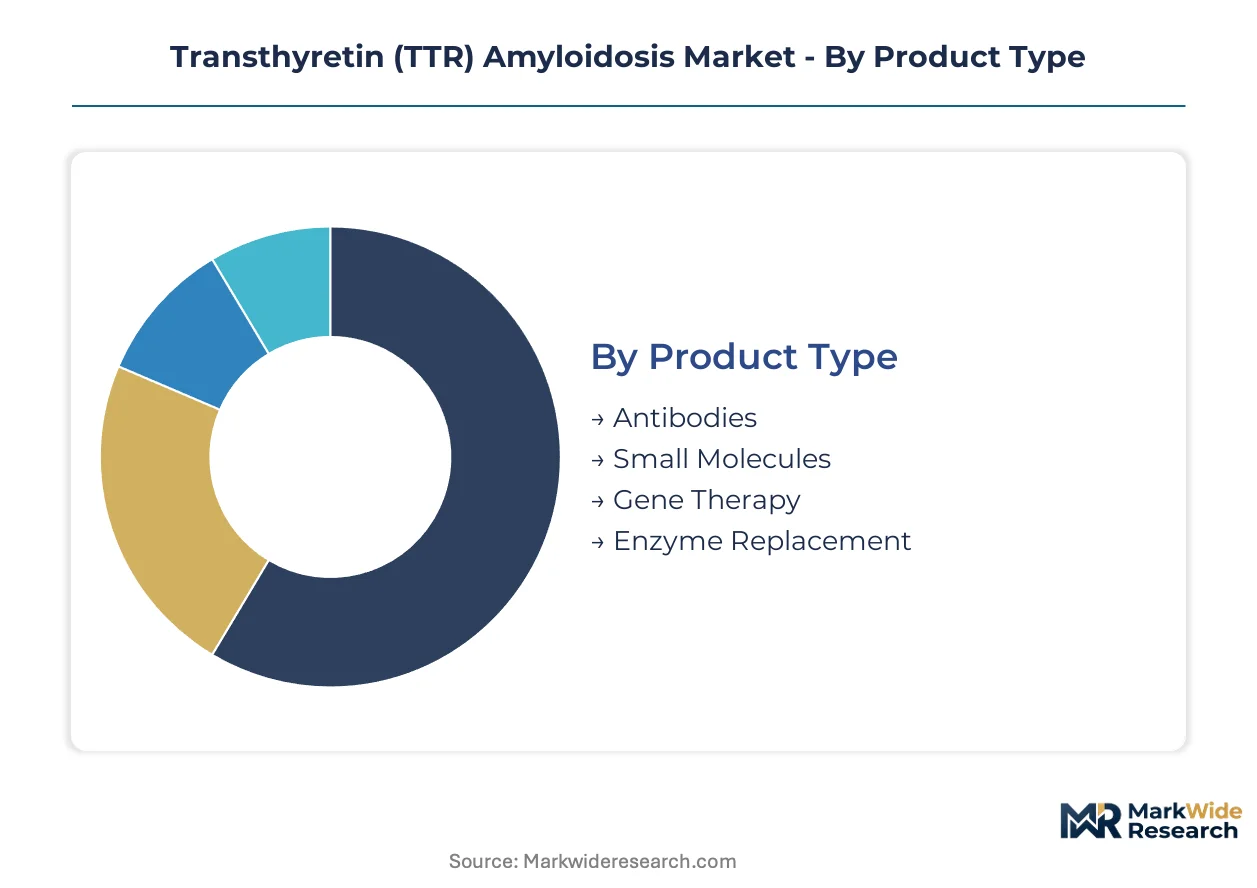
Therapeutic modality selection in transthyretin amyloidosis determines patient routing, reimbursement pathways, and long-term monitoring infrastructure. Segmentation reveals how delivery mechanisms, disease variants, and care settings fragment addressable populations across distinct commercial ecosystems.
Product Type:
After-sales service intensity varies sharply across modalities, with gene therapy requiring dedicated patient monitoring programs versus small molecules that need minimal clinical follow-up.
- Small Molecules:Oral TTR stabilizers such as tafamidis bind the tetrameric protein to prevent misfolding. Demand concentrates in cardiology practices across the United States and Japan where wild-type cardiac amyloidosis diagnosis rates are climbing fastest.
- Gene Therapy:CRISPR-based and AAV-mediated liver-directed editing achieves permanent TTR production cessation. Academic medical centers in Boston and London are establishing dedicated gene therapy units to manage patient selection and post-procedure hepatotoxicity surveillance.
- Antibodies:Monoclonal therapeutics targeting fibril clearance require infusion center capacity and cardiac monitoring protocols.
- Enzyme Replacement:Investigational approaches targeting extracellular matrix remodeling remain confined to early-phase clinical trial networks.
Small molecules hold the largest share; momentum sits with gene therapy.
Indication:
Cost tier stratification separates hereditary variant management with genetic counseling requirements from wild-type disease with simpler diagnostic pathways.
- Wild-Type TTR Amyloidosis:Sporadic cardiac deposition in aging populations drives volume economics for oral stabilizers. Japanese and US geriatric cardiology clinics are expanding amyloidosis screening protocols using nuclear scintigraphy.
- Hereditary TTR Amyloidosis:Autosomal dominant mutations produce progressive neuropathy and cardiomyopathy requiring multidisciplinary care coordination. Portuguese, Swedish, and Japanese mutation carriers represent concentrated founder populations with established national screening programs.
- Cardiac Amyloidosis:Heart failure presentations dominate hospital-based diagnosis and acute intervention patterns.
- Peripheral Neuropathy:Neurologic onset variants require longitudinal functional assessment and pain management integration.
Wild-type presentations dominate prescription volume; hereditary variants command premium pricing through orphan mechanisms.
Delivery Mode:
Application context determines route selection, with acute decompensation favoring intravenous access and maintenance therapy shifting toward patient-administered options.
- Subcutaneous:RNA interference therapies administered via autoinjector enable home-based maintenance dosing. Specialty pharmacy networks in Germany and Switzerland are building cold-chain distribution partnerships to support patient self-administration.
- Intravenous:Antibody-based fibril clearance and initial RNAi loading doses require infusion center capacity with cardiac monitoring. Hospital outpatient departments retain this volume where site-of-care reimbursement differentials favor institutional billing.
- Oral:Small molecule stabilizers bypass infusion infrastructure entirely, reaching community cardiology practices.
- Intraosseous:Emergency vascular access for acute amyloid crisis management in critical care settings.
Intravenous delivery retains the highest per-dose revenue; subcutaneous administration is expanding most quickly through pharmacy channel migration.
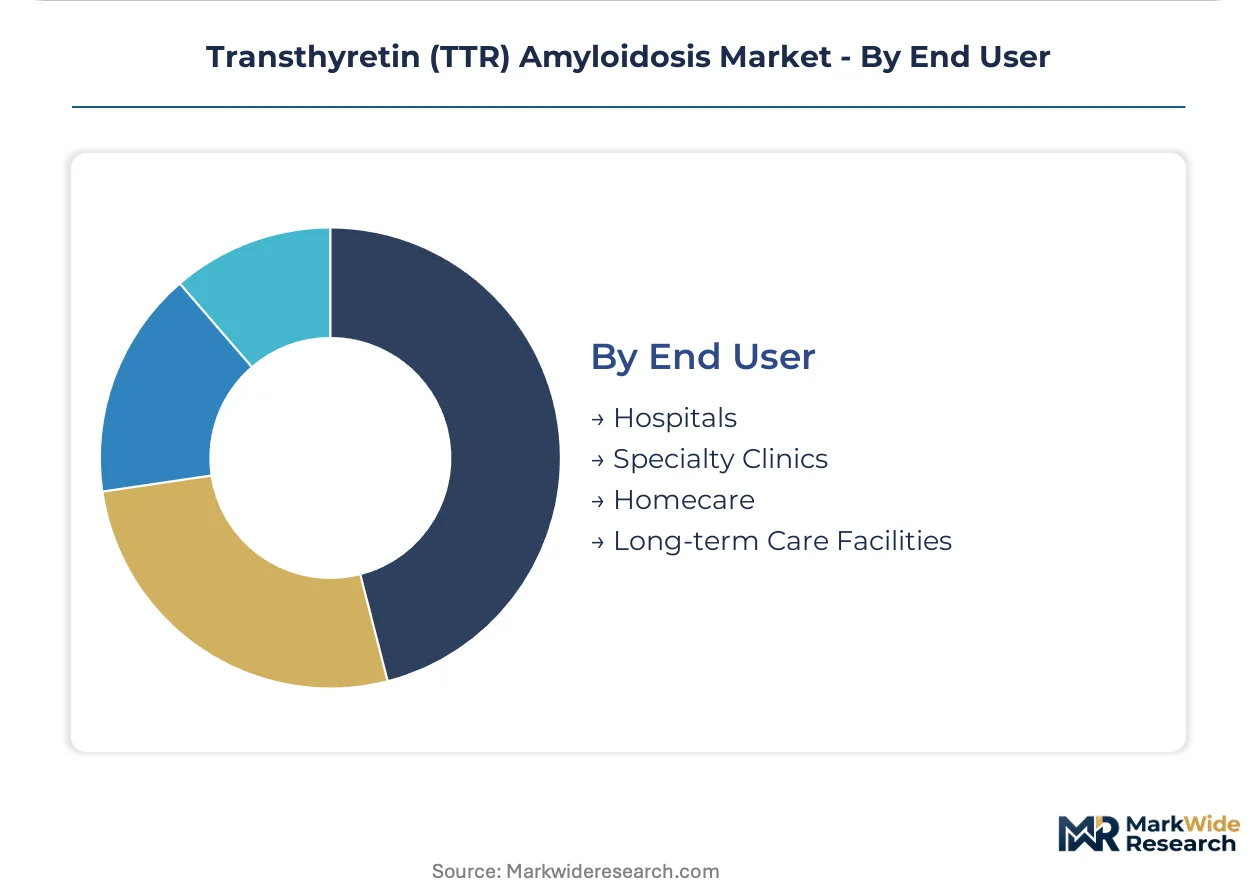
End User:
Customer type fragmentation reflects therapy complexity, with gene therapy concentrating in quaternary centers and chronic RNAi dispersing through retail pharmacy networks.
- Specialty Clinics:Dedicated amyloidosis centers integrate cardiology, neurology, and genetic counseling under single organizational structures. The Mayo Clinic, University College London Hospitals, and Osaka University Hospital anchor referral networks spanning multi-state and multi-national catchment areas.
- Hospitals:Acute diagnosis and initial therapy initiation occur in tertiary medical centers with biopsy capabilities and mass spectrometry-based amyloid typing.
- Homecare:Nursing services support stable patients on subcutaneous RNAi regimens, reducing site-of-care costs.
- Long-term Care Facilities:Geriatric cardiac amyloidosis management in skilled nursing settings focuses on palliative heart failure protocols.
Specialty clinics capture the highest-complexity patients; homecare channels are gaining share fastest through payer pressure on infusion costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor commercial activity in the United States, where diagnostic expansion and specialty clinic infrastructure drive prescription volume. EMA parallel scientific advice and Japan's PMDA sakigake designation create comparable access structures in Europe and Asia-Pacific, conditioning how sponsors sequence geographic filings.
United States
Wild-type cardiac amyloidosis diagnosis rates climb fastest among aging populations, with geriatric cardiology clinics expanding nuclear scintigraphy screening protocols. The FDA's orphan drug designation framework compresses development timelines for rare disease biologics, enabling sponsors to reach commercialization faster. Boston and New York anchor gene therapy unit establishment, with academic medical centers managing patient selection and post-procedure monitoring.
Japan
PMDA's sakigake designation system creates priority review pathways for first-in-class therapies targeting rare diseases, compressing regulatory timelines for sponsors conducting bridging studies. Aging demographics expand eligible populations for TTR stabilizers beyond hereditary mutation carriers into sporadic disease forms. Osaka University Hospital anchors referral networks spanning multi-national catchment areas for amyloidosis-specific diagnostic pathways.
Germany
Specialty pharmacy networks build cold-chain distribution partnerships to support patient self-administration of subcutaneous RNA interference therapies. EMA parallel scientific advice enables synchronized development strategies across European national health technology assessment bodies. Munich and Heidelberg concentrate multidisciplinary care coordination integrating cardiology, neurology, and genetic counseling expertise.
United Kingdom
University College London Hospitals establish dedicated gene therapy units to manage patient selection and post-procedure hepatotoxicity surveillance for CRISPR-based editing protocols. NHS England's specialized commissioning frameworks determine reimbursement access for one-time gene therapies against chronic administration models. London anchors referral networks spanning domestic and international patient funnels for advanced amyloidosis interventions.
Sweden
Founder populations with established national screening programs concentrate hereditary variant carriers requiring longitudinal functional assessment and pain management integration. The Swedish Medical Products Agency aligns with EMA centralized procedures while maintaining national health economic evaluation requirements. Stockholm and Gothenburg anchor regional amyloidosis centers building captive patient funnels for therapy initiation.
Transthyretin (TTR) Amyloidosis Market Competitive Landscape
RNA-targeted specialists and small molecule incumbents split the market along mechanism-of-action lines, with delivery infrastructure investments determining patient volume capture in specialty clinic networks. The vendor base concentrates around three strategic archetypes: large-cap pharmaceutical conglomerates with diversified rare disease portfolios, mid-cap biotech specialists focused on nucleic acid therapeutics, and emerging gene editing platforms pursuing one-time functional cures. Consolidation pressures favor M&A activity targeting antisense oligonucleotide capabilities, while capacity expansion concentrates in viral vector manufacturing to address gene therapy supply bottlenecks.
Within the RNA interference tier, Alnylam Pharmaceuticals and Ionis Pharmaceuticals exemplify platform-specialist positioning, with the former leveraging established intravenous and subcutaneous delivery infrastructure and the latter competing via differentiated antisense mechanisms. Pfizer Inc. anchors the small molecule segment through oral stabilizer portfolios. These three entities occupy positions that reflect broader strategic archetypes in rare disease therapeutics: platform technology leverage, mechanism diversification, and commercial scale execution.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Alnylam Pharmaceuticals, Inc. |
| Ionis Pharmaceuticals, Inc. |
| AstraZeneca PLC |
| BridgeBio Pharma Inc. |
| Intellia Therapeutics, Inc. |
| Akcea Therapeutics |
| Eidos Therapeutics, Inc. |
| Prothena Biosciences Limited |
| Others |
Value Network & Pricing Analysis
Viral vector manufacturing concentration in North American contract manufacturing organizations feeds directly into premium capture at gene therapy sponsors, while small molecule API sourcing from Indian and Chinese manufacturers anchors cost-competitive positioning for oral stabilizers. RNA interference therapies occupy a mid-tier pricing band reflecting cold-chain logistics burdens and specialty pharmacy dispensing fees.
Pricing Analysis
Gene therapy pricing in the United States commands a substantial premium over Japanese and European markets due to outcome-based contracting complexity and payer risk-sharing negotiations. Three-tier pricing structure across premium, standard, and economy levels separates one-time CRISPR interventions from chronic RNAi regimens and generic-bound small molecules. Pricing pressure stems from biosimilar entry timelines for antibody-based fibril clearers and reference pricing harmonization across EU member states. Community cardiology practices exhibit highest price sensitivity due to formulary tier placement constraints, while academic medical centers demonstrate lowest sensitivity given specialized commissioning carve-outs.
Supply Chain Analysis
Supplier-financing facilities extended by contract manufacturing organizations to gene therapy sponsors are compressing working capital cycles for viral vector production campaigns. Manufacturing concentration centers on the United States, Switzerland, and Singapore for biologics fill-finish, with plasmid DNA sourcing anchored in the United States and Germany. Raw material dependencies include HEK293 cell lines, recombinant proteins, and lipid nanoparticle formulations. Single-source vulnerability in AAV capsid supplier networks creates bottlenecks for CRISPR-based programs. Distribution runs through hospital-owned specialty pharmacies and independent infusion center networks with cold-chain custody requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy's one-time functional cure positioning threatens chronic RNA interference revenue streams, forcing incumbents to defend substitution through outcome-based contracting and patient monitoring service bundling.
For Market Incumbents: Harden market position by backward integration into viral vector manufacturing capacity in Massachusetts and North Carolina production corridors, securing supply autonomy against CMO allocation constraints. Expand patient monitoring service platforms to create switching costs for gene therapy candidates, embedding clinical data capture that supports real-world evidence generation for payer negotiations. For New Entrants and Emerging Players: Wild-type cardiac amyloidosis diagnosis in Japanese geriatric cardiology clinics represents the most penetrable entry point, leveraging PMDA sakigake designation pathways to compress regulatory timelines ahead of European filings. Antibody-fibril clearance convergence in advanced disease stages offers a complementary mechanism entry angle, requiring partnership with established amyloidosis centers for patient identification and infusion infrastructure access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed antisense oligonucleotide platform companies lacking commercial infrastructure to compete against Alnylam's established delivery networks. Long-term viability over the projection horizon depends on gene therapy manufacturing scale-up execution and hepatotoxicity surveillance protocol standardization. Watch for FDA breakthrough therapy designation announcements for CRISPR-based candidates as inflection indicators for chronic therapy displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Expands viral vector capacity to address supply bottlenecks constraining one-time dosing protocols. |
| Outcome-Based Contracting Framework | Aligns gene therapy reimbursement with longitudinal clinical outcomes, reducing payer uncertainty. |
| Specialty Clinic Network Partnership | Captures patient volume through dedicated amyloidosis center referral relationships. |
| CRISPR Regulatory Submission Pathway | Accelerates FDA review through breakthrough therapy and regenerative medicine advanced therapy designations. |
| Biomarker Diagnostic Expansion | Drives earlier disease detection through N-terminal pro-brain natriuretic peptide screening protocols. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designations, ClinicalTrials.gov entries, EMA parallel scientific advice documentation, and payer formulary databases. Conversations with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed competitive positioning assessments. Bottom-up patient volume modeling and top-down revenue reconciliation triangulated market size estimates across therapeutic modality segments.
Forecast inputs include treatment line progression rates, diagnostic expansion trajectories, and regional regulatory approval timelines across the analysis window. Segmentation dimensions encompass therapeutic modality, disease variant, delivery route, and end-user setting. CAGRs derive from patient population epidemiology, therapy penetration curves, and pricing evolution assumptions. Viral vector manufacturing capacity expansion schedules and hepatotoxicity surveillance protocol adoption rates constitute industry-specific forecast inputs.
Practitioners should monitor gene therapy manufacturing yield improvements, FDA accelerated approval conversion rates, and Japanese reimbursement determination timelines for early signals of chronic therapy displacement velocity. Forecasts reflect documented assumptions regarding patient identification rates, payer willingness-to-pay thresholds, and competitive launch sequencing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Polycystic Kidney Disease Treatment Market
Specialty Medicine
Interstitial Lung Disease Treatment Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Progressive Multifocal Leukoencephalopathy Treatment Market
Specialty Medicine
Europe Precision Medicine Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Neuromuscular Disorders Treatment Market
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Optic Atrophy Management Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Glaucoma Market
Specialty Medicine
Small Molecule Targeted Cancer Therapy Market