
 EMEA Dental Service Organization Market | 2026-2036
EMEA Dental Service Organization Market Size, Share, and Industry Trends Forecast 2026-2036
EMEA Dental Service Organization Market Analytics
Private equity-backed dental groups across the United Kingdom is hardening the supply of consolidated practice networks. Clyde Munro Dental Group leverages its Scottish base to anchor multi-site operations across northern England. Colosseum Dental Group sustains a European footprint that competes on standardized care protocols and centralized procurement. Portman Dental Care specializes in premium-positioned practices that dominate affluent suburban markets.
A Dental Service Organization contracts with or acquires dental practices to manage non-clinical operations including billing, marketing, equipment procurement, and regulatory compliance while licensed dentists retain clinical autonomy. These entities typically deploy practice management software integrating patient scheduling, electronic health records, and insurance claims processing across dozens to hundreds of locations. General dentistry generates the most visit volume and anchors cash flow predictability for group practice operators. Orthodontics and oral surgery command higher fee-per-visit structures that concentrate margin pools within corporate provider networks.
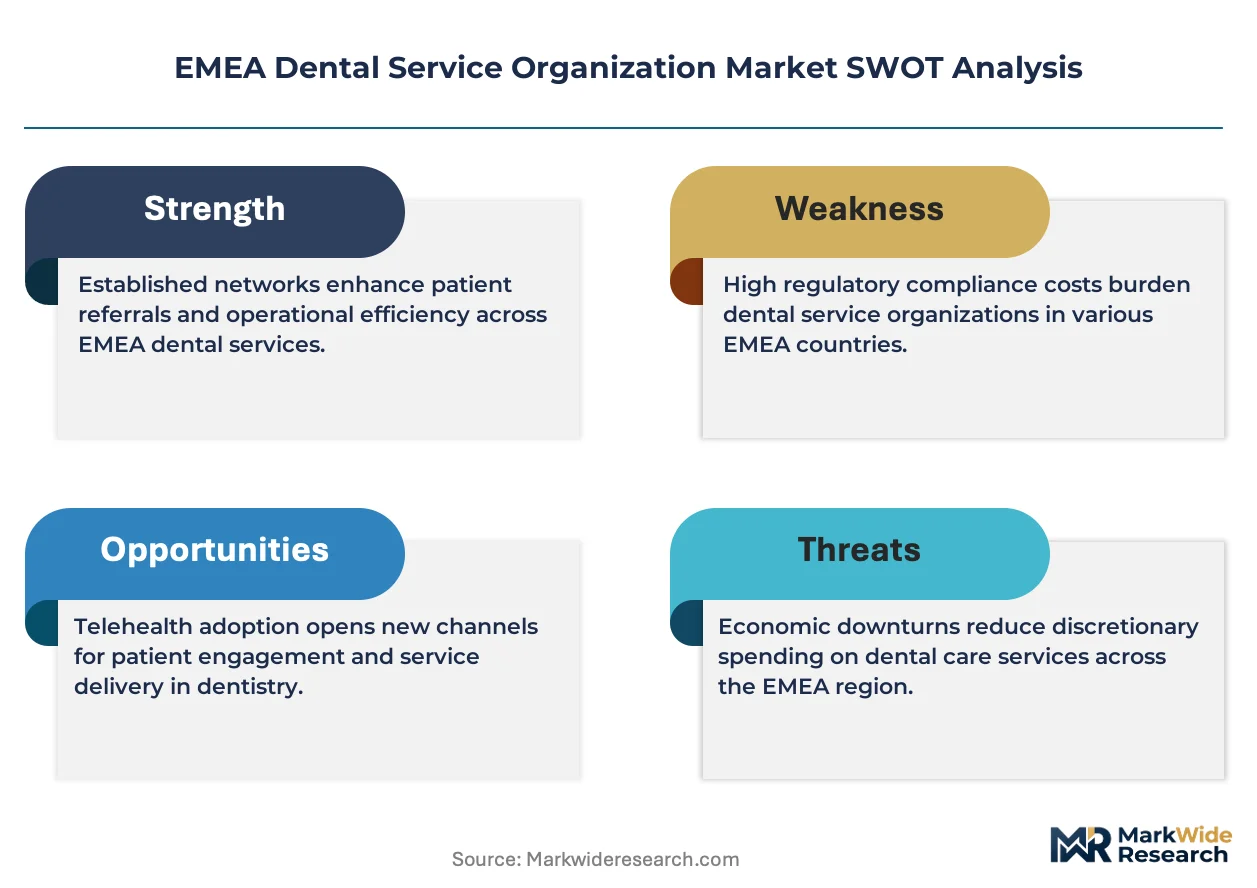
EMAA regulators including the UK Care Quality Commission, Germany's national dental chamber system, and the EU Medical Device Regulation shape operational standards and market access conditions across member states. The EU AI Act will impose conformity requirements on diagnostic imaging algorithms deployed through CAD/CAM systems and teledentistry platforms. Stakeholders must monitor how national reimbursement authorities calibrate fee schedules between independent practitioners and corporate networks.
Market Dynamics
National Health Service contract reforms across the United Kingdom are accelerating dentist migration from solo practices to corporate DSO structures. The EU Medical Device Regulation simultaneously elevates compliance costs for in-house dental laboratories, squeezing independent operators while rewarding centralized procurement networks.
Growth Catalysts
- UK NHS contract restructuring:Reimbursement rate compression and administrative burden reduction incentives push independent practitioners toward group practice models with shared back-office infrastructure.
- CAD/CAM chairside milling systems:Same-day crown production technology reduces laboratory outsourcing dependency and compresses patient visit cycles for multi-site operators.
- Germany's KZBV digitalization mandates:The national dental chamber system's interoperability requirements favor DSOs with capital to deploy integrated practice management platforms across locations.
Market Restraints
- EU MDR laboratory compliance costs:In-house dental laboratories face elevated documentation and quality management system investments that disproportionately burden smaller practice groups.
- Specialist dentist supply concentration:Oral surgeons and orthodontists cluster in urban academic centers across France and the Netherlands, limiting rural DSO expansion.
- Legacy practice valuation inflation:Private equity competition for UK dental assets has compressed acquisition returns below historical benchmarks.
Strategic Opportunities
- Poland and Czech Republic greenfield development:Low DSO penetration rates and growing private insurance coverage create first-mover expansion potential for standardized care protocols.
- EU AI Act diagnostic imaging pathway:Conformity requirements for radiological AI tools favor DSOs with centralized compliance functions and pooled regulatory expertise.
- Teledentistry platform integration:Remote consultation capabilities enable patient acquisition in underserved suburban and exurban catchments across northern England.
Industry Challenges
- Practice management system migration complexity:Consolidating disparate electronic health record architectures across acquired UK practices creates patient data continuity risks.
- Clinical autonomy governance frameworks:DSOs must structure oversight protocols that satisfy UK Care Quality Commission requirements without triggering dentist contractor reclassification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMEA Dental Service Organization Market |
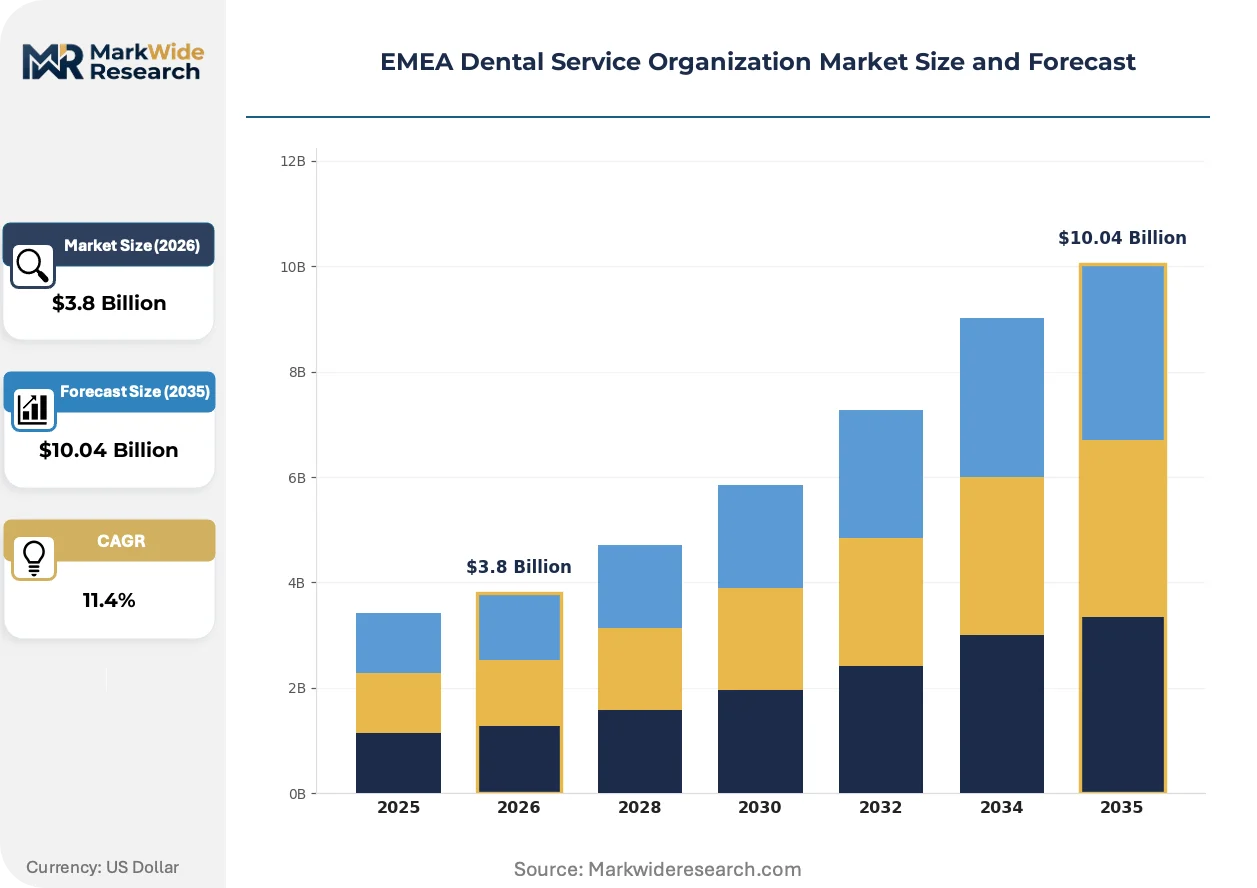
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: General Dentistry, Orthodontics, Endodontics, Oral Surgery Client Type: Private Practices, Group Practices, Corporate Providers, Dental Networks Technology: Teledentistry, CAD/CAM Systems, Imaging Technology, Practice Management Software End User: Patients, Dental Professionals, Insurance Companies, Health Maintenance Organizations |
| Companies Covered | mydentist, Clyde Munro Dental Group, Colosseum Dental Group, Bupa Dental Care, Dental Beauty Group Ltd, Riverdale Healthcare, European Dental Group, Dentex Healthcare Group, Portman Dental Care, Others |
| Regions Covered | EMEA: Germany, UK, France, Saudi Arabia, UAE, South Africa, Russia, Italy, Rest of EMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMEA Dental Service Organization Market Evolving Landscape
Digital workflow integration is compressing treatment timelines and reshaping capital allocation across EMEA dental groups. Three developments are restructuring competitive positioning.
Intraoral scanning hardware combined with cloud-based treatment planning software is expanding into mainstream general dentistry from its orthodontic origins. Multi-site DSOs in the United Kingdom and Germany are deploying chairside scanners across their general practitioner networks to capture margin previously lost to external laboratories. This technology convergence enables same-day restorative workflows that differentiate corporate networks from independent competitors.
The EU AI Act imposes conformity assessment requirements on diagnostic algorithms embedded in radiological imaging systems. DSO procurement teams must now validate that panoramic and CBCT equipment suppliers maintain notified body certification for AI-enhanced pathology detection. German dental groups with centralized technical compliance functions are responding faster than fragmented independent practices.
Patient acquisition patterns are rotating toward subscription-based preventive care packages. DSOs across suburban London and Manchester are displacing fee-for-service checkup models with annual membership structures that lock in recurring revenue. This behavioral shift concentrates most visibly in affluent commuter belts where household dental spending exceeds NHS reimbursement ceilings.
EMEA Dental Service Organization Market Segmentation
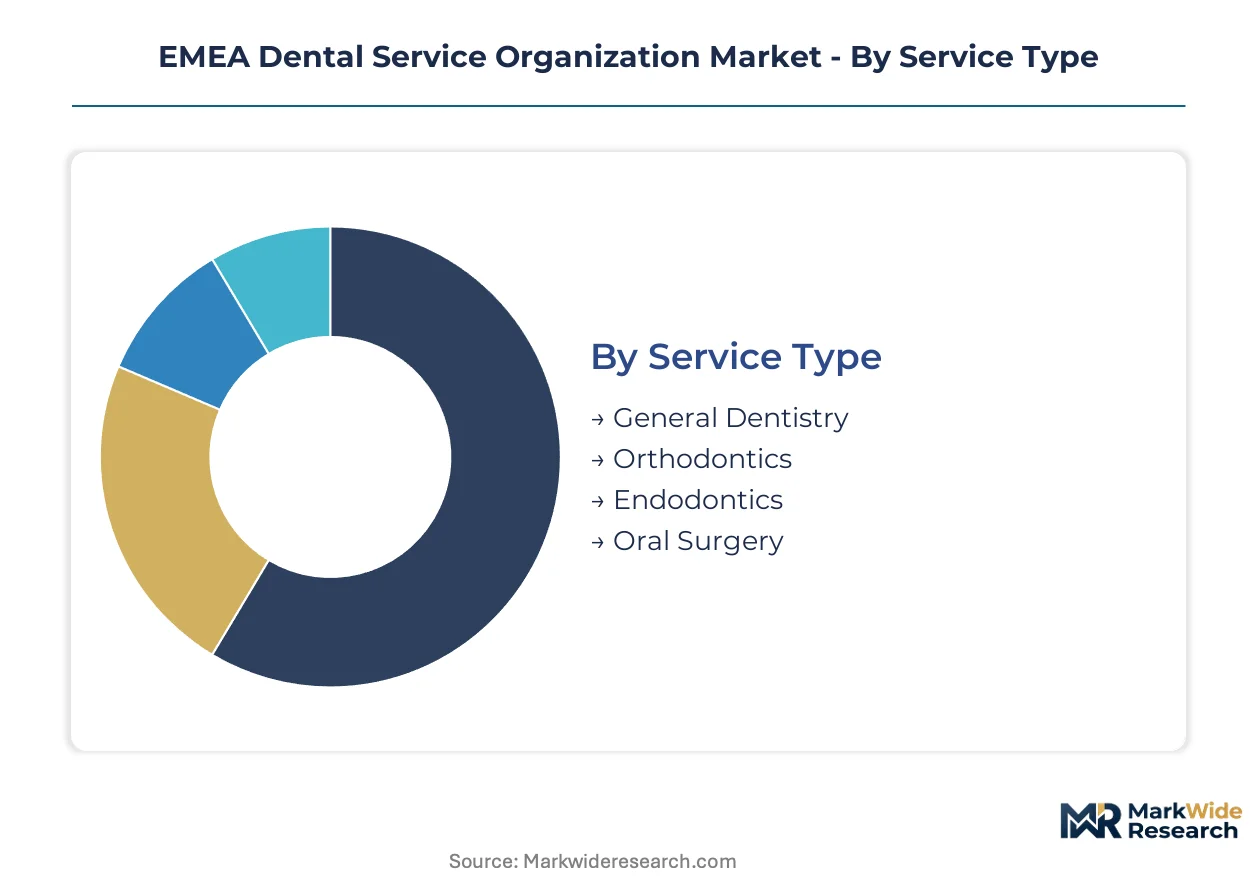
Dental Service Organizations segment their operations across service lines, client structures, technology platforms, and end-user relationships. Understanding these divisions reveals where capital concentrates and which integration models capture margin across European and Middle Eastern markets.
Service Type:
Service type segmentation distinguishes between standalone clinical offerings and those embedded within multi-specialty corporate networks.
- General Dentistry:Comprises preventive care, restorative procedures, and routine diagnostics that generate predictable visit volumes. Demand concentrates across suburban United Kingdom catchments where NHS contract reforms push independent practitioners toward group models with shared back-office infrastructure.
- Orthodontics:Involves teeth alignment therapies using fixed appliances and clear aligner systems that command premium fee structures. German DSOs embed orthodontic capacity within general practice networks to capture margin pools previously lost to standalone specialists in urban academic centers.
- Endodontics:Root canal therapies requiring specialized equipment and training that smaller practice groups struggle to justify.
- Oral Surgery:Complex extractions and implant placements demanding hospital-grade facilities that concentrate in metropolitan France and Netherlands clusters.
General Dentistry leads volumes today; Orthodontics is gaining share fastest.
Client Type:
Client type segmentation maps organizational maturity from solo operators through fully integrated corporate platforms.
- Private Practices:Solo or small-group operators retaining full clinical and administrative autonomy. United Kingdom private practices face mounting pressure from NHS reimbursement compression and are consolidating into larger entities at accelerating rates.
- Group Practices:Multi-dentist collaborations sharing overhead while maintaining independent ownership structures. German group practices leverage KZBV digitalization mandates to justify integrated practice management investments that solo operators cannot afford.
- Corporate Providers:Private equity-backed DSOs with centralized procurement and standardized protocols.
- Dental Networks:Affiliation models preserving clinical independence while pooling purchasing power and marketing resources.
Group Practices dominate transaction volumes; Corporate Providers show the steepest expansion trajectory.
Technology:
Technology segmentation separates point solutions from platforms requiring enterprise-wide deployment infrastructure.
- Teledentistry:Remote consultation and triage platforms enabling patient acquisition in underserved catchments. United Kingdom DSOs deploy teledentistry across northern England exurban corridors where physical practice density remains low.
- CAD/CAM Systems:Chairside milling and digital impression technologies compressing laboratory turnaround times. German corporate networks integrate CAD/CAM across general dentistry locations to displace external laboratory dependencies.
- Imaging Technology:Panoramic radiography and CBCT systems subject to EU AI Act conformity requirements.
- Practice Management Software:Scheduling, billing, and EHR platforms requiring interoperability compliance.
Practice Management Software anchors current infrastructure spending; CAD/CAM Systems are climbing the fastest.
End User:
End user segmentation identifies distinct value propositions across patient-facing and intermediary stakeholder groups.
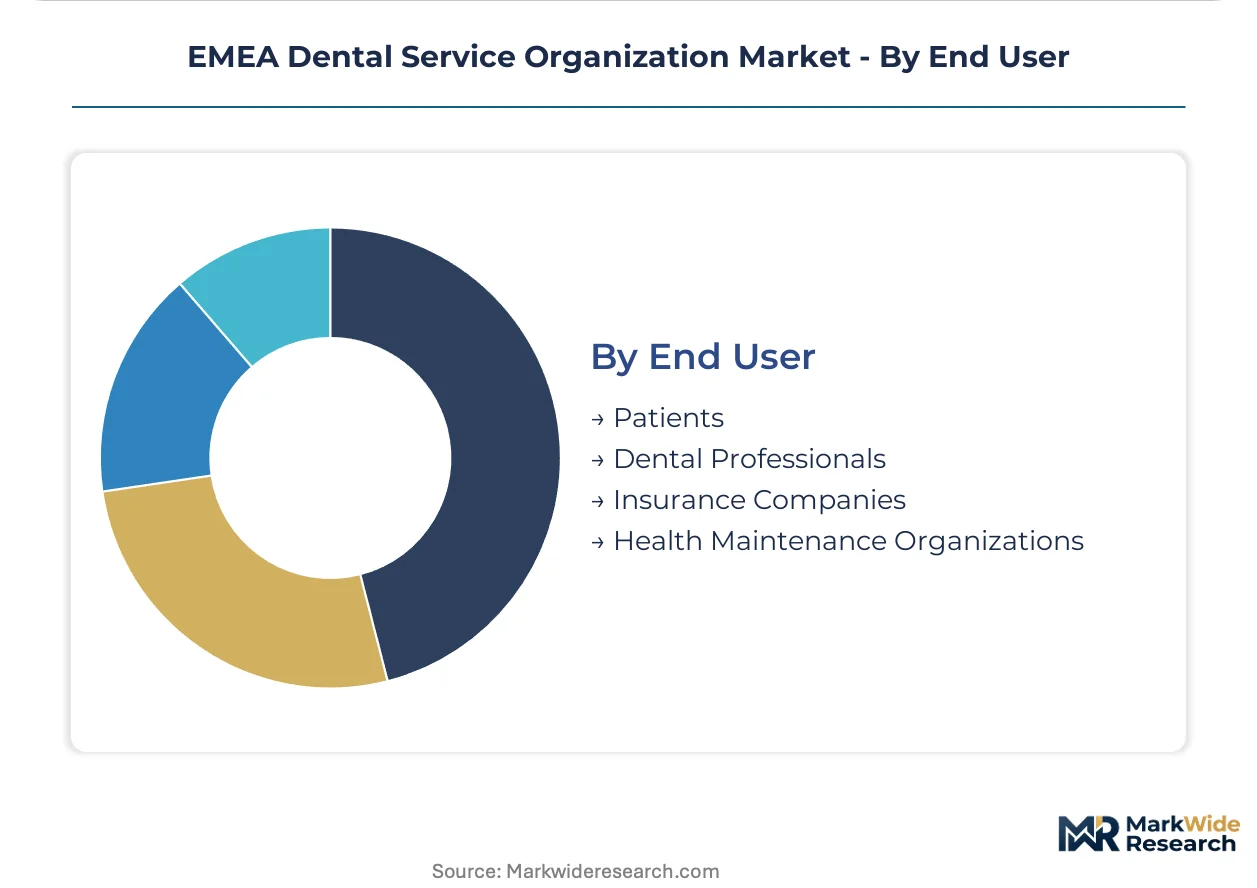
- Patients:Individual consumers selecting providers based on accessibility, price transparency, and service range. Affluent commuter belts around London and Manchester show strongest uptake of subscription-based preventive packages.
- Dental Professionals:Licensed practitioners evaluating DSO partnerships against clinical autonomy and compensation structures. United Kingdom dentist migration toward corporate models accelerates as NHS administrative burdens intensify.
- Insurance Companies:Payers calibrating reimbursement rates between independent and corporate network providers.
- Health Maintenance Organizations:Integrated care systems seeking contracted dental networks for capitated populations.
Patients drive absolute visit volumes; Dental Professionals represent the most contested stakeholder segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping DSO expansion patterns across Europe, Middle East, and Africa. Compliance cost differentials between EU member states and emerging markets are redirecting capital toward jurisdictions with lighter laboratory oversight and favorable reimbursement structures.
United Kingdom
NHS contract reforms are compressing reimbursement rates for independent practitioners while corporate networks absorb administrative burdens. The Care Quality Commission's inspection protocols favor centralized quality management systems that DSOs deploy across multi-site portfolios. Greater Manchester and West Midlands corridors host the densest concentrations of transitioning group practices.
Germany
KZBV digitalization mandates require interoperability-certified practice management platforms that disadvantage solo operators. The national dental chamber system's technical standards favor capital-rich networks with centralized IT infrastructure. North Rhine-Westphalia and Bavaria contain the highest densities of corporate-affiliated practices.
France
ANSM oversight of medical device conformity creates compliance gaps between independent laboratories and centralized DSO procurement functions. Reimbursement authority negotiations increasingly differentiate fee schedules by practice scale. Île-de-France and Auvergne-Rhône-Alpes concentrate specialist dentist supply that constrains rural network expansion.
Poland
Low DSO penetration rates and expanding private insurance coverage create first-mover opportunities for standardized care protocols. EU MDR implementation timelines lag core European markets, temporarily easing laboratory compliance burdens. Warsaw and Kraków metropolitan areas attract initial corporate development capital.
United Arab Emirates
MOHAP facility licensing frameworks favor international DSO operators with established quality management credentials. Medical tourism demand for premium dental services outpaces domestic insurer network development. Dubai Healthcare City and Abu Dhabi clusters concentrate expatriate-serving corporate practices.
EMEA Dental Service Organization Market Competitive Landscape
United Kingdom operators anchor one competitive tier; German and pan-European specialists hold differentiated positions through technology integration depth. Market structure exhibits moderate consolidation with private equity backing accelerating practice portfolio assembly. Three archetypes dominate: NHS-contracted volume players, premium-positioned suburban networks, and technology-forward multi-specialty platforms. M&A activity and centralized procurement network expansion represent the dominant competitive vectors.
Among UK-based corporate networks, mydentist, Clyde Munro Dental Group, and Colosseum Dental Group occupy distinct strategic positions. Mydentist represents the high-volume NHS-contracted archetype with national footprint scale. Clyde Munro Dental Group exemplifies regional consolidation specialists leveraging Scottish operational bases for northern England expansion. Colosseum Dental Group sits within the pan-European tier, competing through standardized protocols across multiple national jurisdictions.
| Leading Market Players |
|---|
| mydentist |
| Clyde Munro Dental Group |
| Colosseum Dental Group |
| Bupa Dental Care |
| Dental Beauty Group Ltd |
| Riverdale Healthcare |
| European Dental Group |
| Dentex Healthcare Group |
| Portman Dental Care |
| Others |
Value Network & Pricing Analysis
Centralized laboratory procurement anchors both supply positioning and pricing power across EMEA Dental Service Organizations, compressing unit costs for chairside milling equipment and CAD/CAM consumables while enabling subscription-based preventive care packages that lock in recurring revenue streams. This integration choice separates corporate networks from fragmented independent practices that face EU MDR compliance burdens without scale economies.
Pricing Analysis
Retailer markup structures dominate downstream dental equipment distribution, with three-tier pricing stratification across premium, standard, and economy equipment tiers differentiated by CE marking certification level and after-sales service bundling. Cost compression in the standard tier intensifies as German KZBV digitalization mandates force interoperability investments. NHS-contracted volume players exhibit highest price sensitivity; premium-positioned suburban networks serving affluent commuter belts around London and Manchester show lowest sensitivity due to household dental spending exceeding reimbursement ceilings.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss precision milling equipment suppliers that dominate chairside CAD/CAM hardware manufacturing. Raw material dependencies span titanium blanks for implant production, zirconia ceramics for crown milling, and optical scanning sensors sourced from Japan and South Korea. Tariff exposure on Chinese-manufactured intraoral scanners creates procurement risk. Distribution runs through specialized dental equipment distributors with direct-to-DSO procurement channels gaining share for multi-site operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMEA Dental Service Organization Market functions as a stable compounder, with NHS contract restructuring and EU regulatory harmonization driving predictable consolidation velocity across independent practice networks.
For Market Incumbents: Anchor defensive positioning through backward integration into in-house dental laboratory networks that absorb EU MDR compliance costs and capture margin from external laboratory displacement. Prioritize certification investment for AI-enhanced diagnostic imaging ahead of EU AI Act enforcement timelines. Consolidate acquired practice portfolios under unified practice management software architectures to reduce patient data continuity risks during system migrations. For New Entrants and Emerging Players: Enter via Poland and Czech Republic greenfield development where DSO penetration rates remain low and private insurance coverage expansion creates first-mover positioning for standardized care protocols. Target exurban catchments across northern England with teledentistry-enabled patient acquisition models that bypass saturated urban markets. Deploy subscription-based preventive care packages as the primary go-to-market angle to displace fee-for-service incumbents. For Investors and Strategic Acquirers: Roll-up economics work for regional consolidation specialists because NHS administrative burden compression and reimbursement rate pressure accelerate dentist migration from solo practices toward corporate structures. The 5-10 year viability window favors platforms with centralized compliance functions and pooled regulatory expertise. Target acquisition profiles center on group practices with 5-15 locations and legacy practice management systems requiring migration. Monitor Care Quality Commission inspection outcome trends as the signal to watch for regulatory risk inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CAD/CAM Platform Integration | Chairside milling deployment captures laboratory margin and compresses patient visit cycles across multi-site networks. |
| EU AI Act Compliance Pathway | Notified body certification for diagnostic imaging algorithms enables continued equipment procurement from approved suppliers. |
| Practice Portfolio Roll-up | Consolidation of independent UK practices absorbs NHS administrative burdens and scales centralized procurement. |
| Teledentistry Platform Launch | Remote consultation capabilities penetrate underserved exurban corridors with low physical practice density. |
| Subscription Care Model Introduction | Annual membership structures lock recurring revenue from affluent commuter belts exceeding NHS reimbursement ceilings. |
Research Methodology
Coverage spans the United Kingdom, Germany, France, Poland, Czech Republic, and United Arab Emirates, with primary inputs from each jurisdiction combining interviews with dental practice owners, DSO operations executives, dental equipment procurement managers, and regulatory affairs specialists with secondary validation from NHS contract databases, EU Medical Device Regulation filings, KZBV technical standards documentation, and national dental chamber system publications. Bottom-up practice count triangulation against top-down market value estimates anchored the analytical framework.
Granularity-level modeling deployed service type, client structure, technology platform, and end-user relationship dimensions across the projection horizon, with general dentistry visit volumes, orthodontic fee-per-visit structures, and corporate provider expansion trajectories as industry-specific forecast inputs. CAGRs were derived from segment-level growth rate reconciliation against aggregate market value expansion.
Inputs from NHS contracting authorities and EU notified bodies were available through the study window; gaps in private insurance coverage expansion timelines across Poland and Czech Republic introduce uncertainty bands around greenfield development velocity. Forecasts reflect assumptions regarding dentist migration rates and regulatory implementation schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Services
Global Dental Support Organizations Market
Dental Services
US Dental Chains Market
Dental Services
United States Dental Services Market
Dental Services
Dental Services Market
Dental Services
Orthodontic Services Market
Dental Services
Dental Fluoride Treatment Market
Dental Services
Dental Service Organization Market
Dental Services
Chronic Gingivostomatitis Treatment Market
Dental Services
Teledentistry Market
Dental Services
Dental Market
Dental Services
Microdontia Treatment Market
Dental Services
Periodontal Dental Service Market