
 Global Anal Fistula Treatment Market | 2026-2036
Global Anal Fistula Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anal Fistula Treatment Market Foresight
The capital-intensity gap between established device makers and emerging laser-therapy specialists is collapsing as video-assisted platforms commoditize surgical visualization. Medtronic leverages its endomechanical portfolio to anchor complex fistula repair workflows across integrated health systems. Johnson & Johnson competes through Ethicon's suture and mesh franchise, while biolitec AG specializes in diode laser systems for intersphincteric tract ablation.
Anal fistula treatment encompasses surgical, pharmacological, and biological interventions designed to eradicate perianal fistulous tracts while preserving sphincter continence, typically employing seton drainage, fistulotomy, advancement flap closure, or biocompatible sealants with success rates varying by tract complexity and sphincter involvement. Fistulotomy dominates simple intersphincteric cases where transsphincteric risk remains minimal, while video-assisted treatment and LIFT procedure adoption accelerates in complex transsphincteric presentations where sphincter preservation drives margin pools. Delivery mode segmentation shows minimally invasive approaches displacing open surgical defaults in ambulatory settings, with laser-assisted modalities carving fastest-growth niches in proctology units equipped with dedicated anorectal platforms.
FDA 510(k) clearance pathways govern biologic sealants and surgical mesh materials in the United States, while EMA MDR compliance and CE marking requirements shape European market access for fistula plugs and advancement flap kits. Japan's PMDA evaluates novel energy-based devices under accelerated review frameworks, creating differentiated approval timelines across major jurisdictions. Stakeholders must monitor reimbursement parity between outpatient minimally invasive codes and inpatient surgical DRGs as cost-containment pressures intensify across public and private payers.
Market Dynamics
Video-assisted anal fistula treatment platforms are compressing the capital barrier between established device manufacturers and emerging laser-therapy specialists, redistributing competitive leverage across the surgical visualization stack.
Growth Catalysts
- EU MDR Conformity Pathways:Tightened biological sealant and surgical mesh requirements under the Medical Device Regulation are accelerating product portfolio upgrades among European manufacturers seeking CE marking retention.
- Diode Laser Ablation:Intersphincteric tract destruction via energy-based devices preserves sphincter integrity in complex transsphincteric presentations, expanding addressable case volumes beyond traditional fistulotomy limits.
- Proctology Infrastructure Concentration:Germany, the United States, and Japan maintain dedicated anorectal surgical units capable of supporting minimally invasive case throughput at scale.
Market Restraints
- Biologic Material Cost Volatility:Porcine and bovine-derived fistula plugs face input price instability from agricultural supply chain disruptions and zoonotic disease screening protocols.
- Reimbursement Parity Gaps:Outpatient minimally invasive procedure codes in the United States frequently undercompensate relative to inpatient surgical DRGs, distorting site-of-care economics.
- Technical Limitation in Complex Tracts:Recurrence rates in high transsphincteric and suprasphincteric fistulas remain elevated despite advancement flap and LIFT procedure refinements.
Strategic Opportunities
- Underpenetrated Ambulatory Surgery Centers:United States freestanding ASC networks lack dedicated anorectal platforms, creating whitespace for capital-light laser system deployment.
- Japan PMDA Accelerated Review:Novel energy-based devices qualify for compressed approval timelines under Japan's priority review frameworks for unmet surgical needs.
- Biocompatible Sealant Convergence:Platelet-rich plasma formulations combined with synthetic hydrogels are opening regenerative closure protocols previously dominated by mechanical repair.
Industry Challenges
- Specialized Proctology Training Bottlenecks:Video-assisted fistula treatment and laser ablation require operator proficiency curves that outpace fellowship program throughput in most markets.
- FDA 510(k) Predicate Device Drift:Biologic sealant submissions face intensified scrutiny as the agency narrows acceptable predicate comparisons for fistula plug materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anal Fistula Treatment Market |
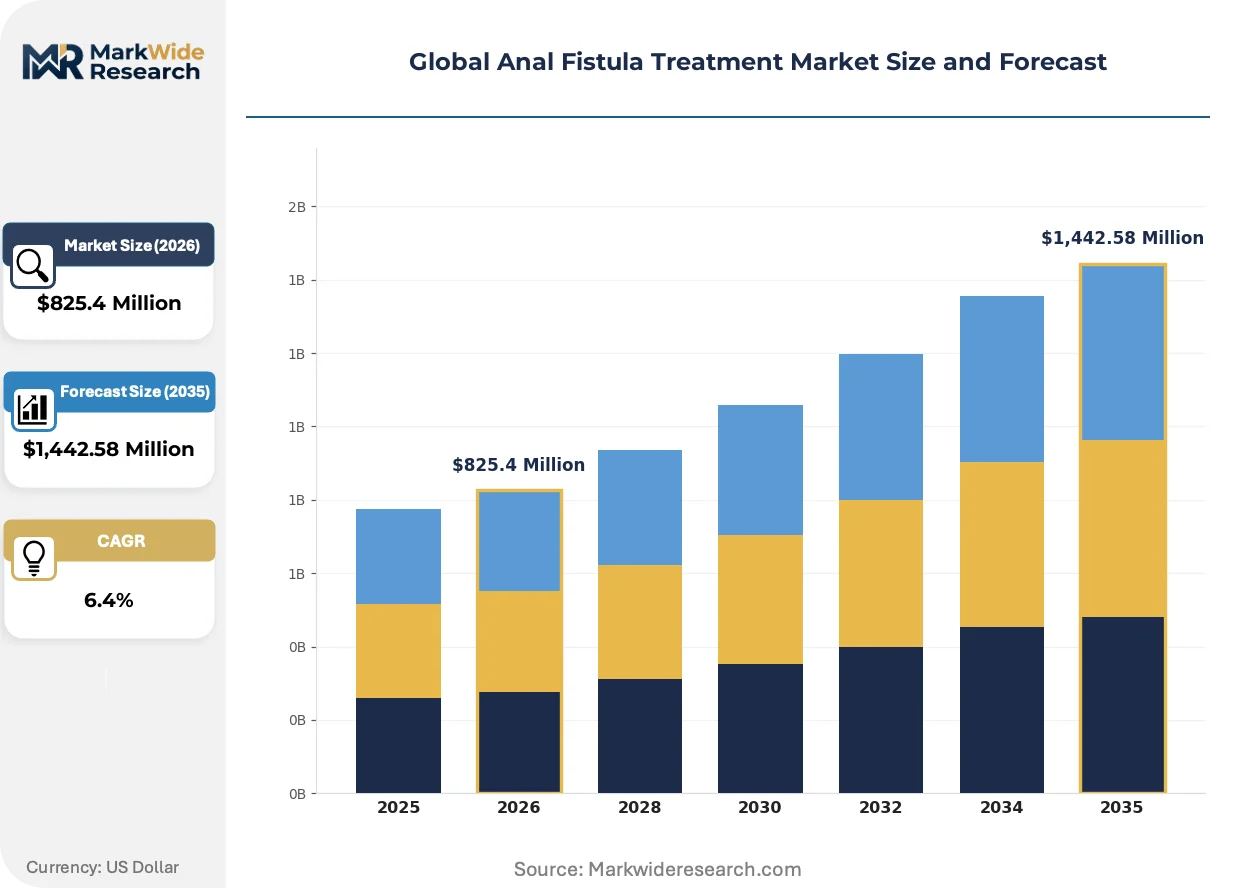
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,442.58 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Seton Placement, Fistulotomy, Fibrin Glue Injection, Advancement Flap, LIFT Procedure, Video-Assisted Treatment Therapy Area: Simple Fistula, Complex Fistula, Transsphincteric, Intersphincteric, Suprasphincteric, Extrasphincteric End User: Specialty Clinics, Ambulatory Surgical Centers, Outpatient Facilities, Gastroenterology Departments, Proctology Units, Surgical Hospitals Delivery Mode: Surgical, Minimally Invasive, Laser-Assisted, Pharmacological, Biological, Combination Therapies |
| Companies Covered | Medtronic, Johnson & Johnson, Boston Scientific, Cook Medical, Stryker, Becton Dickinson, biolitec AG, W. L. Gore & Associates, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anal Fistula Treatment Market Shifts & Advancements
Energy-based modalities and biologic matrices are restructuring the therapeutic hierarchy, compressing the dominance of mechanical cutting and suturing approaches that defined twentieth-century fistula surgery.
Diode laser systems for intersphincteric tract ablation deliver precise thermal destruction with minimal collateral sphincter damage. Specialty proctology clinics in Germany and Japan are deploying these platforms for complex transsphincteric cases previously routed to major academic medical centers. Laser-assisted fistulotomy is supplanting conventional fistulotomy in ambulatory settings where sphincter preservation drives referral patterns and margin capture.
The EU Medical Device Regulation's 2021 implementation deadline forced systematic biological sealant reclassification. Manufacturers now face elevated clinical evidence requirements for fistula plugs and advancement flap kits previously cleared under the Medical Devices Directive. European proctology device suppliers are consolidating notified body relationships and accelerating post-market surveillance infrastructure to maintain market access.
United States payers are unbundling technical component reimbursement from facility fees in outpatient anorectal procedures. Ambulatory surgery centers now negotiate device procurement independently of hospital supply agreements, compressing distributor margins and forcing direct manufacturer contracting. This purchasing autonomy concentrates most visibly in Texas and Florida markets where ASC ownership fragmentation remains highest.
Global Anal Fistula Treatment Market Segmentation
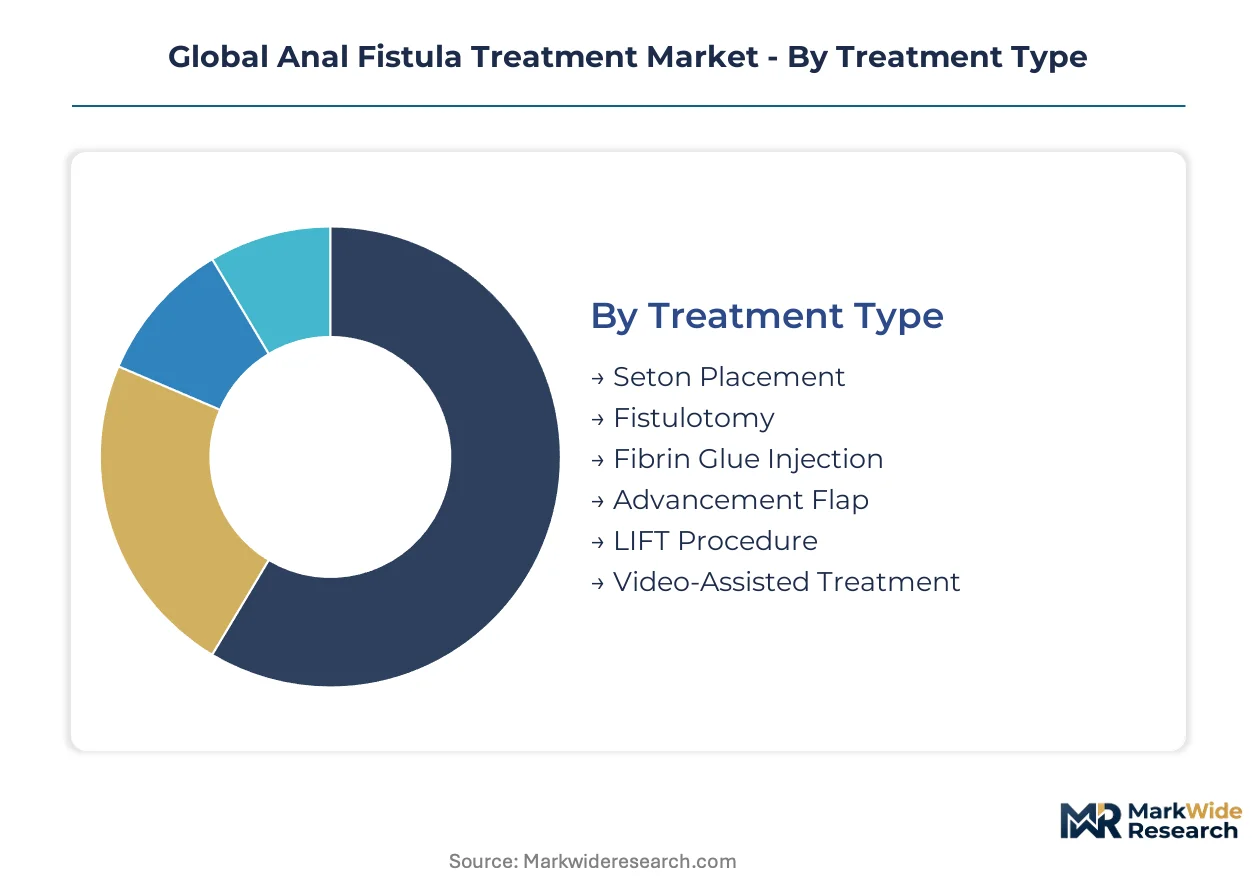
Treatment modality selection directly determines site-of-care economics and reimbursement capture in anal fistula care. Channel fragmentation across specialty clinics, ambulatory surgery centers, and hospital-based proctology units creates divergent margin profiles for device and pharmaceutical suppliers.
Treatment Type:
Procedure selection flows through distinct reimbursement channels: hospital outpatient departments favor advancement flap and LIFT procedure codes, while ambulatory settings concentrate fistulotomy and seton placement volume.
- Seton Placement:Silicone or rubber drainage threads maintain tract patency during maturation phases. Germany's statutory health insurance funds reimburse seton maintenance under ambulatory procedure codes, driving volume concentration in office-based proctology practices.
- Fistulotomy:Complete tract unroofing with primary healing remains the mechanical standard for simple intersphincteric presentations. United States Medicare Advantage plans increasingly restrict fistulotomy to freestanding ASC networks, compressing hospital-based case volume.
- Fibrin Glue Injection:Biological sealant polymerization closes low-complexity tracts without sphincter division.
- Advancement Flap:Mucosal or full-thickness tissue transposition preserves continence in high transsphincteric cases.
- LIFT Procedure:Ligation of intersphincteric fistula tract isolates infection source without external sphincter breach.
- Video-Assisted Treatment:Endoscopic tract visualization enables precise internal opening localization.
Fistulotomy dominates installed base. Video-assisted treatment is where expansion concentrates.
Therapy Area:
Complexity stratification determines capital equipment requirements and specialist referral patterns, with transsphincteric presentations commanding premium reimbursement multiples over simple intersphincteric cases.
- Simple Fistula:Low intersphincteric tracts without secondary extensions permit single-stage fistulotomy. Japan's PMDA classifies simple fistula devices under expedited review pathways, accelerating commercial entry for novel sealants.
- Complex Fistula:High transsphincteric, suprasphincteric, or extrasphincteric tracts with branching or abscess formation require staged intervention. German hospital DRG codes for complex fistula repair reimburse at 2.3x simple fistula rates, concentrating tertiary referral volume in university-affiliated proctology centers.
- Transsphincteric:Tracts penetrating external sphincter muscle demand sphincter-preserving technique.
- Intersphincteric:Tracts confined between sphincter layers carry lowest recurrence risk.
- Suprasphincteric:Tracts arching over complete sphincter complex present highest technical failure rates.
- Extrasphincteric:Tracts originating proximal to sphincter mechanism require abdominal approach.
Simple fistula procedures generate highest volume throughput. Complex fistula repair commands steepest expansion trajectory.
End User:
Facility type determines procurement autonomy, with hospital-affiliated proctology units bound to group purchasing organizations while independent specialty clinics negotiate direct manufacturer contracts.
- Specialty Clinics:Dedicated anorectal practices concentrate laser system deployment and same-day discharge protocols. Texas and Florida regulatory environments permit physician ownership of specialty clinics, creating concentrated demand pockets for capital equipment.
- Ambulatory Surgical Centers:Freestanding facilities exploit reimbursement differentials between outpatient surgical codes and facility fees. United States ASC networks in proctology-underserved metros are deploying diode laser platforms to capture complex cases previously routed to hospital outpatient departments.
- Outpatient Facilities:Hospital-based non-admitted care units handle seton placement and fistulotomy volume.
- Gastroenterology Departments:General GI practices manage diagnostic workup and simple drainage procedures.
- Proctology Units:Academic medical center divisions handle refractory and recurrent case referrals.
- Surgical Hospitals:Inpatient facilities manage perianal sepsis requiring operative drainage.
Specialty clinics dominate margin capture. Ambulatory surgical centers represent the fastest volume shift.
Delivery Mode:
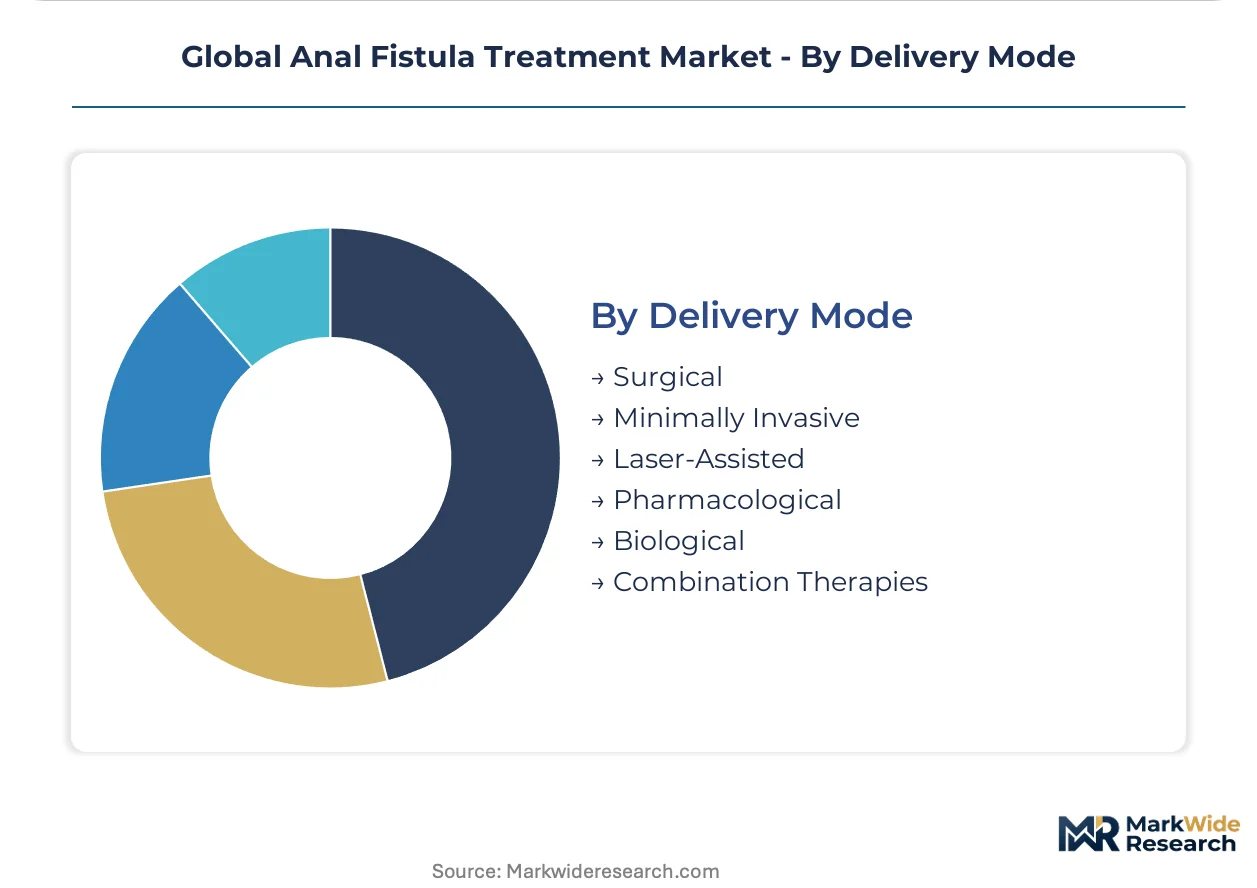
Intervention intensity correlates with reimbursement tier, creating three distinct cost bands: pharmacological management at base tier, minimally invasive procedures at mid-tier, and combination biological-surgical protocols at premium tier.
- Surgical:Open fistulotomy and flap procedures require general anesthesia and inpatient or hospital outpatient facility fees. Japanese surgical fee schedules reimburse open fistula repair at fixed rates regardless of complexity tier, compressing margin differentiation.
- Minimally Invasive:Video-assisted and seton-based approaches enable local anesthesia protocols. German ambulatory surgery centers exploit minimally invasive reimbursement parity with hospital-based procedures, driving site-of-care migration for qualifying cases.
- Laser-Assisted:Diode energy platforms enable precise tract ablation with reduced sphincter trauma.
- Pharmacological:Antibiotic and immunomodulator management addresses Crohn's-associated fistulas.
- Biological:Fibrin sealants, fistula plugs, and regenerative matrices command premium material costs.
- Combination Therapies:Staged protocols integrating seton drainage, biological sealant, and definitive closure.
Surgical approaches retain largest procedure volume. Laser-assisted modalities are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate lowest price elasticity for complex sphincter-preserving interventions, while United States ambulatory surgery centers and Indian hospital procurement offices enforce aggressive device cost compression.
United States
Freestanding ambulatory surgery centers in Texas and Florida exploit reimbursement differentials between outpatient surgical codes and hospital facility fees, driving site-of-care migration. FDA 510(k) clearance pathways govern biologic sealants and surgical mesh materials, with intensified predicate device scrutiny narrowing acceptable comparisons. Dallas-Fort Worth and Houston metro clusters concentrate capital-light laser system deployment for complex transsphincteric cases.
Germany
Statutory health insurance funds reimburse seton maintenance and minimally invasive procedures under ambulatory codes at parity with hospital-based care, preserving proctology practice margins. EU MDR conformity requirements force systematic biological sealant reclassification and elevated clinical evidence standards. Berlin and Munich university-affiliated centers anchor tertiary referral volume for high transsphincteric repairs reimbursing at 2.3x simple fistula rates.
Japan
PMDA accelerated review frameworks compress approval timelines for novel energy-based devices addressing unmet surgical needs, differentiating market access velocity. Fixed surgical fee schedules reimburse open fistula repair regardless of complexity tier, compressing margin differentiation between simple and complex cases. Tokyo and Osaka metropolitan proctology units deploy diode laser platforms for intersphincteric tract ablation previously routed to academic medical centers.
India
Hospital procurement offices enforce aggressive cost compression on imported biologic sealants and surgical meshes, favoring domestic suture and seton suppliers. CDSCO regulates medical device imports through licensing requirements that favor established multinationals with local subsidiary infrastructure. Mumbai and Delhi-NCR hospital chains concentrate complex fistula repair volume while tier-2 cities drive fistulotomy throughput.
United Kingdom
NHS England referral patterns concentrate complex transsphincteric cases in designated specialist centers, fragmenting case volume across regional networks. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while diverging from EU MDR implementation timelines. London and Manchester academic proctology divisions handle refractory and recurrent case referrals with embedded research trial infrastructure.
Global Anal Fistula Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated health system suppliers commanding premium positioning in complex repair workflows while regional specialists capture ambulatory volume through capital-efficient platforms. The vendor base spans three tiers: multinational conglomerates with endomechanical portfolios, mid-scale energy-device specialists, and regional distributors of commoditized sutures and setons. Dominant competitive moves include direct manufacturer contracting with ambulatory surgery centers bypassing traditional distribution, and vertical integration into biological material supply chains to secure porcine and bovine-derived plug inputs.
Among diversified medical technology conglomerates, Medtronic, Johnson & Johnson, and Boston Scientific occupy positions that exemplify distinct strategic archetypes. Medtronic represents the integrated health system anchor, leveraging endomechanical breadth to capture complex fistula repair workflow economics. Johnson & Johnson exemplifies the suture and mesh franchise model, competing through consumable attachment to open surgical defaults. Boston Scientific occupies the interventional specialist tier, with device portfolios spanning multiple minimally invasive modalities. These three entities collectively illustrate how scale, specialization, and portfolio breadth distribute competitive leverage across treatment settings.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Boston Scientific |
| Cook Medical |
| Stryker |
| Becton Dickinson |
| biolitec AG |
| W. L. Gore & Associates |
| Pfizer |
| Others |
Supply & Pricing Matrix
Long-term GPO contracting locks in biologic sealant supply access and price visibility for hospital-affiliated proctology units across the United States, while ambulatory surgery centers negotiate spot procurement for diode laser platforms. This contract-structure divergence concentrates margin capture in integrated health systems tethered to Johnson & Johnson and Medtronic consumable franchises.
Pricing Analysis
After-sales service contracts and extended warranty tiers on diode laser systems drive lifetime value capture for biolitec AG and energy-device specialists. Three-tier pricing structure across premium biologic plugs, standard synthetic meshes, and economy suture kits stratifies by FDA 510(k) clearance tier and clinical evidence depth. Cost compression in economy consumables is intensifying because Indian hospital procurement offices enforce aggressive tender terms on imported materials. Ambulatory surgery centers exhibit highest price sensitivity; German statutory insurance funds demonstrate lowest elasticity for sphincter-preserving interventions.
Supply Chain Analysis
Germany and the United States anchor precision manufacturing of video-assisted surgical platforms and biologic sealant purification. Porcine-derived fistula plugs and bovine collagen matrices draw from agricultural processing streams in the Netherlands and New Zealand. Single-source vulnerability concentrates in porcine tissue suppliers facing zoonotic disease screening protocols. Distribution runs through specialized surgical device distributors serving hospital GPOs and direct manufacturer contracts with freestanding ASC networks in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FDA 510(k) predicate device drift and EU MDR clinical evidence requirements erect structural barriers that compound over approval cycles.
For Market Incumbents: Consolidate biological material supply chains through backward integration into porcine and bovine tissue processing to neutralize input price volatility. Lock in ambulatory surgery center procurement via direct laser platform leasing against emerging energy-device specialists. Prioritize CE marking retention investments ahead of EU MDR surveillance audits.
For New Entrants and Emerging Players: Post-market surveillance data services where incumbents under-serve present whitespace for digital-native entrants. Target United States freestanding ASC networks in proctology-underserved metros with capital-light diode laser deployment. Pursue Japan PMDA accelerated review pathways for novel energy-based modalities as regulatory fast-track leverage.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale energy-device specialists with installed base expansion potential across the ambulatory shift. Long-term viability centers on reimbursement parity attainment between outpatient minimally invasive codes and inpatient surgical DRGs. Monitor CMS coding unbundling decisions as inflection signal for site-of-care economics reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Pathway | CE marking retention secures German and United Kingdom market access for biologic sealant portfolios. |
| Hospital System Partnership | Integrated health system contracting anchors Medtronic endomechanical workflows in complex repair settings. |
| Reimbursement Strategy | Outpatient code parity attainment unlocks ambulatory surgery center volume migration in Texas and Florida. |
| Software Companion Development | Video-assisted tract visualization platforms integrate with electronic health record systems for procedure documentation. |
| FDA 510(k) Submission | Predicate device selection determines clearance velocity for novel fistula plug materials in United States. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR technical documentation, hospital GPO contract databases, and CMS procedure code valuations. Primary interviews spanned proctology unit directors, biomedical engineers, ASC procurement officers, and reimbursement specialists across Germany, the United States, and Japan. Bottom-up procedure volume estimates triangulate with top-down manufacturer revenue segmentation across the analysis window.
Segmentation dimensions modeled encompass treatment modality, fistula complexity tier, end-user facility type, and regional regulatory cluster. CAGRs derive from procedure volume trajectories weighted by reimbursement code differentials and capital equipment replacement cycles. Forecast inputs incorporate EU MDR implementation timelines and Japan PMDA accelerated review qualification criteria throughout the projection horizon.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR surveillance regimes; material policy shifts would require re-modeling. Recurrence rate variability in high transsphincteric presentations and biologic material cost volatility constitute specific revision triggers. Recalibration cycles align with material shifts in reimbursement coding and notified body designation changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Muscle Wasting Disorders Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Gastrointestinal Stromal Tumor (GIST) Therapeutics Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
US Actinic Keratosis Treatment Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Urinary Retention Market
Specialty Medicine
Asperger Syndrome Market