
 Cryptococcosis Market | 2026-2036
Cryptococcosis Market Size, Share, and Industry Trends Forecast 2026-2036
Cryptococcosis Market Analysis
Specialized infectious disease pharmacists is bifurcating the competitive landscape between multinational developers and regional formulators. Pfizer Inc leverages decades of antifungal manufacturing scale to sustain cost-efficient amphotericin B supply chains across endemic regions. Gilead Sciences, Inc. competes through its HIV therapeutic footprint, which anchors cross-selling opportunities into cryptococcal prophylaxis and treatment protocols. Merck & Co., Inc. differentiates via operational strength in hospital channel contracting, securing preferred formulary status in large academic medical centers.
Cryptococcosis constitutes a systemic fungal infection caused by Cryptococcus neoformans and Cryptococcus gattii species complexes, primarily manifesting as meningoencephalitis in immunocompromised hosts with mortality exceeding 50% in untreated HIV-positive cases. The condition demands prolonged combination therapy involving amphotericin B induction followed by fluconazole consolidation and maintenance phases to achieve durable clearance. Amphotericin B dominates current hospital procurement volumes due to its fungicidal potency against severe disseminated disease, though nephrotoxicity constraints sustain demand for liposomal formulations that command premium positioning. Oral fluconazole occupies the largest outpatient maintenance segment, while intravenous administration routes retain structural importance in initial inpatient stabilization where CNS penetration and rapid fungal burden reduction prove critical.
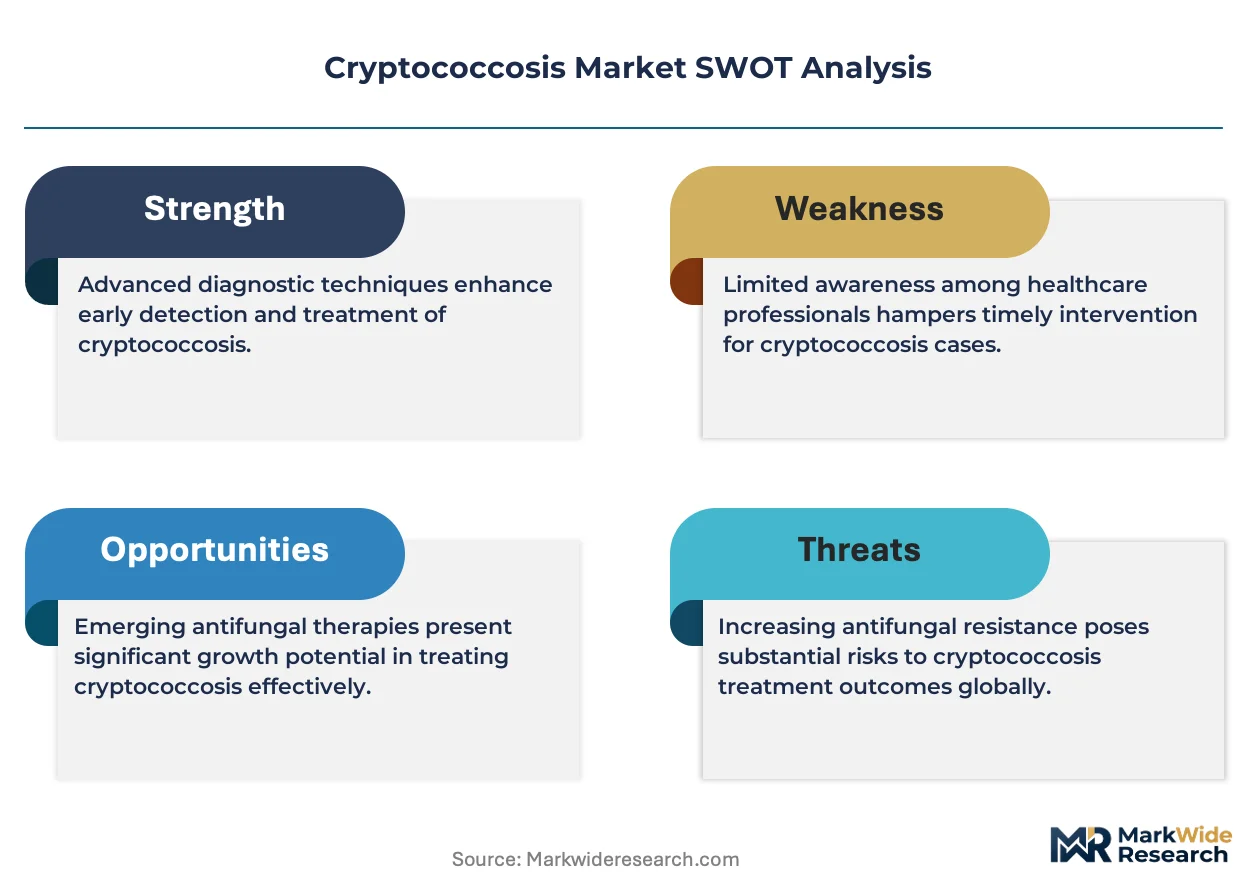
FDA orphan drug designation frameworks and EMA priority medicines pathways incentivize developers to advance novel antifungal candidates through accelerated regulatory channels. WHO inclusion of cryptococcal meningitis on its Essential Medicines List shapes procurement standards and donor-funded access programs across endemic African and Southeast Asian markets. Stakeholders must monitor evolving resistance patterns to azole therapy and corresponding shifts in clinical guideline recommendations that could restructure first-line treatment hierarchies.
Market Dynamics
Hospital formulary committees are consolidating purchasing power around liposomal amphotericin B formulations, compressing margins for conventional deoxycholate variants while elevating quality-of-care metrics as the decisive procurement criterion.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate clinical trial investment for novel cryptococcal meningitis therapeutics, drawing biotech sponsors into previously neglected indication areas.
- WHO Essential Medicines Listing:Inclusion of cryptococcal meningitis diagnostics and treatments shapes donor-funded procurement standards across endemic African markets, stabilizing demand visibility for manufacturers.
- HIV Therapeutic Integration:Cross-protocol prescribing between antiretroviral and antifungal regimens creates bundled treatment pathways in South African and Brazilian public health systems.
Market Restraints
- Amphotericin B Supply Concentration:Active pharmaceutical ingredient production clusters in select Asian manufacturing hubs, exposing procurement chains to single-source disruption risks.
- Nephrotoxicity-Driven Formulation Costs:Liposomal encapsulation technology demands specialized manufacturing infrastructure, constraining price competition against conventional deoxycholate alternatives.
- Azole Resistance Surveillance Gaps:Inconsistent laboratory capacity across endemic regions delays detection of fluconazole-resistant Cryptococcus strains, complicating empiric therapy selection.
Strategic Opportunities
- Point-of-Care Diagnostic Expansion:Lateral flow cryptococcal antigen tests enable same-day treatment initiation in Ugandan and Malawian primary care settings, bypassing centralized laboratory bottlenecks.
- Single-Dose Regimen Development:High-dose liposomal amphotericin B protocols reduce hospitalization duration, aligning with South African national health insurance cost-containment objectives.
- EMA Priority Medicines Pathway:Accelerated assessment frameworks for unmet medical needs shorten time-to-market for novel antifungal classes targeting azole-refractory infections.
Industry Challenges
- Infectious Disease Pharmacist Shortage:Specialized expertise in therapeutic drug monitoring for amphotericin B nephrotoxicity management remains scarce across Brazilian public hospital networks.
- Cold Chain Infrastructure Deficits:Liposomal formulation stability requirements strain distribution capabilities in rural Indian and Southeast Asian treatment corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryptococcosis Market |
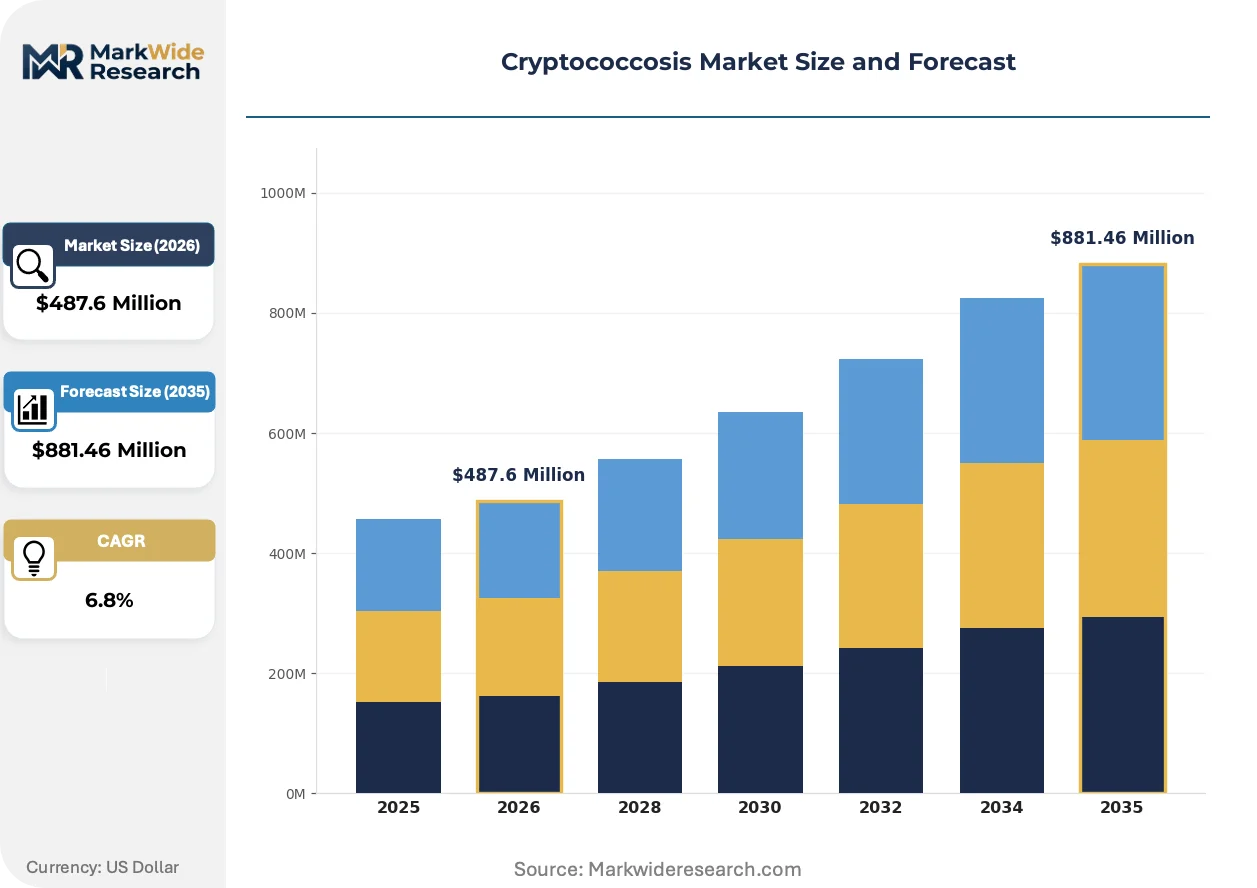
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
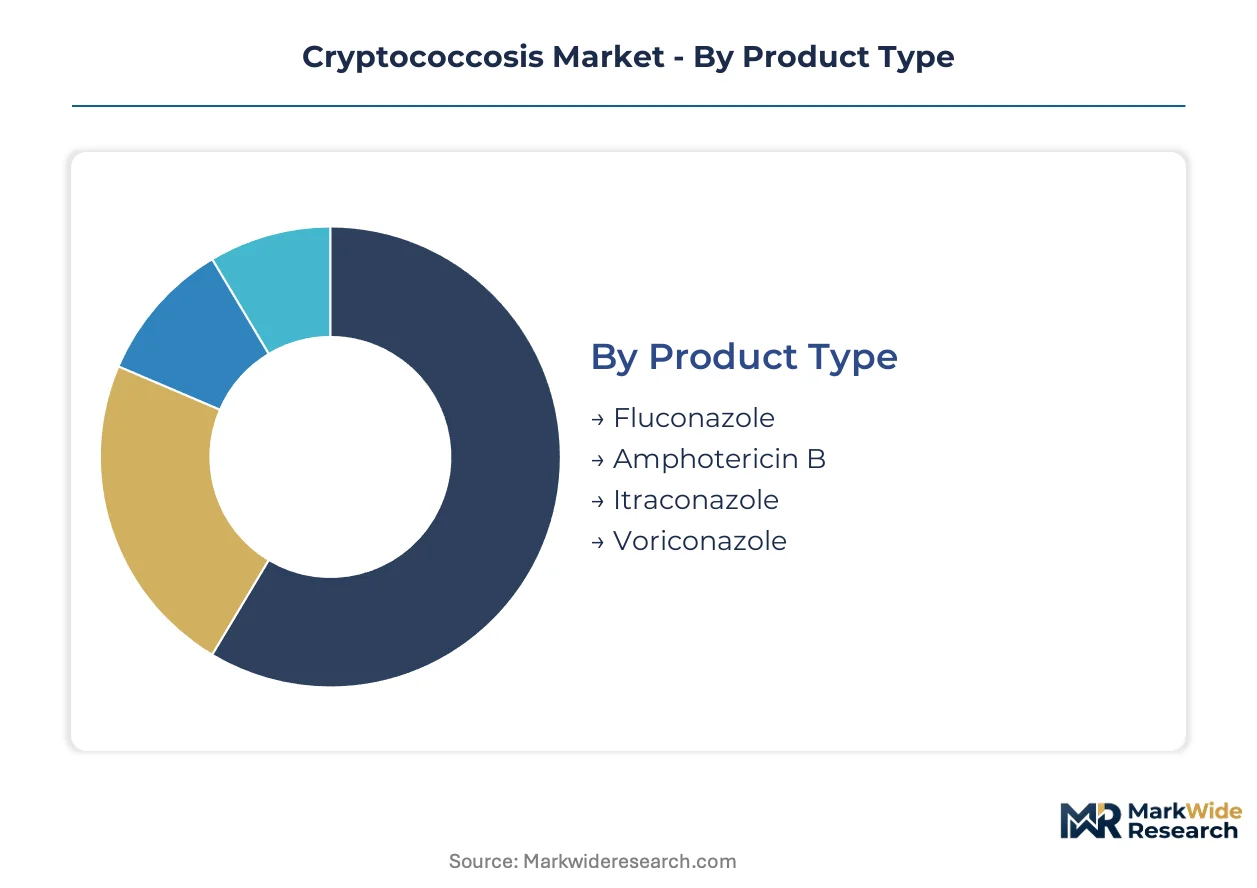
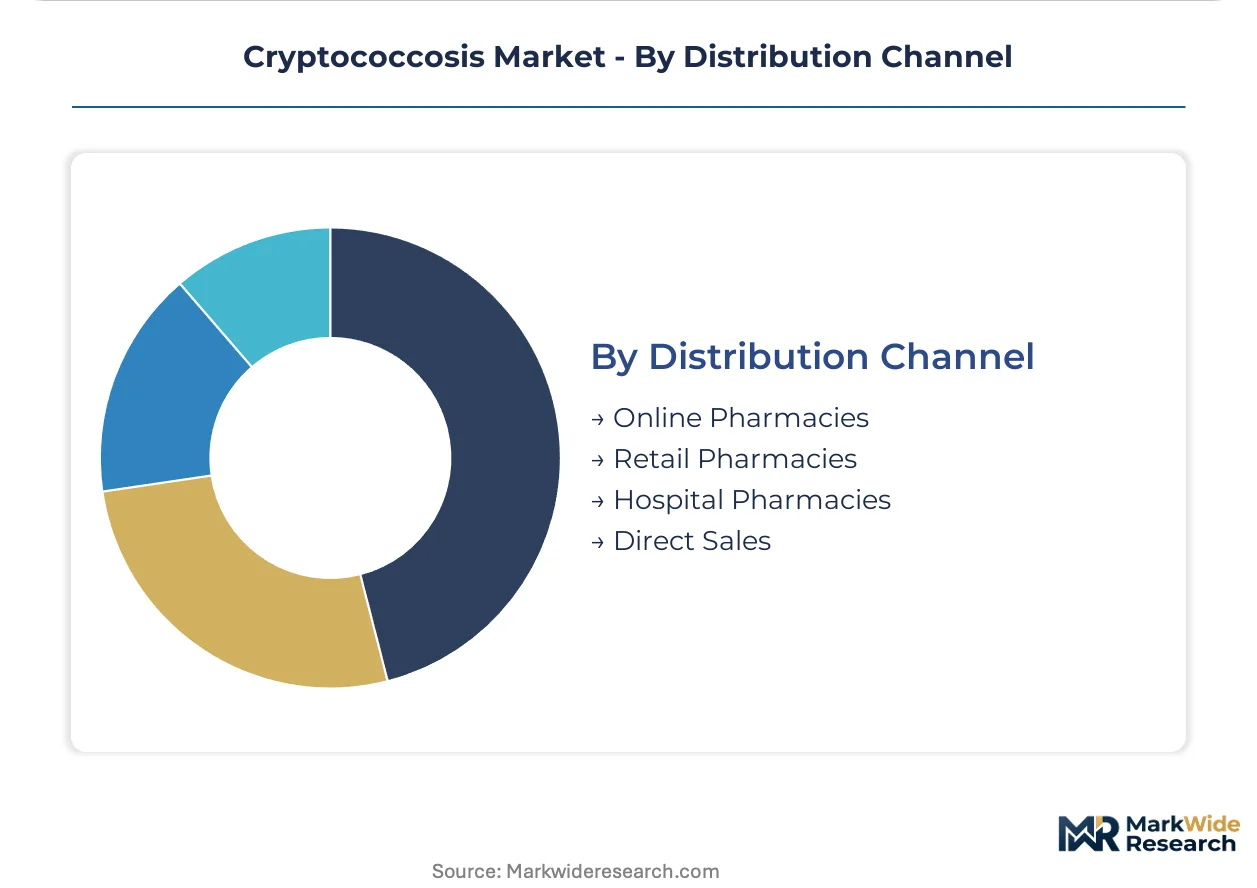
| Segmentation | Product Type: Fluconazole, Amphotericin B, Itraconazole, Voriconazole End User: Hospitals, Clinics, Research Laboratories, Home Healthcare Administration Route: Oral, Intravenous, Inhalation, Topical Distribution Channel: Online Pharmacies, Retail Pharmacies, Hospital Pharmacies, Direct Sales |
| Companies Covered | Gilead Sciences, Inc., Glenmark Pharmaceuticals, Bristol-Myers Squibb Company, Astellas Pharma Inc., Abbott Laboratories, Pfizer Inc, Novartis AG, Sigmapharm Laboratories LLC, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryptococcosis Market Emerging Trajectories
Antifungal development pipelines are pivoting toward host-directed immunomodulatory adjuncts and novel mechanism small molecules, diverging from decades of azole and polyene dominance in cryptococcal therapy protocols.
Liposomal amphotericin B is supplanting conventional deoxycholate formulations in first-line induction protocols at academic medical centers across the United States and Western Europe. Hospital pharmacy and therapeutics committees now mandate liposomal variants for patients with baseline renal impairment or anticipated prolonged therapy courses. This substitution pattern is compressing residual demand for conventional formulations into resource-constrained settings where cost sensitivity overrides toxicity concerns.
EMA's priority medicines scheme and FDA's tropical disease priority review vouchers are restructuring incentive architectures for cryptococcal indication development. These mechanisms reduce regulatory review timelines and enhance commercial exclusivity value, redirecting mid-cap pharmaceutical investment toward neglected tropical disease portfolios. Developers with existing HIV therapeutic footprints leverage cross-indication clinical infrastructure to accelerate cryptococcal candidate enrollment.
Consolidated purchasing by national HIV programs is displacing fragmented hospital-level procurement across high-burden African markets. South Africa's centralised chronic medicines dispensing program and Brazil's unified health system are negotiating multi-year amphotericin B and fluconazole supply agreements directly with manufacturers. This channel compression eliminates wholesale intermediary margins while binding volume commitments to quality certification and local packaging requirements.
Cryptococcosis Market Segmentation
Therapeutic modality and care setting segmentation determines procurement patterns across the cryptococcosis market. Each dimension carries distinct regulatory, pricing, and supply chain implications that reshape competitive positioning.
Product Type:
Domestic manufacturing concentration for polyenes clusters in Asian API hubs, while azole production spreads across European and North American formulation sites. Export-led supply chains dominate liposomal amphotericin B, whereas fluconazole sources from regional generic networks.
- Amphotericin B:Polyene macrolide derived from Streptomyces nodosus with fungicidal action against Cryptococcus biofilms. Hospital procurement in South Africa and Brazil concentrates on liposomal formulations to manage nephrotoxicity in HIV-coinfected patients. Conventional deoxycholate variants retain residual demand in cost-constrained Indian public health programs.
- Fluconazole:Triazole antifungal with excellent CNS penetration for consolidation and maintenance therapy. Outpatient dispensing through Brazilian SUS pharmacies and South African chronic medicine programs sustains volume leadership. Resistance surveillance gaps in sub-Saharan African laboratories complicate empiric selection protocols.
- Voriconazole:Second-generation triazole reserved for refractory or azole-resistant infections requiring therapeutic drug monitoring.
- Itraconazole:Broad-spectrum azole with variable oral bioavailability, positioned for step-down therapy in resource-limited settings.
Fluconazole holds the largest share; momentum sits with liposomal amphotericin B.
End User:
Cost tier stratification separates acute inpatient stabilization from chronic outpatient management, with research channels commanding premium pricing for clinical trial materials.
- Hospitals:Academic medical centers in the United States and Western Europe mandate liposomal amphotericin B for induction therapy through pharmacy and therapeutics committee protocols. Bundled HIV-antifungal purchasing agreements in South African public hospitals compress intermediary margins while binding manufacturers to local packaging requirements.
- Clinics:Primary care facilities in Ugandan and Malawian districts deploy lateral flow cryptococcal antigen tests for same-day treatment initiation. Point-of-care diagnostic expansion enables fluconazole maintenance dispensing without centralized laboratory confirmation.
- Home Healthcare:Oral azole continuation therapy for immunocompetent patients with isolated pulmonary disease.
- Research Laboratories:Reference centers conducting antifungal susceptibility testing and resistance surveillance for national health programs.
Hospitals absorb the dominant procurement volume; clinics are expanding most quickly through decentralized diagnostic integration.
Administration Route:
Volume concentration in intravenous induction reflects hospital admission requirements for severe meningoencephalitis, while oral routes capture extended maintenance phases.
- Intravenous:Essential for initial fungal burden reduction in cryptococcal meningitis with impaired consciousness or elevated intracranial pressure. Liposomal formulation stability demands cold chain infrastructure that strains rural Indian and Southeast Asian distribution corridors. Hospital pharmacy committees in the United States now require renal function screening before conventional deoxycholate authorization.
- Oral:Fluconazole tablets and suspensions enable outpatient consolidation after inpatient stabilization. Brazilian unified health system negotiates multi-year supply agreements directly with manufacturers, eliminating wholesale intermediaries.
- Inhalation:Investigational delivery for isolated pulmonary cryptococcosis in immunocompetent hosts.
- Topical:Limited utility for cutaneous manifestations in disseminated disease.
Intravenous routes command the highest per-patient revenue; oral administration shows the steepest expansion trajectory through community-based care models.
Distribution Channel:
Customer type fragmentation separates institutional procurement from retail dispensing, with direct sales capturing national program tenders.
- Hospital Pharmacies:Centralized purchasing by South Africa's chronic medicines dispensing program and Brazil's unified health system binds volume commitments to WHO prequalification status. Formulary consolidation around liposomal amphotericin B compresses residual demand for conventional formulations into secondary procurement tiers.
- Direct Sales:Manufacturer negotiations with national HIV programs displace fragmented hospital-level procurement across high-burden African markets. Multi-year agreements specify quality certification, local packaging, and cold chain compliance requirements.
- Retail Pharmacies:Private sector fluconazole dispensing for insured outpatients in Brazilian urban centers.
- Online Pharmacies:Emerging channel for maintenance therapy refills in United States specialty pharmacy networks.
Hospital pharmacies retain the dominant procurement share; direct sales channels are gaining share fastest through national program consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States and Western Europe sits at a structural premium to procurement economics in South Africa and Brazil, where national HIV programs negotiate volume-based supply agreements that compress manufacturer margins.
United States
Academic medical centers in Boston and New York mandate liposomal amphotericin B through pharmacy and therapeutics committee protocols. FDA orphan drug incentives accelerate clinical trial investment for novel cryptococcal meningitis therapeutics. Hospital formulary consolidation in the Southeast and Midwest compresses residual demand for conventional deoxycholate formulations into secondary procurement tiers.
Brazil
Brazil's unified health system negotiates multi-year fluconazole and amphotericin B supply agreements directly with manufacturers. ANVISA quality certification requirements bind foreign suppliers to local packaging and cold chain compliance standards. São Paulo and Rio de Janeiro public hospitals anchor bundled HIV-antifungal purchasing that eliminates wholesale intermediary margins.
South Africa
The national health insurance cost-containment objectives drive high-dose liposomal amphotericin B protocols that reduce hospitalization duration. South Africa's centralised chronic medicines dispensing program consolidates procurement across Gauteng and KwaZulu-Natal provinces. Cape Town academic medical centers pilot point-of-care cryptococcal antigen testing for same-day treatment initiation.
India
CDSCO regulatory pathways shape generic fluconazole manufacturing scale across Maharashtra and Gujarat pharmaceutical clusters. Cost-constrained public health programs in rural Bihar and Uttar Pradesh retain conventional amphotericin B deoxycholate demand despite nephrotoxicity profiles. Mumbai and Hyderabad formulation sites supply export-led liposomal encapsulation technology to endemic African markets.
Uganda
Lateral flow cryptococcal antigen tests enable decentralized diagnostic capacity in Kampala and rural district health centers. WHO Essential Medicines Listing stabilizes donor-funded procurement visibility for amphotericin B and fluconazole. Cold chain infrastructure deficits in northern treatment corridors strain liposomal formulation distribution to peripheral clinics.
Cryptococcosis Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with multinational developers commanding premium positioning in liposomal formulations while regional formulators capture volume in generic azole maintenance therapy. The market exhibits consolidated structure at the innovation tier and fragmented competition at the commodity end. Three archetypes dominate: HIV therapeutic footprint extenders, hospital channel contractors, and polyene manufacturing scale operators. Competitive moves center on cross-protocol prescribing integration and national program tender consolidation.
Among multinational developers, Pfizer Inc, Gilead Sciences, Inc., and Merck & Co., Inc. exemplify distinct strategic positioning archetypes. Pfizer occupies the manufacturing scale vector through decades of antifungal supply chain presence across endemic regions. Gilead sits within the HIV therapeutic integration tier, leveraging antiretroviral infrastructure for cross-selling into cryptococcal prophylaxis protocols. Merck represents the hospital channel contracting archetype, securing preferred formulary status in large academic medical centers through operational strength in institutional sales.
| Leading Market Players |
|---|
| Gilead Sciences, Inc. |
| Glenmark Pharmaceuticals |
| Bristol-Myers Squibb Company |
| Astellas Pharma Inc. |
| Abbott Laboratories |
| Pfizer Inc |
| Novartis AG |
| Sigmapharm Laboratories LLC |
| Merck & Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Polyene API fermentation capacity utilization in select Asian manufacturing hubs determines fungicidal supply availability and sets price floors for liposomal encapsulation formulations. Scale concentration among fermentation specialists compresses margin flexibility for downstream formulators while elevating procurement leverage for consolidated hospital buyers.
Pricing Analysis
The customization-premium spread between liposomal amphotericin B and conventional deoxycholate formulations spans therapeutic safety profiles rather than clinical efficacy. Three-tier pricing structure across premium liposomal, standard deoxycholate, and economy generic fluconazole levels reflects nephrotoxicity mitigation value. Price differentiation drivers include WHO prequalification status and cold chain compliance certification. Pricing pressure stems from national HIV program tender consolidation in South Africa and Brazil. Public hospital networks exhibit highest price sensitivity; academic medical centers in the United States demonstrate lowest sensitivity due to formulary protocol rigidity.
Supply Chain Analysis
Strategic stockpile preferences dominate liposomal formulation procurement given stability requirements, while just-in-time inventory management suffices for oral azole maintenance therapy. Active pharmaceutical ingredient production concentrates in India, China, and select European fermentation sites. Raw material dependencies include Streptomyces nodosus culture media, phospholipid encapsulation agents, and sterile filtration membranes. Single-source vulnerability persists in liposomal encapsulation technology licensing. Distribution runs through hospital pharmacy committees and national program tender channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryptococcosis market exhibits cyclical recovery characteristics tied to HIV therapeutic access expansion in high-burden African and Southeast Asian markets. Antiretroviral coverage scale-up drives incident case detection and corresponding antifungal demand.
For Market Incumbents: Fortify formulary positioning through therapeutic drug monitoring service bundling and cold chain logistics certification. Consolidate manufacturing scale in liposomal encapsulation to preempt generic substitution threats from regional Indian formulators. Prioritize backward integration into phospholipid supply to secure margin control against input cost volatility. For New Entrants and Emerging Players: Differentiate on point-of-care diagnostic integration for decentralized treatment initiation in Ugandan and Malawian primary care networks. Target clinic channel expansion as the most penetrable segment given hospital formulary consolidation. Pursue WHO prequalification pathway as the essential go-to-market credential for donor-funded procurement access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors host-directed immunomodulatory adjunct developers over established polyene manufacturers. Long-term viability rests on pipeline diversification beyond azole-polyene dominance. Acquisition target archetype includes point-of-care diagnostic platforms with cryptococcal antigen detection capability. Watch azole resistance surveillance data from sub-Saharan African reference laboratories as the critical inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA orphan drug designation accelerates novel antifungal candidate enrollment timelines. |
| Regulatory Approval Pathway | EMA priority medicines scheme shortens review periods for azole-refractory infection therapies. |
| Manufacturing Scale-Up | Liposomal encapsulation capacity expansion addresses cold chain distribution deficits in rural corridors. |
| Licensing Agreement | Cross-protocol HIV-antifungal bundling secures preferred formulary status in South African public hospitals. |
| Pipeline Diversification | Host-directed immunomodulatory adjuncts reduce dependence on decades-old polyene mechanisms. |
Methodological Framework
Initial hypotheses were tested against primary input from infectious disease pharmacists, hospital formulary directors, national HIV program procurement managers, and antifungal manufacturing executives and refined through secondary validation. Sources included FDA orphan drug designation filings, WHO Essential Medicines List revision records, ClinicalTrials.gov protocol registries, and national tender documentation from South Africa and Brazil. Bottom-up patient volume estimates and top-down pharmaceutical expenditure data were triangulated to establish market sizing.
Variance decomposition across therapeutic modality, care setting, and regional regulatory clusters structured the analytical framework. Segmentation dimensions modeled include product type, end user, administration route, and distribution channel. CAGRs were derived from incidence trend extrapolation and treatment protocol evolution assumptions. Forecast inputs incorporated HIV therapeutic access expansion trajectories and azole resistance surveillance patterns.
The analysis sits within stated boundaries; outcomes outside sustained donor funding commitments and stable antiretroviral coverage expansion would require recalibration. Forecasts reflect documented assumptions regarding treatment guideline adherence and procurement consolidation timelines. Revision becomes warranted when fluconazole resistance prevalence crosses clinical protocol adjustment thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cryoglobulinemia Treatment Market
Specialty Medicine
Systemic Lupus Erythematosus (SLE) Market
Specialty Medicine
Gaucher and Pompe Diseases Enzyme Replacement Therapy (ERT) Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Subdural Haematoma Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Adrenogenital Syndrome Treatment Market
Specialty Medicine
Endometriosis Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Ulcerative Colitis Therapeutics Market
Specialty Medicine
Intestine (Small) Cancer Therapeutics Market
Specialty Medicine
Facial Paralysis Market
Specialty Medicine
Global Psoriatic Arthritis Therapeutics Market