
 Peripheral Neuropathy Market | 2026-2036
Peripheral Neuropathy Market Size, Share, and Industry Trends Forecast 2026-2036
Peripheral Neuropathy Market Outlook
Neuromodulation device miniaturization is reshaping how peripheral neuropathy therapies reach patients outside institutional settings. Pfizer Inc leverages its established pain franchise to sustain formulary access across hospital networks. Eli Lilly and Company anchors its position through R&D intensity in biologic pain pathways. Novartis AG competes on manufacturing scale for injectable neuroactive compounds.
Peripheral neuropathy encompasses damage to peripheral nerves outside the brain and spinal cord, typically presenting as distal symmetric polyneuropathy with sensory loss, pain, or autonomic dysfunction measurable through nerve conduction velocity thresholds below 40 m/s; its primary purpose is to restore functional nerve signaling and reduce morbidity from chronic pain or mobility impairment. Medications occupy the largest value pool due to chronic prescribing patterns, while neuromodulation devices represent the fastest-expanding segment as rechargeable implantable systems gain reimbursement traction. Home healthcare channels are capturing margin from institutional shifts, though hospitals retain the highest acuity cases.
The FDA regulates neuromodulation devices through premarket approval pathways with clinical evidence requirements, while the EMA's MDR framework imposes stricter post-market surveillance on implantable pain devices in Europe. HIPAA governs patient data flows from connected home-use neuromodulation systems in the United States. Stakeholders must monitor how CMS reimbursement decisions for at-home electrical stimulation devices reshape channel economics and investment priorities.
Market Dynamics
The peripheral neuropathy market pivots on CMS reimbursement decisions for at-home electrical stimulation devices, which are compressing hospital-centric delivery models into distributed care networks and rewiring channel economics toward home healthcare providers.
Growth Catalysts
- FDA Accelerated Approval:The FDA's breakthrough therapy designation for novel pain modalities compresses clinical trial timelines and expedites market entry for neuromodulation innovators targeting refractory diabetic neuropathy.
- German Pain Clinic Integration:Specialized outpatient centers across Bavaria and Baden-Württemberg combine pharmacological protocols with spinal cord stimulation, creating template care pathways exportable to other European markets.
- Rechargeable Implantable Systems:Lithium-ion battery miniaturization extends device longevity beyond 10 years, reducing replacement surgery burden and expanding candidacy to elderly comorbid populations previously excluded.
Market Restraints
- Neuroactive Compound Supply Concentration:Injectable biologic manufacturing for nerve growth factors concentrates among three European contract manufacturers, creating single-source vulnerability for pipeline candidates.
- EMA MDR Post-Market Surveillance:Europe's Medical Device Regulation imposes annual safety reporting and clinical follow-up mandates that inflate regulatory compliance costs for implantable pain devices by 25-40% versus pre-2021 requirements.
- Generic Pregabalin Substitution:Patent expiration of Lyrica has triggered price erosion exceeding 90% in oral neuropathic pain medications, collapsing revenue pools for small-molecule innovators.
Strategic Opportunities
- Underpenetrated Rural India:Diabetic neuropathy prevalence exceeds 20% in Maharashtra and Tamil Nadu agricultural belts, yet neuromodulation device penetration sits below 2% due to reimbursement gaps addressable through CDSCO fast-track pathways.
- Connected Home-Use Systems:Bluetooth-enabled transcutaneous electrical nerve stimulators with HIPAA-compliant data streams create recurring revenue through remote monitoring subscriptions and algorithm-driven therapy adjustment.
- Biologic-Neuromodulation Convergence:Combination protocols pairing anti-nerve growth factor antibodies with dorsal root ganglion stimulation target mixed pain phenotypes unresponsive to monotherapy.
Industry Challenges
- Interventional Pain Specialist Shortage:Fellowship-trained physicians capable of implanting spinal cord stimulators number fewer than 3,000 across all US metropolitan statistical areas, creating procedural bottleneck.
- Legacy EMR Integration Friction:Home-use neuromodulation data streams require API development to interface with Epic and Cerner systems, delaying hospital system adoption of remote patient monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peripheral Neuropathy Market |
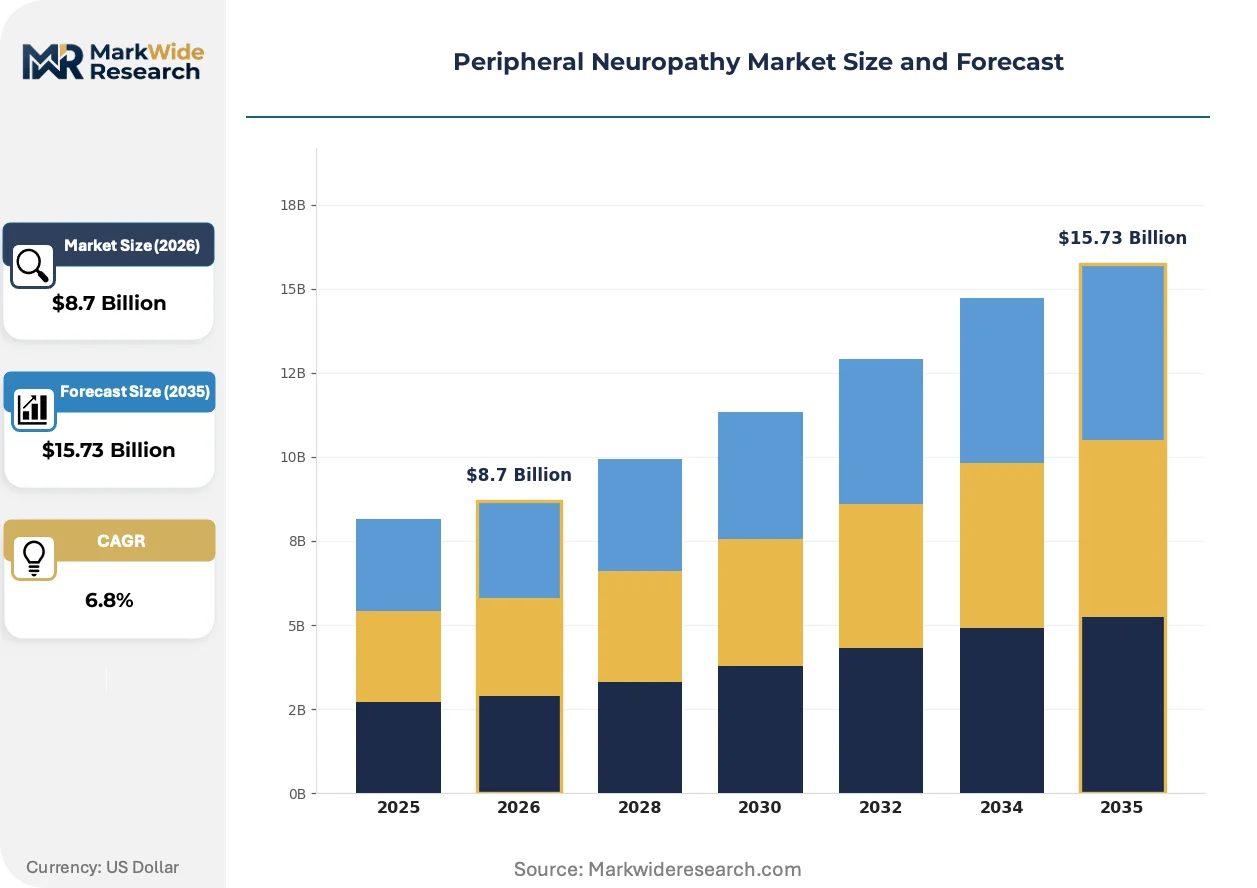
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physical Therapy, Nutritional Supplements, Neuromodulation Devices Technology: Pharmacological Treatment, Electrical Stimulation, Regenerative Medicine, Complementary Therapies End User: Hospitals, Rehabilitation Centers, Home Healthcare, Specialty Clinics Application: Diabetic Neuropathy, Chemotherapy-Induced Neuropathy, Post-Surgery Pain, Idiopathic Neuropathy |
| Companies Covered | Pfizer Inc, Johnson & Johnson, Eli Lilly and Company, Novartis AG, AstraZeneca PLC, Teva Pharmaceutical Industries Ltd, Sanofi S.A., Bristol-Myers Squibb Company, Amgen Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peripheral Neuropathy Market Strategic Shifts
Neuromodulation hardware is shedding institutional tethering through battery chemistry advances and embedded connectivity, while regulatory frameworks on both sides of the Atlantic recalibrate evidence requirements for software-enabled therapeutic delivery.
Closed-loop adaptive stimulation algorithms process real-time nerve feedback to adjust electrical pulse parameters without clinician intervention. Pain management centers at Cleveland Clinic and Mayo Clinic are piloting these systems for complex regional pain syndrome patients. This capability is digitizing the titration process that previously required repeated office visits, compressing the optimization timeline from months to weeks.
Europe's MDR recast directive mandates clinical evaluation reports with post-market clinical follow-up data for all Class III implantable devices, including spinal cord stimulators. Manufacturers must now maintain periodic safety update reports and trend analyses of serious incidents. The German notified body landscape has consolidated from over 80 to fewer than 25 active designations, concentrating certification capacity and extending timeline uncertainty for pipeline products.
Hospital procurement committees are unbundling device acquisition from implantation service contracts, forcing neuromodulation vendors to compete on hardware margin alone while ceding procedure revenue to physician practice groups. This disintermediation is most advanced in Texas and Florida health systems, where ambulatory surgery center joint ventures now capture 60% of spinal cord stimulator implants previously performed in inpatient settings.
Peripheral Neuropathy Market Segmentation
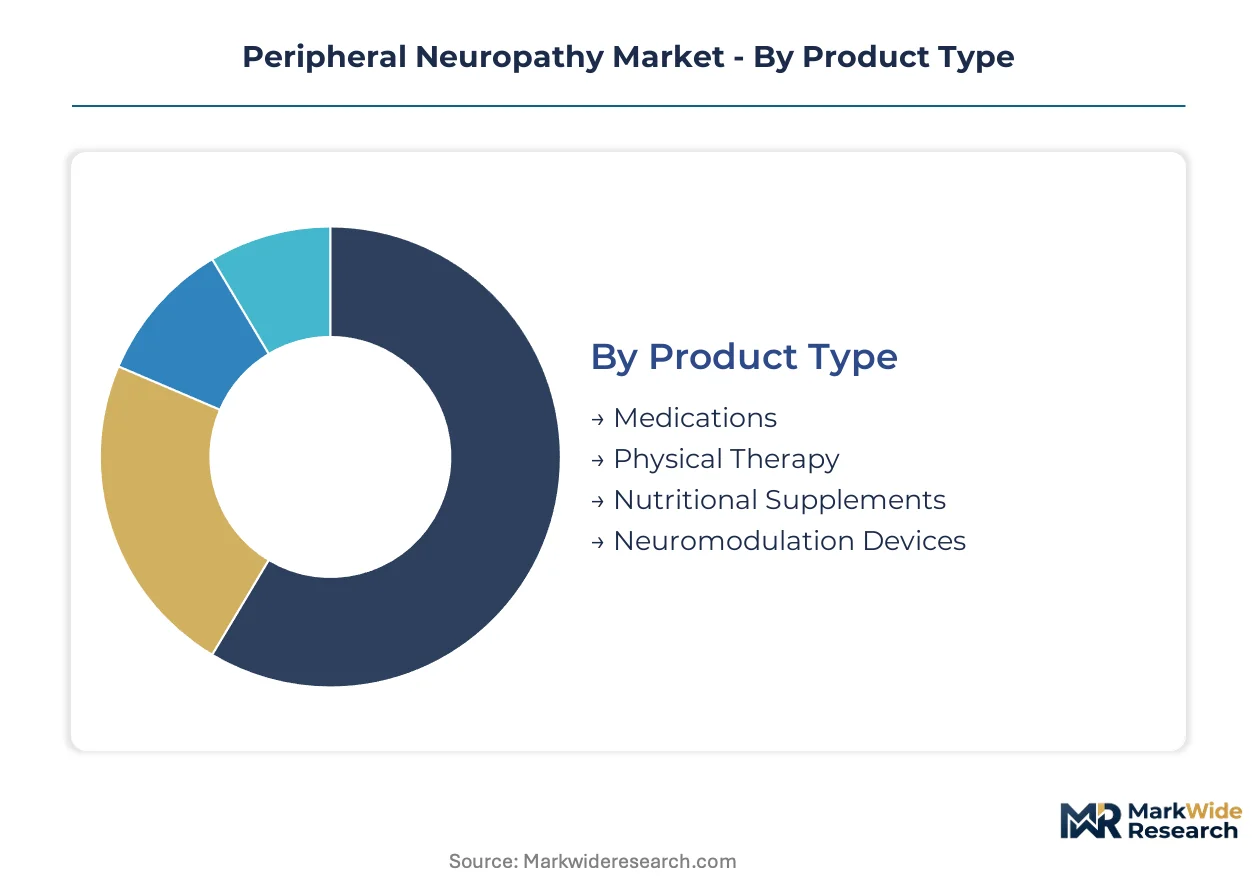
Segmentation in peripheral neuropathy reveals divergent margin profiles across delivery modalities. Chronic medication prescribing generates recurring revenue streams with minimal service overhead, while implantable neuromodulation systems demand intensive post-implant programming and battery management protocols that reshape lifetime customer value calculations.
Product Type:
After-sales service intensity varies dramatically across product categories, with implantable systems requiring decade-long monitoring relationships versus single-transaction supplement sales.
- Medications:Oral and injectable pharmaceutical formulations including anticonvulsants, antidepressants, and topical agents dominate prescription volume through chronic dispensing patterns. Demand concentrates in Germany's integrated pain clinic networks where pharmacological protocols anchor multimodal treatment bundles, though generic pregabalin substitution has collapsed pricing power for small-molecule innovators.
- Neuromodulation Devices:Implantable spinal cord stimulators and peripheral nerve field stimulators with rechargeable lithium-ion architectures deliver electrical pulses to modulate pain signaling pathways. Cleveland Clinic and Mayo Clinic pain centers are piloting closed-loop adaptive systems that process real-time nerve feedback, compressing titration timelines from months to weeks and creating subscription-like revenue through remote monitoring services.
- Physical Therapy:Supervised exercise protocols and manual therapy interventions address mobility impairment and proprioceptive deficits through structured rehabilitation programs.
- Nutritional Supplements:Over-the-counter B-vitamin complexes and alpha-lipoic acid formulations target metabolic nerve support with minimal clinical supervision requirements.
Medications hold the largest share; momentum sits with neuromodulation devices.
Technology:
Cost tier stratification separates high-investment biologic manufacturing from commoditized electrical stimulation hardware with shrinking margins.
- Pharmacological Treatment:Systemic drug delivery through oral, intravenous, and transdermal routes modulates neurotransmitter activity and ion channel function. Hospital formularies in Texas and Florida health systems increasingly prioritize generic substitution, forcing branded manufacturers to defend access through outcome-based contracting.
- Electrical Stimulation:Transcutaneous and implantable devices deliver targeted current to interrupt nociceptive signaling or promote nerve regeneration. CMS reimbursement decisions for at-home electrical stimulation devices are compressing hospital-centric delivery models into distributed care networks across US metropolitan statistical areas.
- Regenerative Medicine:Cell-based therapies and nerve growth factor biologics target structural nerve repair through injectable formulations.
- Complementary Therapies:Acupuncture, biofeedback, and mindfulness-based pain management protocols serve as adjunctive interventions.
Pharmacological treatment commands the greatest revenue concentration; regenerative medicine is climbing the fastest as pipeline candidates advance through EMA MDR pathways.
End User:
Customer type determines procurement authority and reimbursement pathway complexity, with hospital committees negotiating enterprise contracts versus individual patient purchases.
- Hospitals:Inpatient and outpatient departments manage highest-acuity cases requiring multimodal intervention and surgical implantation capabilities. Procurement committees at major US health systems are unbundling device acquisition from implantation service contracts, forcing vendors to compete on hardware margin alone.
- Home Healthcare:Distributed delivery channels capture margin from institutional shifts as rechargeable implantable systems gain reimbursement traction for remote management. HIPAA-compliant data streams from Bluetooth-enabled transcutaneous stimulators create recurring revenue through algorithm-driven therapy adjustment subscriptions.
- Rehabilitation Centers:Structured therapy environments address functional restoration and adaptive equipment training.
- Specialty Clinics:Focused pain management and neurology practices provide targeted intervention for refractory cases.
Hospitals retain the highest acuity concentration; home healthcare is gaining share fastest as CMS expands at-device reimbursement.
Application:
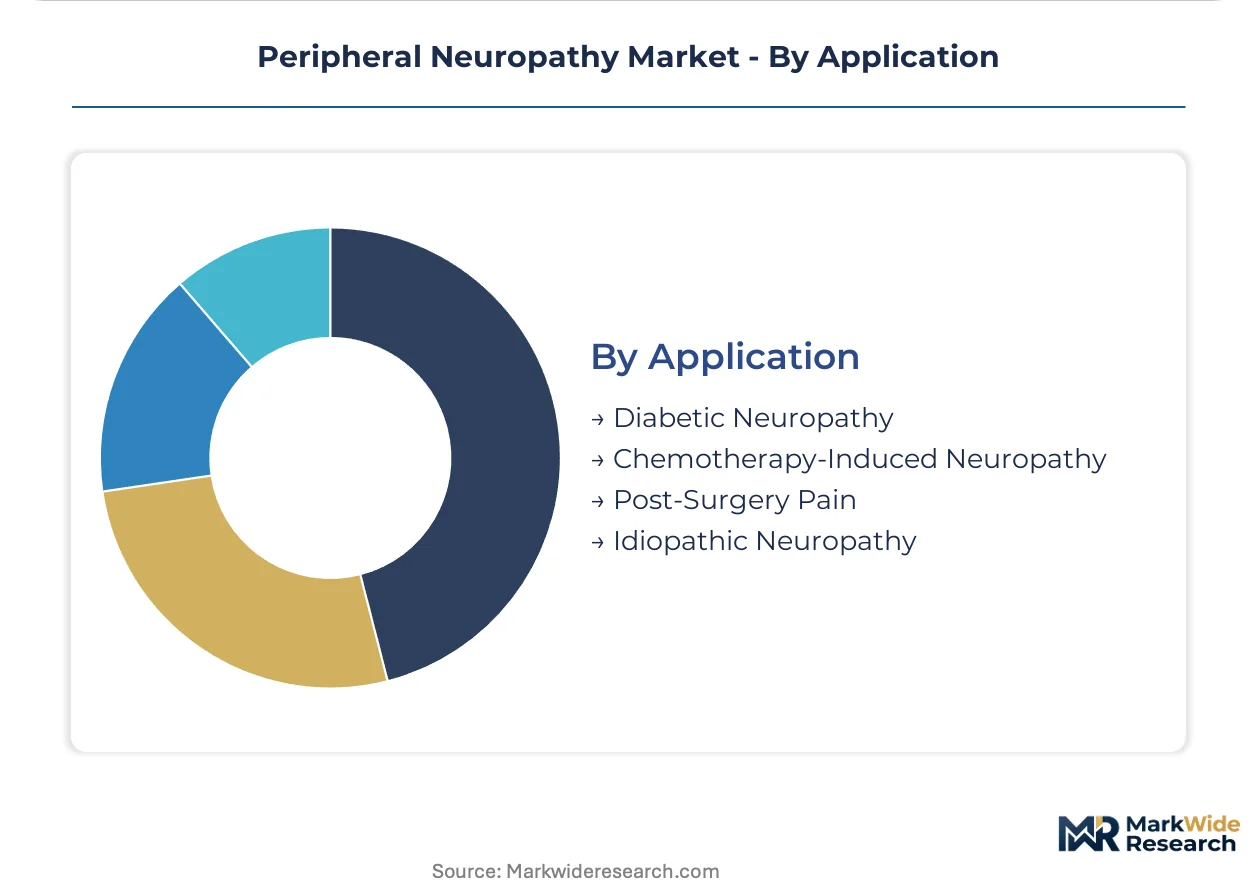
Volume distribution tracks underlying disease prevalence, with diabetic populations driving baseline demand while chemotherapy-induced cases create acute treatment windows.
- Diabetic Neuropathy:Distal symmetric polyneuropathy affecting sensory, motor, and autonomic functions in patients with prolonged hyperglycemia represents the largest addressable population. Maharashtra and Tamil Nadu agricultural belts in India show prevalence exceeding 20% yet neuromodulation penetration sits below 2%, creating expansion opportunity through CDSCO fast-track pathways.
- Chemotherapy-Induced Neuropathy:Platinum-agent and taxane-related neurotoxicity produces dose-limiting sensory deficits in oncology patients. FDA breakthrough therapy designation for novel pain modalities is compressing clinical trial timelines for agents targeting this refractory population.
- Post-Surgery Pain:Iatrogenic nerve injury and inflammatory responses following orthopedic and thoracic procedures.
- Idiopathic Neuropathy:Cryptogenic cases without identifiable underlying etiology requiring diagnostic workup and empirical treatment.
Diabetic neuropathy holds the largest share; chemotherapy-induced neuropathy shows the steepest expansion trajectory as oncology volumes rise and awareness of dose-limiting toxicities increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in peripheral neuropathy therapies tilt toward import dependence in emerging markets while established manufacturing hubs in Germany and the United States supply high-value neuromodulation hardware to hospital systems worldwide.
United States
Cleveland Clinic and Mayo Clinic pain centers pilot closed-loop adaptive stimulation systems for complex regional pain syndrome patients. FDA breakthrough therapy designation compresses clinical trial timelines for novel pain modalities targeting refractory diabetic neuropathy. Texas and Florida health systems lead procurement committee unbundling of device acquisition from implantation service contracts.
Germany
Specialized outpatient centers across Bavaria and Baden-Württemberg combine pharmacological protocols with spinal cord stimulation, creating template care pathways exportable to other European markets. EMA MDR post-market surveillance mandates inflate regulatory compliance costs for implantable pain devices by 25-40% versus pre-2021 requirements. The German notified body landscape has consolidated from over 80 to fewer than 25 active designations.
India
Diabetic neuropathy prevalence exceeds 20% in Maharashtra and Tamil Nadu agricultural belts, yet neuromodulation device penetration sits below 2%. CDSCO fast-track pathways address reimbursement gaps for hardware importation. Hospital procurement in Delhi-NCR and Bengaluru increasingly sources generic pregabalin formulations from domestic API manufacturers.
Japan
PMDA regulatory pathways for combination biologic-neuromodulation protocols are advancing through pilot review frameworks. Aging demographics in Kansai and Chubu regions drive demand for rechargeable implantable systems with decade-long longevity. METI industrial policy supports lithium-ion battery miniaturization for medical device applications.
United Kingdom
NHS England specialized commissioning frameworks restrict spinal cord stimulator implants to designated regional centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory divergence from EMA MDR creates timeline uncertainty for pipeline products. Private pain clinics in Harley Street medical district capture self-pay neuromodulation cases outside NHS rationing.
Peripheral Neuropathy Market Competitive Environment
On the supply side, the industry is consolidating around pharmaceutical incumbents with established pain franchises and emerging neuromodulation hardware specialists with proprietary stimulation algorithms. Three archetypes dominate: large-cap diversified pharmas defending formulary access, mid-cap device innovators capturing ambulatory surgery center volume, and generic manufacturers eroding small-molecule pricing power. Competitive moves concentrate on M&A for biologic pain pathway assets and strategic partnerships for closed-loop adaptive stimulation technology.
Within the large-cap pharmaceutical tier, Pfizer Inc and Eli Lilly and Company exemplify divergent strategic positioning—Pfizer leveraging its established pain franchise for hospital network formulary access, Lilly anchoring through R&D intensity in biologic pain pathways. Novartis AG occupies a manufacturing-scale position for injectable neuroactive compounds among European contract production networks.
| Leading Market Players |
|---|
| Pfizer Inc |
| Johnson & Johnson |
| Eli Lilly and Company |
| Novartis AG |
| AstraZeneca PLC |
| Teva Pharmaceutical Industries Ltd |
| Sanofi S.A. |
| Bristol-Myers Squibb Company |
| Amgen Inc |
| Others |
Value Chain & Pricing Dynamics
Undercapacity at European contract manufacturing sites for injectable nerve growth factor biologics is forcing neuromodulation innovators toward in-house production investments while simultaneously compressing pricing power for outsourced formulations across hospital procurement networks.
Pricing Analysis
Hospital procurement committees anchor pricing negotiations through unbundled device acquisition contracts that separate hardware margin from implantation service revenue. Three-tier pricing structure across premium closed-loop systems, standard rechargeable implants, and economy non-rechargeable devices reflects battery longevity and algorithm sophistication tiers. Cost compression in oral medication tiers intensifies because generic pregabalin substitution exceeds 90% price erosion, while implantable hardware retains firmer pricing due to interventional pain specialist scarcity. Academic medical centers exhibit lowest price sensitivity for adaptive stimulation systems; ambulatory surgery centers demonstrate highest sensitivity to per-unit hardware costs.
Supply Chain Analysis
Three European contract manufacturers hold concentrated capacity for injectable neuroactive compound production, creating single-source vulnerability for pipeline biologics targeting diabetic neuropathy. Manufacturing feeds from German precision electronics for stimulation hardware, Swiss biologics fill-finish capabilities, and Indian API synthesis for generic pregabalin formulations. Lithium-ion cell supply hinges on Japanese and South Korean battery chemistry suppliers, exposing neuromodulation device production to logistics chokepoints through maritime shipping corridors. Distribution runs through hospital procurement committees for implantable systems and direct-to-patient channels for home-use transcutaneous devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from remote monitoring subscriptions and algorithm-driven therapy adjustments is expanding faster than hardware sales, transforming lifetime customer value calculations toward recurring revenue models.
For Market Incumbents: Pre-empt generic erosion in oral neuropathic pain medications by accelerating FDA submissions for biologic-neuromodulation combination protocols. Defend formulary access through outcome-based contracting with integrated delivery networks. Prioritize backward integration into lithium-ion battery cell production to secure supply continuity for rechargeable implantable systems.
For New Entrants and Emerging Players: Pursue Maharashtra and Tamil Nadu agricultural belts in India where diabetic neuropathy prevalence exceeds 20% yet neuromodulation penetration sits below 2%. Target CDSCO fast-track pathways to address reimbursement gaps before domestic manufacturing scale-up. Enter through distribution partnerships with established pain clinic networks rather than direct hospital procurement competition.
For Investors and Strategic Acquirers: Long-term, this sits as a chronic-disease management infrastructure play because durable implantable systems with decade-long battery life create patient lock-in through replacement surgery switching costs. Target mid-cap device innovators with proprietary closed-loop algorithms and established CMS reimbursement codes. Monitor CMS national coverage determinations for at-home electrical stimulation as inflection signal for home healthcare channel expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Designation | Accelerated review compresses clinical timelines for refractory diabetic neuropathy candidates. |
| CE Marking Pathway | EMA MDR post-market surveillance mandates reshape evidence requirements for European market entry. |
| Hospital System Partnership | Integrated delivery network contracts secure formulary access across Cleveland Clinic and Mayo Clinic pain centers. |
| Software Companion Development | Bluetooth-enabled data streams with HIPAA compliance create recurring remote monitoring revenue. |
| Reimbursement Strategy | CMS national coverage determination for at-home electrical stimulation reshapes channel economics toward home healthcare. |
Study Parameters
A spread of perspectives from pain management physicians, hospital procurement managers, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying demand modeling. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and CMS Medicare reimbursement databases. Bottom-up patient population estimates triangulated against top-down pharmaceutical and device revenue benchmarks.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user channel, and underlying etiology. CAGRs derived from historical growth rate analysis adjusted for regulatory approval timelines and reimbursement expansion trajectories. Forecast inputs incorporated nerve conduction velocity diagnostic thresholds and interventional pain specialist supply constraints.
Sensitivities concentrate around CMS reimbursement decisions for at-home electrical stimulation devices and EMA MDR notified body capacity consolidation. Forecasts reflect assumptions about regulatory pathway timelines and hospital procurement unbundling trends. Quarterly review of FDA breakthrough therapy designations and CMS national coverage determinations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Ulcerated Necrobiosis Lipoidica Management Market
Specialty Medicine
Global Plasma Therapeutics Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Cytomegalovirus Retinitis Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Acute Lymphocytic Leukemia Therapeutics Market
Specialty Medicine
Hepatitis C Treatment Market
Specialty Medicine
Epileptic Seizures Treatment Market
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
North America Cancer Therapy Market