
 Europe Nuclear Medicine Equipment Market | 2026-2036
Europe Nuclear Medicine Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Nuclear Medicine Equipment Market Analytics
Hospital procurement in Europe is pivoting from standalone gamma cameras toward integrated hybrid imaging platforms, concentrating buying power among large academic medical centers and consolidated diagnostic networks. Siemens Healthineers AG leverages its installed base of PET/MR systems across German university hospitals to sustain service contract renewals. GE Healthcare anchors its position through cyclotron and radiopharmacy partnerships that secure isotope supply chains for Nordic and Benelux customers. Koninklijke Philips N.V. differentiates via digital PET detector architectures that reduce scan times for high-throughput outpatient facilities in France and Spain.
Europe nuclear medicine equipment encompasses ionizing radiation detection systems, radiopharmaceutical dispensing infrastructure, and quantitative imaging software designed to map physiological function at the molecular level, with PET scanners achieving spatial resolution below 4 mm using lutetium-based scintillation crystals. SPECT systems still occupy the largest installed base across Southern and Eastern European hospitals where reimbursement favors lower-capital modalities, yet PET scanner demand is accelerating fastest in oncology applications as tracer production regionalizes around cyclotron hubs in Germany, France, and Belgium. Software solutions for dosimetry and image reconstruction represent the highest-margin segment, with vendors like Hermes Medical Solutions and DOSIsoft SA competing on regulatory-validated workflow integration.
The EU Medical Device Regulation (MDR) and EMA's radiopharmaceutical guidance are extending certification timelines and tightening quality control requirements for novel tracers, forcing manufacturers to front-load clinical evidence generation. France's ANSM and Germany's BfArM enforce divergent post-market surveillance protocols that fragment compliance costs across national subsidiaries. REACH and RoHS constraints on scintillation crystal materials are reshaping supplier qualification processes for detector manufacturers. Stakeholders must monitor how the EU Green Deal's medical isotope sustainability mandates and the F-Gas Regulation's helium-3 recovery requirements recalibrate supply chain economics for neutron detection components.
Market Dynamics
Hospital procurement across Europe is pivoting decisively toward integrated hybrid imaging platforms, concentrating buying power among large academic medical centers and consolidated diagnostic networks while the EU Medical Device Regulation extends certification timelines for novel molecular imaging systems.
Growth Catalysts
- EU Green Deal isotope mandates:Sustainability requirements for medical isotope production are accelerating investment in regional cyclotron hubs across Germany, France, and Belgium.
- Oncology staging protocols:Hybrid PET/CT systems are becoming standard for tumor characterization in French and German university hospital networks.
- Radiopharmaceutical dispensing automation:Dose calibrators and automated synthesis modules are reducing technician exposure while increasing throughput in high-volume nuclear medicine departments.
Market Restraints
- Lutetium crystal supply concentration:Detector-grade lutetium oxyorthosilicate production concentrates among three Asian suppliers, creating input cost volatility for SPECT and PET manufacturers.
- EMA radiopharmaceutical guidance friction:Novel tracer approval timelines have extended substantially, delaying commercialization of next-generation oncology and neurology agents.
- Helium-3 neutron detection scarcity:F-Gas Regulation recovery requirements are constraining supply for certain radiation monitoring applications.
Strategic Opportunities
- Eastern European imaging infrastructure:Poland, Hungary, and Romania present substantial white space for PET/CT deployment as EU structural funds modernize hospital capital equipment.
- Digital PET detector architectures:Silicon photomultiplier arrays are enabling faster scan protocols that expand outpatient clinic throughput.
- AI-enabled image reconstruction:Machine learning algorithms are reducing acquisition times while maintaining diagnostic accuracy, creating differentiation for high-volume facilities.
Industry Challenges
- Radiochemist workforce scarcity:Cyclotron operation and tracer synthesis require specialized training that European universities are not producing at replacement rates.
- MDR technical documentation burden:Class IIb and III device recertification is consuming substantial regulatory affairs resources across national subsidiaries.
- Legacy gamma camera integration:Standalone SPECT systems require costly workflow adaptation to connect with modern PACS and EMR infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Nuclear Medicine Equipment Market |
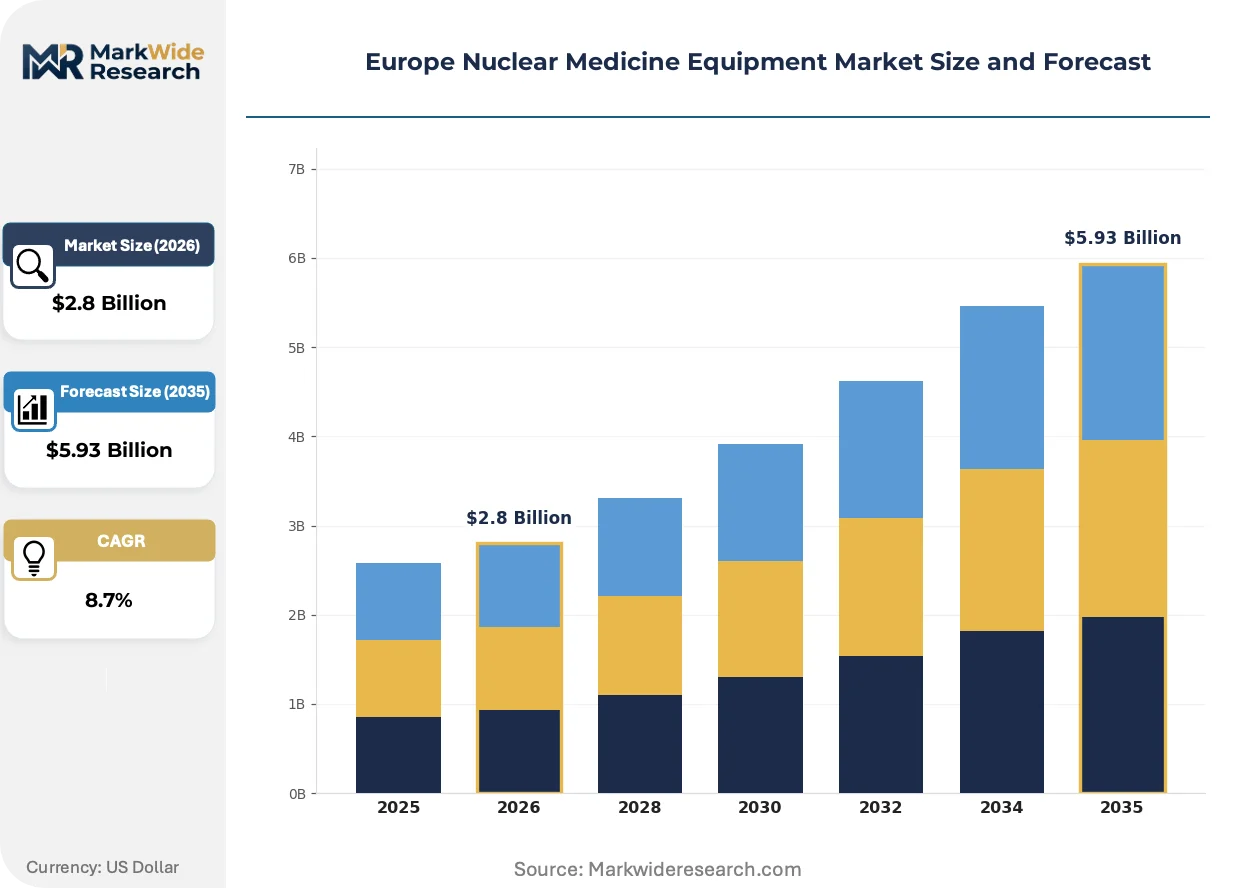
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gamma Cameras, PET Scanners, SPECT Systems, Radiopharmaceuticals End User: Hospitals, Diagnostic Imaging Centers, Research Labs, Outpatient Facilities Technology: Instrumentation, Software Solutions, Imaging Techniques, Quality Control Application: Oncology, Cardiology, Neurology, Thyroid Disorders |
| Companies Covered | GE Healthcare, Siemens Healthineers AG, Koninklijke Philips N.V., Canon Medical Systems Corporation, Hermes Medical Solutions, DOSIsoft SA, Mediso Ltd., Mirion Technologies, Inc., Segami Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Nuclear Medicine Equipment Market Evolving Landscape
Digital detector architectures and artificial intelligence are compressing scan durations while regulatory pressure on isotope supply chains is regionalizing production infrastructure across Western Europe.
Silicon photomultiplier-based PET detectors are consolidating market preference over traditional photomultiplier tube architectures. German and French outpatient imaging centers are adopting these systems to double daily patient throughput. The technology is consolidating competitive advantage around vendors with captive semiconductor supply arrangements.
EMA's tightened radiopharmaceutical quality guidance is extending good manufacturing practice requirements to hospital-based cyclotron facilities. Batch release documentation now demands extensive analytical validation that smaller nuclear medicine departments struggle to resource. Italian and Spanish hospital networks are responding by outsourcing tracer production to centralized regional pharmacies.
Service contract unbundling is fragmenting how European hospitals acquire molecular imaging capabilities. Large diagnostic networks in the Netherlands and Belgium are separating equipment financing from maintenance and software subscriptions. This pattern is most visible among private equity-backed outpatient chains seeking operational flexibility without capital intensity.
Europe Nuclear Medicine Equipment Market Segmentation
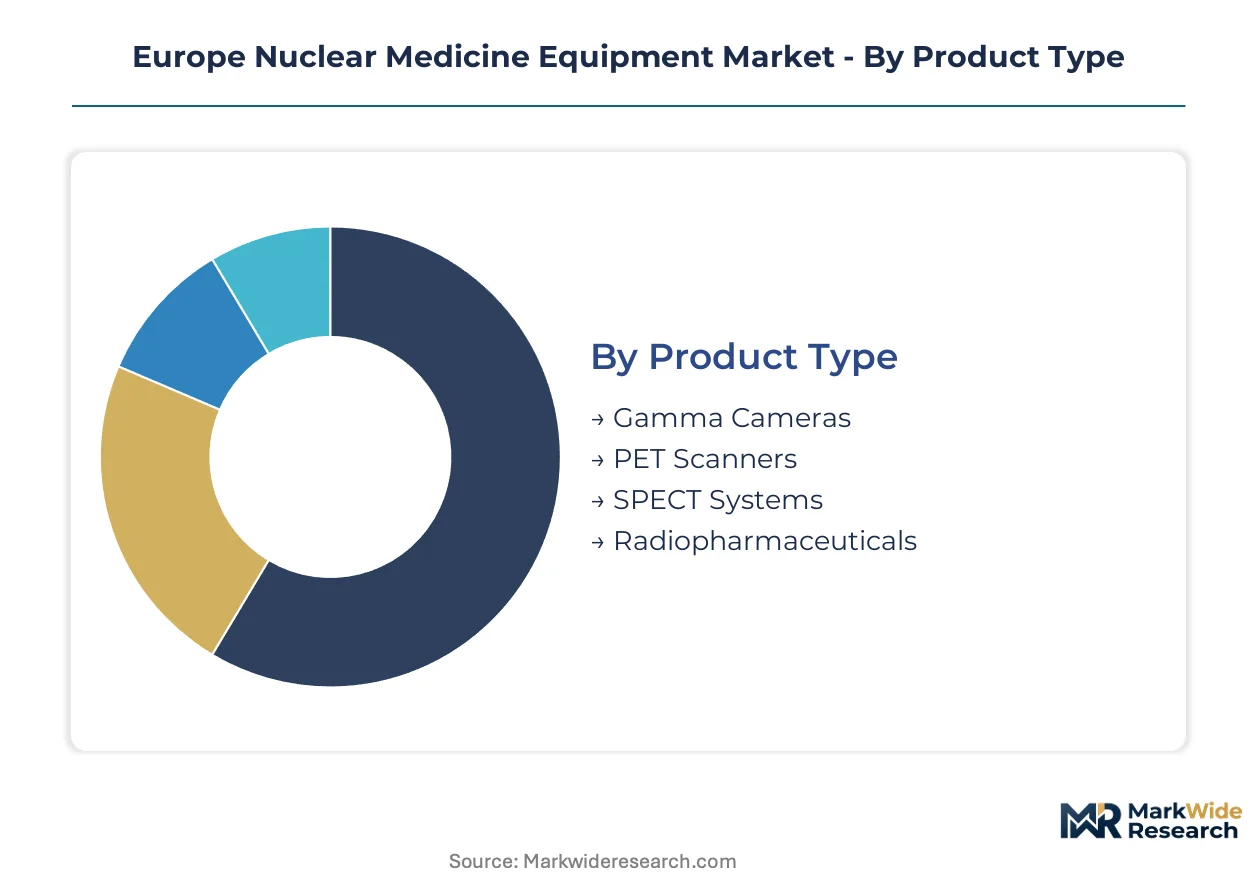
Equipment segmentation across Europe reveals how procurement priorities diverge between capital-intensive hybrid platforms and consumable radiopharmaceuticals, with technology choices directly constraining which clinical applications facilities can support. Understanding these segment boundaries clarifies why German university hospitals concentrate spending differently than French outpatient networks.
Product Type:
Standalone gamma cameras operate independently in budget-constrained settings, while PET and SPECT systems increasingly embed into hybrid CT-integrated workflows that demand synchronized infrastructure investment.
- Gamma Cameras:These single-detector systems capture gamma ray emissions using sodium iodide crystals for planar imaging. Southern and Eastern European hospitals in Italy, Spain, and Poland maintain substantial installed bases where reimbursement schedules favor lower capital expenditure over throughput efficiency.
- PET Scanners:Positron emission tomography systems detect coincident gamma rays from positron-electron annihilation using lutetium-based scintillation crystals achieving sub-4 mm spatial resolution. German and French oncology centers are prioritizing these for tumor staging protocols, though cyclotron proximity constrains deployment geography.
- SPECT Systems:Single photon emission computed tomography platforms rotate gamma cameras around patients to reconstruct 3D functional maps. These systems bridge diagnostic capability gaps in mid-tier European hospitals awaiting hybrid upgrade cycles.
- Radiopharmaceuticals:Tracer molecules labeled with technetium-99m, fluorine-18, or gallium-68 enable specific tissue targeting. Regional cyclotron hubs in Belgium and the Netherlands are consolidating production to serve multiple national markets under EMA quality guidance.
Gamma cameras lead volumes today; PET scanners are gaining share fastest.
End User:
Capital allocation patterns separate consolidated academic networks with dedicated nuclear medicine departments from distributed outpatient operators seeking shared-service arrangements.
- Hospitals:Comprehensive medical centers house integrated hybrid imaging suites, cyclotron facilities, and radiochemistry laboratories. University hospital networks across Germany, France, and Italy command procurement budgets that absorb MDR certification premiums and specialized workforce costs.
- Diagnostic Imaging Centers:Standalone facilities concentrate high-throughput outpatient scanning without inpatient care overhead. Benelux and Nordic markets host mature diagnostic center chains that unbundle equipment financing from service contracts.
- Research Labs:Academic and pharmaceutical research institutions operate preclinical imaging systems and tracer development pipelines. These facilities in Switzerland and the UK drive early-stage radiopharmaceutical innovation outside routine clinical reimbursement frameworks.
- Outpatient Facilities:Community-based clinics provide limited nuclear medicine services with portable or compact systems. Spanish and Portuguese outpatient networks are expanding PET/CT access as regional health authorities delegate diagnostic capacity.
Hospitals dominate capital expenditure; diagnostic imaging centers are expanding most quickly.
Technology:
Margin concentration shifts toward software and quality systems as hardware commoditization pressures detector manufacturers.
- Instrumentation:Detector assemblies, gantries, and patient handling systems constitute the physical imaging platform. Silicon photomultiplier arrays are displacing traditional photomultiplier tubes in German-manufactured digital PET systems.
- Software Solutions:Image reconstruction algorithms, dosimetry calculation tools, and PACS integration middleware command premium pricing. Regulatory-validated workflow software from Nordic vendors captures recurring revenue streams.
- Imaging Techniques:Protocol libraries and acquisition parameter sets differentiate system capabilities. Time-of-flight PET and digital SPECT techniques are compressing scan durations for high-volume French outpatient operators.
- Quality Control:Calibration phantoms, dose calibrators, and automated testing systems ensure regulatory compliance. EMA's tightened batch release documentation is elevating quality system importance across hospital-based cyclotron facilities.
Instrumentation anchors installed value; software solutions are climbing the fastest.
Application:
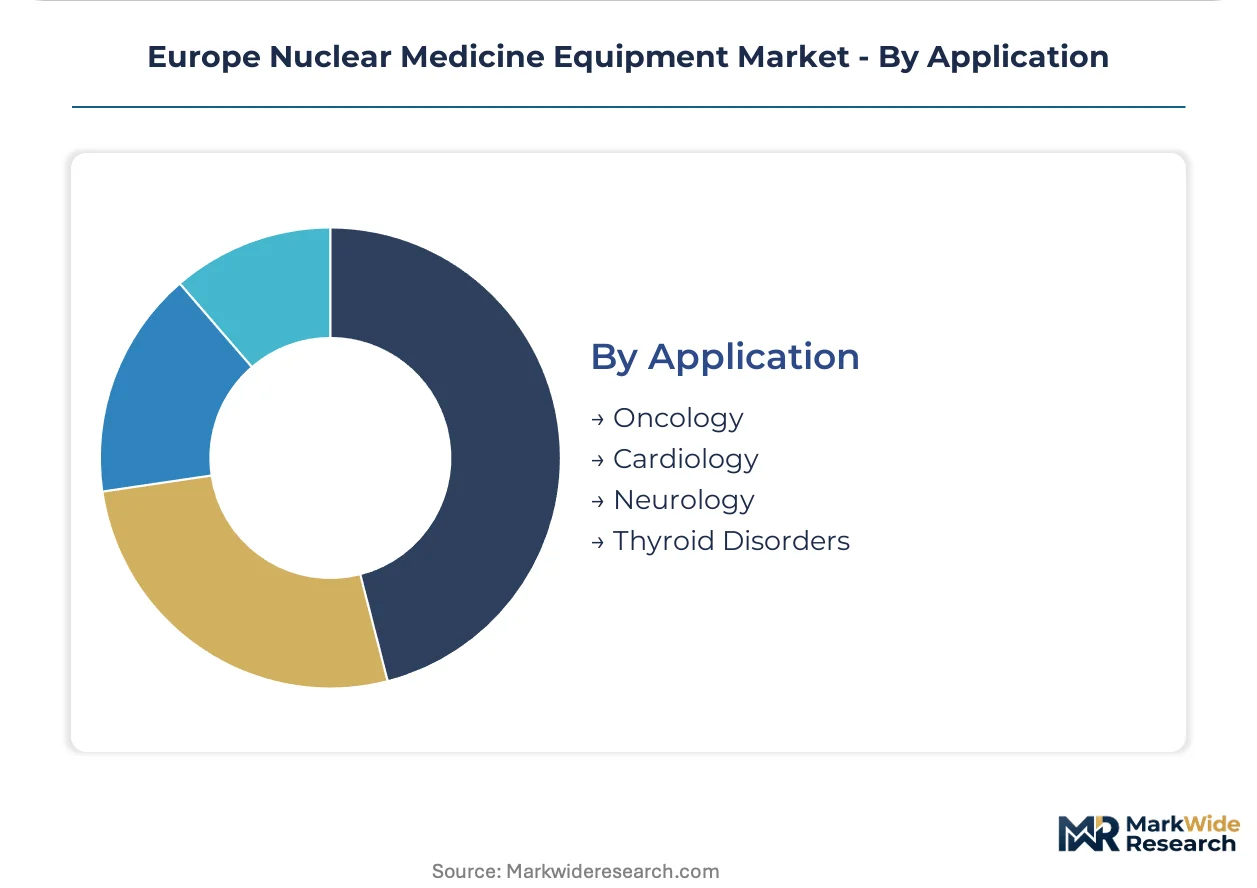
Clinical utility determines tracer selection and imaging protocol design, with oncology applications commanding the most sophisticated hybrid platform investment.
- Oncology:Tumor detection, staging, and treatment response monitoring using FDG-PET and PSMA-targeted agents. French and German cancer centers are standardizing PET/CT for lymphoma and prostate cancer pathways, driving hybrid system procurement.
- Cardiology:Myocardial perfusion imaging and viability assessment using SPECT with thallium-201 or technetium-99m tracers. Southern European cardiac centers maintain substantial SPECT utilization where reimbursement preserves standalone system economics.
- Neurology:Dementia differential diagnosis and epilepsy focus localization via amyloid and FDG brain PET. Specialized memory clinics in the Netherlands and Sweden are adopting tau-targeting tracers as EMA approvals expand.
- Thyroid Disorders:Hyperthyroidism treatment planning and thyroid cancer follow-up using iodine-131 imaging. These applications sustain gamma camera utilization in general hospitals across Eastern Europe where case volumes justify dedicated systems.
Oncology generates the steepest equipment revenue; neurology is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiochemist talent pools concentrate in German university cities and French pharmaceutical clusters, anchoring cyclotron operations that supply tracer-dependent imaging networks across Western Europe.
Germany
University hospital networks in Munich, Heidelberg, and Berlin drive hybrid PET/CT procurement for oncology staging protocols. BfArM enforces divergent post-market surveillance protocols that fragment compliance costs across national subsidiaries. The Baden-Württemberg and Bavaria regions host Siemens Healthineers' installed base of PET/MR systems sustaining service contract renewals.
France
ANSM radiopharmaceutical guidance extends good manufacturing practice requirements to hospital-based cyclotron facilities, accelerating regional pharmacy consolidation. The Île-de-France cluster around Paris and the Rhône-Alpes corridor near Lyon concentrate tracer production capacity serving multiple national markets. Koninklijke Philips N.V. digital PET detector architectures reduce scan times for high-throughput outpatient facilities in these metropolitan zones.
Italy
Lombardy and Emilia-Romagna hospital networks maintain substantial standalone SPECT utilization where reimbursement preserves lower-capital modalities. EMA quality guidance drives Italian and Spanish hospital networks toward outsourcing tracer production to centralized regional pharmacies. Milan and Bologna academic centers anchor hybrid imaging adoption for cardiac and oncology applications.
Netherlands
Benelux diagnostic center chains unbundle equipment financing from maintenance and software subscriptions, fragmenting acquisition patterns. Large diagnostic networks separate capital expenditure from operational flexibility without capital intensity. Amsterdam and Rotterdam host mature outpatient imaging chains adopting silicon photomultiplier arrays to double daily patient throughput.
Belgium
Regional cyclotron hubs in Flanders consolidate production to serve multiple national markets under EMA quality guidance. Batch release documentation demands extensive analytical validation that smaller nuclear medicine departments struggle to resource. Brussels and Antwerp radiopharmaceutical manufacturing clusters anchor isotope supply chains for Nordic customers.
Europe Nuclear Medicine Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across detector manufacturing, software validation, and radiopharmaceutical dispensing segments. The vendor base stratifies into three tiers: integrated imaging system manufacturers commanding premium pricing through captive cyclotron partnerships, mid-scale detector component suppliers competing on lutetium crystal sourcing, and regulatory-validated software vendors capturing recurring workflow revenue. Consolidation pressures favor players with backward integration into scintillation materials or forward integration into tracer production networks.
Among diversified imaging conglomerates, GE Healthcare anchors cyclotron and radiopharmacy partnerships securing isotope supply chains, while Siemens Healthineers AG leverages its German university hospital installed base. Koninklijke Philips N.V. occupies a distinct position through digital detector architectures targeting high-throughput outpatient facilities. These three represent contrasting strategic archetypes: supply chain integration, service contract anchoring, and technology differentiation respectively.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Hermes Medical Solutions |
| DOSIsoft SA |
| Mediso Ltd. |
| Mirion Technologies, Inc. |
| Segami Corporation |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up diagnostic center chains in the Netherlands and Belgium are unbundling equipment financing from service contracts, tightening pricing discipline on vendors while fragmenting procurement volumes across multiple suppliers. This ownership pattern compresses margins for PET and SPECT manufacturers that previously captured lifetime value through bundled offerings, while simultaneously forcing radiopharmaceutical producers to absorb certification costs that hospital-based cyclotrons can no longer bear.
Pricing Analysis
The bundled-versus-unbundled service split defines competitive positioning across European nuclear medicine equipment, with three-tier pricing structure across premium, standard, and economy levels separating academic medical centers from outpatient chains. Price differentiation rests on MDR certification grade and after-sales service intensity, with university hospital networks absorbing premium tiers while diagnostic centers gravitate toward stripped-down hardware-only arrangements. Cost compression in economy-tier gamma cameras is intensifying because Southern European reimbursement schedules favor capital discipline over throughput. Outpatient facilities in Spain and Portugal exhibit the sharpest price sensitivity, whereas German university hospitals prioritize uptime guarantees and regulatory documentation over acquisition cost.
Supply Chain Analysis
Direct-to-hospital channels handle cyclotron and radiopharmacy partnerships for German and French academic centers, while distributor-mediated routes serve fragmented diagnostic networks in Southern and Eastern Europe. Geographic supply concentration centers on China, Japan, and the United States for detector-grade lutetium oxyorthosilicate crystals, with scintillation materials drawing from three Asian suppliers that anchor input cost volatility. Raw material dependencies include helium-3 for neutron detection, lutetium-based crystals for PET resolution, and technetium-99m generators for SPECT workflows. Single-source vulnerability in lutetium crystal supply creates procurement risk for Siemens Healthineers and GE Healthcare manufacturing lines. Distribution runs through regional radiopharmacy hubs in Belgium and the Netherlands that consolidate batch release for multiple national markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder, with EU Green Deal isotope mandates and oncology protocol standardization generating predictable replacement cycles for hybrid imaging platforms across Western European hospital networks.
For Market Incumbents: Cement service contract anchoring across German university hospital networks to capture PET/MR renewal revenue streams, while deepening backward integration into scintillation crystal supply through captive semiconductor arrangements. MDR technical documentation burdens threaten margin compression for competitors lacking regulatory affairs scale, making certification investment the critical defensive lever. Prioritize cyclotron partnership exclusivity in France and Belgium to lock out emerging radiopharmaceutical competitors. For New Entrants and Emerging Players: Begin with digital PET detector architectures targeting high-throughput outpatient facilities in Poland, Hungary, and Romania where EU structural funds are modernizing imaging infrastructure. Eastern European hospital capital equipment presents the most penetrable geography, with Spanish and Portuguese outpatient networks offering secondary expansion paths. Pursue software-as-a-service go-to-market models that bypass capital-intensive hardware manufacturing while capturing recurring dosimetry and image reconstruction revenue. For Investors and Strategic Acquirers: Valuations sit cheapest among regulatory-validated software vendors like Hermes Medical Solutions and DOSIsoft SA that command recurring workflow revenue without cyclotron infrastructure exposure. Long-term viability over the projection horizon favors players with EMA-validated quality systems and hospital GPO contract penetration. Watch for EU Green Deal medical isotope sustainability mandates as the inflection signal that recalibrates supply chain economics toward regional cyclotron consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR technical documentation investment secures Class IIb and III device access across German and French hospital procurement. |
| Hospital System Partnership | Exclusive cyclotron supply agreements with Paris and Lyon radiopharmacy clusters lock in tracer-dependent imaging volumes. |
| Software Companion Development | AI-enabled image reconstruction algorithms differentiate digital PET offerings for high-throughput Dutch diagnostic chains. |
| Reimbursement Strategy | FDG-PET and PSMA-targeted agent pathway standardization in French oncology centers accelerates hybrid system procurement. |
| Backward Integration | Captive lutetium crystal sourcing insulates detector manufacturing from Asian supplier concentration risk. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down cyclotron and radiopharmaceutical production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at EMA-notified bodies combined with secondary validation from EMA submission databases, hospital procurement registries, and BfArM post-market surveillance filings. Trade data from German and French customs authorities, alongside SEC filings from listed imaging equipment manufacturers, anchored supply-side triangulation against end-use demand signals.
Historical trendline analysis of PET and SPECT system shipments across the analysis window established baseline growth trajectories, with segmentation modeling across product type, end user, technology, and application dimensions. CAGRs were derived from equipment replacement cycle analysis, cyclotron capacity expansion patterns, and radiopharmaceutical tracer approval timelines. Forecast inputs incorporated EU MDR implementation friction, REACH and RoHS material constraints, and regional reimbursement schedule divergence between German statutory health insurance and French national health service frameworks.
Several conditions sit outside the modeled scope, including unforeseen EMA radiopharmaceutical guidance revisions, abrupt lutetium crystal supply disruptions, and geopolitical trade restrictions affecting scintillation material flows. Forecasts reflect documented assumptions regarding MDR certification timeline standardization and EU structural fund disbursement continuity for Eastern European hospital modernization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Medical Automation Market
Medical Equipment
Medical Fluid Bags Market
Medical Equipment
Global Cardiopulmonary Stress Testing Systems Market
Medical Equipment
Global Carbon Dioxide Incubators Market
Medical Equipment
Intensive Care Unit (ICU) Equipment Market
Medical Equipment
Apheresis Equipment Market
Medical Equipment
Tissue Culture Incubator Market
Medical Equipment
North America Radiotherapy Market
Medical Equipment
Durable Medical Equipment Rental Market
Medical Equipment
Asia-Pacific Medical Device Cleaning Market
Medical Equipment
Operating Table Market
Medical Equipment
Bone Marrow Processing Systems Market
Medical Equipment
Brain Mapping Instruments Market
Medical Equipment
RFID Blood Refrigerators and Freezers Market
Medical Equipment
Benchtop Platelet Agitator Market
Medical Equipment
Hybrid Operating Room Market