
 Cancer Pain Management Market | 2026-2036
Cancer Pain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer Pain Management Market Outlook
Market Context
The gap between genomic biomarker-guided dosing and traditional weight-based opioid titration is narrowing as pharmacogenomic platforms enter clinical workflows. Pfizer Inc. leverages its established hospital formulary relationships to sustain volume in intravenous analgesic categories. Teva Pharmaceutical Industries Ltd. anchors its position through generic opioid portfolios that compete aggressively on price in outpatient settings. Johnson & Johnson differentiates via transdermal delivery systems that dominate post-surgical cancer pain protocols.
Technical Definition and Segments
Cancer pain management encompasses pharmacological and interventional therapies targeting nociceptive, neuropathic, and breakthrough pain pathways in oncology patients, with morphine-equivalent dosing and World Health Organization analgesic ladder protocols serving as standard clinical parameters. The primary purpose is restoring functional capacity and quality of life during active treatment, remission, or end-of-life care. Opioid formulations still occupy the largest revenue pool despite regulatory compression, while transdermal administration routes represent the fastest-expanding segment driven by patient preference for non-invasive chronic dosing. Palliative care settings concentrate margin capture due to reimbursement advantages and longer patient retention compared to acute hospital episodes.
Regulatory Frame
The FDA's REMS program for extended-release and long-acting opioids mandates prescriber certification and patient counseling, directly constraining product access and shaping manufacturer distribution models. The EMA's pharmacovigilance requirements and Germany's AMNOG benefit assessment framework create parallel compliance burdens in Europe. Stakeholders must monitor how pharmacogenomic labeling claims evolve under FDA and EMA review standards, as biomarker-directed analgesia represents the next regulatory frontier for product differentiation and payer negotiation leverage.
Market Dynamics
The FDA's REMS certification mandate for extended-release opioids has triggered a wholesale restructuring of prescriber-manufacturer relationships, forcing pharmaceutical companies to abandon traditional detailing models in favor of certified education platforms that gate product access.
Growth Catalysts
- Pharmacogenomic integration:Biomarker-guided dosing platforms are entering hospital formularies in the United States and Germany, enabling precision opioid titration that reduces adverse events and extends therapy duration.
- Palliative care expansion:Hospital-based palliative units in Japan are adopting multimodal analgesic protocols that bundle transdermal delivery systems with adjuvant therapies, capturing higher reimbursement rates.
- WHO analgesic ladder protocols:National cancer control programs in emerging markets are institutionalizing step-care frameworks that normalize morphine access and expand addressable patient populations.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for synthetic opioids concentrates in a limited number of specialized chemical manufacturers, creating vulnerability to single-source disruptions.
- REMS compliance costs:The FDA's prescriber certification and patient counseling mandates impose fixed operational burdens that disproportionately constrain smaller generic manufacturers with limited field forces.
- Non-opioid substitution:Peripheral nerve stimulation devices and regional anesthesia protocols are capturing post-surgical cancer pain cases that previously defaulted to systemic opioids.
Strategic Opportunities
- Home-based palliative care:Remote patient monitoring platforms in Germany are enabling opioid titration outside institutional settings, opening reimbursement pathways for connected delivery devices.
- EMA pharmacogenomic labeling:The European regulator's evolving framework for biomarker-directed analgesia creates first-mover advantage for manufacturers submitting pharmacogenomic evidence packages.
- Transdermal formulation innovation:Iontophoretic and microneedle delivery technologies are converging with abuse-deterrent polymer matrices to address both patient preference and regulatory safety demands.
Industry Challenges
- Specialized pain nursing shortage:Palliative care units face recruitment gaps for clinicians trained in multimodal analgesic coordination and opioid risk assessment.
- Legacy EHR integration:Pharmacogenomic decision support tools require costly interface development with entrenched hospital information systems that lack standardized data architectures.
- REMS audit complexity:Manufacturers must maintain auditable prescriber certification records across 50 state-level variations in continuing medical education requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer Pain Management Market |
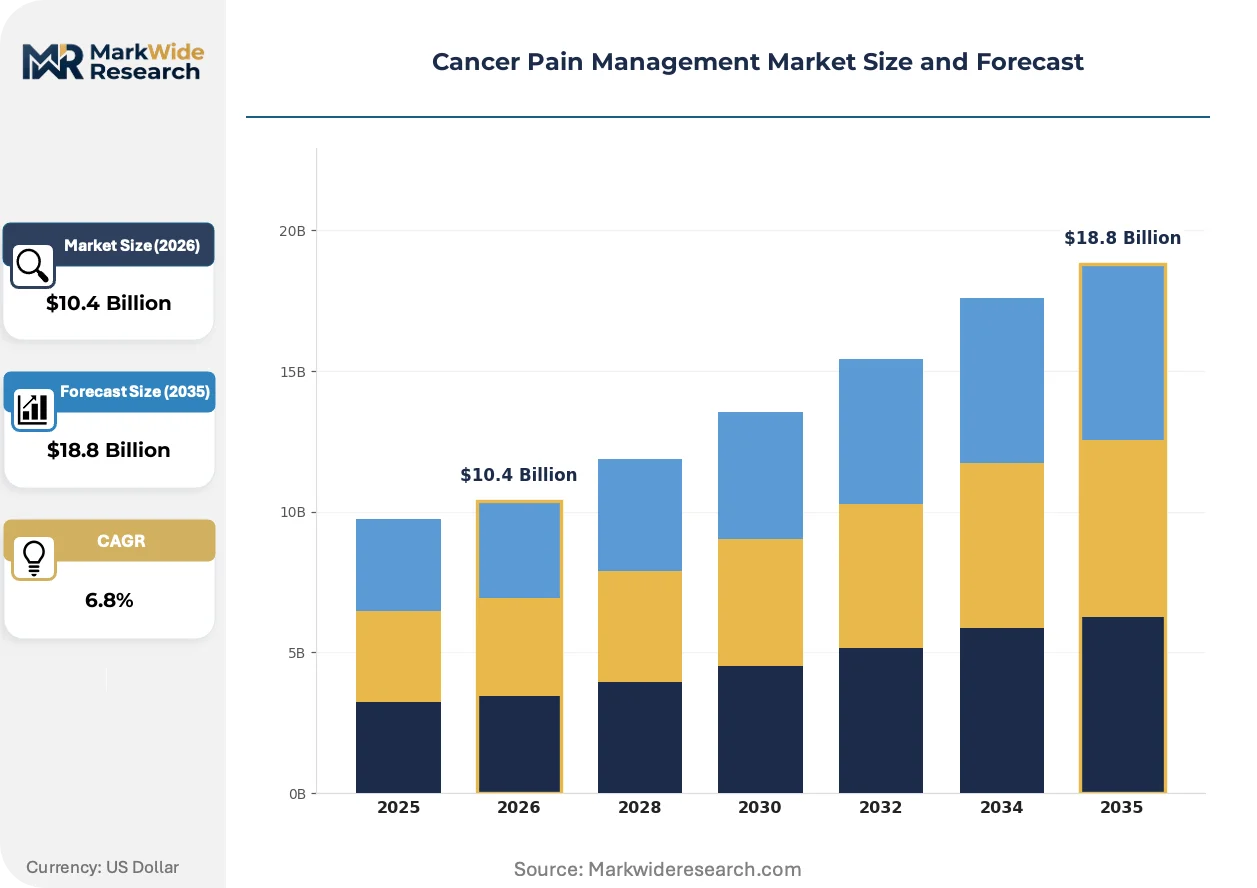
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $18.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Opioids, Non-Opioids, Adjuvant Medications Administration Route: Oral, Intravenous, Transdermal, Subcutaneous Care Setting: Hospitals, Home Care, Palliative Care, Outpatient Clinics Patient Age Group: Pediatric, Adult, Geriatric, Others |
| Companies Covered | Pfizer Inc., Johnson & Johnson, Teva Pharmaceutical Industries Ltd., Novartis AG, Purdue Pharma L.P., AstraZeneca, GlaxoSmithKline plc, Eli Lilly and Company, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer Pain Management Market Strategic Shifts
Pharmacogenomic platforms are collapsing the traditional latency between opioid initiation and effective dosing, compressing the trial-and-error window that has historically defined cancer pain therapy. This technological shift is redistributing value toward diagnostic-analgesic bundled offerings.
Artificial intelligence algorithms analyzing CYP2D6 and OPRM1 variants are collapsing the gap between genomic profiling and bedside dosing decisions. Oncology centers in the United States are deploying these platforms within 48-hour admission windows. The compression of titration timelines is shifting prescribing loyalty toward manufacturers with integrated diagnostic partnerships.
The EMA's evolving pharmacovigilance requirements for extended-release formulations are forcing manufacturers to submit real-world evidence packages as a condition of marketing authorization renewal. German and French regulators are aligning their national assessment frameworks with this standard. Product categories lacking longitudinal safety databases face compressed market access timelines in Europe's largest economies.
Hospital procurement committees are unbundling analgesic purchasing from traditional group purchasing organization contracts, negotiating direct manufacturer agreements that incorporate outcomes guarantees and risk-sharing provisions. This behavioral shift is most visible in United States academic medical centers with established palliative care divisions. The displacement of GPO intermediaries is compressing price transparency and accelerating switching between therapeutic alternatives.
Cancer Pain Management Market Segmentation
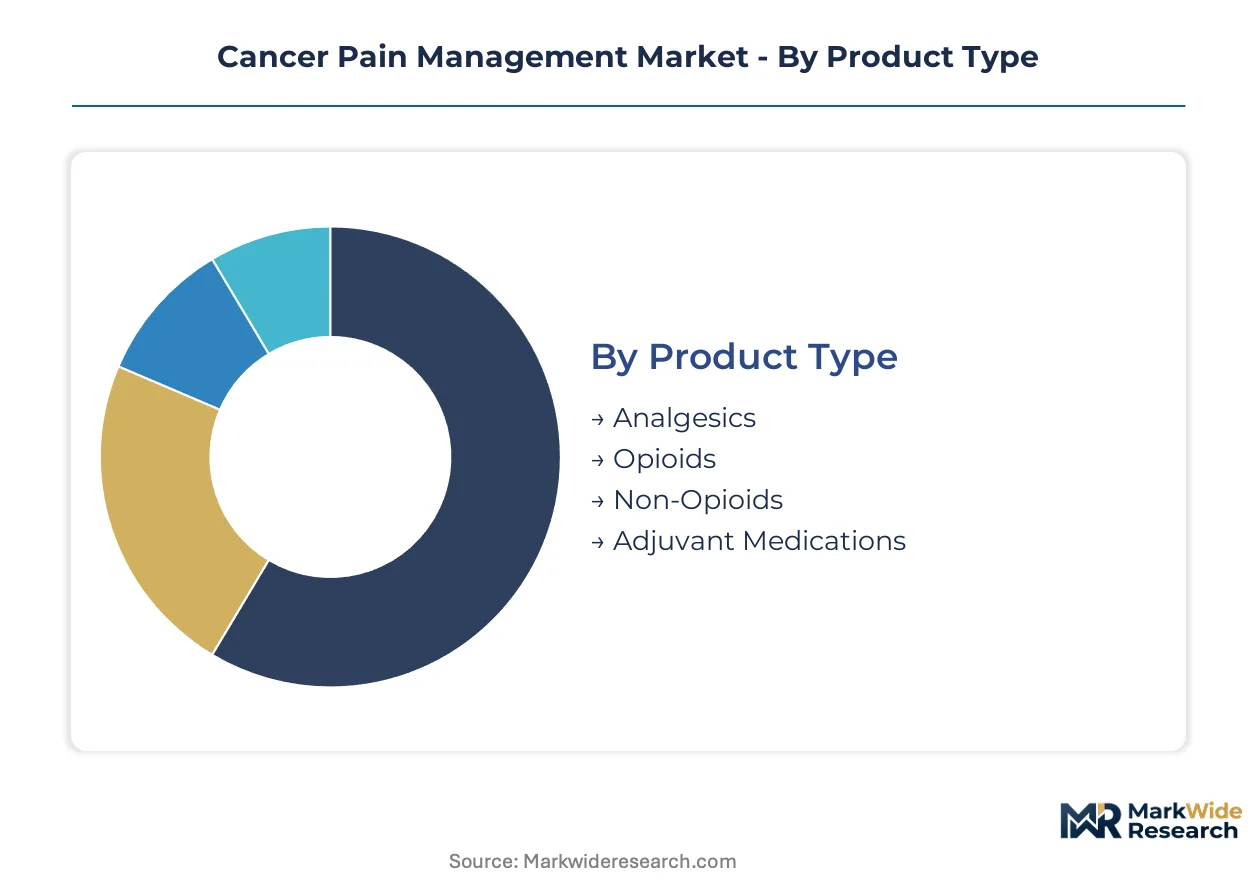
Cancer pain management segmentation reveals how clinical workflows, reimbursement structures, and patient acuity reshape demand patterns across product categories. Understanding these divisions exposes where margin concentrates versus where volume scales.
Product Type:
Cycle times vary sharply across pharmacological categories, with acute rescue medications turning over in days while maintenance formulations stretch across months of therapy.
- Opioids:Morphine-equivalent formulations remain the clinical backbone for moderate-to-severe nociceptive pain, with extended-release and immediate-release variants serving distinct temporal patterns in the WHO analgesic ladder. Demand concentrates in United States hospital formularies where REMS-certified prescribing gates access, though German palliative care units are expanding multimodal protocols that blend opioid classes with adjuvant therapies to reduce dependence escalation.
- Non-Opioids:NSAIDs and acetaminophen combinations address mild-to-moderate pain and step-down scenarios, with particular traction in Japanese outpatient oncology clinics managing treatment-related toxicities. The segment faces compression from peripheral nerve stimulation devices capturing post-surgical cases that previously defaulted to systemic pharmacology.
- Analgesics:Broad-spectrum pain relievers span multiple mechanisms and serve as flexible rescue options across care settings.
- Adjuvant Medications:Anticonvulsants and antidepressants targeting neuropathic pain pathways complement primary analgesia in complex cases.
Opioids dominate installed base. Non-Opioids is where expansion concentrates.
Administration Route:
Cost tiers separate invasive from non-invasive delivery, with premium positioning attaching to patient-controlled and continuous infusion technologies versus commoditized oral generics.
- Transdermal:Fentanyl and buprenorphine patches enable steady-state plasma levels without first-pass metabolism, with particular adoption in United States home hospice programs where caregiver burden reduction drives formulary preference. Johnson & Johnson's established hospital relationships sustain volume in post-surgical cancer protocols, while iontophoretic innovations are advancing through FDA review for breakthrough pain rescue.
- Intravenous:Patient-controlled analgesia pumps and continuous infusions serve acute exacerbations and perioperative periods, with concentration in German academic medical centers where specialized pain nursing supports titration protocols. The segment faces margin pressure from generic competition and growing regional anesthesia substitution.
- Oral:Immediate and extended-release tablets remain the default for stable chronic pain, with lowest per-dose cost but highest adherence variability.
- Subcutaneous:Portable infusion devices bridge hospital and home settings for patients requiring steady opioid delivery without vascular access.
Oral formulations dominate installed base. Transdermal delivery is expanding most quickly.
Care Setting:
Application context determines reimbursement rates and therapy duration, with institutional episodes yielding higher per-patient revenue than ambulatory management.
- Palliative Care:Dedicated units in Japan and Germany bundle multimodal analgesia with psychosocial support, capturing enhanced reimbursement for complex symptom management. Hospital-based programs in the United States are expanding bed capacity as oncology centers integrate early palliative referral protocols, with average patient retention exceeding acute episodes by substantial margins.
- Hospitals:Acute oncology wards and surgical services generate concentrated demand for intravenous rescue medications and perioperative pain protocols, with formulary decisions driven by anesthesia and pharmacy committees.
- Home Care:Remote monitoring platforms in Germany are enabling opioid titration outside institutional walls, opening reimbursement pathways for connected delivery devices and telehealth supervision.
- Outpatient Clinics:Community oncology practices manage stable chronic pain with oral formulations and periodic reassessment.
Hospitals dominate installed base. Palliative Care is where expansion concentrates.
Patient Age Group:
Volume scales with demographic weighting toward aging populations, while pediatric applications require specialized formulations and dosing expertise that constrain supplier participation.
- Geriatric:Patients over 65 constitute the predominant cancer pain burden across United States, German, and Japanese markets, with polypharmacy complexity and renal clearance considerations driving demand for transdermal alternatives to oral polypharmacy. Pharmacogenomic platforms are entering workflows to guide opioid selection amid CYP450 variability in aging populations.
- Adult:Working-age patients between 18 and 64 balance efficacy demands with functional preservation requirements, with particular sensitivity to sedation and cognitive side effects that affect employment.
- Pediatric:Neonatal through adolescent populations require weight-based dosing and specialized formulations, with limited approved products constraining therapeutic options.
- Others:Adolescent and young adult categories span developmental transitions with distinct psychosocial and adherence considerations.
Geriatric populations dominate installed base. Adult segments are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in cancer pain management products show the United States importing specialized transdermal formulations while exporting extended-release opioid technologies. Germany and Japan maintain near-balanced pharmaceutical exchange in analgesic categories, with both nations serving as regional distribution hubs for neighboring markets.
United States
Hospital-based palliative care units in the United States are expanding bed capacity to accommodate aging oncology populations. The FDA's Risk Evaluation and Mitigation Strategy mandates prescriber certification for extended-release opioids, reshaping manufacturer distribution models. Academic medical centers in Boston and New York Metro are unbundling analgesic purchasing from group purchasing organization contracts to negotiate direct agreements.
Germany
German palliative care units are adopting multimodal analgesic protocols that bundle transdermal delivery systems with adjuvant therapies. The AMNOG benefit assessment framework creates compliance burdens that favor manufacturers with robust health technology assessment capabilities. Hospital clusters in Bavaria and North Rhine-Westphalia are deploying remote patient monitoring platforms to enable home-based opioid titration.
Japan
Japan's aging cancer population is driving sustained clinical investment in pain management infrastructure. The PMDA maintains stringent pharmacovigilance requirements for extended-release formulations that align with evolving EMA standards. Oncology centers in the Kanto region around Tokyo are integrating early palliative referral protocols that extend average patient retention.
United Kingdom
The UK's National Health Service is institutionalizing WHO analgesic ladder protocols through national cancer control programs. NICE guidelines shape formulary decisions across England's regional clinical commissioning groups. Research institutions in London and the Southeast are advancing pharmacogenomic platforms for precision opioid dosing in geriatric populations.
India
Indian pharmaceutical manufacturers are expanding generic opioid production for export to regulated markets. The CDSCO is strengthening active pharmaceutical ingredient oversight to address supply concentration vulnerabilities. Manufacturing clusters in Maharashtra and Gujarat are investing in specialized chemical synthesis capabilities for synthetic opioid precursors.
Cancer Pain Management Market Competitive Environment
On the supply side, the industry is consolidating around manufacturers with established hospital formulary relationships and certified education platforms. Three strategic archetypes dominate: diversified pharmaceutical conglomerates with transdermal delivery expertise, generic specialists competing on price in outpatient settings, and precision medicine platforms integrating pharmacogenomic diagnostics. Competitive intensity centers on M&A activity targeting diagnostic-analgesic bundled offerings and strategic partnerships with remote patient monitoring providers.
Among diversified pharmaceutical conglomerates, Pfizer Inc., Johnson & Johnson, and Teva Pharmaceutical Industries Ltd. occupy distinct positioning vectors. Pfizer exemplifies the hospital-centric archetype leveraging intravenous analgesic categories. Johnson & Johnson represents transdermal delivery system specialization. Teva Pharmaceutical Industries Ltd. anchors the generic opioid portfolio segment competing aggressively on outpatient pricing.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd. |
| Novartis AG |
| Purdue Pharma L.P. |
| AstraZeneca |
| GlaxoSmithKline plc |
| Eli Lilly and Company |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
Active pharmaceutical ingredient production for synthetic opioids concentrates in Indian and Chinese specialized chemical manufacturers, creating upstream chokepoints that downstream formulation players convert into margin capture through REMS-certified distribution networks and hospital formulary lock-ins.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy tiers, with transdermal delivery systems commanding premium positioning due to Johnson & Johnson's established post-surgical protocols and FDA abuse-deterrent certifications. Price differentiation hinges on REMS compliance infrastructure and pharmacogenomic labeling claims. Cost compression in generic oral opioids is intensifying as Teva Pharmaceutical Industries Ltd. and Indian manufacturers compete on outpatient volume. Oncology clinics in Japan exhibit highest price sensitivity due to national health insurance reimbursement ceilings, while United States academic medical centers with dedicated palliative divisions demonstrate lowest sensitivity when bundled with outcomes guarantees.
Supply Chain Analysis
Contract manufacturing of extended-release opioid formulations concentrates among Patheon, Catalent, and specialized European CMs with FDA-inspected facilities. API synthesis draws from Maharashtra and Gujarat clusters in India, supplemented by Zhejiang and Jiangsu provinces in China. The supply chain rests on concentrated precursor chemical availability from single-source suppliers. Tariff exposure on Chinese-sourced intermediates poses structural vulnerability. Distribution runs through REMS-certified specialty pharmacies and direct hospital agreements that bypass traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
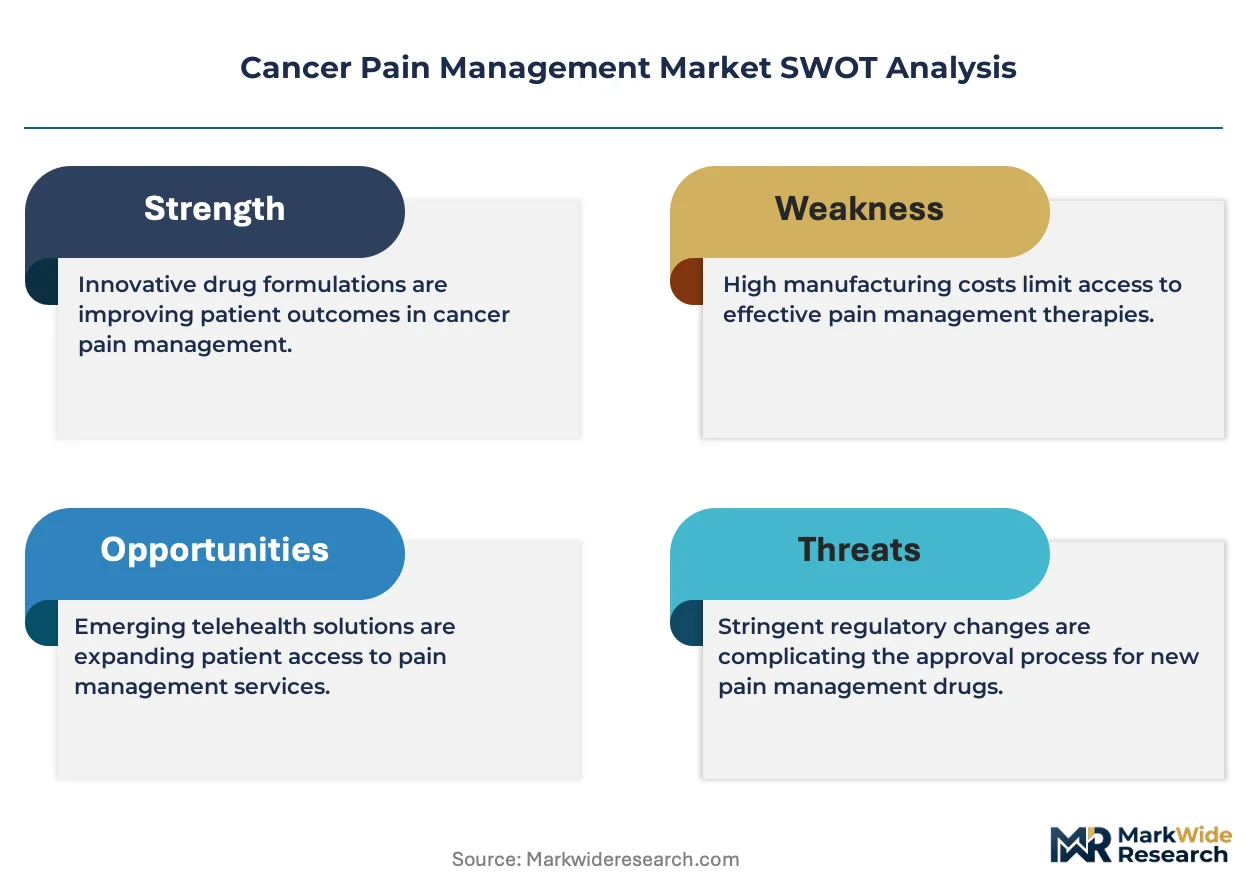
Pharmacogenomic platform integration is disrupting traditional weight-based opioid titration, creating first-mover advantage windows for manufacturers bundling diagnostic-analgesic offerings before EMA labeling frameworks crystallize.
For Market Incumbents: Harden REMS-certified prescriber relationships through exclusive education platform partnerships that gate competitor access to hospital formularies. Deepen backward integration into specialized API synthesis to mitigate Indian and Chinese supply concentration risks. Pfizer Inc.'s intravenous analgesic volume depends on defending anesthesia committee relationships against regional anesthesia substitution. For New Entrants and Emerging Players: Establish a beachhead in German home-based palliative care by pairing connected delivery devices with remote patient monitoring platforms that qualify for enhanced reimbursement. Target adult working-age segments in United States outpatient oncology where functional preservation requirements create willingness-to-pay for non-sedating alternatives. Pursue pharmacogenomic diagnostic partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic opioid portfolios lacking REMS infrastructure and pharmacogenomic capabilities. Five-to-ten year viability favors manufacturers with integrated diagnostic-analgesic bundles and established hospital GPO bypass relationships. Monitor FDA pharmacogenomic labeling decisions as the critical inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Diagnostic Partnership | Bundles CYP2D6 testing with opioid prescribing to reduce adverse events and extend therapy duration. |
| REMS Education Platform Certification | Gates prescriber access and locks out competitors lacking compliant field infrastructure. |
| Transdermal Iontophoretic Innovation | Addresses breakthrough pain rescue while meeting FDA abuse-deterrent polymer matrix requirements. |
| Home-Based Palliative Care Expansion | Captures German reimbursement pathways for connected delivery devices outside institutional settings. |
| API Backward Integration | Reduces vulnerability to Indian and Chinese single-source precursor disruptions. |
Study Parameters
Desk research of FDA REMS compliance databases, EMA pharmacovigilance filings, and hospital formulary directories preceded structured interviews with palliative care physicians, hospital pharmacy directors, regulatory affairs specialists, and GPO contract managers. Secondary validation drew from ClinicalTrials.gov entries, CMS Medicare reimbursement data, and pharmaceutical trade flow records. Bottom-up patient volume estimates and top-down manufacturer revenue analysis were triangulated across these sources.
Assumptions held fixed include current FDA REMS certification requirements and existing WHO analgesic ladder protocol adoption rates, while pharmacogenomic platform penetration and home-based care reimbursement pathways were varied across sensitivity scenarios. Segmentation modeling spanned product type, administration route, care setting, and patient age group dimensions across the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical extended-release opioid prescription trends and palliative care bed expansion rates.
Sensitivities concentrate around FDA pharmacogenomic labeling decisions, EMA real-world evidence submission requirements, and Indian API export restriction policies. Quarterly review of REMS audit findings, hospital procurement committee unbundling announcements, and CDSCO manufacturing inspection reports is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Heat Therapy Market
Pain Management
Pain Management Devices Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Provoked Vestibulodynia Treatment Market
Pain Management
Tattoo Numbing Cream Market
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Chronic Pain Market
Pain Management
Global Pain Management Market
Pain Management
Cluster Headache Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Chronic Pain Treatment Market