
 Chemotherapy Induced Thrombocytopenia Market | 2026-2036
Chemotherapy Induced Thrombocytopenia Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy Induced Thrombocytopenia Market Analysis
Recombinant thrombopoietin analogs are broadening therapeutic options beyond traditional platelet transfusions, reducing transfusion dependency and associated complications. Amgen Inc. leverages its biologics manufacturing scale to dominate the growth factor segment. Novartis AG anchors European market access through specialized oncology distribution networks. Pfizer Inc. competes across multiple delivery modes with integrated hospital contracting.
Chemotherapy induced thrombocytopenia denotes a hematologic complication characterized by platelet counts falling below safe thresholds, typically defined as fewer than 50,000 platelets per microliter, requiring intervention to prevent hemorrhage during cytotoxic cancer treatment. The condition arises when myelosuppressive chemotherapy damages megakaryocyte progenitors in bone marrow, necessitating exogenous platelet support or pharmacologic stimulation of thrombopoiesis. Platelet enhancers command the largest revenue pool due to recurring administration cycles across multi-month oncology regimens. Intravenous delivery maintains protocol dominance in hospital settings, though subcutaneous formulations are gaining traction in outpatient and home care environments where patient convenience drives formulary decisions.
The FDA oversees clinical trial endpoints and labeling for thrombopoietin receptor agonists, while the EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across EU member states. Both agencies require robust cardiovascular safety data, extending development timelines but elevating barriers to entry for new entrants. Stakeholders must monitor evolving biosimilar pathways for reference biologics, as patent cliffs on established growth factors will reshape competitive dynamics and pricing architectures.
Market Dynamics
The FDA's evolving guidance on thrombopoietin receptor agonists is compressing development timelines while elevating cardiovascular safety requirements, forcing sponsors to front-load risk mitigation strategies in clinical protocols.
Growth Catalysts
- Expanded supportive care protocols:Oncology clinics are integrating platelet-enhancing therapies earlier in treatment cycles, reducing transfusion dependency and associated complications. This shift is standardizing pharmacologic intervention across integrated cancer centers.
- EMA centralized marketing authorizations:The Committee for Medicinal Products for Human Use is streamlining cross-border access for thrombopoietin receptor agonists, enabling faster patient access in EU member states with fragmented reimbursement systems.
- Subcutaneous formulation development:Outpatient and home care environments are driving formulary decisions toward patient-administered delivery modes, expanding addressable settings beyond hospital infusion centers.
Market Restraints
- Cardiovascular safety data requirements:Both FDA and EMA mandate extensive cardiac monitoring endpoints, extending development timelines and elevating capital requirements for new entrants seeking marketing authorization.
- Reference biologic patent cliffs:Established growth factors face imminent biosimilar competition, creating pricing pressure that compresses revenue pools for originator products and deters incremental innovation investment.
- Megakaryocyte progenitor biology complexity:Variable patient response to thrombopoietin stimulation limits predictable efficacy, constraining label expansion into broader oncology indications.
Strategic Opportunities
- Home care channel penetration:Subcutaneous administration protocols are creating white space in ambulatory settings, enabling service unbundling from hospital-based infusion centers.
- Dual carbon goals alignment:China's NMPA is prioritizing reduced transfusion dependency as a sustainability metric, creating regulatory tailwind for platelet enhancers in the country's expanding oncology infrastructure.
- Real-world evidence integration:FDA's expanding acceptance of post-market surveillance data is opening pathways for label expansion based on retrospective outcomes rather than prospective trials.
Industry Challenges
- Specialized hematology-oncology trial design:Complex platelet count endpoint validation requires rare expertise in coagulation biomarker interpretation, creating recruitment bottlenecks for clinical operations teams.
- Legacy transfusion infrastructure lock-in:Hospital blood bank relationships and established reimbursement codes for platelet units create switching friction against pharmacologic alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy Induced Thrombocytopenia Market |
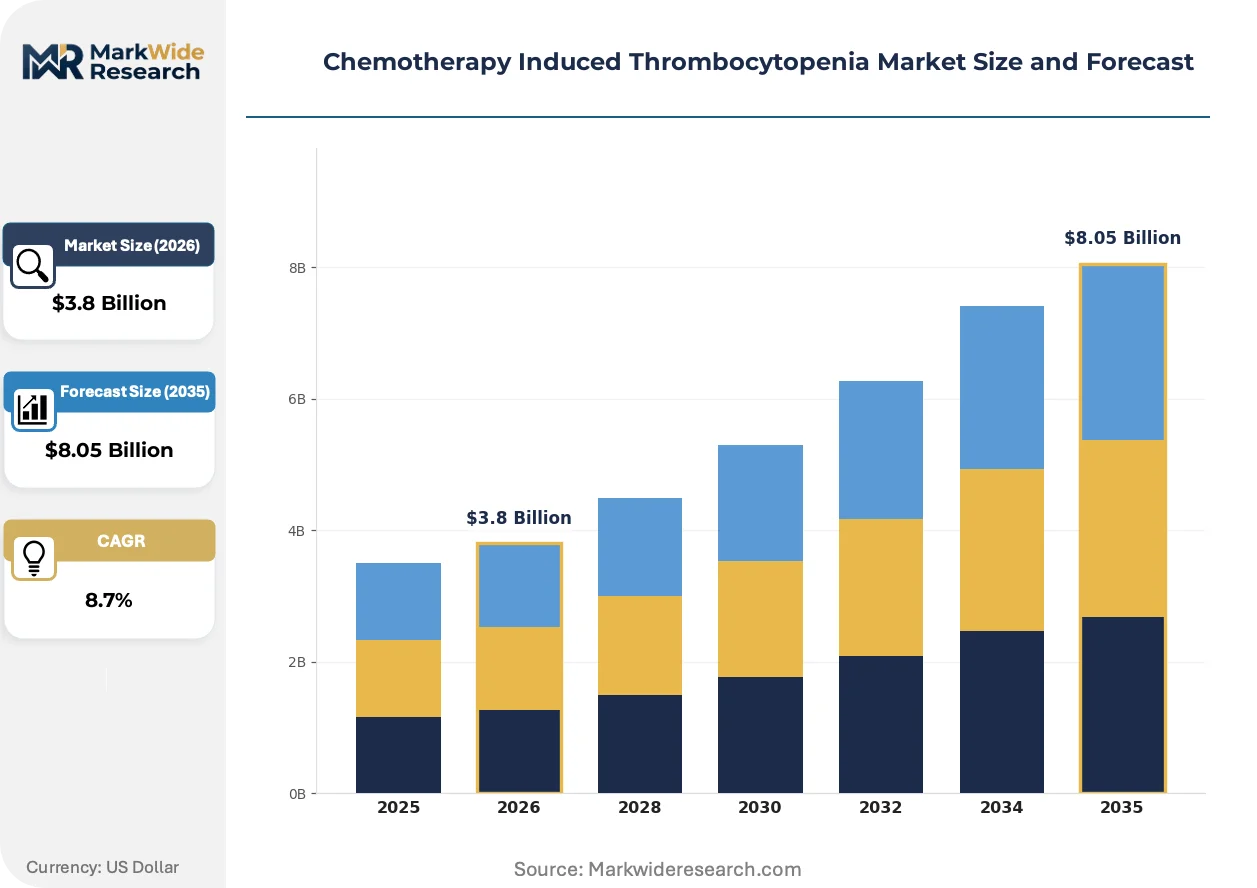
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Platelet Enhancers, Antithrombotic Agents, Immunoglobulin Therapies, Growth Factors Therapy Area: Hematologic Disorders, Oncology, Pharmacotherapy, Supportive Care Delivery Mode: Intravenous, Subcutaneous, Oral, Injectable End User: Hospitals, Clinics, Home Care, Outpatient Facilities |
| Companies Covered | Amgen Inc., Novartis AG, Pfizer Inc., Teva Pharmaceutical Industries Ltd, Swedish Orphan Biovitrum AB, Johnson & Johnson, Fresenius Kabi AG, Jiangsu HengRui Medicine Co., Ltd., Mylan N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy Induced Thrombocytopenia Market Emerging Trajectories
Biologics manufacturing scale and delivery mode innovation are actively rewriting competitive boundaries in platelet support therapy, compressing the traditional transfusion-pharmacology divide.
Recombinant thrombopoietin analogs are rewriting therapeutic paradigms by enabling prophylactic platelet management rather than reactive transfusion. Integrated cancer centers in the United States are adopting these agents at accelerating pace across multi-month regimens. The structural consequence is a compression of hospital blood bank utilization rates and a reallocation of supportive care budgets toward pharmaceutical interventions.
REACH regulatory frameworks in Europe are tightening environmental accountability for biologics manufacturing waste streams, compelling facility upgrades. Industrial consequence includes elevated production costs for European-sourced active pharmaceutical ingredients. The segment most affected is contract manufacturing organizations serving EU markets, which are responding by consolidating production into fewer, higher-capacity sites with advanced effluent treatment.
Hospital procurement committees are unbundling supportive care contracts from chemotherapy bundling agreements, creating discrete purchasing categories for platelet management. The channel being disrupted is traditional group purchasing organization dominance, replaced by direct manufacturer-contracting for high-value biologics. This pattern is most visible in United States academic medical centers, where pharmacy and therapeutics committees now independently evaluate thrombopoietin receptor agonists.
Chemotherapy Induced Thrombocytopenia Market Segmentation
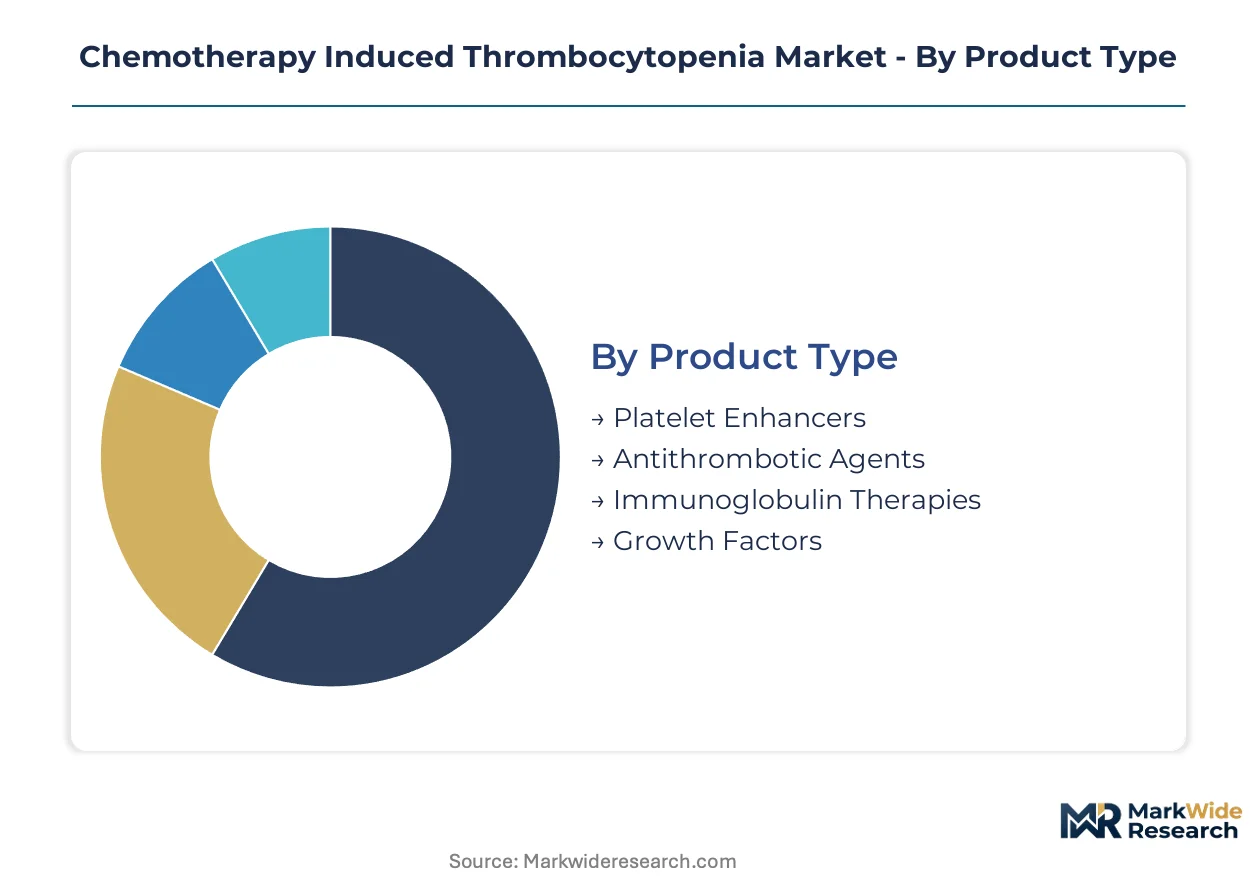
Segmentation in the chemotherapy induced thrombocytopenia market reveals how capital allocation, regulatory pathways, and care setting economics fragment commercial opportunity. Product type and delivery mode segments carry the heaviest manufacturing infrastructure burdens, while end user and therapy area dimensions determine reimbursement velocity and prescriber access.
Product Type:
Platelet enhancers demand the steepest upfront biologics manufacturing investment, with recombinant protein production requiring dedicated cell culture suites and extensive purification trains. Antithrombotic agents and immunoglobulin therapies occupy intermediate capital tiers, while growth factors leverage existing cytokine manufacturing platforms with lower facility barriers.
- Platelet Enhancers:Recombinant thrombopoietin receptor agonists manufactured through mammalian cell expression systems require multi-hundred-million-dollar bioreactor installations and extended viral clearance validation. United States integrated cancer centers concentrate demand as these institutions standardize pharmacologic platelet support across myelosuppressive regimens, driven by transfusion reduction protocols and blood bank cost containment mandates.
- Growth Factors:Established erythropoietin and G-CSF manufacturing infrastructure partially transfers to thrombopoietic cytokine production, lowering greenfield investment thresholds. European EMA centralized authorizations accelerate access across fragmented reimbursement systems, though REACH environmental compliance elevates ongoing operational expenditure for EU-sourced active pharmaceutical ingredients.
- Antithrombotic Agents:Small-molecule synthesis routes with lower capital intensity than biologics, though specialized hematology-oncology indication trials require equivalent clinical development spend.
- Immunoglobulin Therapies:Plasma fractionation dependency constrains supply scalability; Cohn fractionation and chromatographic purification infrastructure dominates capital allocation.
Most installed capacity flows through platelet enhancers. Expansion is steepest in growth factors as manufacturing platform standardization accelerates.
Therapy Area:
Oncology commands the dominant share of clinical trial investment and regulatory submission expenditure, with supportive care indications trailing in absolute capital deployment but gaining share through label expansion strategies.
- Oncology:Myelosuppressive chemotherapy regimens in solid tumors and hematologic malignancies drive the core addressable population, with FDA thrombopoietin receptor agonist guidance shaping endpoint validation costs.
- Supportive Care:Prophylactic platelet management protocols are expanding fastest as integrated cancer centers unbundle supportive care from chemotherapy bundling agreements, creating discrete purchasing categories.
- Hematologic Disorders:Aplastic anemia and myelodysplastic syndrome indications require specialized trial design with rare disease recruitment premiums.
- Pharmacotherapy:Combination regimen development with cytotoxic agents elevates interaction study burdens and extends development timelines.
Clinical development spend concentrates in oncology. Supportive care label expansion is climbing the fastest as real-world evidence pathways mature.
Delivery Mode:
Intravenous administration retains infrastructure lock-in through hospital infusion center dependency, while subcutaneous formulation development demands equivalent analytical characterization investment with differentiated device and stability package costs.
- Intravenous:Hospital-based infusion infrastructure with established reimbursement codes and blood bank coordination protocols maintains protocol dominance in acute care settings.
- Subcutaneous:Patient-administered delivery enables ambulatory and home care penetration, with United States outpatient facilities driving formulary prioritization based on convenience metrics and total cost of care reduction.
- Oral:Small-molecule thrombopoietin receptor agonists in development promise the lowest administration infrastructure burden, though bioavailability challenges elevate formulation science investment.
- Injectable:Intramuscular and depot formulations occupy niche positioning with limited current commercial presence.
Hospital procurement volume flows predominantly through intravenous channels. Subcutaneous expansion is gaining share fastest as home care reimbursement frameworks mature.
End User:
Hospitals absorb the highest per-site capital investment in biologics cold chain and pharmacy infrastructure, while home care penetration requires distributed logistics networks with equivalent aggregate capital deployment across numerous smaller sites.
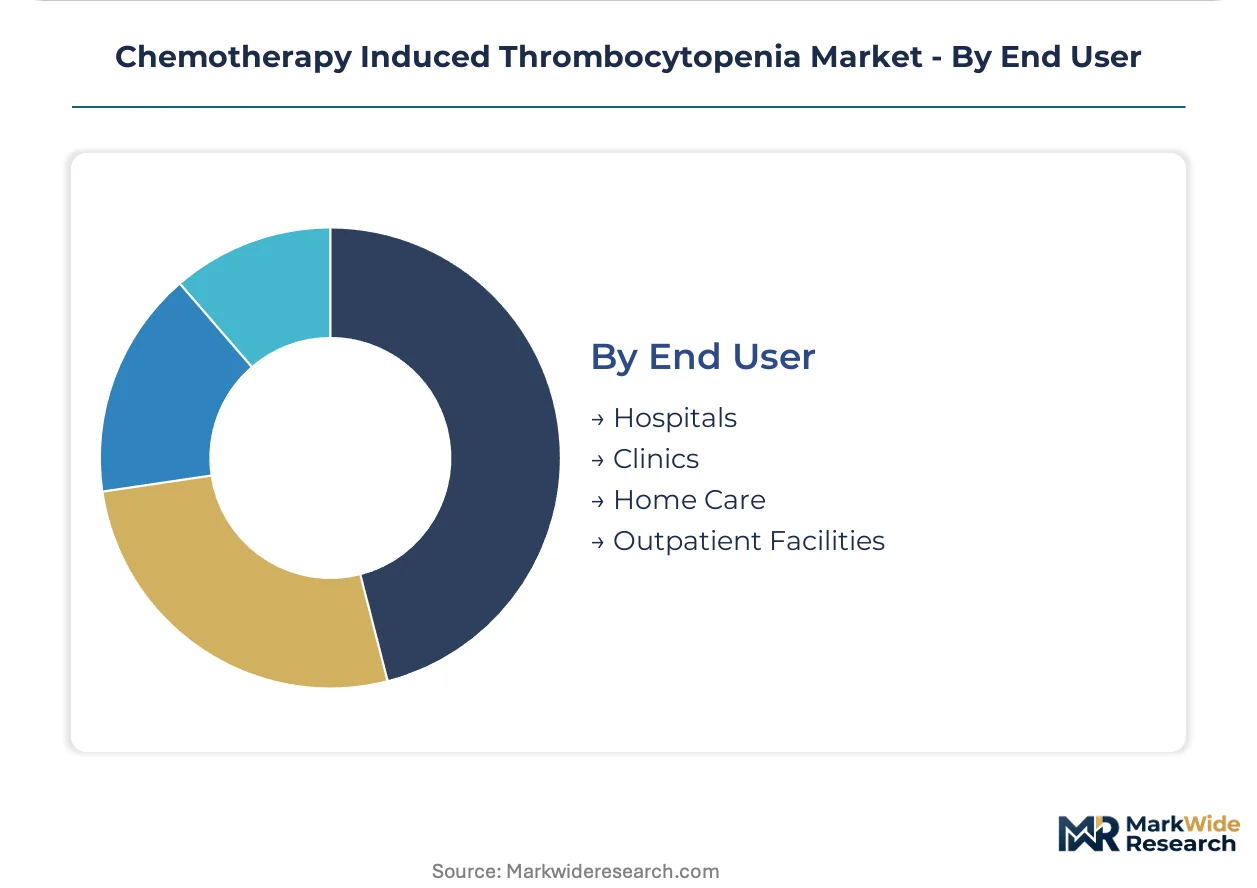
- Hospitals:Academic medical centers and integrated cancer centers in the United States concentrate high-value biologics procurement through independent pharmacy and therapeutics committees, displacing traditional group purchasing organization dominance.
- Clinics:Community oncology practices with limited infusion capacity favor subcutaneous alternatives, though reimbursement parity gaps constrain adoption velocity.
- Home Care:Self-administration protocols and remote monitoring infrastructure create white space outside hospital walls, with nursing support requirements elevating service delivery costs.
- Outpatient Facilities:Ambulatory surgery centers and infusion suites occupy intermediate positioning with growing procedure migration from inpatient settings.
Biologics distribution infrastructure concentrates in hospitals. Home care channel development is expanding most quickly as patient-administered formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated cancer centers in the United States concentrate the highest density of thrombopoietin receptor agonist utilization, establishing the clinical protocol templates that diffuse internationally through academic medical networks and regulatory reference standards.
United States
FDA guidance on cardiovascular safety endpoints shapes trial design costs for all sponsors targeting the market. Academic medical centers in Boston and the Research Triangle unbundle supportive care contracts from chemotherapy bundling, creating discrete purchasing categories for platelet enhancers. Hospital procurement committees now independently evaluate thrombopoietin receptor agonists through pharmacy and therapeutics channels.
Germany
EMA centralized marketing authorizations through the Committee for Medicinal Products for Human Use accelerate cross-border patient access. REACH environmental frameworks tighten accountability for biologics manufacturing waste streams, compelling facility upgrades among contract manufacturing organizations. The Rhine-Main cluster consolidates production into fewer high-capacity sites with advanced effluent treatment capabilities.
China
NMPA prioritization of reduced transfusion dependency aligns platelet enhancer development with national dual carbon goals. Domestic oncology infrastructure expansion creates regulatory tailwind for localized manufacturing of thrombopoietin analogs. The Yangtze River Delta biotech corridor attracts capacity investments from both multinational and indigenous developers seeking proximity to hospital networks.
Japan
PMDA evaluation standards for supportive care biologics emphasize real-world evidence integration from post-market surveillance. METI industrial policy incentivizes domestic biologics manufacturing scale to reduce import dependency for critical oncology medicines. The Kansai region maintains concentration of plasma fractionation infrastructure serving immunoglobulin therapy demand.
United Kingdom
NICE technology appraisal processes determine reimbursement velocity for thrombopoietin receptor agonists within the National Health Service. MHRA post-Brexit regulatory autonomy enables streamlined marketing authorization pathways for novel platelet-enhancing modalities. The London-Southeast corridor concentrates hematology-oncology trial recruitment through specialized research networks.
Chemotherapy Induced Thrombocytopenia Market Vendor Landscape
Portfolio diversification dominates the current landscape as established biologics manufacturers extend cytokine manufacturing platforms into thrombopoietic growth factors. The market structure concentrates around three strategic archetypes: multinational pharmaceutical conglomerates with integrated hospital contracting capabilities, mid-cap biologics specialists with focused hematology-oncology portfolios, and emerging biosimilar developers targeting patent cliffs on reference biologics. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturing scale and regulatory submission velocity serving as primary differentiators.
Among North American-based developers, Amgen Inc. and Pfizer Inc. anchor the scale-driven tier with established biologics manufacturing infrastructure and integrated distribution networks. Novartis AG exemplifies the European multinational archetype, leveraging specialized oncology distribution networks to secure market access across fragmented reimbursement systems. Jiangsu HengRui Medicine Co., Ltd. represents the Asia-Pacific indigenous developer segment, occupying a position shaped by proximity to expanding domestic oncology infrastructure and NMPA regulatory pathways.
| Leading Market Players |
|---|
| Amgen Inc. |
| Novartis AG |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd |
| Swedish Orphan Biovitrum AB |
| Johnson & Johnson |
| Fresenius Kabi AG |
| Jiangsu HengRui Medicine Co., Ltd. |
| Mylan N.V. |
| Others |
Supply Flow & Price Mechanics
Mammalian cell culture media costs cascade through recombinant thrombopoietin production tiers, with United States-sourced fetal bovine serum commanding premium pricing against Chinese alternatives that feed economy-grade biosimilar manufacturing channels.
Pricing Analysis
Input-cost pass-through from bioreactor-grade raw materials shapes contract manufacturing organization quotes, with three-tier pricing structure across premium, standard, and economy levels reflecting GMP certification grade and viral clearance validation depth. FDA-validated facilities extract brand premiums from integrated cancer centers, while REACH environmental compliance costs elevate European-sourced active pharmaceutical ingredients above Asian alternatives. Pricing pressure stems from impending patent cliffs on reference biologics, compressing originator margins and accelerating biosimilar entry. Community oncology practices exhibit highest price sensitivity due to limited infusion reimbursement parity, whereas academic medical centers prioritize clinical protocol standardization over unit cost.
Supply Chain Analysis
Cell line development and master cell bank maintenance rests on specialized contract manufacturing organizations concentrated in the United States, Germany, and China, with viral vector production capacity anchoring in the Boston-Cambridge corridor and the Yangtze River Delta biotech cluster. Stainless steel bioreactor fabrication draws from German and Japanese precision engineering suppliers, while single-use bag assemblies hinge on South Korean polymer film specialists. Single-source vulnerability pervades the viral clearance filtration segment, where Pall and Sartorius dominance creates procurement bottlenecks during capacity expansion cycles. Distribution runs through temperature-controlled logistics networks serving hospital-based infusion centers, with direct manufacturer contracting displacing traditional group purchasing organization channels for high-value biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost arbitrage between United States GMP-validated facilities and Chinese NMPA-registered sites creates geographic positioning leverage, with REACH environmental compliance in Europe adding regulatory-driven cost differentiation.
For Market Incumbents: Deploy manufacturing platform standardization to amortize bioreactor infrastructure across cytokine portfolios, extending thrombopoietic growth factor production without greenfield capital deployment. Consolidate contract manufacturing organization relationships to secure viral clearance filtration capacity against single-source bottlenecks. Deepen backward integration into cell line development to reduce dependency on external master cell bank providers facing capacity constraints. For New Entrants and Emerging Players: Digital health platform partnerships with remote patient monitoring vendors open ambulatory administration channels outside hospital infusion center lock-in. Home care reimbursement frameworks in United States Medicare Advantage plans represent the most penetrable segment, with subcutaneous formulation development as the critical go-to-market angle. Target community oncology practices with limited blood bank infrastructure through pharmacy benefit manager contracting. For Investors and Strategic Acquirers: Consolidation pressure builds where biosimilar developers face extended FDA cardiovascular safety data requirements that strain capital reserves before revenue realization. Long-term viability favors platforms with demonstrated thrombopoietin receptor agonist manufacturing scale and existing EMA centralized marketing authorizations. Watch for NMPA approval velocity in China as inflection indicator for geographic demand rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Patient-administered delivery expands addressable settings beyond hospital infusion centers into home care environments. |
| EMA Centralized Marketing Authorization | Streamlined cross-border access accelerates patient reach across EU member states with fragmented reimbursement systems. |
| Real-World Evidence Integration | FDA post-market surveillance acceptance opens label expansion pathways without prospective clinical trial expenditure. |
| Biologics Manufacturing Scale-Up | Multi-hundred-million-dollar bioreactor installations secure capacity for multi-month oncology regimen demand cycles. |
| Biosimilar Development Pipeline | Patent cliff positioning on reference thrombopoietin growth factors captures pricing compression upside in economy tiers. |
Methodological Framework
Bottom-up oncology clinic demand modeling reconciled against top-down biologics manufacturing capacity tracking forms the analytical core, combining primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Triangulation across stakeholder perspectives and documentary sources addresses data gaps inherent in pre-commercial pipeline assessment.
Historical trendline analysis of thrombopoietin receptor agonist adoption patterns across academic medical centers established baseline penetration curves, with forward projection incorporating segmentation dimensions of delivery mode, therapy area, end-user setting, and regional regulatory cluster. CAGR derivation reflected procedure volume trajectories in myelosuppressive chemotherapy regimens and reimbursement velocity for prophylactic platelet management protocols across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for oral small-molecule thrombopoietin receptor agonists would alter the outlook if bioavailability challenges resolve faster than projected. Forecasts reflect assumptions regarding FDA cardiovascular safety endpoint stability and EMA REACH environmental framework persistence. Material deviation in NMPA approval timelines or biosimilar litigation outcomes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Polymyalgia Rheumatica Treatment Market
Specialty Medicine
Chordoma Disease Therapeutics Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Low-Grade Glioma Therapeutics Market
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Immunoglobulin (Igg) Replacement Therapy Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Lamellar Ichthyosis Treatment Market
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Neuroscience Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Secondary Progressive Multiple Sclerosis (SPMS) Treatment Market
Specialty Medicine
Bartter Syndrome Treatment Market