
 Whipple's Disease Market | 2026-2036
Whipple's Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Whipple's Disease Market Analytics
North American pharmaceutical manufacturing capacity is tilting toward rare infectious disease therapeutics. Pfizer Inc. leverages its established antibiotic infrastructure to sustain supply chain reliability for Whipple's disease treatments. Roche Holding AG anchors diagnostic innovation through its molecular testing platforms. AbbVie Inc. differentiates via immunomodulator R&D programs targeting refractory cases.
Whipple's disease is a chronic systemic infection caused by Tropheryma whipplei, a Gram-positive actinobacterium characterized by PAS-positive macrophage infiltration of the intestinal lamina propria and periodic acid-Schiff staining confirmation in histopathology. The condition primarily serves infectious disease and gastroenterology practice by requiring prolonged combination antibiotic therapy to prevent neurological relapse and endocarditis. Antibiotics dominate current revenue pools due to mandatory year-long treatment courses, while Diagnostic Kits represent the fastest-expanding segment as PCR-based detection replaces slower histological methods. Hospitals capture the largest end-user share given the need for intravenous induction therapy and multidisciplinary management, whereas Research Institutions are gaining traction for host-pathogen interaction studies.
FDA's Qualified Infectious Disease Product incentives and EMA's orphan drug frameworks shape development economics by extending market exclusivity for novel Whipple's therapies. The WHO's inclusion of T. whipplei in its bacterial priority pathogen research agenda elevates diagnostic standardization requirements across member states. Stakeholders must monitor evolving molecular diagnostic reimbursement policies and antibiotic stewardship constraints that could alter prescribing patterns for this ultra-rare indication.
Market Dynamics
The transition from histopathological diagnosis to molecular PCR detection is restructuring clinical workflows and reimbursement patterns across infectious disease departments. FDA's Qualified Infectious Disease Product designation is accelerating antibiotic development timelines while diagnostic manufacturers compete to displace slower PAS-staining protocols.
Growth Catalysts
- QIDP Incentive Framework:FDA's Qualified Infectious Disease Product designation grants five additional years of market exclusivity for novel Whipple's therapies, stimulating antibiotic R&D investment.
- PCR Platform Adoption:Hospital laboratories are replacing PAS-staining with real-time PCR detection, cutting diagnostic confirmation from weeks to hours.
- WHO Priority Pathogen Status:The WHO's inclusion of T. whipplei in its bacterial priority research agenda is elevating diagnostic standardization requirements across member state health systems.
Market Restraints
- Ultra-Rare Prevalence:The extreme rarity of Whipple's disease limits commercial viability, forcing developers to rely entirely on orphan drug economics.
- Prolonged Treatment Burden:Mandatory twelve-month antibiotic courses create adherence challenges and elevate resistance risks for companion drugs.
- Specialist Concentration:Diagnostic and treatment expertise clusters in tertiary academic medical centers, restricting access in community hospital settings.
Strategic Opportunities
- Point-of-Care Molecular Testing:Portable PCR platforms could decentralize diagnosis from centralized labs to regional hospitals and infectious disease clinics.
- Immunomodulator Adjuncts:Refractory neurological cases create white space for host-directed therapies targeting macrophage dysfunction.
- EMA Orphan Framework:European orphan drug designation offers protocol assistance and fee reductions for pediatric indication extensions.
Industry Challenges
- Histopathology Skill Erosion:Declining PAS-staining proficiency among pathologists threatens confirmatory capacity as molecular methods dominate.
- Antibiotic Stewardship Constraints:Hospital antimicrobial committees are scrutinizing prolonged combination regimens, complicating protocol adherence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whipple's Disease Market |
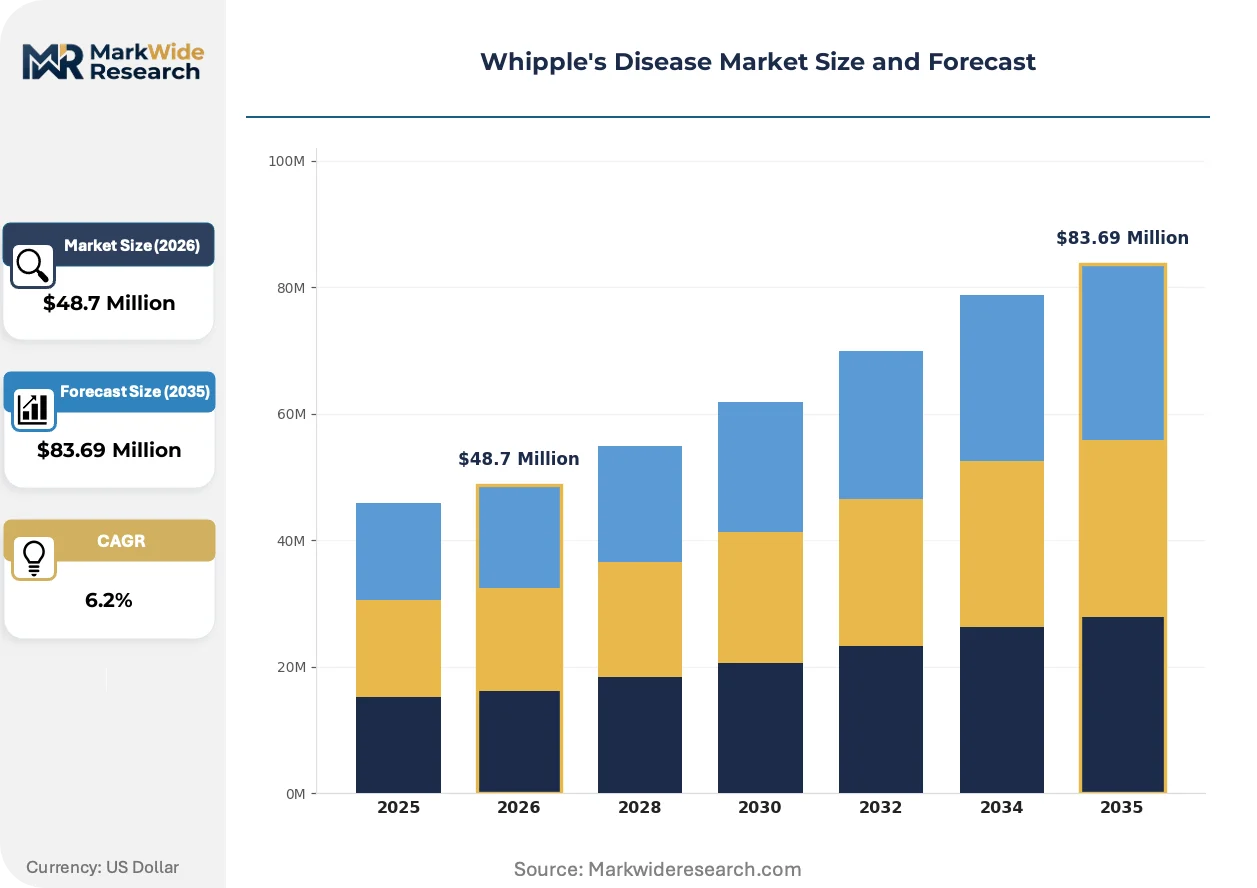
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $83.69 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Nutritional Supplements, Diagnostic Kits, Immunomodulators End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutions Delivery Mode: Oral, Intravenous, Subcutaneous, Intra-articular Application: Symptomatic Relief, Infection Control, Nutritional Management, Disease Prevention |
| Companies Covered | Roche Holding AG, Pfizer Inc., GlaxoSmithKline plc, Johnson & Johnson, Novartis AG, AstraZeneca PLC, Eli Lilly and Company, AbbVie Inc., Bristol Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whipple's Disease Market Evolving Landscape
Molecular diagnostics and host-pathogen interaction science are converging to reshape Whipple's disease management. Three developments are altering competitive positioning across the antibiotic and diagnostic segments.
Real-time PCR detection is collapsing the diagnostic timeline from histopathology's multi-week turnaround to same-day confirmation. Tertiary care infectious disease departments are adopting these platforms rapidly. This compression is eliminating the historical advantage of empiric treatment initiation and forcing antibiotic manufacturers to demonstrate superior CNS penetration earlier in clinical development.
EMA's orphan drug framework is extending data exclusivity periods for ultra-rare indications. European developers gain ten years of market protection versus standard eight-year terms. Small-cap antibiotic specialists are prioritizing EMA submissions to leverage this tailwind, while larger manufacturers focus QIDP pathways through FDA.
Multidisciplinary care coordination is replacing siloed gastroenterology management. Infectious disease specialists now lead treatment protocols in major academic centers. This behavioral shift is most visible in United States hospital systems, where bundled reimbursement for complex infections incentivizes centralized expertise over distributed care.
Whipple's Disease Market Segmentation
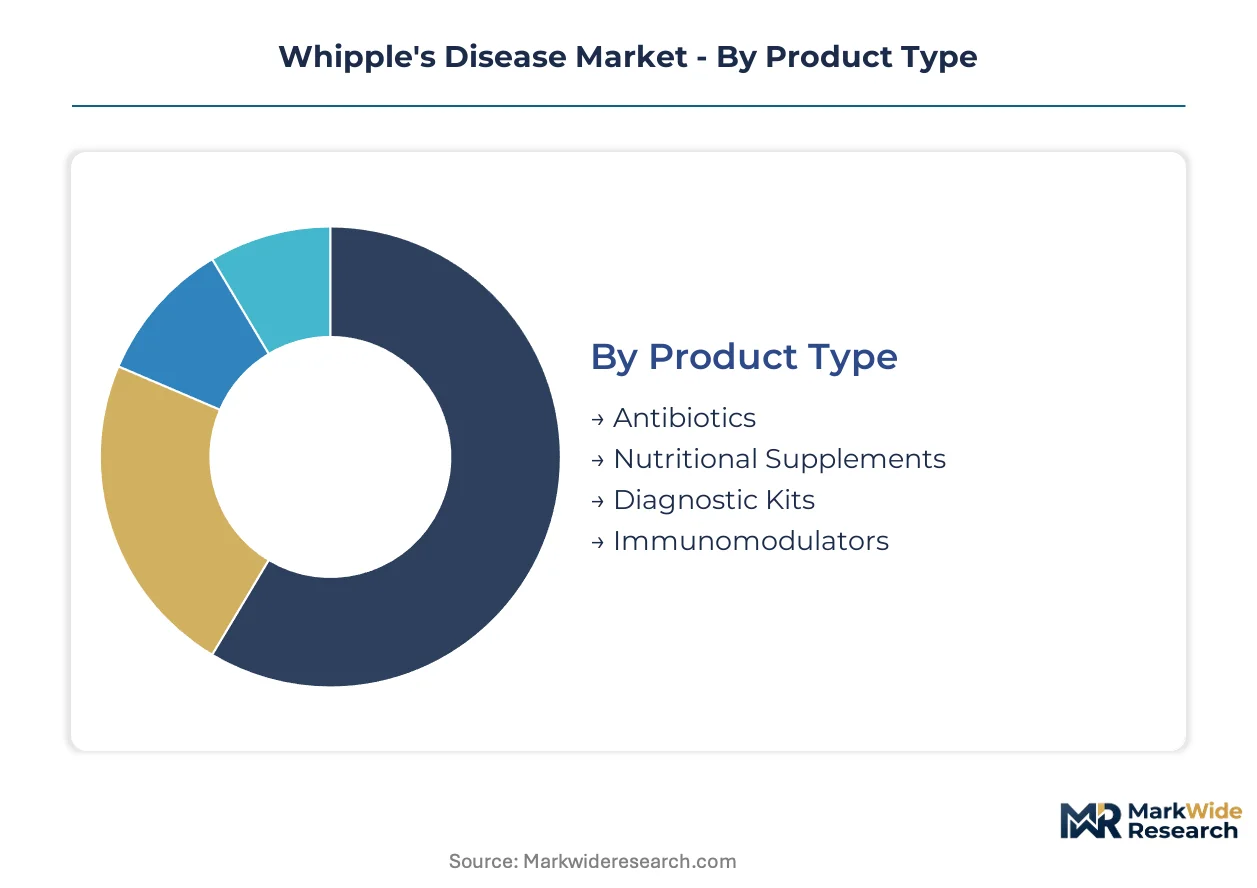
Whipple's disease management requires precise alignment between diagnostic modality, treatment intensity, and care setting. Segmentation reveals where twelve-month antibiotic protocols concentrate versus where point-of-care molecular testing is displacing centralized lab workflows.
Product Type:
Cycle times vary dramatically across this category, with diagnostic consumables turning over in days while immunomodulator development spans years.
- Antibiotics:Combination regimens of ceftriaxone followed by trimethoprim-sulfamethoxazole constitute the mandatory year-long treatment backbone. Demand concentrates in United States infectious disease departments where FDA's QIDP designation has sustained manufacturer commitment to chronic therapy supply.
- Diagnostic Kits:Real-time PCR platforms targeting Tropheryma whipplei 16S rRNA are collapsing confirmation timelines from weeks to hours. Academic medical centers in Germany and France are driving adoption fastest as EMA diagnostic reimbursement frameworks mature.
- Nutritional Supplements:Malabsorption correction via parenteral vitamin B12 and iron replacement accompanies antibiotic induction.
- Immunomodulators:Host-directed therapies for refractory neurological relapse remain investigational, with programs concentrated at Swiss and Dutch university hospitals.
Antibiotics dominate installed base. Diagnostic Kits are where expansion concentrates.
End User:
Cost tiers separate this category, with capital-intensive hospital infrastructure at one extreme and grant-funded research at the other.
- Hospitals:Tertiary academic centers manage complex Whipple's cases requiring intravenous induction and multidisciplinary coordination. United States hospital systems capture the highest procedure volumes where bundled reimbursement for rare infections incentivizes centralized expertise.
- Diagnostic Laboratories:Hospital-affiliated and reference labs process PCR confirmation and PAS-staining histopathology. Regional networks in Spain and Italy are consolidating testing volume as national health systems standardize molecular protocols.
- Clinics:Community infectious disease and gastroenterology practices handle stable maintenance-phase patients.
- Research Institutions:Host-pathogen interaction studies at Belgian and Austrian universities advance understanding of macrophage dysfunction in refractory cases.
Hospitals dominate installed base. Diagnostic Laboratories are where expansion concentrates.
Delivery Mode:
Application urgency dictates route selection, with CNS involvement demanding immediate intravenous access.
- Intravenous:Ceftriaxone induction penetrates the blood-brain barrier to prevent neurological relapse. United States emergency departments and infectious disease wards administer the highest volumes where rapid CNS coverage determines outcomes.
- Oral:Trimethoprim-sulfamethoxazole maintenance continues for twelve months following IV induction. Patient adherence programs at German and French outpatient clinics focus on this transition phase.
- Subcutaneous:Alternative access for patients with difficult venous anatomy.
- Intra-articular:Direct joint injection for isolated articular manifestations without systemic involvement.
Intravenous dominates installed base. Oral is where expansion concentrates.
Application:
Clinical objectives separate acute intervention from chronic management, with infection control commanding resource intensity.
- Infection Control:Eradication of Tropheryma whipplei from macrophage reservoirs requires prolonged combination therapy. Infectious disease specialists at Mayo Clinic, Johns Hopkins, and Cleveland Clinic anchor protocol development.
- Nutritional Management:Correcting malabsorption-induced deficiencies restores patient functional status. Gastroenterology departments at Charité Berlin and Karolinska Institute Stockholm integrate dietetic support.
- Symptomatic Relief:Addressing arthralgia, diarrhea, and weight loss pending definitive diagnosis.
- Disease Prevention:Prophylactic protocols for at-risk immunocompromised populations remain investigational.
Infection Control dominates installed base. Nutritional Management is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Antibiotic manufacturing for ultra-rare infectious diseases clusters in the United States and Western Europe. Diagnostic platform development concentrates in Germany and Switzerland where molecular testing infrastructure receives sustained public investment.
United States
FDA's Qualified Infectious Disease Product designation drives antibiotic development economics for Whipple's disease. Mayo Clinic in Rochester, Johns Hopkins in Baltimore, and Cleveland Clinic anchor specialized treatment protocol development. Hospital systems in Massachusetts and California capture the highest diagnostic volumes where bundled reimbursement incentivizes centralized infectious disease expertise.
Germany
Charité Berlin and University Hospital Heidelberg lead European adoption of real-time PCR detection platforms. EMA's orphan drug framework extends market exclusivity periods, stimulating small-cap antibiotic specialists to prioritize European submissions. The country's statutory health insurance system standardizes molecular diagnostic reimbursement across regional hospital networks.
Switzerland
Swissmedic's streamlined rare disease pathways accelerate diagnostic kit approvals for Tropheryma whipplei detection. University hospitals in Zurich and Geneva host the continent's largest host-pathogen interaction research programs for refractory neurological cases. Basel anchors pharmaceutical manufacturing infrastructure serving ultra-rare indication supply chains.
France
ANSM's early access programs for infectious disease diagnostics reduce time-to-market for novel PCR platforms. Parisian academic medical centers coordinate multidisciplinary Whipple's management protocols integrating gastroenterology and infectious disease departments. The national health system's rare disease reference networks standardize diagnostic pathways across regional hospital groups.
Whipple's Disease Market Competitive Landscape
Established pharmaceutical conglomerates and specialized diagnostic manufacturers split the market between antibiotic supply and molecular detection platforms. The structure tilts toward consolidated antibiotic production given manufacturing scale requirements, while diagnostic kits sustain more fragmented competition among platform specialists. Two strategic archetypes dominate: diversified pharmaceutical majors leveraging infectious disease infrastructure, and molecular diagnostics pure-plays targeting ultra-rare pathogen detection. Competitive moves concentrate on regulatory pathway optimization and academic medical center partnership networks.
Among diversified pharmaceutical majors, Pfizer Inc. and Roche Holding AG occupy anchor positions exemplifying the infrastructure-led archetype. Pfizer represents sustained antibiotic manufacturing commitment for prolonged combination regimens. Roche exemplifies diagnostic platform integration into infectious disease workflows. AbbVie Inc. sits within the immunomodulator development tier targeting refractory case adjunct therapies.
| Leading Market Players |
|---|
| Roche Holding AG |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Novartis AG |
| AstraZeneca PLC |
| Eli Lilly and Company |
| AbbVie Inc. |
| Bristol Myers Squibb Company |
| Others |
Value Network & Pricing Analysis
Undercapacity in European diagnostic kit manufacturing drives dual behavior: suppliers prioritize academic medical center contracts over community hospital orders, while buyers accept premium pricing for guaranteed PCR reagent supply. This utilization squeeze concentrates pricing power with Roche and specialized molecular platform manufacturers.
Pricing Analysis
FDA's QIDP designation dictates the pricing tier structure for Whipple's disease antibiotics, separating standard-of-care ceftriaxone from premium-positioned novel regimens with CNS penetration advantages. Price differentiation rests on clinical outcome guarantees and bundled hospital reimbursement rates. Cost compression in oral maintenance-phase trimethoprim-sulfamethoxazole is intensifying because of antimicrobial stewardship committee scrutiny. Community infectious disease clinics exhibit highest price sensitivity; tertiary academic centers prioritize efficacy over acquisition cost.
Supply Chain Analysis
Tariff exposure between Switzerland and Germany dominates supply chain risk for diagnostic platform components. Manufacturing concentrates in the United States, Germany, and Switzerland. Active pharmaceutical ingredient sourcing draws from India and Italy for antibiotic precursors. Single-source vulnerability threatens 16S rRNA primer production. Distribution runs through hospital-affiliated laboratories and specialized infectious disease distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Whipple's disease market rewards players who control scarce PCR assay development expertise and maintain relationships with the fifteen to twenty academic medical centers managing the majority of confirmed cases. Profitable participation requires bridging the gap between diagnostic innovation and prolonged antibiotic supply security.
For Market Incumbents: Build regulatory exclusivity moats through simultaneous FDA QIDP and EMA orphan pathway submissions. Secure sole-source contracts with Mayo Clinic, Johns Hopkins, and Cleveland Clinic infectious disease departments. Add manufacturing capacity in Basel or Heidelberg to reduce cross-border logistics exposure. Patent novel CNS-penetrant antibiotic formulations ahead of generic trimethoprim-sulfamethoxazole pressure. For New Entrants and Emerging Players: Establish a beachhead in point-of-care molecular testing for regional hospital networks outside major metropolitan academic centers. Target Spain and Italy where diagnostic laboratory consolidation creates procurement centralization opportunities. Partner with Swiss university hospitals for refractory neurological case immunomodulator trials. Leverage EMA protocol assistance for pediatric indication extensions as a differentiated regulatory angle. For Investors and Strategic Acquirers: Capital is best deployed toward small-cap antibiotic specialists with existing QIDP designations and European orphan drug submissions in progress. The five-to-ten year viability window favors developers who can demonstrate CNS relapse prevention superiority. Watch for FDA diagnostic reimbursement policy shifts affecting PCR platform adoption curves as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Simultaneous FDA QIDP and EMA orphan submissions extend exclusivity protection across both jurisdictions. |
| Hospital System Partnership | Exclusive supply agreements with Mayo Clinic and Johns Hopkins anchor volume and protocol influence. |
| Manufacturing Scale-Up | Basel-based capacity expansion reduces Swiss-German border friction for diagnostic kit distribution. |
| Platform Integration | PCR assay compatibility with Roche molecular diagnostics infrastructure accelerates hospital adoption. |
| Pipeline Diversification | Immunomodulator programs for refractory neurological cases address unmet need in ultra-rare relapse populations. |
Research Methodology
Cross-validation between infectious disease specialist interviews and FDA QIDP filing data anchors the qualitative findings. Primary fieldwork engaged drug development executives at antibiotic manufacturers, regulatory affairs leads navigating orphan pathways, hospital procurement managers at academic medical centers, and payer access specialists at major United States insurers. Secondary sources included FDA 510(k) clearances for diagnostic platforms, EMA orphan drug designation registers, ClinicalTrials.gov entries for refractory case studies, and hospital procurement databases tracking PCR reagent purchasing patterns. Bottom-up demand modeling and top-down epidemiological prevalence estimates were reconciled through iterative triangulation.
Calibration against historical antibiotic pricing trajectories and diagnostic platform adoption curves in comparable ultra-rare infectious diseases refined the analytical framework. Segmentation dimensions modeled include product type, end user category, delivery mode, and application objective across the projection horizon. CAGRs were derived from epidemiological incidence projections, treatment protocol adherence assumptions, and molecular diagnostic substitution rates for PAS-staining methods. Industry-specific inputs incorporated WHO bacterial priority pathogen research funding allocations and EMA diagnostic reimbursement framework maturity by member state.
Stress conditions across antibiotic resistance emergence timelines, PCR platform price erosion curves, and hospital antimicrobial stewardship enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway timelines and academic medical center consolidation trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Chronic Idiopathic Constipation Treatment Market
Specialty Medicine
Dravet Syndrome Treatment Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Piriformis Syndrome Market
Specialty Medicine
Polychondritis Disease Treatment Market
Specialty Medicine
Desmoid Tumor Market
Specialty Medicine
North America Cancer Therapy Market
Specialty Medicine
Short Bowel Syndrome Market
Specialty Medicine
Sports Medicine Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Global Melanoma Therapeutics Market
Specialty Medicine
Disruptive Behavior Disorder (DBD) Treatment Market
Specialty Medicine
Global Cough Hypersensitivity Syndrome Treatment Market