
 Europe Pediatric Neurology Device Market | 2026-2036
Europe Pediatric Neurology Device Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pediatric Neurology Device Market Foresight
Hospital procurement channels for pediatric neurology equipment is narrowing as consolidated purchasing alliances gain leverage across European health systems. Medtronic plc leverages its deep neurostimulation portfolio to sustain long-term service contracts with major pediatric centers. Siemens Healthineers anchors the imaging segment through high-field MRI configurations tailored to neonatal and infant protocols. Natus Medical competes on specialized EEG platforms designed for ambulatory pediatric monitoring.
Europe pediatric neurology devices comprise electrophysiological, neurostimulation, imaging, and intracranial pressure monitoring systems engineered for patients from neonates through adolescents, typically featuring scaled-down sensor arrays, modified anesthesia protocols, and software algorithms adjusted for developing brain morphology. EEG Devices dominate procedural volumes due to routine epilepsy diagnostics, while Neurostimulation Devices capture disproportionate value from implantable vagus nerve and responsive neurostimulation systems for drug-resistant seizure populations. Monitoring Systems extend into hydrocephalus shunt surveillance where programmable valve technologies reduce revision surgeries.
The EU Medical Device Regulation and EMA pediatric investigation plans impose escalating clinical trial obligations for novel neurology devices in children under eighteen. CE marking under MDR now demands pediatric-specific benefit-risk documentation that many legacy manufacturers must reconstruct. Germany's BfArM and France's ANSM coordinate national early access pathways that accelerate reimbursement for breakthrough pediatric neurotechnologies. Stakeholders must monitor how national health technology assessment bodies weight quality-of-life endpoints against procedural cost thresholds in pediatric neurological interventions.
Market Dynamics
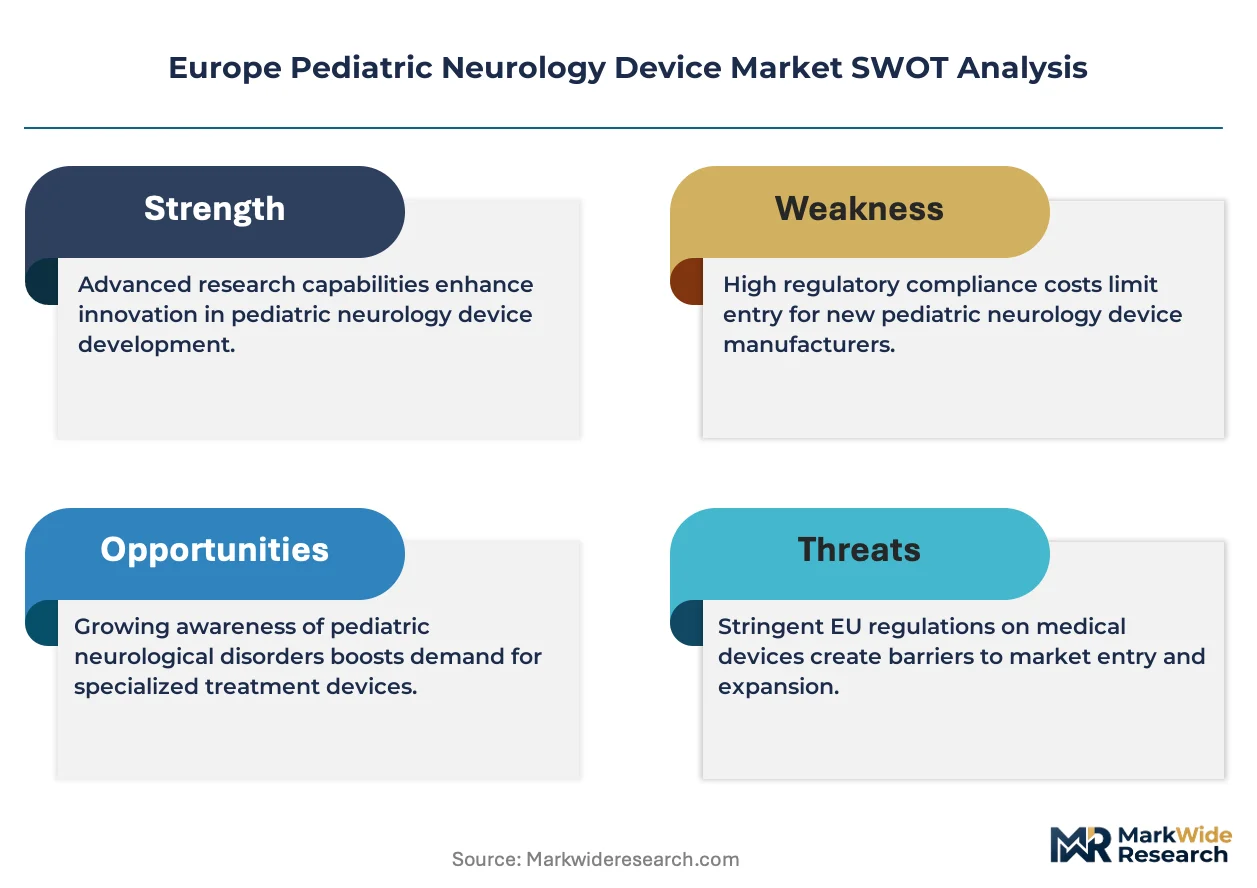
The EU Medical Device Regulation's pediatric-specific clinical evidence mandates are compressing product development timelines while elevating barriers for legacy device portfolios lacking childhood trial data.
Growth Catalysts
- EMA Pediatric Investigation Plans:Regulatory mandates for pediatric study data create dedicated pathways for neurology devices, accelerating market access for compliant manufacturers.
- Epilepsy surgery referral networks:France's centralized pediatric neurosurgery hubs generate concentrated demand for intraoperative monitoring and neurostimulation systems.
- Neonatal MRI protocol standardization:Germany's university hospital clusters drive procurement of high-field imaging configured for infant neurodevelopmental assessment.
Market Restraints
- Neonatal sensor fabrication:Precision manufacturing of scaled-down EEG electrode arrays concentrates among specialized European suppliers, creating input bottlenecks.
- MDR transition compliance costs:Reconstruction of pediatric benefit-risk documentation for legacy CE-marked devices drains R&D resources from innovation pipelines.
- Long-implant neurostimulation systems:Extended device lifecycles in pediatric vagus nerve stimulation reduce replacement revenue and procedural volumes.
Strategic Opportunities
- Poland's pediatric neurology capacity:Underserved regional referral networks present first-mover potential for ambulatory EEG and remote monitoring platforms.
- Responsive neurostimulation AI integration:Convergence of seizure detection algorithms with closed-loop stimulation protocols opens premium pricing tiers for drug-resistant epilepsy.
- France's ANSM early access pathways:National reimbursement acceleration for breakthrough pediatric neurotechnologies reduces commercialization lag for novel implants.
Industry Challenges
- Pediatric neurophysiologist scarcity:Specialized training pipelines for intraoperative neuromonitoring technologists lag device deployment rates across European centers.
- Legacy hospital IT integration:EEG and neurostimulation data streams require custom middleware to interface with established electronic health record architectures.
- Multi-site pediatric trial execution:Recruitment coordination across dispersed national healthcare systems extends MDR-mandated clinical study durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pediatric Neurology Device Market |
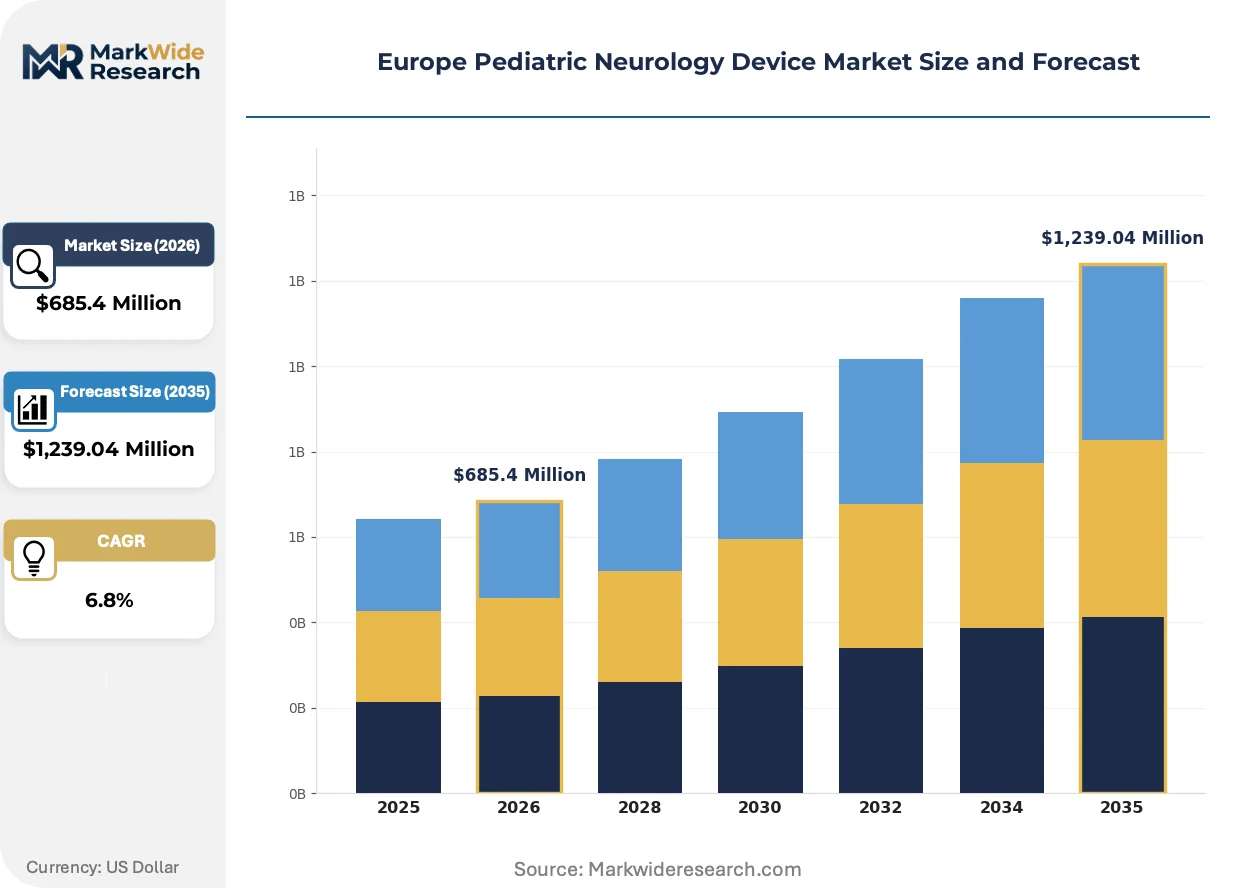
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: EEG Devices, Neurostimulation Devices, Monitoring Systems, Imaging Devices Indication: Epilepsy, Cerebral Palsy, Hydrocephalus, Neurogenetic Disorders End User: Pediatric Hospitals, Clinics, Rehabilitation Centers, Research Facilities Distribution Channel: Direct Sales, Distributors, Online Sales, Third-Party Retailers |
| Companies Covered | Johnson & Johnson, Integra LifeSciences, Medtronic plc, Nihon Kohden, Natus Medical, Abbott Laboratories, LivaNova PLC, Siemens Healthineers, Boston Scientific, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pediatric Neurology Device Market Shifts & Advancements
Non-invasive neuromodulation platforms and AI-augmented diagnostic algorithms are compressing the traditional hierarchy between electrophysiological monitoring and interventional neurostimation in pediatric care pathways.
Magnetoencephalography systems configured for infant head morphology are rendering obsolete conventional scalp EEG for pre-surgical epilepsy localization in high-volume German and French centers. Pediatric neurosurgery departments at Charité Berlin and Hôpital Necker-Enfants Malades have adopted cryogenic sensor arrays for source localization without patient sedation. The technology is compressing diagnostic timelines from multi-day inpatient video-EEG monitoring to single-ambulatory-visit protocols.
EMA's tightened pediatric investigation plan enforcement under MDR Article 59 is mandating device-specific childhood trial cohorts rather than extrapolated adult data. Manufacturers must now recruit neonatal through adolescent strata for novel neurostimulation implants. German BfArM and French ANSM have coordinated parallel scientific advice procedures to reduce redundant regulatory submissions across the two largest national markets.
Hospital purchasing alliances in the UK and Netherlands are consolidating procurement decisions for high-value neurodiagnostic capital equipment. NHS Supply Chain and regional Dutch hospital cooperatives now negotiate multi-year EEG and MRI service contracts as bundled packages. France's pediatric neurology referral networks resist this concentration, maintaining independent procurement authority at university hospital level.
Europe Pediatric Neurology Device Market Segmentation
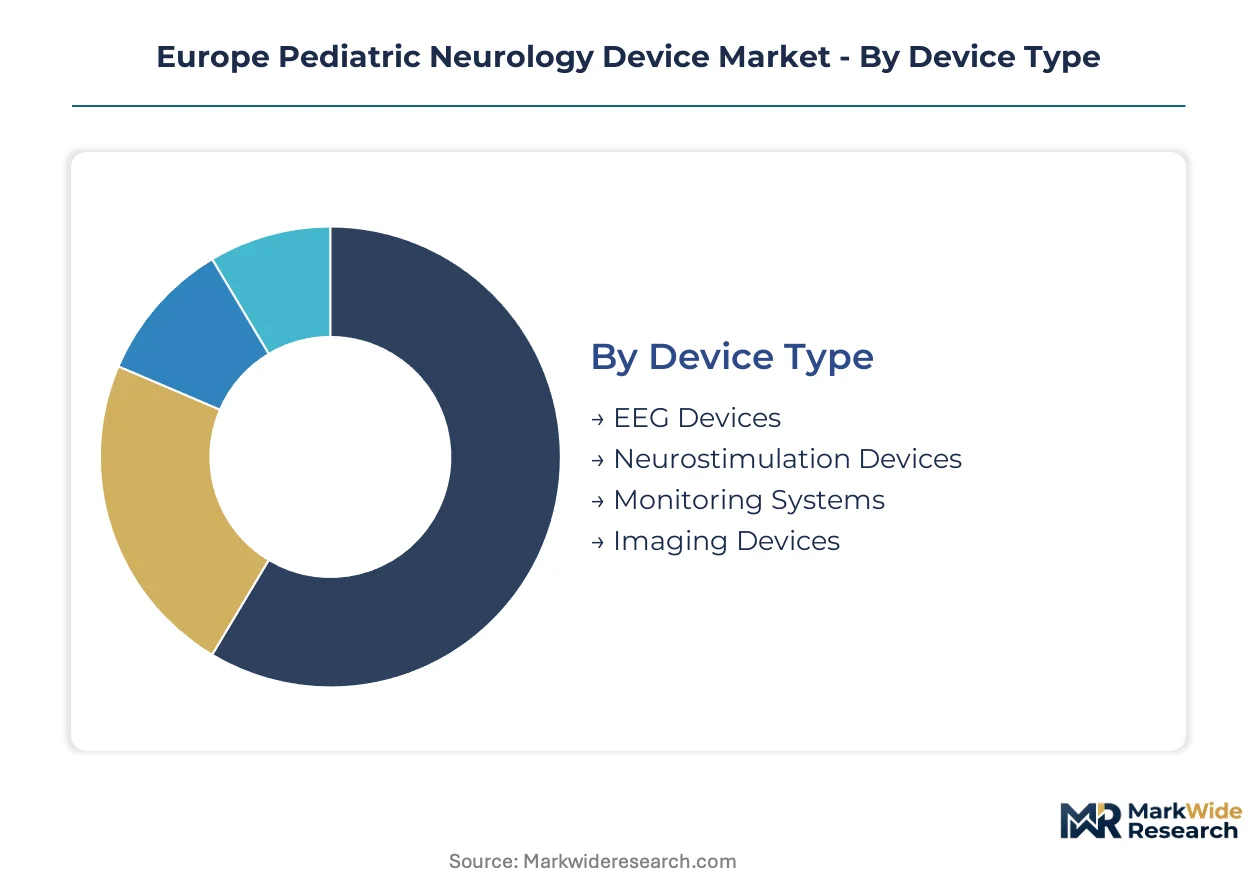
Device categorization in European pediatric neurology reveals distinct procurement patterns across acute care, ambulatory monitoring, and surgical intervention pathways. Each segment carries unique regulatory burdens under MDR and EMA pediatric investigation requirements.
Device Type:
Cost tier differentiation separates capital-intensive imaging platforms from disposable electrode arrays and implantable pulse generators.
- EEG Devices:Scalp electrode arrays and digital acquisition systems configured for neonatal through adolescent head circumferences. Demand concentrates in France's pediatric neurology referral networks where ambulatory monitoring protocols reduce inpatient bed utilization.
- Neurostimulation Devices:Implantable vagus nerve stimulators and responsive neurostimulation systems with pediatric-specific electrode leads and battery capacities. Germany's university hospital clusters drive procurement for drug-resistant epilepsy surgical candidates, with Charité Berlin and Heidelberg University Hospital anchoring regional implant volumes.
- Monitoring Systems:Intracranial pressure sensors and programmable shunt valves for hydrocephalus surveillance.
- Imaging Devices:High-field MRI configurations with neonatal head coils and modified anesthesia protocols.
EEG Devices command the established base. The steepest expansion runs through Neurostimulation Devices.
Indication:
Application severity determines reimbursement tiering across national health technology assessment frameworks.
- Epilepsy:Diagnostic and interventional device deployment spanning scalp EEG, invasive monitoring, and neurostimulation implantation. France's centralized pediatric neurosurgery hubs generate concentrated demand for intraoperative monitoring systems, with EMA pediatric investigation plans mandating device-specific childhood trial cohorts.
- Cerebral Palsy:Movement disorder assessment through gait analysis integration with neurophysiological monitoring.
- Hydrocephalus:Shunt-dependent populations requiring programmable valve technologies and intracranial pressure telemetry.
- Neurogenetic Disorders:Rare disease diagnostics driving specialized EEG phenotyping and neuroimaging protocols.
Epilepsy anchors the procedural volume base. The steepest clinical trial investment flows into Neurogenetic Disorders.
End User:
Customer type dictates service contract complexity and regulatory documentation requirements.
- Pediatric Hospitals:Tertiary referral centers with comprehensive neurodiagnostic suites and neurosurgical capabilities. Germany's university hospital clusters and France's pediatric neurology networks concentrate high-value capital procurement, with bundled multi-year service agreements replacing transactional equipment purchases.
- Clinics:Ambulatory EEG and botulinum toxin administration for movement disorders.
- Rehabilitation Centers:Long-term neurostimulation programming and functional electrical stimulation protocols.
- Research Facilities:Magnetoencephalography and advanced neuroimaging for pre-surgical epilepsy localization.
Pediatric Hospitals command the capital equipment base. The steepest connectivity investment runs through Research Facilities.
Distribution Channel:
Supply concentration shapes margin structure and customer relationship intensity across the region.
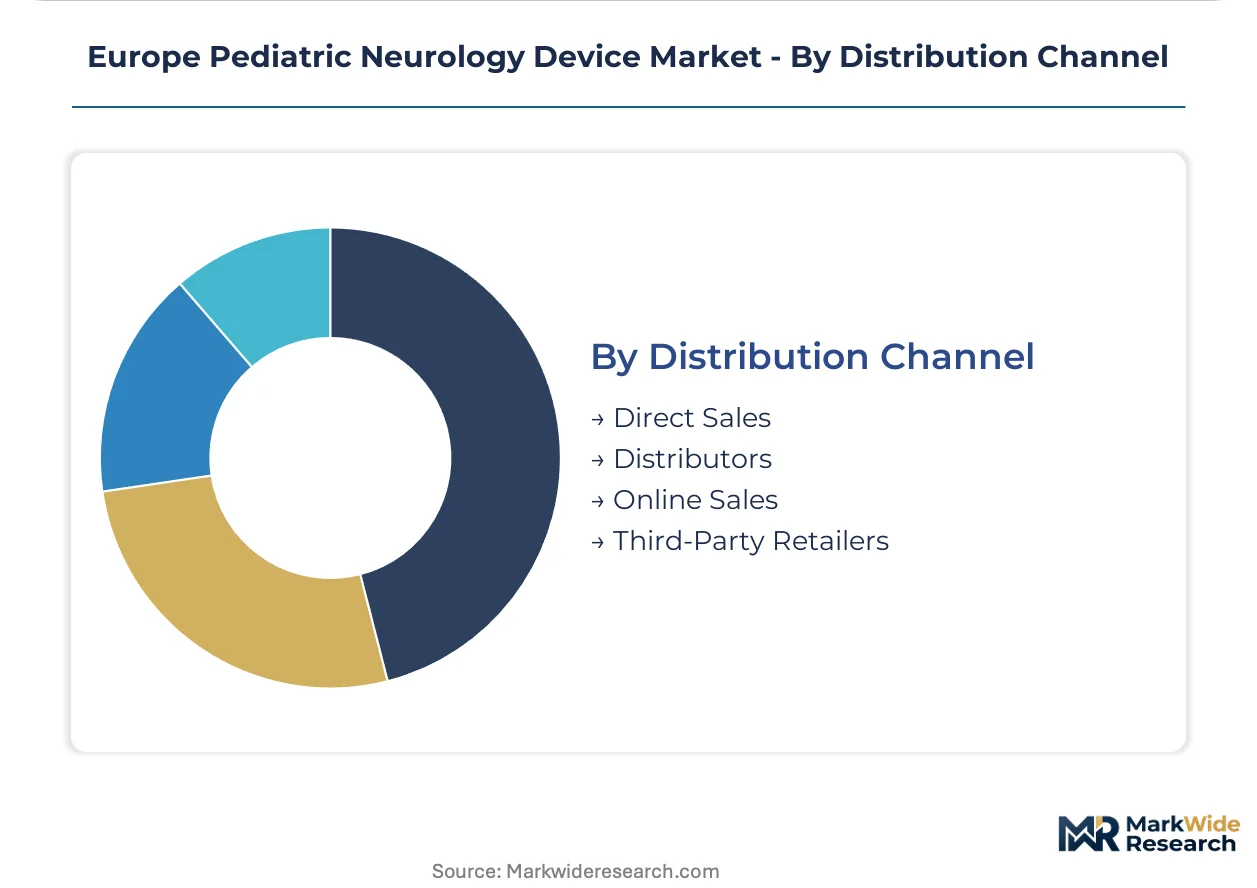
- Direct Sales:Manufacturer field teams negotiating enterprise contracts with consolidated purchasing alliances. NHS Supply Chain and regional Dutch hospital cooperatives now bundle EEG and MRI service agreements through direct manufacturer relationships, compressing intermediary margins.
- Distributors:Regional specialists handling installation, training, and maintenance for mid-tier hospitals.
- Online Sales:Consumables and replacement electrodes through procurement platforms.
- Third-Party Retailers:Limited to home-use ambulatory monitoring accessories.
Direct Sales commands the high-value contract base. The steepest channel expansion runs through Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium pricing leverage for high-field pediatric MRI configurations, while Poland's underserved referral networks absorb mid-tier EEG platforms at compressed margins. This asymmetry shapes manufacturer geographic prioritization across the continent.
Germany
University hospital clusters in Berlin and Heidelberg drive demand for intraoperative neuromonitoring and responsive neurostimulation systems. BfArM coordinates with France's ANSM on parallel scientific advice procedures to accelerate pediatric device approvals. Charité Berlin and Heidelberg University Hospital anchor regional implant volumes for drug-resistant epilepsy surgical candidates.
France
Centralized pediatric neurosurgery hubs generate concentrated procurement of magnetoencephalography systems and invasive monitoring equipment. ANSM early access pathways compress reimbursement timelines for breakthrough neurotechnologies. Hôpital Necker-Enfants Malades in Paris has adopted cryogenic sensor arrays for pre-surgical epilepsy localization without patient sedation.
United Kingdom
NHS Supply Chain consolidates purchasing decisions for neurodiagnostic capital equipment into bundled multi-year service contracts. NICE health technology assessments weight quality-of-life endpoints against procedural cost thresholds for pediatric neurological interventions. London's Great Ormond Street Hospital maintains independent procurement authority for specialized neonatal EEG configurations.
Poland
Underserved regional referral networks present first-mover opportunities for ambulatory EEG and remote monitoring platforms at price points below Western European benchmarks. The national health fund's reimbursement catalog excludes several premium neurostimulation categories, limiting implantable device penetration. Kraków and Warsaw pediatric centers are expanding neurodiagnostic capacity to reduce outbound referrals to German clinics.
Netherlands
Regional hospital cooperatives negotiate bundled EEG and MRI service agreements through direct manufacturer relationships, compressing intermediary distributor margins. The Dutch Healthcare Authority enforces outcome-based procurement criteria for pediatric neurology capital investments. University Medical Center Utrecht leads adoption of AI-augmented seizure detection algorithms integrated with ambulatory monitoring platforms.
Europe Pediatric Neurology Device Market Competitive Landscape
Full-spectrum neurotechnology conglomerates and specialized pediatric diagnostic manufacturers split the market into distinct capability tiers. The vendor base concentrates around imaging modality leaders, implantable neurostimulation specialists, and electrophysiology platform developers. Three strategic archetypes dominate: diversified medtech conglomerates with deep neuro portfolios, pure-play neurology device specialists, and imaging equipment manufacturers with pediatric protocol expertise. Competitive positioning hinges on M&A activity to acquire pediatric-specific regulatory dossiers and long-term service contract capture through bundled equipment-maintenance offerings.
Within the diversified conglomerate tier, Medtronic plc and Johnson & Johnson occupy positions anchored by implantable neurostimulation portfolios and deep service relationships with major European pediatric centers. Siemens Healthineers exemplifies the imaging-centric archetype, while Natus Medical represents specialized electrophysiology platform development. These three entities illustrate how regulatory compliance scale and pediatric-specific clinical evidence libraries function as defensive moats under EMA and MDR frameworks.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Integra LifeSciences |
| Medtronic plc |
| Nihon Kohden |
| Natus Medical |
| Abbott Laboratories |
| LivaNova PLC |
| Siemens Healthineers |
| Boston Scientific |
| Others |
Supply & Pricing Matrix
Undercapacity in precision neonatal sensor fabrication across specialized European suppliers is compressing margins for mid-tier EEG device manufacturers while amplifying pricing leverage for integrated neurostimulation conglomerates with captive component supply. German university hospital clusters and French pediatric neurology networks absorb these cost differentials through bundled multi-year service contracts that obscure unit-level pricing transparency.
Pricing Analysis
The customization-premium spread between configured-to-order responsive neurostimulation systems and standard vagus nerve stimulators spans three-tier pricing structure across premium, standard, and economy levels, with premium tiers capturing value from AI-augmented seizure detection algorithms and closed-loop protocols. Price differentiation rests on CE marking tier under MDR Article 59 and volume scale through consolidated NHS Supply Chain procurement. Cost compression in standard EEG electrode arrays is intensifying because Polish and Dutch hospital cooperatives are consolidating purchasing decisions into outcome-based frameworks. Pediatric hospitals in Germany and France exhibit lowest price sensitivity due to dedicated neurosurgery budgets, while Poland's regional referral networks face strict national health fund reimbursement ceilings.
Supply Chain Analysis
Tariff exposure between Switzerland and the EU dominates supply chain risk planning for cryogenic sensor arrays used in magnetoencephalography systems deployed at Charité Berlin and Hôpital Necker-Enfants Malades. Geographic supply concentration centers on Germany for high-field MRI configurations, Ireland for neurostimulation pulse generator assembly, and Switzerland for precision sensor fabrication. Raw material dependencies draw from rare earth elements for cryogenic sensors, biocompatible alloys for implantable leads, and specialized polymers for neonatal-scaled electrode arrays. Single-source vulnerability in cryogenic sensor production creates bottleneck exposure. Distribution runs through direct manufacturer field teams for capital equipment and regional distributors for consumables and replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe pediatric neurology device market rewards manufacturers possessing pediatric-specific MDR clinical evidence libraries, a capability gap that fragments competitive tiers between conglomerates with reconstructed legacy dossiers and emerging specialists building de novo childhood trial portfolios from EMA pediatric investigation plans.
For Market Incumbents: Harden regulatory moats by accelerating parallel scientific advice procedures with BfArM and ANSM to preempt competitor dossier submissions, while consolidating backward integration into precision neonatal sensor fabrication to neutralize input bottlenecks threatening mid-tier EEG margins. The priority defensive lever is locking multi-year service contracts with NHS Supply Chain and Dutch hospital cooperatives before procurement alliances expand bundled negotiation mandates. For New Entrants and Emerging Players: Poland's underserved regional referral networks present first-mover positioning for ambulatory EEG platforms with remote monitoring capabilities at price points below German and French benchmarks. The most penetrable segment is hydrocephalus shunt surveillance where programmable valve technologies face limited incumbent loyalty. The recommended go-to-market angle is partnering with Kraków and Warsaw pediatric centers expanding neurodiagnostic capacity to capture outbound referral reduction budgets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across responsive neurostimulation AI integration sub-segments as algorithm development and closed-loop hardware convergence demand sustained R&D commitment. Long-term viability over the projection horizon favors acquisition targets possessing completed EMA pediatric investigation plans with neonatal through adolescent cohort data. The signal to watch is ANSM early access pathway designation frequency as inflection indicator for reimbursement acceleration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Pediatric Dossier Reconstruction | BfArM and ANSM parallel submissions compress approval timelines for legacy device portfolios. |
| AI-Companion Software Development | Seizure detection algorithms integrated with responsive neurostimulation command premium pricing tiers. |
| Hospital System Partnership | Charité Berlin and Heidelberg University Hospital anchor regional implant volumes for drug-resistant epilepsy. |
| Reimbursement Strategy | NICE quality-of-life endpoint weighting determines cost threshold acceptance for pediatric interventions. |
| CE Marking Pathway | Article 59 pediatric-specific benefit-risk documentation mandates separate childhood trial cohorts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA pediatric investigation plan databases, MDR CE marking registries, and hospital procurement contract disclosures, combining interviews with pediatric neurosurgeons, biomedical engineers, GPO contracts managers, and regulatory affairs leads with validation through BfArM and ANSM approval documentation. Bottom-up demand modeling from individual hospital neurodiagnostic capital budgets triangulates against top-down market sizing from national health technology assessment frameworks.
Forecast inputs include device-specific procedural volumes across EEG, neurostimulation, and imaging modalities segmented by indication severity, end-user facility tier, and distribution channel concentration, with CAGRs derived from regression analysis against historical reimbursement catalog updates and procurement alliance formation timelines. Modeled dimensions span device type, indication category, end-user archetype, and geographic regulatory cluster, incorporating neonatal MRI protocol standardization velocity and EMA pediatric investigation plan enforcement intensity as industry-specific forecast inputs.
Practitioners should monitor MDR transition compliance cost trajectories and EMA pediatric cohort recruitment timelines for early signals of forecast revision. Assumptions underlying projections reflect current reimbursement tiering stability and procurement alliance consolidation momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Grand Mal Seizure Treatment Market
Neurology
Neurological Biomarkers Market
Neurology
Central Nervous System (CNS) Therapeutics Market
Neurology
Neurocutaneous Disorders Market
Neurology
South Korea Neurology Devices Market
Neurology
North America Neurology Monitoring Market
Neurology
Nerve Repair Market
Neurology
Global Neurovascular Embolization Devices (Neurology) Market
Neurology
CNS Treatment and Therapy Market
Neurology
Chronic Brain Damage Management Market
Neurology
Status Epilepticus Treatment Market
Neurology
Neurology Services Market
Neurology
Arachnoiditis Treatment Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Mexico Neurology Devices Market
Neurology
Parkinsons Disease Therapeutics Market