
 Epidermal Nevus Syndrome Market | 2026-2036
Epidermal Nevus Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Epidermal Nevus Syndrome Market Analysis
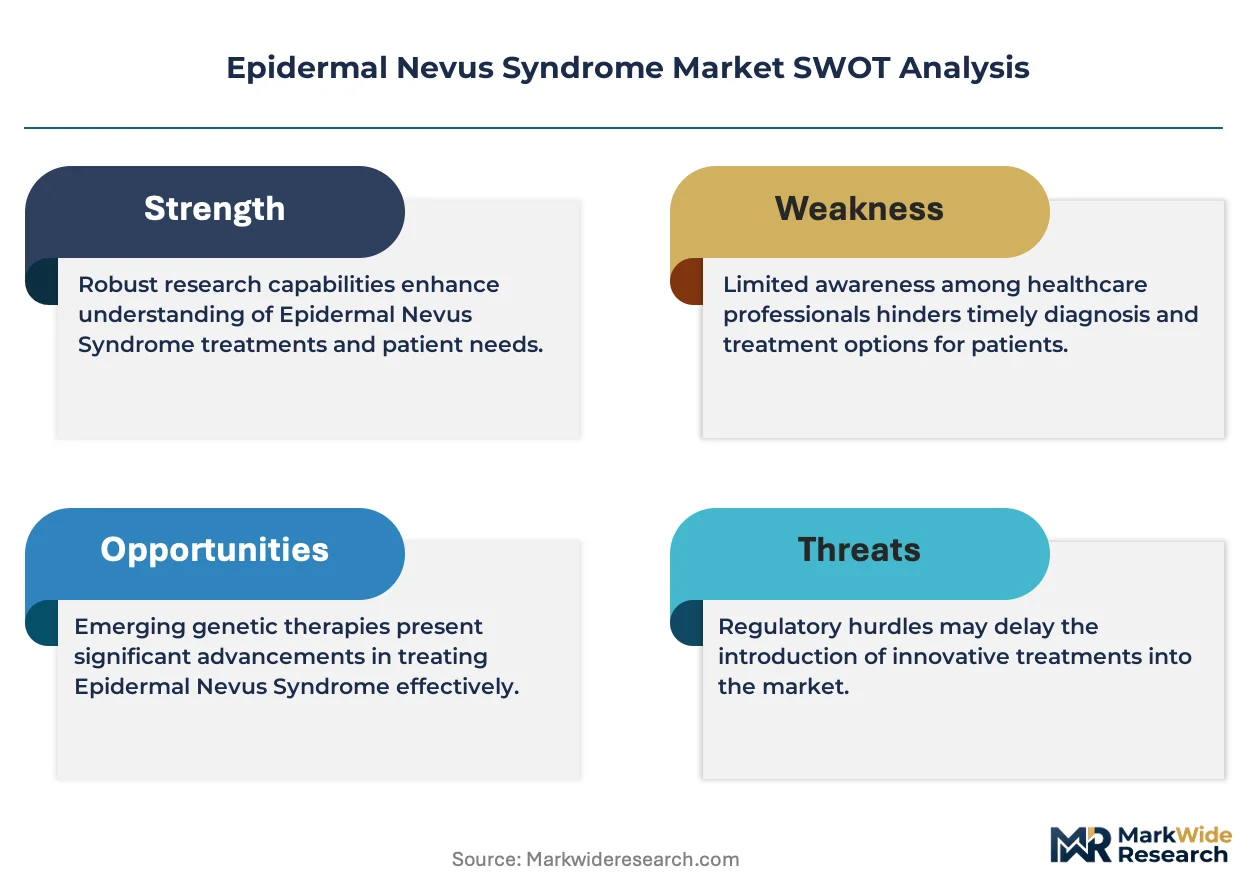
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape into qualified and non-qualified suppliers. GSK Plc. leverages its rare disease portfolio to sustain clinical trial momentum in dermatology therapeutics. Bayer AG anchors its position through integrated pharmaceutical development spanning topical and systemic modalities. Siemens Healthcare GmbH competes on diagnostic imaging systems that identify neurological comorbidities in affected patients.
Epidermal Nevus Syndrome comprises a group of congenital disorders characterized by hamartomatous epidermal proliferations, often presenting with keratinocytic or sebaceous nevi accompanied by extracutaneous manifestations including skeletal, neurological, and ocular abnormalities. The condition serves primary clinical purposes in early dermatological intervention, multidisciplinary monitoring for malignant transformation, and functional rehabilitation of associated orthopedic or neurological deficits. Laser Therapies command premium positioning within the product type architecture due to precision targeting of localized lesions with reduced scarring profiles. Pediatric end users represent the fastest-expanding demand node as early intervention protocols gain institutional traction across specialized care networks.
FDA orphan drug incentives and EMA rare disease designations shape therapeutic investment thresholds by compressing development timelines and extending market exclusivity windows for qualifying sponsors. The country's national pharmaceutical regulator in Japan, PMDA, imposes distinct clinical evidence requirements that filter which developers can access the Asia-Pacific's second-largest dermatology market. Stakeholders must monitor evolving payer policies for combination therapy reimbursement as treatment protocols integrate surgical, pharmaceutical, and rehabilitative interventions across care continuums.
Market Dynamics
FDA orphan drug incentives are compressing development timelines for rare disease therapeutics, while pediatric dermatology protocols expand multidisciplinary care coordination across specialized centers.
Growth Catalysts
- EMA Rare Disease Framework:Extended market exclusivity windows incentivize European pharmaceutical investment in dermatology therapeutics.
- Pediatric end-use expansion:Early intervention protocols at specialized care networks accelerate treatment initiation for congenital presentations.
- Laser precision targeting:Reduced scarring profiles drive adoption in localized lesion management across academic medical centers.
Market Restraints
- Supply concentration in specialized equipment:Diagnostic imaging systems for neurological comorbidities rely on limited qualified suppliers with ISO 13485 certification.
- PMDA evidence requirements:Japan's distinct clinical thresholds filter developer access to the Asia-Pacific dermatology market.
- Combination therapy reimbursement friction:Payer policies lag behind integrated surgical-pharmaceutical-rehabilitative protocols.
Strategic Opportunities
- Underpenetrated German market:Multidisciplinary center coordination remains below optimal density for rare congenital disorder management.
- Technology convergence:Diagnostic imaging integration with laser therapy platforms enables real-time lesion monitoring.
- Telemedicine channel expansion:Remote consultation protocols extend specialist access to geographically dispersed pediatric populations.
Industry Challenges
- Pediatric dermatology specialist scarcity:Training pipeline gaps constrain workforce expansion at academic medical centers.
- ISO 13485 certification timelines:Medical device quality management compliance extends supplier qualification cycles.
- Multidisciplinary care integration:Orthopedic, neurological, and dermatological service coordination creates administrative complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epidermal Nevus Syndrome Market |
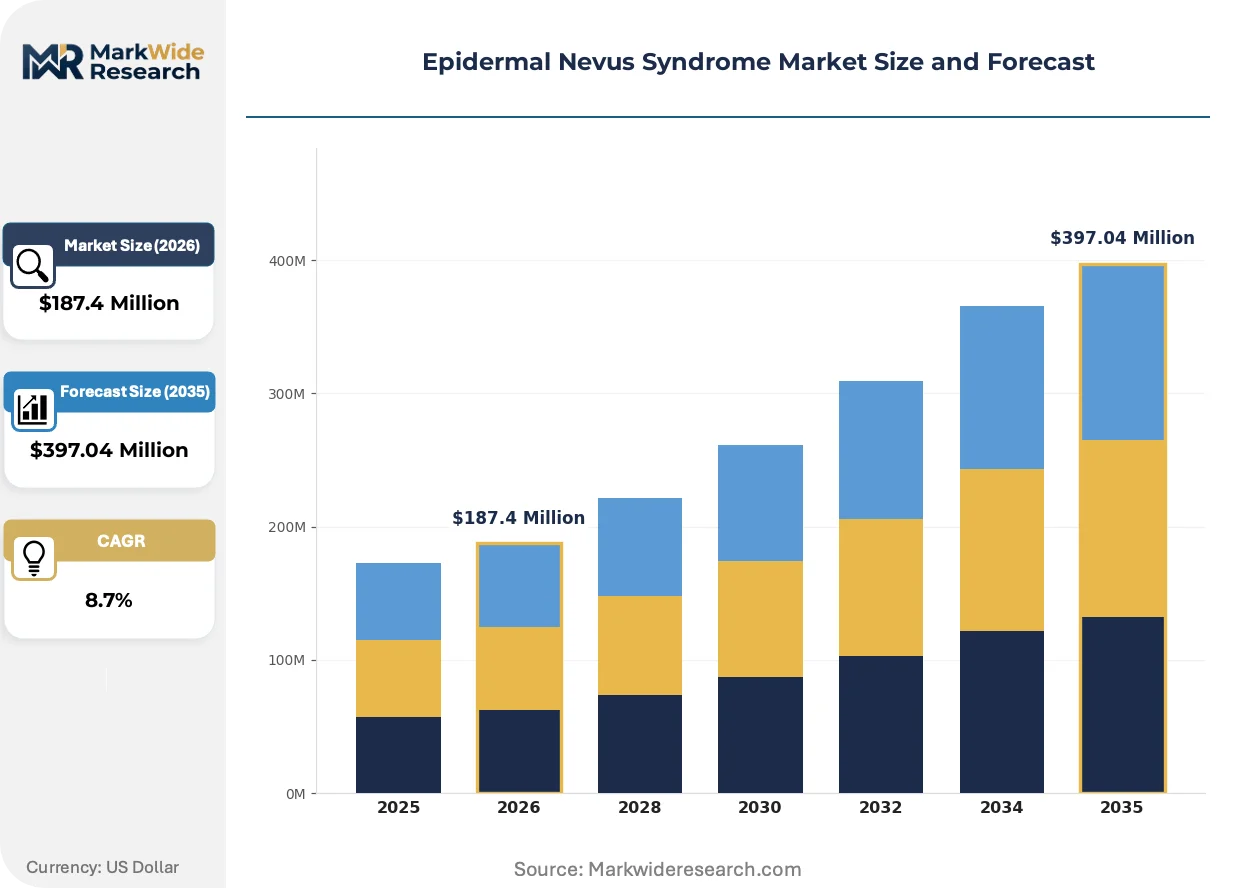
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Surgical Options, Laser Therapies, Symptomatic Treatments End User: Pediatrics, Dermatology Clinics, Hospitals, Cosmetic Centers Therapy Area: Dermatology, Oncology, Pain Management, Rehabilitation Delivery Mode: Topical, Injectable, Oral, Surgical |
| Companies Covered | GSK Plc., Bayer AG, Hologic Inc., Shanghai Fosun Pharmaceutical Group Co., Ltd., Zimmer Biomet, Stryker Corporation, Koninklijke Philips N.V., General Electric, Siemens Healthcare GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epidermal Nevus Syndrome Market Emerging Trajectories
Precision diagnostic platforms and regulatory incentive structures are reshaping competitive positioning in rare congenital disorder management, while care delivery models pivot toward integrated multidisciplinary protocols.
Fractional laser technology is fragmenting treatment protocols for keratinocytic nevi by enabling staged lesion reduction with preserved tissue architecture. Academic pediatric dermatology departments adopt these systems at accelerating replacement cycles. The technology is fragmenting historical surgical excision volumes into outpatient laser sequences.
REACH compliance requirements for medical device materials are restricting substrate selections in dermatology equipment manufacturing. European manufacturers reformulate device coatings and housing polymers to satisfy substance restriction thresholds. Laser therapy platforms face particular scrutiny for heavy metal content in optical components.
Certification-driven procurement preferences are elevating ISO 13485-qualified suppliers in institutional purchasing decisions. Hospital procurement departments now mandate quality management documentation prior to vendor onboarding. This shift concentrates supplier relationships in the United States and Germany where certification density remains highest.
Epidermal Nevus Syndrome Market Segmentation
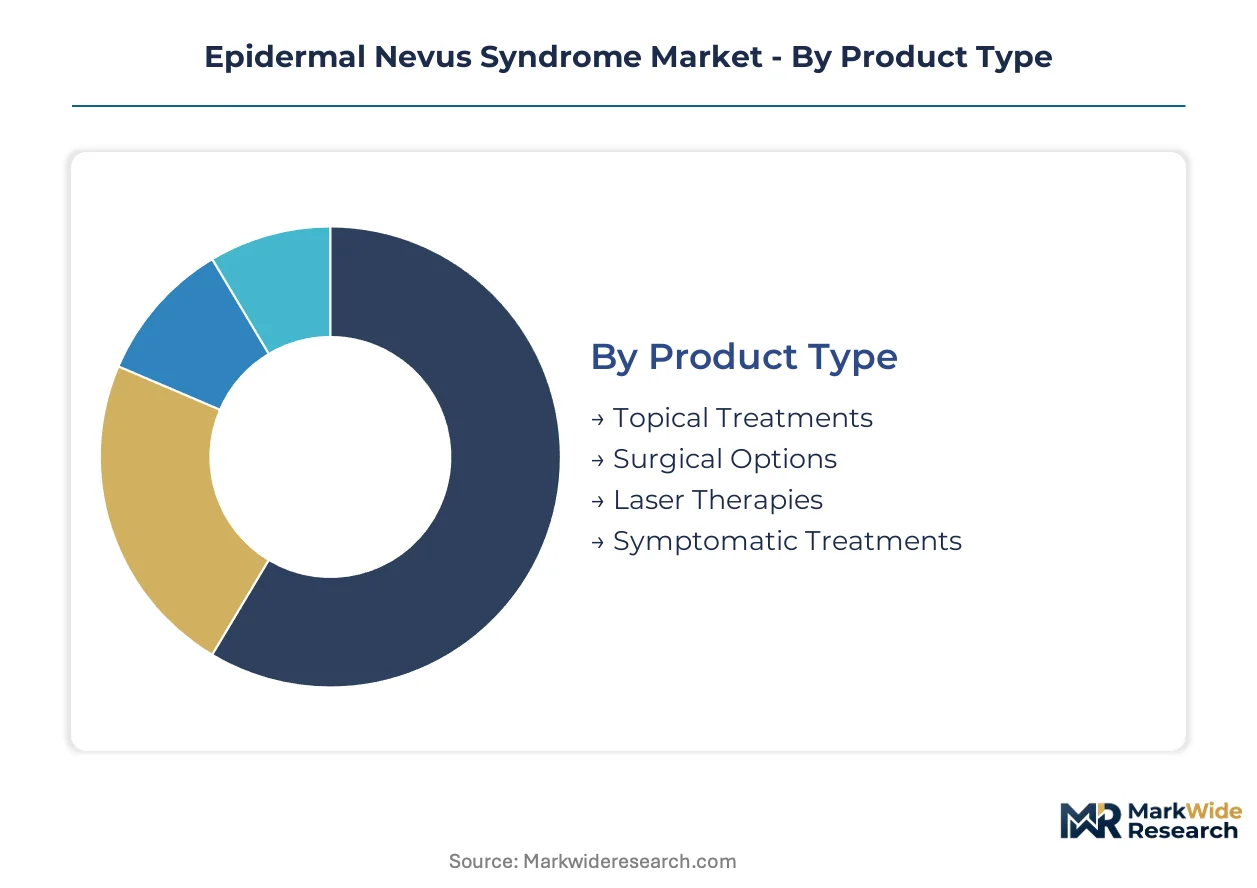
Segmentation in the Epidermal Nevus Syndrome Market reveals distinct procurement patterns across product modalities and care settings. Treatment protocols diverge sharply between pediatric congenital presentations and adult cosmetic interventions, while reimbursement pathways vary by therapy area and delivery mechanism.
Product Type:
Laser Therapies and Topical Treatments concentrate demand in domestic United States and German markets where specialized dermatology infrastructure supports premium modalities, while Surgical Options and Symptomatic Treatments see broader geographic dispersion through general hospital networks.
- Laser Therapies:Fractional and pulsed dye systems enable precise keratinocytic nevi ablation with minimized dermal scarring. Academic medical centers in Boston and Heidelberg drive replacement cycles as pediatric protocols prioritize tissue preservation over excision speed.
- Topical Treatments:Retinoid-based formulations and keratolytic agents address superficial lesion management in outpatient settings. Dermatology clinics in the United States and Germany account for disproportionate prescription volumes due to earlier diagnostic capture in newborn screening programs.
- Surgical Options:Excision and grafting procedures remain essential for large or dysplastic lesions requiring histopathological evaluation.
- Symptomatic Treatments:Adjunctive therapies address pruritus, inflammation, and secondary infection in comprehensive care plans.
Laser Therapies commands the established base. The steepest expansion runs through Topical Treatments.
End User:
Cost stratification separates institutional purchasers from private practice operators, with pediatric academic centers absorbing premium pricing for integrated multidisciplinary protocols while cosmetic centers negotiate aggressively on device leases.
- Pediatrics:Specialized congenital anomaly centers coordinate dermatology, orthopedics, and neurology services for early intervention. United States children's hospitals in Philadelphia and Cincinnati anchor referral networks that concentrate complex case volumes.
- Dermatology Clinics:Outpatient facilities manage stable patients with localized nevi through scheduled laser sequences. German university-affiliated clinics in Munich and Hamburg demonstrate highest per-clinic procedure density in Europe.
- Hospitals:General acute care settings handle emergency presentations and surgical coordination for extracutaneous complications.
- Cosmetic Centers:Private aesthetic practices address adult patients seeking lesion reduction for psychosocial or functional improvement.
Pediatrics absorbs the premium tier. Cosmetic Centers are expanding most quickly as aesthetic demand broadens the addressable population.
Therapy Area:
Application urgency varies dramatically across segments, with Oncology surveillance protocols demanding immediate specialist referral while Rehabilitation services integrate across extended care timelines.
- Dermatology:Primary lesion management and malignant transformation monitoring constitute the clinical core. Japanese academic centers in Tokyo and Osaka advance combined diagnostic-therapeutic platforms.
- Oncology:Surveillance for basal cell carcinoma and squamous cell carcinoma development in large epidermal nevi drives cross-specialty consultation. United States NCCN guidelines mandate periodic biopsy protocols.
- Pain Management:Neuropathic pain from associated spinal abnormalities requires anesthesiology collaboration in severe presentations.
- Rehabilitation:Orthopedic and neurological deficits from skeletal asymmetries or CNS involvement necessitate prolonged physical and occupational therapy.
Dermatology anchors clinical volume. Oncology is gaining share fastest as surveillance protocols extend monitoring intensity.
Delivery Mode:
Supply concentration favors established pharmaceutical and device manufacturers with ISO 13485 certification, creating procurement friction for novel injectable and oral modalities lacking qualified supplier networks.
- Topical:Cream and ointment formulations dominate first-line management with minimal regulatory barriers. German pharmacies compound specialized preparations for pediatric patients with formulation intolerance.
- Surgical:Operative delivery requires qualified facility credentials and specialized nursing support. United States ambulatory surgery centers in Florida and California demonstrate highest case throughput efficiency.
- Injectable:Intralesional corticosteroids and emerging biologic agents target refractory inflammatory components.
- Oral:Systemic retinoids and immunomodulators address extensive or syndromic presentations with multi-organ involvement.
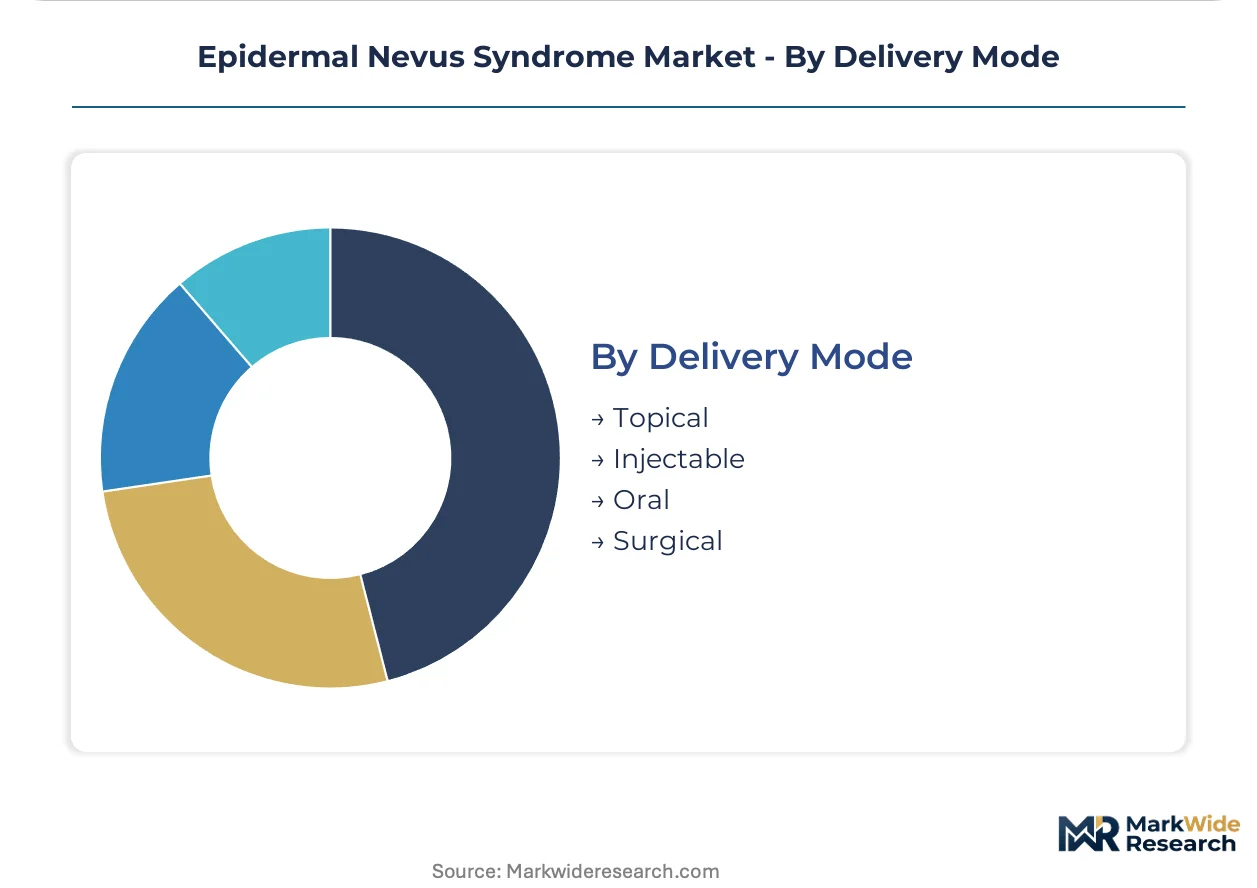
Topical maintains the volume base. Injectable delivery is climbing the fastest as biologic development pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric academic medical centers and specialized dermatology clinics concentrate procurement decisions across major markets, with regulatory incentive structures and reimbursement frameworks shaping geographic expansion priorities for device and pharmaceutical developers.
United States
Children's hospitals in Philadelphia and Cincinnati anchor referral networks for complex congenital anomaly management. FDA orphan drug designation pathways compress development timelines for rare disease therapeutics targeting epidermal nevus presentations. Boston academic medical centers drive replacement cycles for fractional laser systems as pediatric protocols prioritize tissue preservation.
Germany
University-affiliated dermatology clinics in Munich and Hamburg demonstrate the highest per-clinic laser procedure density in Europe. EMA rare disease frameworks extend market exclusivity windows, incentivizing pharmaceutical investment in dermatology therapeutics. Heidelberg pediatric centers coordinate multidisciplinary care protocols that integrate orthopedic and neurological service lines.
Japan
Academic centers in Tokyo and Osaka advance combined diagnostic-therapeutic platforms for lesion monitoring. PMDA imposes distinct clinical evidence requirements that filter developer access to the Asia-Pacific dermatology market. Osaka clusters concentrate demand for diagnostic imaging systems that identify neurological comorbidities in affected patients.
United Kingdom
NHS specialized commissioning frameworks direct complex congenital cases toward designated pediatric dermatology centers in London and Manchester. MHRA regulatory alignment with EMA standards facilitates streamlined market access for qualifying therapeutics. London academic hospitals pilot telemedicine protocols that extend specialist consultation to geographically dispersed pediatric populations.
China
Shanghai Fosun Pharmaceutical Group anchors domestic development capacity for rare disease therapeutics. NMPA regulatory reforms accelerate review timelines for orphan indications, though clinical evidence requirements remain stringent. Beijing tertiary hospitals concentrate surgical volumes for large lesion excisions requiring histopathological evaluation.
Epidermal Nevus Syndrome Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates and specialized medical device manufacturers with rare disease portfolios. Market structure exhibits moderate consolidation, with ISO 13485 certification requirements bifurcating qualified from non-qualified suppliers. Strategic archetypes include rare disease portfolio builders, integrated diagnostic-therapy platform developers, and precision laser technology specialists. Competitive moves center on M&A activity targeting pediatric dermatology capabilities and strategic partnerships for telemedicine channel expansion.
Within the rare disease pharmaceutical tier, GSK Plc. and Bayer AG occupy anchor positions, with the former leveraging its orphan drug development infrastructure and the latter anchoring integrated pharmaceutical development across topical and systemic modalities. Shanghai Fosun Pharmaceutical Group Co., Ltd. represents the Asia-Pacific development vector, while Siemens Healthcare GmbH and Koninklijke Philips N.V. sit within the diagnostic imaging archetype serving neurological comorbidity identification. Stryker Corporation and Zimmer Biomet exemplify orthopedic intervention specialists addressing skeletal manifestations, with Hologic Inc. occupying a position in precision diagnostic platforms.
| Leading Market Players |
|---|
| GSK Plc. |
| Bayer AG |
| Hologic Inc. |
| Shanghai Fosun Pharmaceutical Group Co., Ltd. |
| Zimmer Biomet |
| Stryker Corporation |
| Koninklijke Philips N.V. |
| General Electric |
| Siemens Healthcare GmbH |
| Others |
Supply Flow & Price Mechanics
Fractional laser technology substitution for conventional surgical excision simultaneously shifts procurement geography toward ISO 13485-certified manufacturing clusters in the United States and Germany while compressing per-procedure economics through outpatient delivery models. This substitution dynamic concentrates pricing power with qualified suppliers capable of quality management documentation, while hospital procurement departments filter vendor relationships through certification mandates.
Pricing Analysis
Cost-plus contracts with laser equipment indexation to rare earth metal prices dominate institutional purchasing agreements between academic medical centers and device manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates fractional laser platforms with real-time imaging integration from basic pulsed dye systems and refurbished legacy units. Price differentiation hinges on ISO 13485 certification tier and bundled service coverage duration. Margins are tightening in the economy tier due to refurbished equipment availability, while pediatric academic centers demonstrate lowest price sensitivity given reimbursement capture through specialized congenital anomaly codes.
Supply Chain Analysis
Strait of Hormuz transit risk underwrites shipping contingency costs for rare earth optical components sourced from Chinese processing facilities. Laser therapy platform manufacturing draws from German precision optics, United States semiconductor controls, and Japanese laser diode substrates. Single-source vulnerability concentrates in neodymium-doped yttrium aluminum garnet crystal supply. Distribution runs through authorized dealer networks serving hospital procurement departments with ISO 13485 documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where preventive maintenance contracts and laser fiber replacement programs expand recurring revenue faster than capital equipment sales. The hardware-service bundling ratio is climbing as academic centers prioritize uptime guarantees over acquisition cost minimization.
For Market Incumbents: Compound certification density advantages by acquiring ISO 13485-qualified component suppliers in southern Germany, while expanding pediatric dermatology training partnerships to counter specialist scarcity threatening procedure volume growth. Threat substitution from topical biologic pipelines demands accelerated fractional laser feature development. Capacity addition in Heidelberg anchors European service response times. For New Entrants and Emerging Players: Lead with telemedicine-enabled remote consultation platforms targeting geographically dispersed pediatric populations in the United Kingdom and Japan where specialist density lags demand. The most penetrable white space sits in underdeveloped multidisciplinary center coordination across German secondary cities. Go-to-market execution should prioritize GPO contracts with United States children's hospital networks over direct capital sales cycles. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diagnostic-therapy platform integrators with FDA orphan drug infrastructure already deployed. Long-term viability across the projection horizon rests on capturing the intersection of precision laser technology and neurological comorbidity monitoring. Acquisition target archetype: ISO 13485-certified laser manufacturers with installed base expansion potential in pediatric academic centers. Signal to monitor: PMDA regulatory harmonization progress with FDA standards as inflection indicator for Asia-Pacific market access timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pathway | Hospital procurement departments in Boston and Heidelberg mandate quality documentation prior to vendor onboarding. |
| Pediatric Center Partnership | Philadelphia and Cincinnati children's hospitals anchor referral networks concentrating complex congenital case volumes. |
| Telemedicine Platform Launch | Remote consultation protocols extend specialist dermatology access to geographically dispersed rural pediatric populations. |
| Diagnostic-Therapy Integration | Combined laser-imaging platforms enable real-time lesion monitoring during fractional ablation procedures. |
| Orphan Drug Designation Pursuit | FDA and EMA rare disease frameworks compress development timelines and extend market exclusivity for qualifying sponsors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric dermatologists, hospital procurement managers, laser device biomedical engineers, and pharmaceutical regulatory affairs specialists. Secondary validation drew from FDA orphan drug designation filings, EMA rare disease framework documentation, ClinicalTrials.gov protocol registries, and hospital GPO contract databases. Bottom-up procedure volume estimates across laser therapy, topical, and surgical modalities were triangulated against top-down pharmaceutical and device manufacturer revenue allocations.
Across the analysis window, the forecasting framework modeled patient population segmentation by congenital presentation severity, therapy area concentration across dermatology and oncology surveillance, delivery mode transition from surgical to laser modalities, and regional regulatory cluster differentiation between FDA, EMA, and PMDA jurisdictions. CAGRs were derived from procedure volume trajectories weighted by reimbursement code evolution and technology replacement cycle acceleration in academic medical centers.
The analysis sits within stated boundaries; outcomes outside stable orphan drug incentive structures and continued pediatric subspecialty training pipeline expansion would require recalibration. Forecasts reflect documented assumptions regarding ISO 13485 certification penetration rates and telemedicine reimbursement policy evolution. Revision becomes warranted when PMDA clinical evidence requirement thresholds cross accessibility inflection points for multinational sponsors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
China Ulcerative Colitis Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Hemangioma Market
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Stress Urinary Incontinence Market