
 Small Molecule Targeted Cancer Therapy Market | 2026-2036
Small Molecule Targeted Cancer Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Small Molecule Targeted Cancer Therapy Market Analysis
Companion diagnostic bundling is pivoting how small molecule therapies reach payers and prescribers, shifting transactional drug sales toward outcomes-validated contracts. F. Hoffmann-La Roche AG leverages its dual diagnostics-pharmaceutical footprint to anchor integrated testing-and-treatment workflows across European and North American markets. Novartis International AG sustains kinase inhibitor leadership through deep clinical trial investment in gastrointestinal stromal tumors and chronic myeloid leukemia. Pfizer Inc. competes aggressively in breast cancer CDK inhibition, extending its presence through co-development arrangements with regional biotech partners.
Small molecule targeted cancer therapies constitute synthetic organic compounds, typically below 900 Daltons, designed to modulate specific intracellular signaling pathways implicated in malignant transformation; these agents function by binding defined protein domains—kinase ATP pockets, hormone receptors, or immune checkpoint interfaces—to interrupt oncogenic propagation with minimized collateral cytotoxicity. Kinase inhibitors dominate current revenue pools given their applicability across hematologic and solid tumor indications, while immune checkpoint inhibitors represent the fastest-expanding category as combination protocols with existing standards of care multiply. Oral delivery mode commands the largest patient-volume share due to convenience and adherence advantages, though intravenous administration retains primacy in hospital-based oncology settings where infusion monitoring protocols prevail.
FDA breakthrough therapy designation and EMA priority medicines pathways compress regulatory review timelines, directly influencing sponsor investment allocation toward higher-risk, higher-reward molecular targets. REACH chemical safety requirements and evolving EPA pharmaceutical discharge standards impose manufacturing compliance costs that favor scaled producers with dedicated active pharmaceutical ingredient facilities. Stakeholders must monitor how CMS national coverage determination revisions and parallel EMA health technology assessment evolution reshape reimbursement access for novel mechanism classes before committing pipeline prioritization decisions.
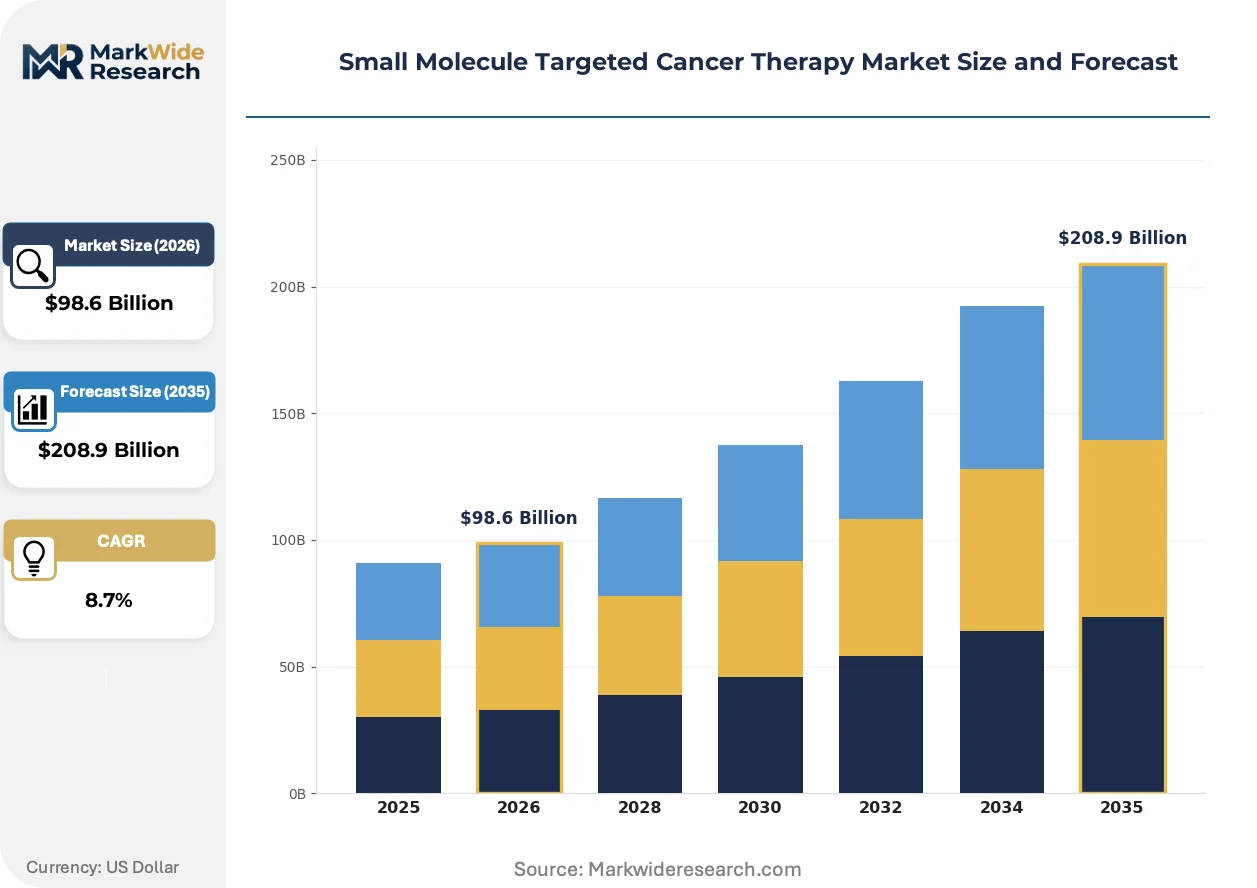
Market Dynamics
The FDA's breakthrough therapy designation is compressing clinical development timelines from ten years toward six, forcing sponsors to front-load manufacturing scale-up and companion diagnostic co-development before Phase II completion.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy and EMA's priority medicines frameworks compress regulatory review from twelve months to six, redirecting R&D investment toward higher-risk molecular targets with orphan indication potential.
- Companion Diagnostic Integration:Bundled testing-and-treatment protocols reshape payer contracts toward outcomes-validated reimbursement, with Medicare coverage determinations creating favorable access conditions for biomarker-selected patient populations.
- Kinase Inhibitor Expansion:ATP-competitive small molecules demonstrate cross-tumor applicability in gastrointestinal stromal tumors and chronic myeloid leukemia, extending addressable patient pools beyond initial hematologic indications.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient production concentrates in India and China, exposing supply chains to export license delays and geopolitical friction that disrupt just-in-time clinical trial material availability.
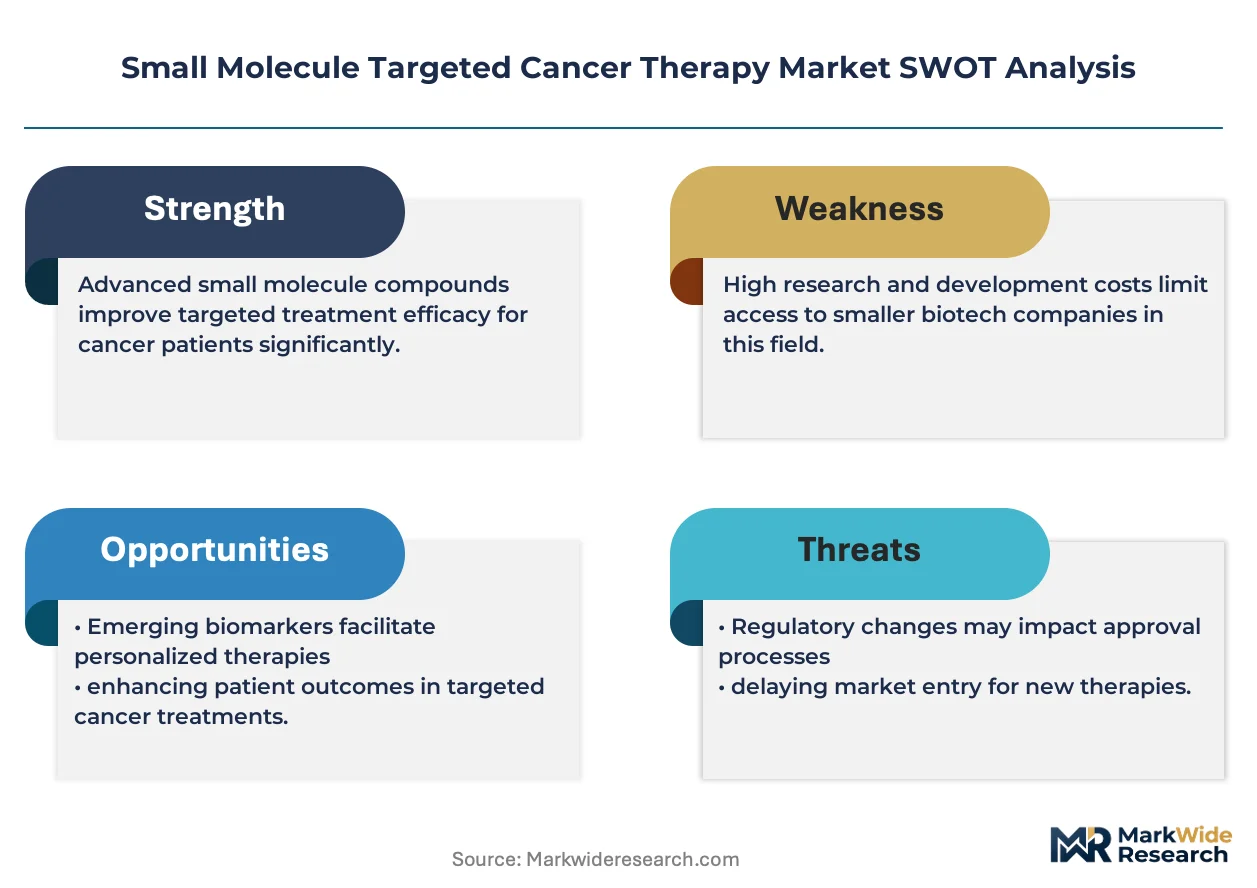
- REACH Compliance Burden:ECHA chemical safety requirements impose toxicology documentation costs exceeding $2 million per novel compound, favoring scaled producers with dedicated regulatory affairs teams over emerging biotech sponsors.
- Patent Cliff Compression:First-generation BCR-ABL and EGFR inhibitors face imminent generic entry, eroding branded pricing power and forcing originators to defend position through formulation improvements rather than molecular innovation.
Strategic Opportunities
- Underserved Solid Tumors:Pancreatic and glioblastoma indications remain poorly addressed by existing kinase inhibitors, creating white space for agents penetrating the blood-brain barrier or targeting KRAS-mutant subpopulations.
- Oral Fixed-Dose Combinations:Co-formulated CDK and aromatase inhibitors simplify adherence in breast cancer maintenance therapy, differentiating against intravenous competitors in community oncology settings where infusion capacity constrains patient throughput.
- IRA Price Negotiation Exclusions:Small molecule drugs receive nine years of Medicare price protection versus thirteen for biologics, accelerating development timelines toward earlier launch windows before statutory negotiation eligibility triggers.
Industry Challenges
- Translational Biology Talent Scarcity:Patient stratification biomarker discovery requires computational biologists fluent in both next-generation sequencing analysis and regulatory-grade assay validation, a hybrid skill set concentrated at academic medical centers.
- Multi-Regional Trial Complexity:Simultaneous FDA, EMA, and PMDA submissions demand divergent primary endpoint specifications and quality management system documentation, stretching clinical operations teams across incompatible inspection readiness frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Molecule Targeted Cancer Therapy Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kinase Inhibitors, Hormonal Agents, Cytotoxic Agents, Immune Checkpoint Inhibitors Application: Breast Cancer, Lung Cancer, Colorectal Cancer, Melanoma Therapy Area: Oncology, Hematology, Urology, Neurology Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal |
| Companies Covered | F. Hoffmann-La Roche AG, Novartis International AG, Pfizer Inc., AstraZeneca PLC, Bristol-Myers Squibb Company, Merck KGaA, Bayer AG, Sanofi S.A., GlaxoSmithKline plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Molecule Targeted Cancer Therapy Market Emerging Trajectories
Artificial intelligence is restructuring how lead compounds advance from target validation toward first-in-human studies, compressing traditional timelines through predictive toxicology and patient selection algorithms.
Fragment-based drug discovery is unifying structural biology and computational chemistry into single integrated workflows. Mid-cap biotech sponsors adopt this approach to access novel allosteric binding sites inaccessible to traditional high-throughput screening. The technology is unifying target validation and lead optimization phases that previously operated as sequential handoffs between distinct research functions.
REACH authorization requirements for pharmaceutical intermediates impose mandatory substitution assessments on solvents and reagents used in multi-step synthesis. European manufacturing sites face capital expenditure decisions between process redesign and supply chain relocation to jurisdictions with less stringent chemical discharge monitoring. Solid tumor API production is most affected, with sponsors responding through contract manufacturer diversification across Switzerland and Singapore.
Academic medical centers are consolidating procurement decisions into centralized pharmacy and therapeutics committees, displacing individual physician prescribing autonomy. Community oncology practices respond through membership in group purchasing organizations that aggregate volume for rebate negotiation. The United States exhibits this concentration most visibly, where Medicare reimbursement rate disparities between hospital outpatient and physician office settings accelerate site-of-care migration toward integrated delivery networks.
Small Molecule Targeted Cancer Therapy Market Segmentation
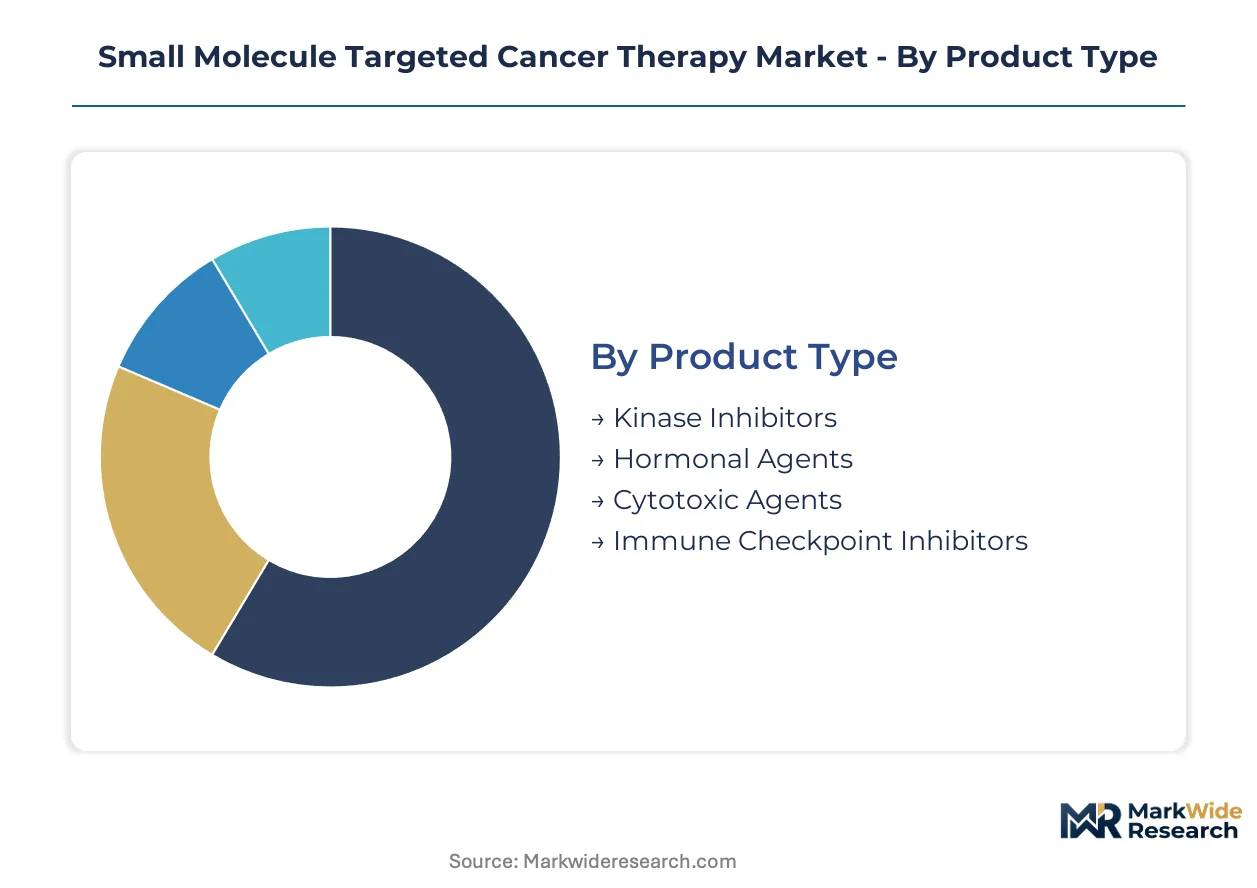
Small molecule targeted cancer therapies fragment across four critical dimensions that determine reimbursement pathways, manufacturing scale requirements, and prescriber access patterns. Each segmentation layer reveals distinct supply chain configurations and regulatory exposure profiles that sponsors must navigate during portfolio prioritization.
Product Type:
Supply concentration varies sharply across mechanism classes, with kinase inhibitor API production clustering in dedicated facilities while immune checkpoint inhibitor synthesis demands more distributed contract manufacturing networks.
- Kinase Inhibitors:ATP-competitive small molecules below 900 Daltons modulate intracellular signaling through precise protein domain binding. Demand concentrates in United States academic medical centers where Medicare reimbursement for biomarker-selected populations creates favorable access. Manufacturing scale requirements favor sponsors with captive active pharmaceutical ingredient facilities.
- Immune Checkpoint Inhibitors:Synthetic organic compounds targeting PD-1/PD-L1 and CTLA-4 interfaces interrupt oncogenic immune evasion with minimized collateral cytotoxicity. United States community oncology practices drive volume through oral convenience advantages, though hospital outpatient settings retain primacy for combination protocols requiring infusion monitoring.
- Hormonal Agents:Receptor modulators for breast and prostate malignancies leverage well-characterized synthetic routes with lower toxicology documentation burdens.
- Cytotoxic Agents:DNA-intercalating and microtubule-disrupting compounds face generic erosion pressure, forcing differentiation through formulation improvements.
Today's leader: Kinase Inhibitors. Tomorrow's challenger: Immune Checkpoint Inhibitors.
Application:
Cost tier stratification separates premium-priced novel mechanisms in breast and lung malignancies from commoditized standards in colorectal indications where biosimilar pressure intensifies.
- Breast Cancer:CDK and aromatase inhibitor combinations dominate maintenance therapy, with oral fixed-dose formulations simplifying adherence in community settings. United States integrated delivery networks concentrate procurement decisions, accelerating site-of-care migration toward hospital outpatient departments with favorable Medicare reimbursement differentials.
- Lung Cancer:EGFR and ALK inhibitors address molecularly defined subpopulations, with blood-brain barrier penetration representing a critical differentiator for central nervous system metastasis. United States specialized cancer center density creates concentrated demand nodes.
- Colorectal Cancer:Established kinase inhibitor protocols face imminent generic entry, eroding branded pricing power and compressing originator margins.
- Melanoma:BRAF and MEK inhibitor combinations command premium positioning despite smaller addressable populations, supported by breakthrough therapy designation pathways.
Revenue pools concentrate in breast and lung applications; melanoma represents the steepest expansion trajectory for novel mechanism classes.
Therapy Area:
Customer type fragmentation distinguishes academic medical center procurement committees from community practice group purchasing organizations, with oncology and hematology presenting the sharpest institutional purchasing concentration.
- Oncology:Solid tumor indications drive the largest patient-volume share, with centralized pharmacy and therapeutics committees displacing individual physician prescribing autonomy. United States Medicare coverage determinations for companion diagnostic bundling reshape contract structures toward outcomes-validated reimbursement.
- Hematology:Chronic myeloid leukemia and gastrointestinal stromal tumors anchor kinase inhibitor revenue, with deep clinical trial investment sustaining molecular leadership.
- Urology:Prostate cancer hormonal protocols face patent cliff compression, forcing defenders toward formulation improvements.
- Neurology:Glioblastoma remains poorly addressed, creating white space for blood-brain barrier penetrating agents.
Oncology commands current procurement volume; neurology offers the most underserved addressable population.
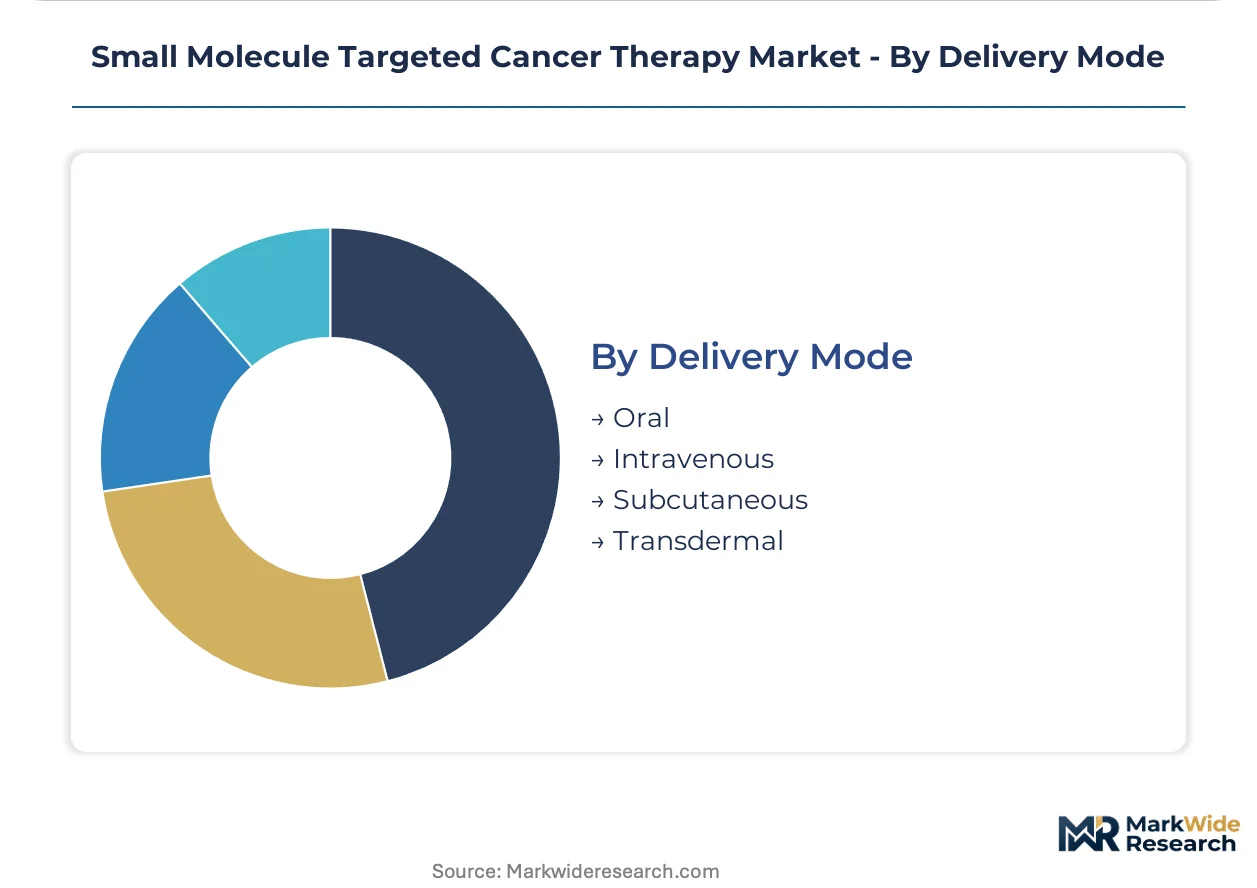
Delivery Mode:
Maturity gradients separate established oral and intravenous channels from emerging subcutaneous and transdermal formats still navigating regulatory validation requirements.
- Oral:Convenience and adherence advantages command the largest patient-volume share across maintenance therapy indications. United States community oncology practices favor oral agents where infusion capacity constrains patient throughput.
- Intravenous:Infusion monitoring protocols prevail in hospital-based oncology settings, with Medicare reimbursement rate disparities accelerating site-of-care migration toward integrated delivery networks.
- Subcutaneous:Self-administration potential reduces healthcare utilization costs, though formulation stability challenges limit current adoption.
- Transdermal:Sustained release patches remain experimental for small molecule oncology agents, with limited regulatory precedent.
Oral delivery dominates convenience-driven demand; intravenous retains primacy for acute combination protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as REACH compliance costs and EPA discharge standards create divergent cost-of-compliance gaps between jurisdictions, prompting sponsors to relocate active pharmaceutical ingredient synthesis toward Singapore and Switzerland while retaining clinical trial density in the United States.
United States
Medicare reimbursement policies and specialized cancer center density concentrate demand for novel kinase inhibitors, with the FDA's breakthrough therapy designation compressing development timelines toward earlier commercialization. The Inflation Reduction Act's nine-year price protection window for small molecules accelerates launch strategies before statutory negotiation triggers. Greater Boston and San Diego anchor the highest concentration of precision oncology clinical trials.
Germany
EMA priority medicines pathways and statutory health insurance reimbursement create favorable access conditions for biomarker-selected therapies, with ECHA REACH requirements imposing toxicology documentation burdens that favor scaled producers. The country's pharmaceutical regulator maintains rigorous manufacturing inspection standards. The Rhine-Main and Upper Bavaria clusters host dedicated active pharmaceutical ingredient facilities serving European supply chains.
Switzerland
Swissmedic's streamlined approval processes and bilateral recognition agreements with the FDA attract sponsors seeking concurrent US-European market entry, with chemical discharge regulations less stringent than REACH. The country's pharmaceutical sector benefits from proximity to German and French markets without full EU regulatory membership. Basel and the Lake Geneva region concentrate contract manufacturing organizations serving global clinical trial material needs.
China
NMPA reforms accelerating innovative drug approvals and domestic biotech investment are expanding local development capabilities, though export license delays for pharmaceutical intermediates expose supply chain vulnerabilities. The country's national pharmaceutical regulator has tightened good manufacturing practice inspections for oncology APIs. Shanghai and Suzhou industrial parks attract multinational sponsors seeking cost-advantaged synthesis for non-regulated markets.
India
CDSCO accelerated approval pathways for orphan indications and contract manufacturing cost advantages position the country as a secondary source for generic-facing kinase inhibitors, with DGFT export licensing creating intermittent supply disruptions. The central drug regulator has harmonized bioequivalence standards with ICH guidelines. Hyderabad and Ahmedabad clusters specialize in oncology active pharmaceutical ingredient production for regulated and emerging markets.
Small Molecule Targeted Cancer Therapy Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostics-pharmaceutical conglomerates commanding premium positioning in biomarker-driven indications while mid-cap biotech sponsors compete through kinase inhibitor specialization in narrower hematologic niches. The market structure concentrates around three strategic archetypes: dual-capability testing-and-treatment integrators, deep clinical trial investors in defined tumor types, and regional partnership builders accessing distributed prescriber networks. Dominant competitive moves include companion diagnostic co-development arrangements and manufacturing scale-up ahead of Phase II completion.
Among Swiss- and German-based pharmaceutical conglomerates, F. Hoffmann-La Roche AG and Novartis International AG occupy positions exemplifying the integrated diagnostics-therapeutics archetype, with Roche leveraging dual-footprint workflows and Novartis representing sustained kinase inhibitor leadership through deep clinical investment. New York-based Pfizer Inc. anchors the partnership-building tier, extending market presence through co-development arrangements with regional biotech sponsors. These three entities represent distinct strategic postures within a landscape where FDA breakthrough designations and EMA priority pathways compress competitive windows.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Novartis International AG |
| Pfizer Inc. |
| AstraZeneca PLC |
| Bristol-Myers Squibb Company |
| Merck KGaA |
| Bayer AG |
| Sanofi S.A. |
| GlaxoSmithKline plc |
| Others |
Supply Flow & Price Mechanics
Specialty chemical feedstock indices for heterocyclic intermediates cascade through multi-step synthesis costs, compressing margins for emerging biotech sponsors while scaled producers with captive active pharmaceutical ingredient facilities capture pricing power through backward integration into raw material sourcing.
Pricing Analysis
Hospital outpatient markup layers over manufacturer net pricing create substantial access differentials between academic medical centers and community oncology practices. Three-tier pricing structure across premium kinase inhibitors, standard hormonal agents, and economy-facing cytotoxic generics reflects molecular complexity and companion diagnostic bundling requirements. Pricing pressure stems from first-generation BCR-ABL and EGFR inhibitor patent cliffs, with generic entry eroding branded pricing power in chronic myeloid leukemia and non-small cell lung cancer. Community oncology group purchasing organizations exhibit highest price sensitivity due to Medicare reimbursement rate disparities, while integrated delivery networks with favorable site-of-care differentials show lowest sensitivity.
Supply Chain Analysis
Direct-to-hospital channels handle breakthrough therapy designation volumes requiring cold-chain integrity and just-in-time clinical trial material availability. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland, with heterocyclic intermediate synthesis and final drug substance manufacturing drawing from distinct geographic clusters. Key inputs include palladium catalysts for cross-coupling reactions, high-purity solvents for chromatographic purification, and specialized packaging for oral solid dosage forms. Single-source vulnerability in isotope-labeled reference standards for bioanalytical testing creates regulatory submission risk. Distribution runs through contract manufacturing organizations with dedicated oncology facilities and qualified person release capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as precision-matched protocols displace empirical chemotherapy, with demand shifting toward biomarker-selected patient populations commanding premium positioning.
For Market Incumbents: Acquire computational biology platforms with regulatory-grade assay validation capabilities to anchor companion diagnostic co-development ahead of Phase II completion. Consolidate manufacturing scale through dedicated active pharmaceutical ingredient facility investment in Singapore or Switzerland to mitigate REACH compliance burden and export license exposure. Patent cliff compression in first-generation kinase inhibitors demands formulation improvement differentiation rather than molecular innovation defense.
For New Entrants and Emerging Players: Digital pathology and remote patient monitoring platforms offer lower-friction entry vectors than traditional pharmaceutical development. Underserved solid tumor indications—particularly pancreatic and glioblastoma—present the most penetrable white space for blood-brain barrier penetrating agents or KRAS-mutant targeted therapies. Co-development arrangements with regional biotech partners provide validated go-to-market access without full clinical infrastructure buildout.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap biotech sponsors possessing fragment-based drug discovery platforms and concurrent FDA-EMA submission capabilities. Long-term viability hinges on pipeline diversification across multiple tumor types rather than single-indication concentration. Watch for CMS national coverage determination revisions for novel mechanism classes as the critical inflection indicator for reimbursement access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA breakthrough therapy designation demands biomarker validation before Phase II completion. |
| Manufacturing Scale-Up Ahead of Approval | REACH compliance costs favor sponsors with dedicated active pharmaceutical ingredient facilities. |
| Regional Partnership Expansion | Co-development with Asian biotech partners accelerates NMPA pathway access for China launch. |
| Oral Fixed-Dose Combination Development | Community oncology practices favor adherence-simplifying formulations over intravenous competitors. |
| Pipeline Diversification Across Tumor Types | Patent cliff compression in hematologic indications demands solid tumor expansion. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare coverage determination databases. Bottom-up patient-volume modeling across mechanism classes and top-down revenue triangulation against disclosed pharmaceutical sales provided cross-check integrity.
Historical reference periods anchored the projection horizon through documented regulatory approval timelines and launch-to-peak sales curves across prior kinase inhibitor and immune checkpoint inhibitor cohorts. Segmentation dimensions included product type, application, therapy area, delivery mode, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating biomarker testing penetration rates and companion diagnostic co-approval frequencies. Forecast inputs encompassed Medicare reimbursement rate evolution and EMA health technology assessment pathway timing.
The model assumes a particular technology adoption path; alternative pathways for artificial intelligence-driven patient selection algorithms would alter the outlook. Forecasts reflect base-case assumptions regarding FDA breakthrough therapy designation retention and IRA price negotiation exclusion windows. Regulatory pathway delays, supply chain disruptions from export licensing, and biomarker test reimbursement denials represent specific risk factors that could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Epilepsy Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
US Opioid Use Disorder (OUD) Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Eosinophilic Granulomatosis with Polyangiitis Treatment Market
Specialty Medicine
Global Multiple Sclerosis Therapeutics Market
Specialty Medicine
Relapsing-Remitting Multiple Sclerosis (MS) Market
Specialty Medicine
Achondroplasia Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Community Acquired Bacterial Pneumonia (CABP) Treatment Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Cryoglobulinemia Treatment Market