
 Polymyalgia Rheumatica Treatment Market | 2026-2036
Polymyalgia Rheumatica Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Polymyalgia Rheumatica Treatment Market Analytics
Biologic IL-6 pathway inhibition is rewriting clinical protocols for glucocorticoid-resistant polymyalgia rheumatica cases. Sanofi leverages its immunology pipeline depth to compete in corticosteroid-sparing regimens. AbbVie anchors its position through rheumatology franchise integration across autoimmune indications. Pfizer differentiates via oral JAK inhibitor positioning against injectable biologic alternatives.
Polymyalgia rheumatica treatment encompasses pharmacological management of systemic inflammatory disease marked by elevated erythrocyte sedimentation rate and C-reactive protein, typically involving prednisone-equivalent glucocorticoid initiation at 15-20 mg daily with structured taper protocols. The therapeutic goal centers on rapid symptom resolution while minimizing corticosteroid exposure duration to prevent osteoporosis, diabetes, and cardiovascular complications. Glucocorticoids still occupy the dominant share of prescriptions due to immediate efficacy and low cost, though biological agents represent the fastest-expanding segment as steroid-sparing alternatives in refractory or relapsing patients. Oral administration leads volume by route, while subcutaneous biologics capture premium positioning in the treatment setting hierarchy where outpatient infusion centers compete with home self-injection models.
FDA oversight through CDER's Division of Pulmonary, Allergy, and Rheumatology Products shapes trial design requirements and label indications for new molecular entities in this space. EMA's Committee for Medicinal Products for Human Use applies divergent benefit-risk thresholds that delay or accelerate European market entry for novel mechanisms. Stakeholders must monitor biomarker-guided taper algorithms and real-world evidence generation requirements that will determine reimbursement for non-glucocorticoid alternatives across payer systems.
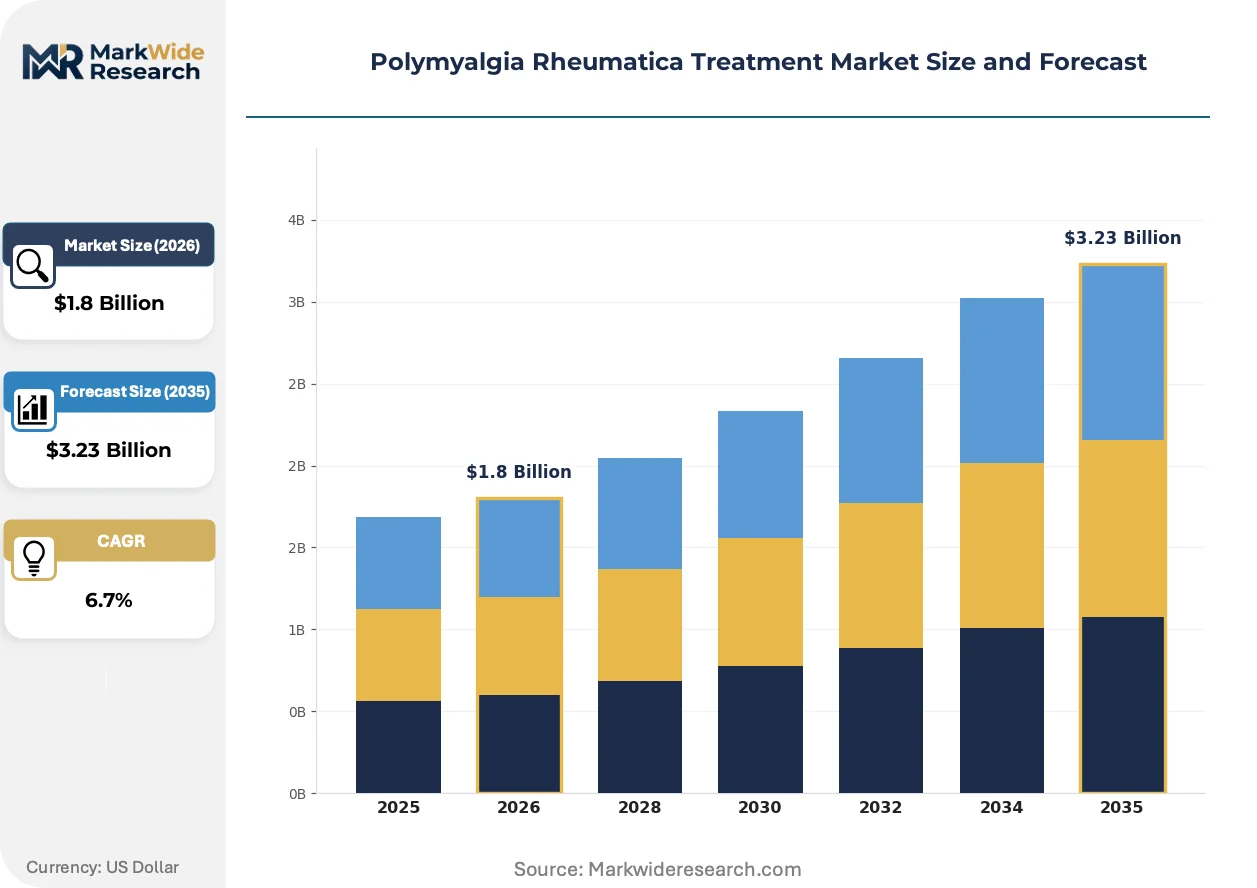
Market Dynamics
The FDA's orphan drug incentives and accelerated approval pathways for autoimmune therapies are compressing development timelines and redirecting R&D investment toward corticosteroid-sparing mechanisms in polymyalgia rheumatica.
Growth Catalysts
- EMA's adaptive pathways framework:European regulators now permit smaller confirmatory trials for biologics in relapsing polymyalgia rheumatica, shortening time-to-market for IL-6 inhibitors.
- Hospital outpatient rheumatology expansion:United States health systems are building dedicated autoimmune infusion centers that streamline biologic initiation and monitoring.
- Biomarker-guided taper protocols:Erythrocyte sedimentation rate and C-reactive protein monitoring technologies enable precision dosing that reduces glucocorticoid exposure duration.
Market Restraints
- Biologic manufacturing concentration:Monoclonal antibody production for IL-6 pathway inhibitors clusters among contract manufacturers in Ireland and Singapore, creating single-source vulnerability.
- Glucocorticoid cost anchoring:Generic prednisone at pennies per pill sets an impossible reimbursement benchmark for novel mechanisms requiring thousand-fold pricing multiples.
- Diagnostic specificity limitations:Absence of pathognomonic biomarkers forces reliance on clinical criteria that exclude patients with atypical presentations from biologic trials.
Strategic Opportunities
- Japan's aging demographic density:The world's oldest population concentrates polymyalgia rheumatica prevalence in a single-payer system receptive to corticosteroid-sparing value propositions.
- Home self-injection channel development:Subcutaneous biologics bypass infusion center capacity constraints and capture patient preference for treatment location flexibility.
- Real-world evidence mandates:Payer requirements for post-approval effectiveness data create first-mover advantage for sponsors investing in patient registries early.
Industry Challenges
- Rheumatology workforce scarcity:Fellowship-trained specialists concentrate in urban academic centers, leaving community diagnosis and management to generalists with limited autoimmune expertise.
- Legacy electronic health record integration:Structured taper protocols and flare documentation tools fail to interoperate with dominant ambulatory platforms, fragmenting care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymyalgia Rheumatica Treatment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucocorticoids, Methotrexate, Non-Steroidal Anti-Inflammatory Drugs, Biological Agents Treatment Setting: Outpatient, Home Care, Inpatient, Telemedicine Administration Route: Oral, Intravenous, Subcutaneous, Topical Patient Demographics: Adults, Geriatric Population, Women, Men |
| Companies Covered | Sanofi, Merck & Co., Inc., F. Hoffmann-La Roche Ltd., Regeneron Pharmaceuticals Inc., Amgen Inc., Pfizer Inc., GSK plc, Novartis AG, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymyalgia Rheumatica Treatment Market Evolving Landscape
Clinical protocol evolution is fragmenting the once-uniform glucocorticoid pathway into stratified treatment algorithms that match mechanism to patient phenotype.
IL-6 receptor antagonism is hybridizing with conventional taper schedules to create corticosteroid-sparing regimens that maintain remission while minimizing bone density loss and glycemic disruption. Academic medical centers in the United States and Germany are piloting these combination protocols for patients with recurrent relapse patterns. The structural consequence compresses average glucocorticoid exposure duration from years to months in eligible populations.
REACH registration requirements in Europe now mandate extended safety databases for chronic autoimmune biologics, forcing sponsors to design larger Phase IIIb programs than FDA equivalents require. This regulatory asymmetry delays European launches by twelve to eighteen months for novel mechanisms. Smaller biotechnology firms are responding by prioritizing US-first filing strategies and partnering with established European marketers for commercialization.
Patient-driven switching between outpatient infusion centers and home administration is disrupting traditional site-of-care economics for biologic delivery. United States rheumatology practices report accelerating preference for self-injection training over recurring infusion appointments among working-age patients. This behavioral shift concentrates volume in specialty pharmacy distribution channels and reduces hospital outpatient department capture rates for maintenance therapy.
Polymyalgia Rheumatica Treatment Market Segmentation
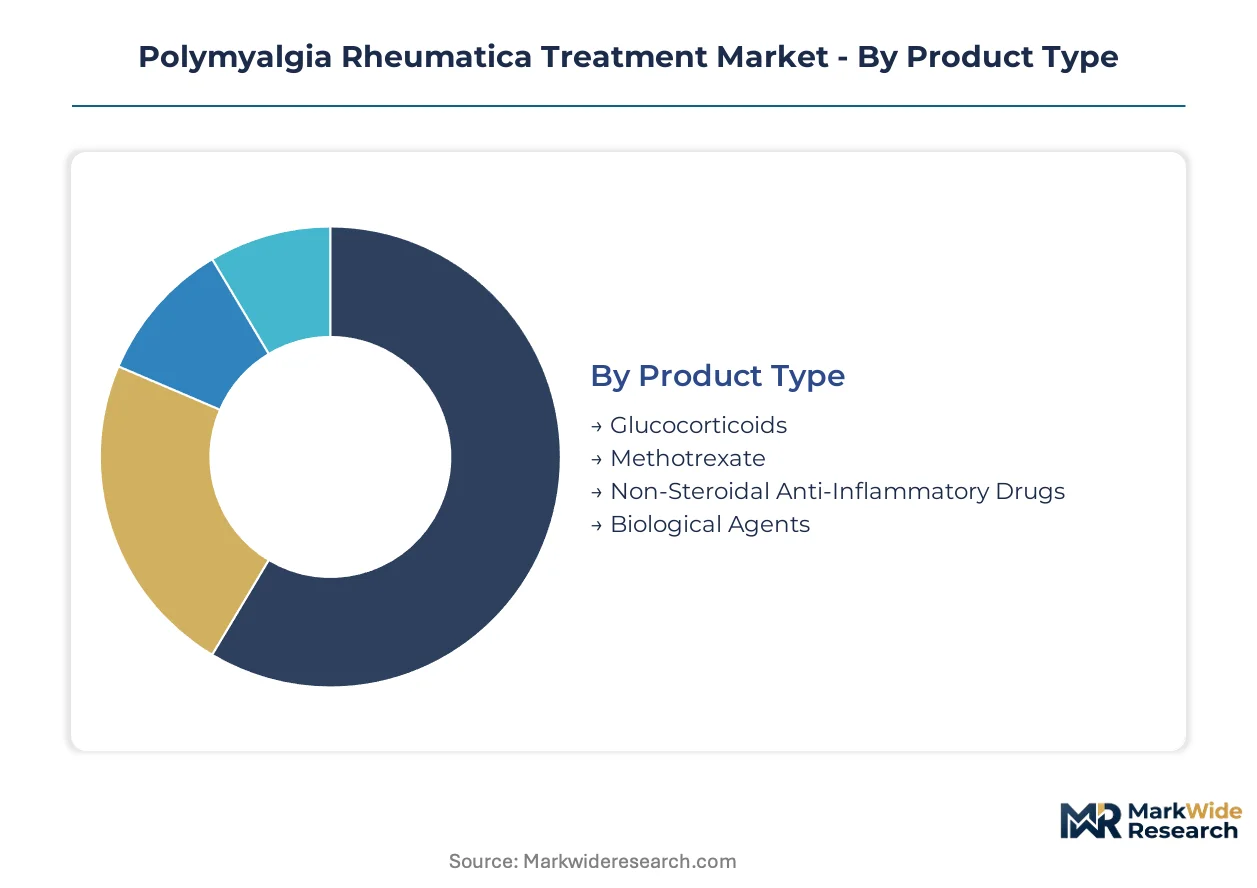
Polymyalgia rheumatica treatment stratifies across pharmacological classes, care delivery venues, and patient phenotypes. Each dimension carries distinct reimbursement logic and regulatory requirements that shape commercial strategy.
Product Type:
Cycle times vary dramatically — glucocorticoids turn over in weeks while biologics lock patients into year-long regimens with structured monitoring protocols.
- Glucocorticoids:Prednisone-equivalent formulations deliver immediate anti-inflammatory suppression through rapid cytokine pathway inhibition. Demand concentrates in United States Medicare Part D formularies where generic pricing anchors reimbursement benchmarks and limits novel mechanism penetration.
- Biological Agents:IL-6 pathway inhibitors and emerging B-cell modulators interrupt refractory disease through targeted immunomodulation. United States academic medical centers drive adoption for corticosteroid-sparing protocols in relapsing patients with comorbidity burdens.
- Methotrexate:Folate antagonist immunosuppressant used as steroid-sparing adjunct in taper-resistant cases.
- Non-Steroidal Anti-Inflammatory Drugs:Adjunctive symptom management with limited disease-modifying impact in this indication.
Glucocorticoids dominate installed base. Biological agents are where expansion concentrates.
Treatment Setting:
Cost tier separation runs deepest here — hospital outpatient departments capture premium biologic administration while home care and telemedicine compete on convenience and co-pay reduction.
- Outpatient:Hospital-based rheumatology clinics and dedicated infusion centers manage biologic initiation, taper monitoring, and flare response. United States health systems in metropolitan clusters anchor volume through specialist concentration and payer contract leverage.
- Home Care:Self-injection training and remote monitoring programs shift maintenance therapy from facility to residence. Patient preference for location flexibility accelerates adoption among working-age cohorts managing employment constraints.
- Inpatient:Acute flare management and diagnostic workup for atypical presentations requiring exclusion of giant cell arteritis.
- Telemedicine:Virtual follow-up for stable patients on established taper protocols, expanding fastest in post-pandemic reimbursement frameworks.
Outpatient settings capture premium biologic volume. Home care is climbing the fastest as self-administration protocols mature.
Administration Route:
Patient type and disease severity dictate route selection — oral for initiation and stable maintenance, parenteral for refractory cases requiring precise bioavailability.
- Oral:Prednisone tablets and methotrexate dosing dominate first-line therapy through convenience and decades of clinical familiarity. Geriatric adherence challenges in polypharmacy contexts create demand for simplified regimens and packaging.
- Subcutaneous:Pre-filled syringe and auto-injector devices for IL-6 inhibitors enable home administration with reduced healthcare utilization. United States specialty pharmacy distribution channels concentrate volume as site-of-care economics shift.
- Intravenous:Infusion center delivery for rituximab and investigational biologics requiring controlled administration.
- Topical:Limited application for localized symptom relief without systemic immunosuppression.
Oral administration dominates prescription volume. Subcutaneous delivery is gaining share fastest through patient preference and payer cost avoidance.
Patient Demographics:
Age and sex stratification reveals distinct phenotypic presentations with implications for treatment intensity and comorbidity management.
- Geriatric Population:Patients over 70 years constitute the core prevalence pool with elevated giant cell arteritis risk and heightened corticosteroid toxicity concerns. Bone density preservation and glycemic control drive biologic eligibility screening in United States Medicare populations.
- Women:Female predominance in disease incidence creates sex-specific research priorities around osteoporosis prevention and cardiovascular risk stratification.
- Adults:Working-age patients under 65 with early-onset polymyalgia rheumatica represent distinct clinical trial eligibility and employment-centered quality-of-life endpoints.
- Men:Lower absolute incidence but potentially more severe disease trajectory in comparative cohort studies.
Geriatric patients anchor disease prevalence. Women represent the steepest expansion trajectory for targeted corticosteroid-sparing value propositions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologic exports from Swiss and German manufacturing clusters supply infusion centers across the United States and Japan, creating a transatlantic trade corridor that anchors supply security calculations for corticosteroid-sparing therapies.
United States
Medicare Part D formularies and commercial payer prior authorization frameworks concentrate demand for IL-6 pathway inhibitors among geriatric populations in Florida and Arizona retirement corridors. FDA's accelerated approval pathway for autoimmune indications compresses development timelines for sponsors targeting relapsing patients. Boston and San Francisco academic medical centers pilot biomarker-guided taper protocols that reduce glucocorticoid exposure duration.
Germany
EMA's adaptive pathways framework permits smaller confirmatory trials for biologics in relapsing polymyalgia rheumatica, shortening time-to-market for novel mechanisms. REACH registration requirements mandate extended safety databases that force larger Phase IIIb programs than FDA equivalents. Heidelberg and Munich rheumatology departments anchor corticosteroid-sparing protocol adoption through specialist concentration and statutory health insurance reimbursement leverage.
Japan
The world's oldest population concentrates polymyalgia rheumatica prevalence in a single-payer system receptive to corticosteroid-sparing value propositions. PMDA's orphan drug designation streamlines review timelines for targeted immunomodulators. Tokyo and Osaka metropolitan areas host the highest density of rheumatology specialists driving biologic eligibility screening for bone density preservation.
Switzerland
Contract manufacturing clusters for monoclonal antibody production supply IL-6 pathway inhibitors to European and North American markets, creating single-source vulnerability in the supply chain. Swissmedic's regulatory alignment with EMA procedures facilitates parallel market entry strategies. Basel and Zurich anchor pharmaceutical R&D investment in autoimmune mechanisms.
United Kingdom
NICE technology appraisals apply distinct cost-effectiveness thresholds that delay or accelerate National Health Service formulary inclusion for novel mechanisms. The UK's aging demographic drives treatment volume through established specialist referral networks in London and Manchester. Academic medical centers in Oxford and Cambridge generate real-world evidence for post-approval effectiveness mandates.
Polymyalgia Rheumatica Treatment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital outpatient departments and specialty pharmacy distribution networks. The vendor base stratifies into three tiers: diversified pharmaceutical conglomerates with immunology franchise depth, biotechnology specialists with single-mechanism focus, and generic manufacturers anchoring glucocorticoid supply. Consolidation pressures intensify as corticosteroid-sparing protocols displace volume from high-margin biologics toward lower-cost alternatives. Dominant competitive moves include rheumatology franchise integration across autoimmune indications and home self-injection channel development to bypass infusion center capacity constraints.
Within the diversified pharmaceutical tier, Sanofi, AbbVie Inc., and Pfizer Inc. exemplify distinct strategic positioning archetypes. Sanofi leverages immunology pipeline breadth to compete across corticosteroid-sparing regimens. AbbVie anchors its position through rheumatology franchise integration that spans multiple autoimmune indications. Pfizer differentiates via oral small-molecule positioning against injectable biologic alternatives, capturing patient preference for administration convenience. These three conglomerates occupy positions that reflect channel-control capabilities rather than product-specific dominance, with each representing a distinct pathway to market access in the United States and European reimbursement environments.
| Leading Market Players |
|---|
| Sanofi |
| Merck & Co., Inc. |
| F. Hoffmann-La Roche Ltd. |
| Regeneron Pharmaceuticals Inc. |
| Amgen Inc. |
| Pfizer Inc. |
| GSK plc |
| Novartis AG |
| AbbVie Inc. |
| Others |
Value Network & Pricing Analysis
Basel and Zurich contract manufacturing clusters anchor monoclonal antibody supply for IL-6 pathway inhibitors, concentrating production capacity among three dominant biologics suppliers. This geographic concentration translates directly into pricing power for corticosteroid-sparing therapies, where thousand-fold multiples over generic prednisone still find reimbursement traction through Medicare Part D specialty tier placement.
Pricing Analysis
Prior-generation glucocorticoid pricing at pennies per pill sits against current-generation IL-6 inhibitor biologics commanding specialty pharmacy premiums, with next-generation oral JAK inhibitors positioning between these extremes on convenience value. Three-tier pricing structure across premium biologics, standard small-molecule alternatives, and economy glucocorticoids reflects reimbursement stratification by corticosteroid-sparing eligibility. Cost compression in the biologic tier is intensifying as FDA accelerated approvals multiply therapeutic alternatives. Hospital outpatient departments show least price sensitivity due to pass-through reimbursement mechanics, while Medicare Part D enrollees face highest sensitivity through coinsurance exposure.
Supply Chain Analysis
Tariff exposure between Switzerland and the United States dominates supply chain risk calculations for monoclonal antibody distribution. Manufacturing concentrates in Ireland, Singapore, and Swiss contract facilities, with active pharmaceutical ingredient synthesis drawing from Chinese and Indian chemical supply bases. Single-source vulnerability permeates sterile fill-finish capacity for pre-filled syringe devices. Distribution runs through specialty pharmacy channels for home self-injection, bypassing traditional hospital outpatient capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polymyalgia rheumatica treatment is approaching a platform-economics inflection as biomarker-guided taper protocols create interoperability standards between diagnostic monitoring and dosing algorithms. EHR integration requirements for structured flare documentation are consolidating vendor selection around systems capable of real-world evidence capture.
For Market Incumbents: Entrench position through rheumatology franchise integration across autoimmune indications, securing formulary placement through outcomes-based contracts with Medicare Advantage plans. Capacity addition in United States specialty pharmacy distribution counters infusion center capacity constraints threatening biologic volume capture. Vertical integration into patient registry infrastructure addresses payer mandates for post-approval effectiveness documentation. For New Entrants and Emerging Players: Establish a beachhead in Japan's single-payer system where aging demographic density concentrates polymyalgia rheumatica prevalence and corticosteroid-sparing value propositions command statutory health insurance reimbursement. Home self-injection channel development offers the most penetrable entry vector, bypassing established hospital outpatient relationships. Go-to-market execution should prioritize PMDA orphan drug designation pathways to compress review timelines. For Investors and Strategic Acquirers: Long-term, this sits as a chronic disease management play because corticosteroid-sparing protocol adoption creates recurring revenue streams with decade-long patient lifecycles. Acquisition targets should display biomarker-guided taper algorithm capabilities and EHR interoperability infrastructure. The signal to watch is real-world evidence generation requirements in CMS Medicare coverage determinations, which will bifurcate reimbursement between registry-enabled and registry-absent therapies.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Guided Taper Algorithm Development | Precision dosing protocols reduce glucocorticoid exposure duration and capture payer preference for outcomes-based contracts. |
| Home Self-Injection Channel Expansion | Subcutaneous biologics bypass hospital outpatient capacity constraints and align with patient preference for location flexibility. |
| Patient Registry Infrastructure Investment | Real-world evidence generation capabilities satisfy post-approval effectiveness mandates from United States commercial payers. |
| Rheumatology Franchise Integration | Cross-indication immunology depth secures formulary placement through bundled contracting with hospital systems. |
| EHR Interoperability Certification | Structured taper protocol integration with dominant ambulatory platforms fragments care coordination for non-integrated competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare Part D formulary databases. Primary interviews engaged drug development executives at biologics sponsors, regulatory affairs leads navigating accelerated approval pathways, formulary directors at national pharmacy benefit managers, and payer access specialists at Medicare Advantage plans. Bottom-up prescription volume modeling triangulates against top-down epidemiological prevalence estimates for polymyalgia rheumatica across geriatric populations.
Forecast inputs span pharmacological class segmentation, treatment setting hierarchies, administration route preferences, and patient demographic stratification. The analytical framework projects volume and value across the modeling period by integrating corticosteroid-sparing protocol adoption curves, biologic penetration rates in relapsing patients, and generic glucocorticoid erosion patterns. CAGRs derive from regression analysis of historical prescription trends against demographic aging trajectories and regulatory approval timelines.
Stress conditions across IL-6 inhibitor manufacturing concentration, Medicare reimbursement policy shifts, and rheumatology workforce scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding biomarker-guided taper protocol adoption speed and EHR interoperability implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Systemic Scleroderma Treatment Market
Specialty Medicine
Cerebral Vein Thrombosis Treatment Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Benign Positional Vertigo Market
Specialty Medicine
Combined Immune Deficiency (CID) Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Benign and Malignant Soft Tissue Tumors Treatment Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Monoclonal Antibody Therapy Market
Specialty Medicine
Global Interstitial Cystitis Market