
 Sickle Cell Treatment Market | 2026-2036
Sickle Cell Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Sickle Cell Treatment Market Analytics
A shortage of hematology-trained gene therapy administrators is redrawing competitive boundaries in sickle cell care. Novartis AG leverages its established rare disease infrastructure to sustain patient access programs across treatment centers. Vertex Pharmaceuticals Inc. anchors its position through deep specialization in CRISPR-based curative protocols.
Sickle cell treatment encompasses pharmacologic, genetic, and supportive interventions targeting hemoglobin S polymerization and its vaso-occlusive consequences. Hydroxyurea remains the oral standard of care, while gene therapy segments concentrate margin pools in curative treatment categories. Hospital end users dominate volume, though home care administration of oral agents occupies a growing share of supportive therapy delivery.
FDA accelerated approval designations and EMA priority medicines status shape development timelines and reimbursement negotiations for novel modalities. The EU AI Act and national health technology assessment bodies in France and Germany introduce additional evidence requirements for gene therapy market access. Stakeholders must monitor payer willingness to fund single-administration curative therapies against chronic supportive care models.
Market Dynamics
CRISPR-based curative protocols are compressing chronic care revenue models while expanding the addressable patient base beyond traditional hydroxyurea-dependent cohorts. Hospital systems face capital reallocation pressures as gene therapy administration requires specialized infrastructure distinct from standard hematology units.
Growth Catalysts
- FDA Accelerated Approval Pathway:Compressed review timelines for cell and gene therapies enable faster commercialization of single-administration curative treatments. Pediatric treatment centers gain earlier access to novel modalities.
- Medicaid Coverage Expansion:State-level reimbursement policy shifts in the United States are removing prior authorization barriers for gene therapy. Commercial payers follow public program precedents.
- Hematology-Gene Therapy Convergence:Cross-training programs at academic medical centers are expanding the administrator pool. Treatment center certification standards are harmonizing across hospital networks.
Market Restraints
- Specialized Manufacturing Input Concentration:Viral vector production capacity concentrates at contract manufacturers in the United States and Europe. Supply bottlenecks delay patient slot allocation.
- EMA Health Technology Assessment Friction:France's Haute Autorité de Santé and Germany's Institut für Qualität und Wirtschaftlichkeit im Gesundheitswesen impose incremental evidence requirements. Market access timelines extend 12-18 months post-approval.
- Allogeneic Stem Cell Transplant Substitution:Established curative protocols from matched sibling donors compete for payer budgets. Transplant centers defend referral relationships against gene therapy displacement.
Strategic Opportunities
- Sub-Saharan Africa Patient Identification Infrastructure:Newborn screening program expansion in Nigeria and Ghana creates addressable cohorts previously excluded from curative therapy eligibility. Partnership models with ministry of health systems enable market development.
- EU AI Act Compliance Services:Algorithmic diagnostic tools for vaso-occlusive crisis prediction require conformity assessment. Software vendors can embed into hospital system procurement workflows.
- Home-Based Oral Agent Administration:Digital therapeutic companions for hydroxyurea adherence create recurring revenue streams. Pharmacy benefit managers seek outcomes-linked contracting structures.
Industry Challenges
- Cell Processing Technician Certification Backlogs:Foundation for the Accreditation of Cellular Therapy standards create training pipeline constraints. Treatment center expansion outpaces qualified personnel supply.
- Multi-Site Clinical Trial Coordination Complexity:Gene therapy protocols require centralized cell processing facilities. Site initiation timelines stretch due to institutional review board heterogeneity.
- Long-Term Follow-Up Registry Integration:FDA-mandated 15-year outcome tracking demands interoperable data systems. Hospital information technology departments struggle with legacy electronic health record compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sickle Cell Treatment Market |
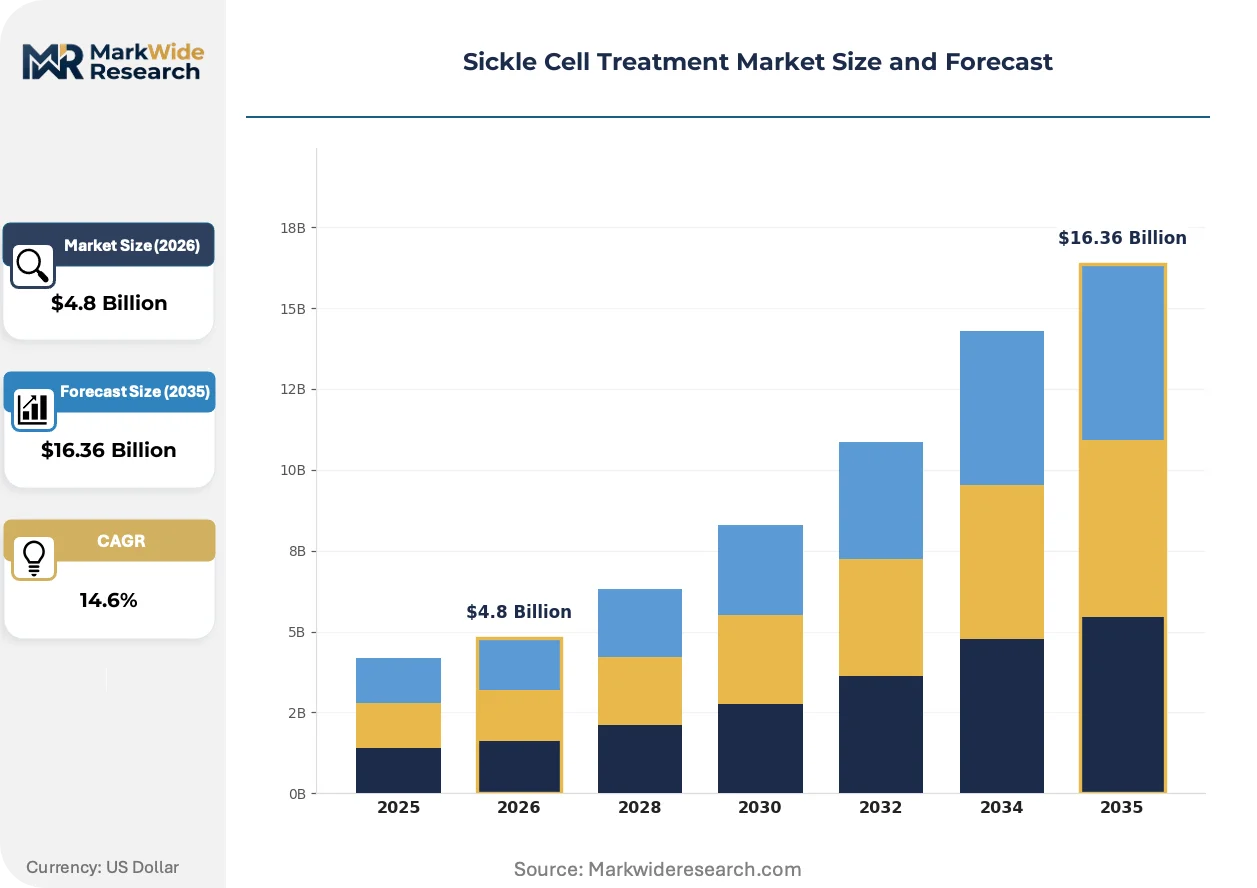
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydroxyurea, L-glutamine, Gene Therapy, Pain Management End User: Hospitals, Clinics, Home Care, Research Institutions Treatment Type: Curative, Supportive, Preventive, Palliative Administration Route: Oral, Intravenous, Subcutaneous, Intra-muscular |
| Companies Covered | Novartis AG, Pfizer Inc., Vertex Pharmaceuticals Inc., CRISPR Therapeutics AG, Bluebird Bio Inc., Bristol-Myers Squibb Company, Emmaus Medical Inc., Sanofi SA, Editas Medicine Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sickle Cell Treatment Market Evolving Landscape
Gene editing platforms are fragmenting the treatment continuum between acute episodic management and definitive cure. Regulatory science is racing to keep pace with manufacturing scalability challenges.
Lentiviral and CRISPR-Cas9 delivery systems are bifurcating the curative therapy pipeline into ex vivo and in vivo administration pathways. Academic medical centers in Boston and San Francisco are piloting same-day apheresis-to-infusion workflows. This compression is collapsing the traditional multi-week hospitalization model into ambulatory settings.
The EU AI Act's risk classification framework for clinical decision support tools is reshaping software procurement criteria at European treatment centers. Algorithms predicting vaso-occlusive crisis onset now require conformity assessment before hospital deployment. German university hospitals are delaying pilot programs pending notified body guidance.
Patient advocacy organizations are consolidating purchasing influence through dedicated gene therapy access funds. The Sickle Cell Disease Association of America channels employer-sponsored donations toward treatment center co-pay assistance. This intermediation is displacing traditional pharmaceutical patient assistance program structures in the United States.
Sickle Cell Treatment Market Segmentation
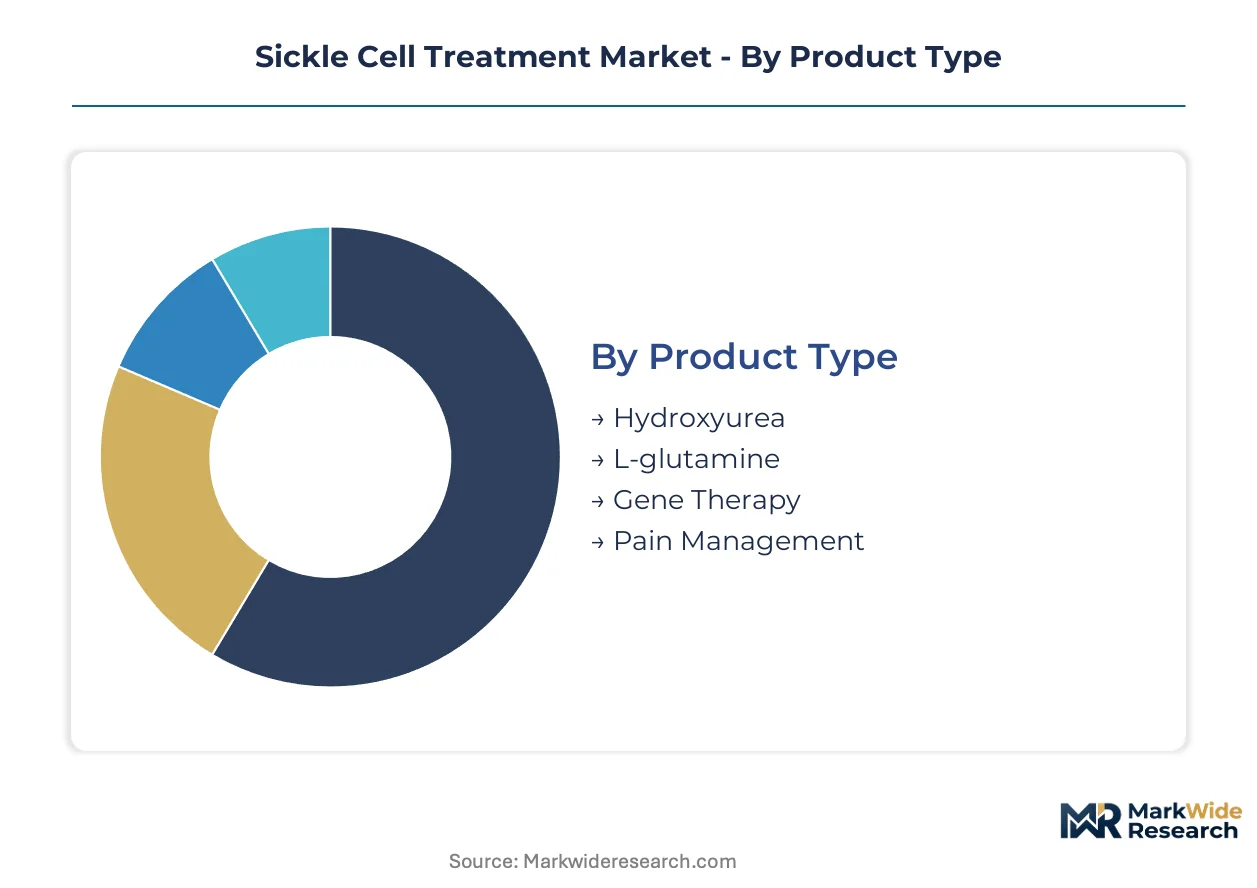
Sickle cell treatment markets fragment sharply between chronic pharmacologic management and emerging curative modalities. Channel economics differ radically: oral agents flow through retail pharmacy networks, while gene therapies require certified treatment center infrastructure with specialized cell processing capabilities.
Product Type:
Hospital procurement channels favor high-complexity curative products, while retail and specialty pharmacy networks handle chronic oral therapies. Distribution partnerships determine patient access velocity across each segment.
- Hydroxyurea:The oral ribonucleotide reductase inhibitor remains the pharmacologic backbone of chronic management, with once-daily dosing enabling broad prescriber adoption. Demand concentrates in Medicaid-covered cohorts across southeastern United States states, where disease prevalence intersects with established pharmacy benefit structures.
- Gene Therapy:CRISPR-Cas9 and lentiviral vector-based protocols deliver single-administration functional cures through ex vivo cell modification. Academic medical centers in Boston, San Francisco, and Philadelphia anchor initial commercial deployment, with FDA accelerated approval pathways compressing site certification timelines.
- L-glutamine:Oral amino acid supplementation reduces oxidative stress in red blood cells, prescribed as adjunctive therapy. Prescription volumes track hydroxyurea non-responders and pediatric populations with adherence challenges.
- Pain Management:Opioid and non-opioid analgesics address acute vaso-occlusive crises, administered across emergency departments and infusion centers. Payer scrutiny on opioid utilization shapes formulary positioning.
Hydroxyurea dominates installed base. Gene Therapy is where expansion concentrates.
End User:
Cost tier stratification separates high-acuity inpatient administration from lower-cost ambulatory and home-based delivery models.
- Hospitals:Comprehensive sickle cell centers with apheresis capabilities and stem cell transplant infrastructure anchor curative therapy delivery. Capital requirements for cell processing suites limit network expansion to major metropolitan clusters.
- Clinics:Community hematology practices manage stable chronic patients with oral therapies and routine monitoring. Volume concentrates in disease-specific centers achieving Foundation for the Accreditation of Cellular Therapy recognition.
- Home Care:Infusion nursing services and digital therapeutic platforms extend supportive care beyond facility walls. Pharmacy benefit managers pilot outcomes-linked contracts for hydroxyurea adherence programs.
- Research Institutions:Academic medical centers conduct gene therapy trials and long-term follow-up registries. FDA-mandated 15-year outcome tracking demands dedicated data infrastructure.
Hospitals capture curative therapy margin. Clinics represent the largest patient volume base.
Treatment Type:
Application urgency determines reimbursement pathway complexity, with curative modalities requiring prior authorization infrastructure distinct from chronic supportive care.
- Curative:Allogeneic stem cell transplant and autologous gene-edited cell therapies eliminate disease pathology. Payer actuarial models weigh single-administration costs against lifetime chronic care expenditures.
- Supportive:Transfusion programs, pain management protocols, and infection prophylaxis sustain patient function. This category absorbs the majority of annual sickle cell expenditure across commercial and public payers.
- Preventive:Newborn screening programs and penicillin prophylaxis in pediatric populations reduce sepsis mortality. Implementation varies by state Medicaid program infrastructure.
- Palliative:End-of-life symptom management for patients with organ failure or advanced disease complications. Hospice benefit utilization remains underdeveloped relative to disease burden.
Supportive treatment dominates expenditure volume. Curative approaches are climbing the fastest.
Administration Route:
Supply concentration for sterile injectable manufacturing shapes availability of parenteral options, while oral formulations benefit from mature generic production infrastructure.
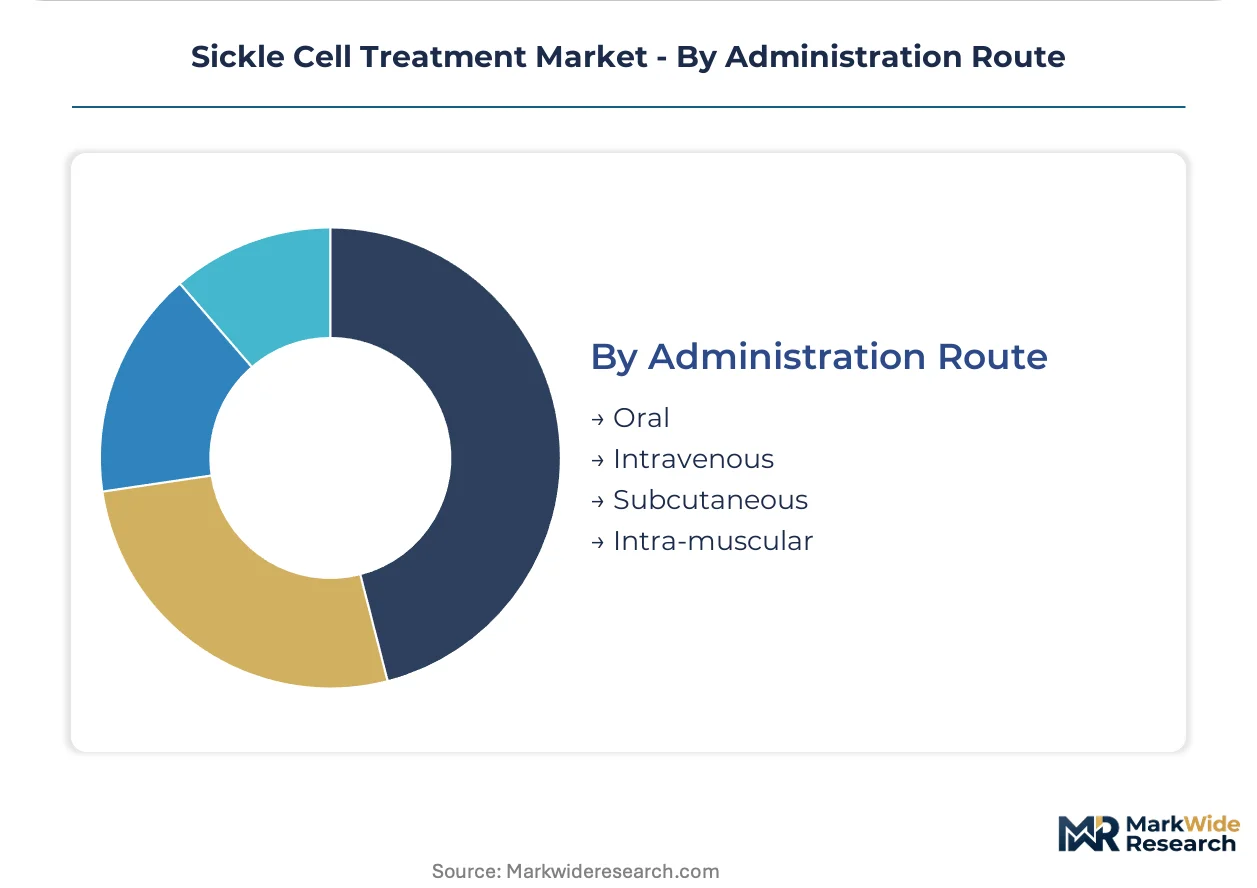
- Oral:Hydroxyurea and L-glutamine tablets enable patient self-administration and pharmacy dispensing. Formulation stability supports broad distribution without cold chain requirements.
- Intravenous:Gene therapy infusion and acute pain management require clinical supervision. Viral vector production bottlenecks at contract manufacturers constrain patient slot allocation.
- Subcutaneous:Crizanlizumab and similar monoclonal antibodies target P-selectin to reduce vaso-occlusive crisis frequency. Self-injection training programs expand ambulatory administration.
- Intra-muscular:Limited current utilization, with historical application for depot analgesic formulations. Route selection follows pharmacokinetic requirements for specific therapeutic classes.
Oral administration commands patient preference. Intravenous delivery captures curative therapy value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies with established curative therapy infrastructure and those reliant on chronic supportive care. The United States concentrates gene therapy administration in certified academic medical centers, while European markets emphasize health technology assessment gatekeeping. Sub-Saharan African markets remain anchored to hydroxyurea and transfusion programs pending infrastructure buildout.
United States
Medicaid expansion across southeastern states has removed prior authorization barriers for gene therapy, concentrating patient volume in Georgia, Mississippi, and Louisiana. FDA accelerated approval pathways compress commercialization timelines for CRISPR-based protocols. Boston, Philadelphia, and San Francisco anchor the initial treatment center network, with same-day apheresis-to-infusion workflows collapsing traditional multi-week hospitalization models.
Germany
The Institut für Qualität und Wirtschaftlichkeit im Gesundheitswesen imposes incremental evidence requirements that extend market access timelines. Hospital procurement committees prioritize outcomes-linked contracting for chronic oral therapies over single-administration curative modalities. The Rhine-Ruhr and Munich metropolitan clusters concentrate hematology-gene therapy cross-training programs at university hospitals.
France
Haute Autorité de Santé assessments create reimbursement friction for novel modalities despite EMA marketing authorization. The Paris-Saclay cluster hosts centralized cell processing facilities serving multi-site clinical trial networks. Lyon and Marseille treatment centers pilot digital therapeutic companions for hydroxyurea adherence monitoring.
United Kingdom
NHS England specialized commissioning frameworks allocate gene therapy slots through designated treatment centers in London, Birmingham, and Manchester. The National Institute for Health and Care Excellence evaluates curative therapies against lifetime chronic care cost baselines. Cambridge and Oxford academic medical centers integrate 15-year FDA-mandated follow-up registries into existing data infrastructure.
Nigeria
Newborn screening program expansion in Lagos and Abuja creates addressable cohorts previously excluded from curative therapy eligibility. Ministry of Health partnerships with international sponsors enable market development for supportive care protocols. The Lagos University Teaching Hospital anchors regional hematology referral networks serving West African patient flows.
Sickle Cell Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with pharmaceutical conglomerates leveraging rare disease infrastructure against gene therapy pure-plays. The structure bifurcates between chronic care incumbents with established payer relationships and curative modality developers requiring treatment center certification. Three archetypes dominate: diversified rare disease platforms, CRISPR-specialized biotechs, and cell therapy contract manufacturers. Competitive moves center on treatment center network expansion and long-term follow-up registry integration.
Within the diversified pharmaceutical tier, Novartis AG and Pfizer Inc. exemplify rare disease platform operators with established Medicaid and commercial payer channels. Vertex Pharmaceuticals Inc. occupies a position among gene editing specialists, representing the CRISPR-Cas9 therapeutic archetype. Bristol-Myers Squibb Company anchors the cell therapy manufacturing vector through legacy infrastructure in viral vector production.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Vertex Pharmaceuticals Inc. |
| CRISPR Therapeutics AG |
| Bluebird Bio Inc. |
| Bristol-Myers Squibb Company |
| Emmaus Medical Inc. |
| Sanofi SA |
| Editas Medicine Inc. |
| Others |
Value Network & Pricing Analysis
CRISPR-Cas9 vector systems displacing lentiviral platforms redraw manufacturing geography toward single-source bioreactor facilities in Massachusetts and North Carolina, compressing per-dose production economics while amplifying contract manufacturer pricing power over therapy developers.
Pricing Analysis
Long-term offtake agreements between gene therapy sponsors and viral vector manufacturers dominate procurement, with pricing stratifying across premium GMP-certified batches, standard clinical-grade lots, and economy research-use materials. Price differentiation hinges on FDA tier certification and apheresis-to-infusion turnaround guarantees. Cost compression in standard-grade vector production intensifies as platform standardization spreads. Medicaid-covered hospital systems exhibit highest price sensitivity, while self-insured employers funding gene therapy access programs show lowest.
Supply Chain Analysis
The United States and Switzerland anchor plasmid DNA and viral vector production, with Singapore emerging as a GMP fill-finish hub serving Asia-Pacific trial networks. Manufacturing draws from specialized cell lines, synthetic guide RNA, and cryopreservation media. Single-source vulnerability concentrates at contract manufacturers holding exclusive platform licenses. Distribution runs through certified treatment center networks with validated cold chain custody.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as allogeneic stem cell transplant centers compete for curative therapy budgets and payer actuarial favor.
For Market Incumbents: Shield market position by deepening backward integration into viral vector manufacturing to capture margin pools currently flowing to contract manufacturers. Secure Foundation for the Accreditation of Cellular Therapy certification across hospital network affiliates before competitor site expansion saturates metropolitan clusters. For New Entrants and Emerging Players: Anchor in Sub-Saharan Africa newborn screening infrastructure buildout, where ministry of health partnerships create first-mover advantage in patient identification previously excluded from eligibility. Target Nigeria and Ghana for supportive care protocol market development before curative therapy infrastructure matures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed cell therapy contract manufacturers holding GMP viral vector capacity. Five-to-ten year viability hinges on treatment center network density achieving critical mass for patient slot utilization. Monitor FDA long-term follow-up registry compliance rates as inflection signal for sustained reimbursement confidence.| Strategic Initiative | Industry Significance |
|---|---|
| Treatment Center Certification | Foundation for the Accreditation of Cellular Therapy recognition unlocks Medicaid reimbursement in southeastern United States states. |
| Viral Vector Manufacturing Scale-Up | GMP bioreactor capacity expansion at contract manufacturers reduces patient slot allocation bottlenecks. |
| Long-Term Follow-Up Registry Integration | FDA-mandated outcome tracking demands interoperable data infrastructure at academic medical centers. |
| EU AI Act Compliance Pathway | Conformity assessment for vaso-occlusive crisis prediction algorithms enables European hospital procurement. |
| Sub-Saharan Africa Partnership Model | Ministry of Health collaborations in Nigeria and Ghana establish newborn screening program market access. |
Research Methodology
The analysis maps gene therapy modalities, pharmacologic interventions, and supportive care protocols, each validated through hematology-gene therapy cross-training program directors, hospital procurement managers, payer access specialists, and cell processing technicians. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient cohort sizing and top-down expenditure flow analysis provided triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include treatment type, administration route, end-user facility tier, and regional regulatory cluster. CAGRs derived from patient population epidemiology, therapy adoption curves, and reimbursement expansion trajectories. Forecast inputs incorporated Medicaid coverage policy shifts and treatment center certification timelines.
Decision-makers should treat outputs as directional under assumptions of sustained FDA accelerated approval pathway utilization and stable viral vector manufacturing capacity expansion; material deviation in payer willingness to fund single-administration therapies would warrant model refresh. Recalibration cycles align with material shifts in health technology assessment outcomes and gene therapy long-term follow-up data maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Sickle Cell Disease Market
Hematology
Non-Hodgkin Lymphoma Treatment Market
Hematology
Hematology Analyzers Market
Hematology
Graft vs Host Disease Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Global Immunohematology Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Acute Lymphoblastic Leukemia Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Polycythemia Vera Market
Hematology
Neutropenia Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
Patient Blood Management Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
Hairy Cell Leukemia Treatment Market
Hematology
Apheresis Market