
 Primary Ciliary Dyskinesia Market | 2026-2036
Primary Ciliary Dyskinesia Market Size, Share, and Industry Trends Forecast 2026-2036
Primary Ciliary Dyskinesia Market Outlook
The United States is tilting toward expanded rare disease infrastructure for primary ciliary dyskinesia management. ReCode Therapeutics leverages lipid nanoparticle delivery platforms to target underlying genetic mutations in PCD subtypes. Vertex Pharmaceuticals anchors its position through deep expertise in cystic fibrosis translational science that extends to ciliary dysfunction biology. Parion Sciences specializes in epithelial ion channel modulators with direct relevance to mucociliary clearance restoration.
Primary ciliary dyskinesia comprises a heterogeneous group of autosomal recessive disorders characterized by defective ciliary ultrastructure and motility, with diagnostic confirmation requiring transmission electron microscopy or genetic testing for mutations in genes such as DNAH5, DNAI1, and CCDC39. The condition impairs mucociliary clearance, leading to chronic respiratory infection, bronchiectasis, and situs abnormalities as its primary clinical manifestations. Medications targeting mucus hydration and airway clearance dominate current therapeutic revenue, while diagnostic tools represent the fastest-growing segment as newborn screening protocols and genetic panels expand detection rates. Hospitals absorb the majority of diagnostic and acute therapeutic volume, though home care settings are gaining traction for long-term airway clearance device utilization.
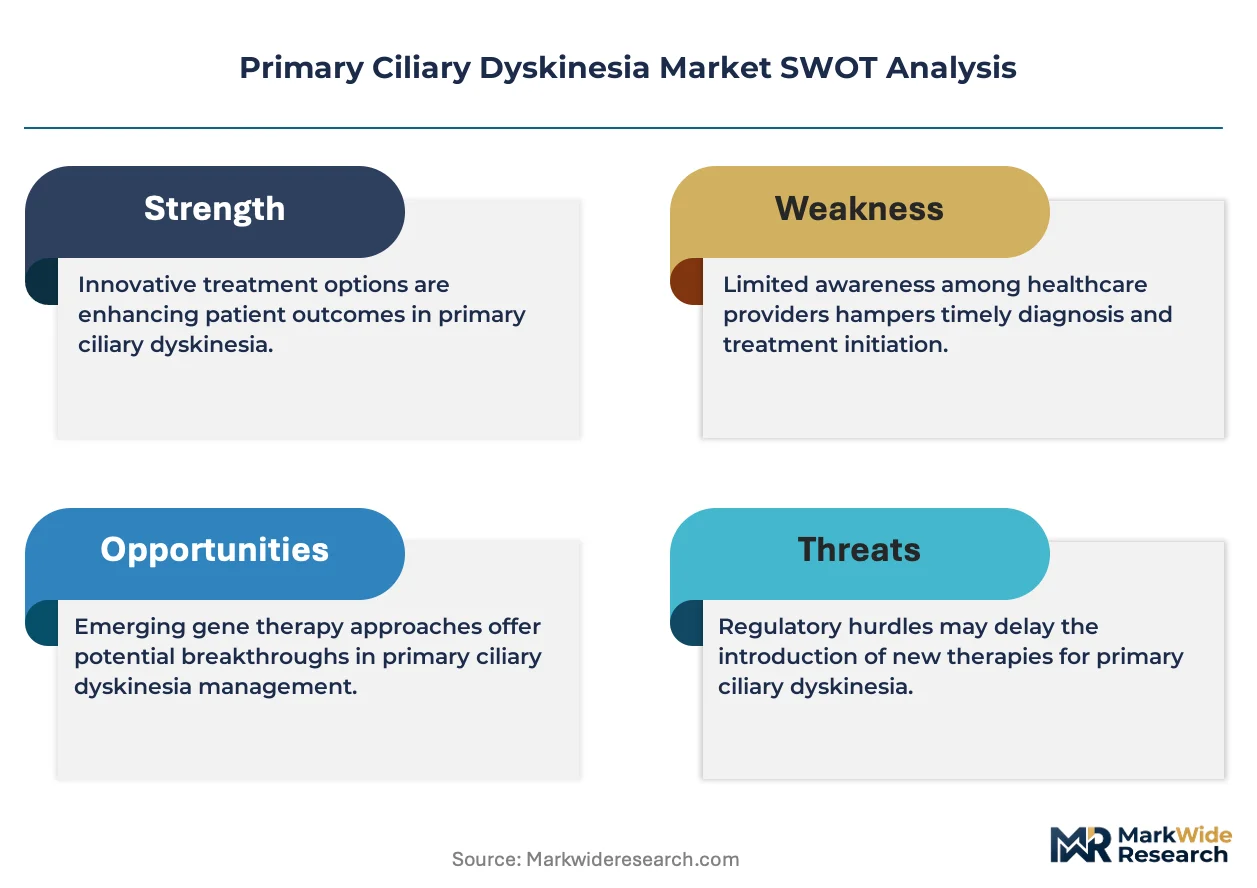
The FDA's orphan drug program and the European Medicines Agency's priority medicines scheme both shape clinical development incentives and accelerated review pathways for PCD therapeutics. Reimbursement frameworks under national health systems in Germany, France, and the United Kingdom determine patient access to high-cost genetic diagnostics and biologic therapies. Stakeholders must monitor regulatory precedent from cystic fibrosis therapy approvals to anticipate payer expectations for PCD clinical trial endpoints and value demonstration.
Market Dynamics
Genetic diagnostic panels are compressing time-to-diagnosis from years to months, fundamentally restructuring how patients enter treatment pathways and reshaping prescriber behavior across respiratory and pediatric specialties.
Growth Catalysts
- EMA Priority Medicines Scheme:Accelerated review timelines for PCD therapeutics reduce development risk and attract venture funding into rare disease programs.
- Newborn screening expansion:State-level mandates in the United States and pilot programs in Germany are embedding genetic panels into standard infant health protocols.
- Transmission electron microscopy automation:AI-assisted ultrastructural analysis is digitizing diagnostic workflows and reducing specialist pathologist dependency.
Market Restraints
- Specialized diagnostic infrastructure concentration:TEM facilities cluster in academic medical centers across Germany, the United Kingdom, and the United States, creating geographic access gaps.
- Reimbursement lag for genetic testing:National health technology assessment bodies in France and England impose multi-year evidence requirements before panel coverage.
- Small patient cohorts per mutation:Heterogeneity across DNAH5, DNAI1, and CCDC39 subtypes fragments clinical trial design and regulatory precedent.
Strategic Opportunities
- Home-based airway clearance devices:Remote monitoring integration is opening reimbursement pathways under chronic disease management frameworks.
- Japan's orphan drug incentives:PMDA consultation programs and tax credits for rare disease development are attracting Western biotech licensing activity.
- CFTR modulator knowledge transfer:Cystic fibrosis translational science is converging with ciliary biology to accelerate target validation.
Industry Challenges
- Specialized pediatric pulmonologist scarcity:Fellowship programs produce insufficient clinicians trained in ultrastructural diagnostics and longitudinal rare disease management.
- Multi-site trial coordination complexity:Patient dispersion across continents forces sponsors to maintain redundant regulatory submissions and site contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Primary Ciliary Dyskinesia Market |
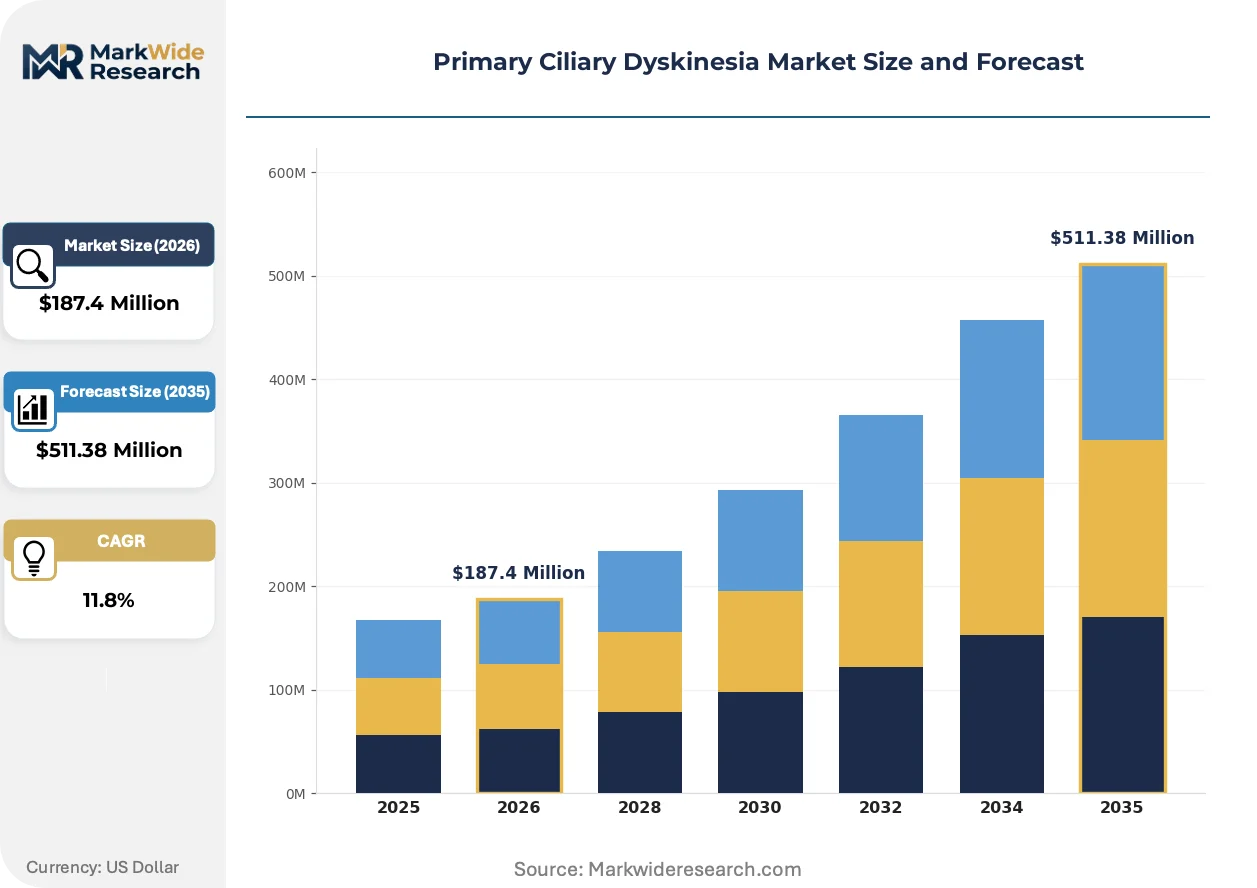
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $511.38 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Therapies, Diagnostic Tools, Supportive Devices Indication: Respiratory Infections, Chronic Sinusitis, Bronchiectasis, Fertility Issues End User: Hospitals, Clinics, Research Institutions, Home Care Settings Delivery Mode: Oral, Inhalation, Intranasal, Injectable |
| Companies Covered | ReCode Therapeutics, Parion Sciences, Vertex Pharmaceuticals, Boehringer Ingelheim, Novartis, AstraZeneca, Pfizer, Sanofi, GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Primary Ciliary Dyskinesia Market Strategic Shifts
Biomarker-driven patient stratification is replacing empirical treatment selection, while regulatory frameworks adapt to accommodate single-arm trials and real-world evidence in rare disease settings.
Next-generation sequencing platforms are digitizing mutation detection workflows across diagnostic laboratories. Tertiary care centers in the United States and Germany are adopting automated variant interpretation pipelines that compress reporting timelines from weeks to days. This compression is digitizing how payers evaluate prior authorization requests and specialist referral patterns.
The FDA's orphan drug designation pathway has expanded to include gene therapy products with accelerated manufacturing inspections. Sponsors now receive rolling review eligibility for PCD programs that demonstrate mucociliary clearance improvement in surrogate endpoints. Pediatric respiratory specialists in academic medical centers are restructuring clinical trial units to accommodate these compressed timelines.
Patient advocacy organizations are consolidating registry data to support natural history studies and regulatory submissions. Cystic fibrosis foundation networks in the United States are repurposing their data infrastructure to capture PCD longitudinal outcomes. This behavioral shift is most visible in North American and Western European markets where foundation-funded research coordinates directly with regulatory pre-submission meetings.
Primary Ciliary Dyskinesia Market Segmentation
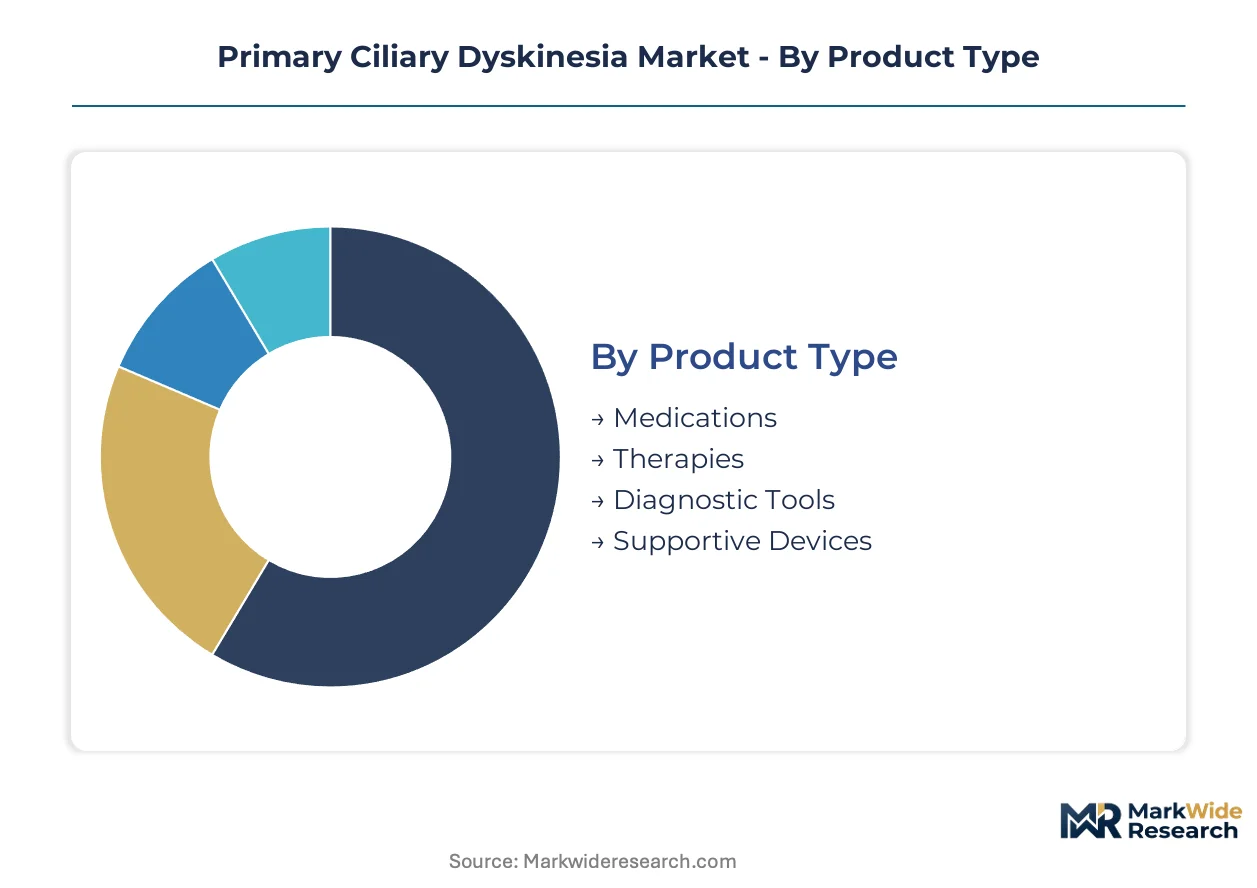
Segmentation in the Primary Ciliary Dyskinesia market determines reimbursement pathways and care delivery models. Each category reflects distinct stakeholder priorities, from diagnostic laboratories seeking automation to home care providers managing chronic airway clearance.
Product Type:
After-sales service intensity varies sharply across product categories, with diagnostic equipment demanding specialized maintenance contracts and consumable-driven segments relying on replenishment logistics.
- Medications:Mucolytics, antibiotics, and anti-inflammatory agents form the current standard of care for chronic respiratory management. Demand clusters in United States academic medical centers where specialized PCD clinics prescribe prophylactic antibiotic protocols. Reimbursement under Medicare Part D and commercial formularies shapes prescribing patterns for long-term therapy.
- Diagnostic Tools:Genetic screening panels and transmission electron microscopy services enable definitive PCD confirmation. Tertiary care centers in Germany and the United States are automating variant interpretation pipelines to compress reporting timelines. Payer prior authorization requirements for high-complexity molecular testing create administrative friction in patient access.
- Therapies:Emerging gene therapies and mucociliary clearance restoration approaches target underlying ciliary dysfunction biology. Clinical development concentrates in sponsors leveraging cystic fibrosis translational expertise.
- Supportive Devices:Oscillating positive expiratory pressure devices and high-frequency chest wall oscillation systems support daily airway clearance. Home care distribution channels are expanding as remote monitoring integration opens chronic disease management reimbursement pathways.
Medications hold the largest share; momentum sits with Diagnostic Tools.
Indication:
Cost tier stratification separates acute infection management from chronic structural disease, with fertility-related interventions occupying a distinct reimbursement category.
- Respiratory Infections:Recurrent pneumonia and bronchitis drive the majority of acute care utilization and antibiotic prescribing volume. Pediatric pulmonology practices in the United States manage these episodes through specialized PCD care centers with embedded infectious disease consultation.
- Bronchiectasis:Irreversible airway dilation represents the dominant long-term morbidity, requiring chronic airway clearance and exacerbation management. German and United Kingdom respiratory centers are standardizing physiotherapy protocols through national bronchiectasis registry networks.
- Chronic Sinusitis:Persistent sinus inflammation necessitates recurrent antibiotic courses and occasional surgical intervention. Otolaryngology referral patterns in academic medical centers coordinate with pulmonology for integrated airway management.
- Fertility Issues:Sperm immotility and fallopian tube dysfunction create distinct reproductive medicine referral pathways. Assisted reproductive technology centers handle these cases outside standard respiratory care reimbursement frameworks.
Bronchiectasis holds the largest share; momentum sits with Respiratory Infections.
End User:
Volume concentration in hospital-based settings is giving way to dispersed home care delivery as device technology enables remote monitoring.
- Hospitals:Academic medical centers absorb diagnostic confirmation, acute exacerbation management, and clinical trial enrollment. United States cystic fibrosis foundation care networks are repurposing infrastructure to capture PCD longitudinal outcomes.
- Home Care Settings:Daily airway clearance device utilization and remote physiotherapy supervision are expanding outside institutional settings. German disease management programs and United States remote patient monitoring reimbursement codes are accelerating this shift.
- Clinics:Community pulmonology practices handle stable patient follow-up and routine infection management. Specialist scarcity limits expansion outside metropolitan areas with academic affiliations.
- Research Institutions:Natural history registries and biomarker validation studies concentrate in foundation-funded networks across North America and Western Europe.
Hospitals hold the largest share; momentum sits with Home Care Settings.
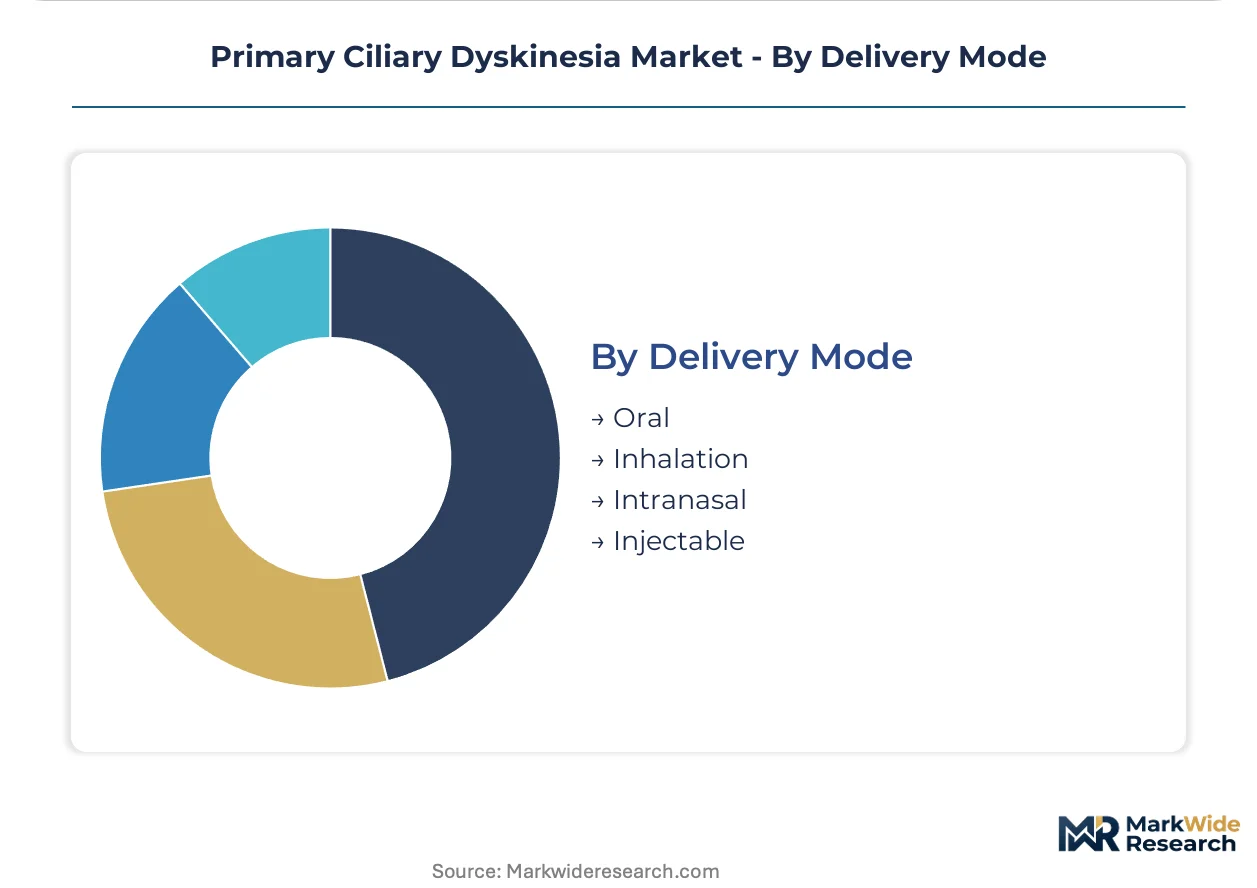
Delivery Mode:
Customer type differentiation separates chronic daily therapy from acute intervention, with inhalation and intranasal routes targeting localized airway deposition.
- Inhalation:Nebulized hypertonic saline and mucolytic agents deliver direct airway surface hydration. United States home care suppliers are integrating adherence monitoring into compressor nebulizer systems.
- Oral:Systemic antibiotics and anti-inflammatory agents support chronic prophylaxis and acute exacerbation management. Pharmacy benefit managers influence formulary placement for long-term macrolide therapy.
- Intranasal:Topical saline irrigation and corticosteroid sprays address chronic sinusitis manifestations. Otolaryngology practices prescribe these as adjuncts to systemic therapy.
- Injectable:Acute intravenous antibiotic courses treat severe exacerbations and resistant infections. Hospital outpatient infusion centers handle administration under bundled payment models.
Oral delivery holds the largest share; momentum sits with Inhalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives anchor the United States as the dominant geography for PCD therapeutic development, while specialized diagnostic infrastructure concentrates in Germany and the United Kingdom. Genetic screening expansion and newborn screening mandates are restructuring patient identification pathways across North America and Western Europe.
United States
Specialized cystic fibrosis care centers in Boston and Chapel Hill are repurposing infrastructure to capture PCD patient longitudinal outcomes. The FDA's orphan drug designation pathway accelerates clinical trial timelines for novel mucociliary clearance therapies. Vertex Pharmaceuticals and ReCode Therapeutics anchor development activity in Massachusetts and Texas innovation clusters.
Germany
Academic medical centers in Munich and Heidelberg maintain the highest concentration of transmission electron microscopy diagnostic facilities in Europe. The national disease management program framework reimburses home-based airway clearance device utilization under chronic care protocols. Bavarian and Baden-Württemberg respiratory networks standardize bronchiectasis physiotherapy through national registry coordination.
United Kingdom
The National Institute for Health and Care Excellence imposes multi-year evidence requirements before genetic panel coverage, creating reimbursement lag for diagnostic testing. London and Manchester tertiary care centers automate variant interpretation pipelines to compress reporting timelines. Cystic fibrosis foundation networks in England are repurposing data infrastructure to support PCD natural history studies.
Japan
PMDA consultation programs and tax credits for rare disease development are attracting Western biotech licensing activity into Tokyo and Osaka clinical trial units. The country's national pharmaceutical regulator streamlines orphan drug review through priority assessment pathways. Kanto region academic hospitals coordinate multi-site trials with North American sponsors to overcome patient dispersion challenges.
France
ANSM and national health technology assessment bodies coordinate prior authorization requirements for high-complexity molecular testing. Paris and Lyon academic medical centers concentrate pediatric pulmonology fellowship training programs. The Île-de-France region hosts the majority of fertility-related PCD intervention referrals outside standard respiratory care frameworks.
Primary Ciliary Dyskinesia Market Competitive Environment
Capability concentration sits with gene therapy specialists and epithelial ion channel modulators; scale advantage sits with established respiratory pharmaceutical portfolios. The market structure tiers into three archetypes: platform-technology developers targeting underlying genetic mutations, mucociliary clearance restoration specialists, and diversified respiratory portfolio holders extending cystic fibrosis expertise. Dominant competitive moves include strategic partnerships for lipid nanoparticle delivery licensing and geographic expansion through orphan drug regulatory pathway navigation.
Within the platform-technology tier, ReCode Therapeutics and Vertex Pharmaceuticals exemplify divergent approaches to genetic targeting, with the former representing lipid nanoparticle delivery specialization and the latter anchoring translational science convergence from cystic fibrosis biology. Parion Sciences occupies a distinct position among epithelial ion channel modulators. Boehringer Ingelheim and Novartis sit within the diversified pharmaceutical tier, leveraging established respiratory commercial infrastructure across European and North American markets.
| Leading Market Players |
|---|
| ReCode Therapeutics |
| Parion Sciences |
| Vertex Pharmaceuticals |
| Boehringer Ingelheim |
| Novartis |
| AstraZeneca |
| Pfizer |
| Sanofi |
| GlaxoSmithKline |
| Others |
Value Chain & Pricing Dynamics
Munich and Heidelberg academic medical centers anchor European diagnostic capacity, concentrating TEM facility operations and genetic panel processing power that translates directly into pricing leverage for high-complexity molecular testing services. This geographic concentration of specialized infrastructure creates asymmetric bargaining dynamics between consolidated diagnostic laboratories and dispersed payer networks across Germany, France, and the United Kingdom.
Pricing Analysis
Transatlantic price spreads separate United States commercial reimbursement rates from European national health system tariffs for identical genetic screening panels. Three-tier pricing structure across premium, standard, and economy levels segments by diagnostic turnaround time and genetic counselor consultation depth. Cost compression in standard-tier panels is intensifying because automated variant interpretation pipelines reduce manual pathologist hours. Academic medical centers exhibit lowest price sensitivity; community pulmonology practices in non-metropolitan United States regions demonstrate highest sensitivity to out-of-pocket diagnostic costs.
Supply Chain Analysis
Contract manufacturing for lipid nanoparticle delivery systems concentrates among specialized CDMOs in the United States, Switzerland, and Singapore with validated GMP suites for rare disease gene therapy production. Active pharmaceutical ingredient sourcing for mucolytic agents draws from established respiratory chemistry suppliers in India and Ireland. Single-source vulnerability sits with specialized ciliary biology reagent producers maintaining exclusive cell line licenses. Distribution runs through hospital-based specialty pharmacy networks and home medical equipment suppliers with respiratory therapist training capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as newborn screening data infrastructure and patient registry interoperability create network effects that compound with each additional diagnostic laboratory connection.
For Market Incumbents: Pre-empt gene therapy entrant disruption by securing exclusive lipid nanoparticle formulation partnerships with established CDMOs before clinical trial readouts. Anchor defensive positioning through backward integration into genetic testing laboratory networks, capturing patient identification upstream of therapeutic prescribing decisions. FDA rolling review eligibility for mucociliary clearance surrogates represents the critical regulatory lever to compress competitor launch windows. For New Entrants and Emerging Players: Establish a beachhead in Japanese orphan drug development through PMDA consultation program enrollment, leveraging tax credit incentives that reduce early-stage capital requirements. White-space concentration sits with home-based airway clearance device remote monitoring integration, where chronic disease management reimbursement codes remain underdeveloped relative to institutional acute care. Go-to-market execution should prioritize German disease management program contracting, where national bronchiectasis registry coordination creates consolidated procurement entry points. For Investors and Strategic Acquirers: Long-term, this sits as a platform-economics play because patient registry data infrastructure and diagnostic network effects compound competitive moats over extended horizons. Acquisition targets should display integrated capabilities spanning genetic testing laboratory operations and therapeutic development pipelines, enabling vertical capture of patient journeys from diagnosis through chronic management. The signal to watch is FDA breakthrough therapy designation grants for PCD gene therapy programs, indicating regulatory precedent formation that would accelerate comparable submissions.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway Navigation | FDA accelerated review timelines reduce development risk and attract venture funding into rare disease programs. |
| Genetic Screening Panel Automation | AI-assisted variant interpretation compresses reporting timelines from weeks to days in tertiary care centers. |
| Home Care Remote Monitoring Integration | German disease management programs and United States RPM codes expand reimbursement for daily airway clearance. |
| Lipid Nanoparticle Delivery Licensing | Specialized CDMO partnerships in Switzerland and Singapore secure manufacturing capacity for gene therapy scale-up. |
| Patient Registry Data Infrastructure | Cystic fibrosis foundation network repurposing captures longitudinal PCD outcomes for regulatory submissions. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA orphan drug designation databases, EMA priority medicines scheme records, ClinicalTrials.gov PCD program listings, and national health technology assessment body publications. Primary interviews engaged drug development executives at gene therapy sponsors, regulatory affairs leads navigating rolling review pathways, formulary directors at United States pharmacy benefit managers, and hospital procurement managers at academic medical centers with specialized PCD clinics. Bottom-up patient cohort sizing by mutation subtype triangulates against top-down market value estimates derived from reimbursement rate analysis across Medicare Part D, commercial formularies, and European national health system tariffs.
Forecast inputs incorporate treatment line progression from diagnostic confirmation through chronic management, dosage form differentiation between nebulized and oral delivery, administration route stratification across inhalation and intranasal categories, and regional regulatory clustering by FDA, EMA, and PMDA jurisdiction. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs include newborn screening mandate adoption timelines by United States state and genetic panel automation deployment curves in German and United Kingdom tertiary care centers.
Stress conditions across regulatory approval timeline variability, genetic testing reimbursement lag duration, and specialized pediatric pulmonologist supply constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding orphan drug incentive continuity and diagnostic infrastructure investment trajectories. Payer prior authorization requirement tightening and multi-site trial coordination complexity represent primary revision risks. Quarterly review of FDA breakthrough therapy designation grants and EMA PRIME scheme eligibility decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bulimia Nervosa Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Leukemia Inhibitory Factor (LIF) Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Anaplastic Large Cell Lymphoma (ALCL) Therapeutics Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
China Precision Medicine Market
Specialty Medicine
Global Post Traumatic Stress Disorder (PTSD) Therapeutics Market
Specialty Medicine
Global Plasma Protease C1 Inhibitor Treatment Market
Specialty Medicine
Carcinoid Syndrome Diarrhea Treatment Market
Specialty Medicine
North America Dry Eye Syndrome Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Gerontology/Aging Market
Specialty Medicine
Bipolar Disorder Therapeutics Market