
 Sanitary Pumps Market | 2026-2036
Sanitary Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitary Pumps Market Outlook
The EU Green Deal's industrial emissions benchmarks is pivoting European dairy processors toward pumps with verified clean-in-place validation. Alfa Laval AB dominates stainless steel centrifugal designs for high-temperature pasteurization lines. SPX Flow, Inc. specializes in modular pump skids that reduce installation downtime in greenfield plants. GEA Group Aktiengesellschaft leverages its German engineering base to sustain premium positioning in aseptic filling applications.
Sanitary pumps are positive-displacement or kinetic machines constructed from 316L stainless steel or FDA-compliant polymers, designed with surface finishes below 0.8 micrometers Ra to eliminate bacterial adhesion during food, pharmaceutical, or biotech fluid transfer. Centrifugal pumps lead volume in liquid transfer duties across large-scale dairy operations where continuous flow dominates, while peristaltic pumps capture the fastest growth in biotechnology fill-finish lines requiring disposable fluid paths. Diaphragm pumps anchor margin pools in pharmaceutical applications where metal contamination risks mandate polymer-wetted construction.
The FDA enforces 3-A Sanitary Standards and EHEDG guidelines for hygienic equipment design, compelling pump manufacturers to validate cleanability through standardized soil tests. EMA's Annex 1 revisions on sterile manufacturing push European pharmaceutical buyers toward pumps with fully drainable housings and seal-less magnetic drives. Stakeholders must monitor evolving material certification requirements for recycled stainless steel content as the EU CSRD disclosure rules extend upstream into capital equipment supply chains.
Market Dynamics
The FDA's Food Safety Modernization Act enforcement is compressing cleanability validation timelines, forcing pump manufacturers to accelerate surface finish testing and 3-A Sanitary Standards certification cycles before equipment deployment.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:European pharmaceutical facilities are replacing conventional sealed pumps with fully drainable magnetic-drive designs to eliminate contamination risks in aseptic filling operations.
- Biotechnology fill-finish expansion:Single-use peristaltic pumps with disposable fluid paths are capturing demand from cell therapy manufacturers requiring rapid batch changeover without cross-contamination.
- Wisconsin and California dairy clusters:Processing capacity expansions in these states are driving centrifugal pump orders for high-temperature pasteurization lines with clean-in-place validation.
Market Restraints
- 316L stainless steel price volatility:Nickel and molybdenum input cost swings are compressing margin pools for pump housings and impellers, particularly affecting small-batch pharmaceutical equipment producers.
- German engineering labor concentration:Premium aseptic pump design expertise clusters around Frankfurt and Ludwigshafen, creating supply bottlenecks for complex magnetic-drive configurations.
- Polymer-wetted diaphragm limitations:PTFE and EPDM elastomer fatigue life constraints restrict continuous-duty pharmaceutical applications, forcing redundant pump installations.
Strategic Opportunities
- EU CSRD recycled content mandates:Capital equipment disclosure rules are creating first-mover advantage for pump manufacturers certifying recycled stainless steel supply chains ahead of upstream supplier deadlines.
- Modular skid integration:Greenfield dairy and beverage plants are specifying pre-validated pump skids that compress installation timelines and reduce commissioning labor costs.
- Cell and gene therapy manufacturing:Disposable fluid path pumps are penetrating this emerging biotech segment where metal contamination risks and batch flexibility requirements exclude conventional designs.
Industry Challenges
- Clean-in-place validation expertise scarcity:Dairy and pharmaceutical facilities face shortages of technicians capable of executing standardized soil tests and documenting EHEDG-compliant cleanability.
- Surface finish metrology capex:Profilometer investments required for sub-0.8 micrometer Ra verification are straining quality control budgets at mid-tier pump fabricators.
- Legacy control system integration:Magnetic-drive pumps with advanced sensor packages require protocol translation to connect with existing SCADA infrastructure in retrofit pharmaceutical facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitary Pumps Market |
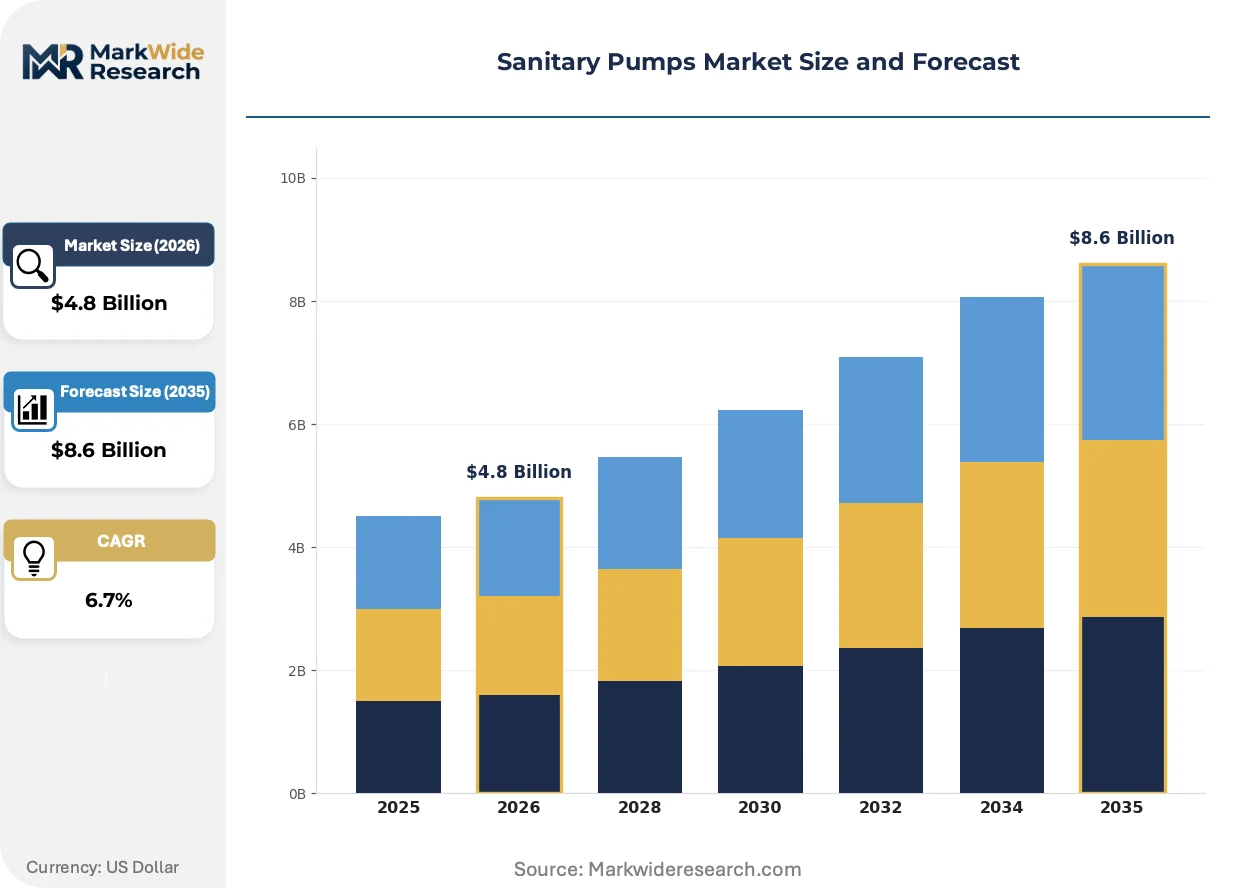
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Peristaltic Pumps, Centrifugal Pumps, Gear Pumps End User: Food Processing, Pharmaceuticals, Biotechnology, Personal Care Material: Stainless Steel, Plastic, Alloy, Rubber Application: Liquid Transfer, Mixing, Heating, Filtering |
| Companies Covered | Flowserve Corporation, Grundfos Holding A/S, Alfa Laval AB, Inoxpa S.A., Dover Corporation, SPX Flow, Inc., KSB SE & Co. KGaA, Spirax-Sarco Engineering plc, GEA Group Aktiengesellschaft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitary Pumps Market Strategic Shifts
Sanitary pump engineering is pivoting toward seal-less magnetic drive architectures and single-use disposable fluid paths, with regulatory pressure on sterile manufacturing cleanability accelerating technology substitution cycles.
Magnetic-drive centrifugal pumps are electrifying high-temperature pasteurization lines by eliminating mechanical seals and their associated contamination risks. Dairy processors in Wisconsin and California are specifying these designs for continuous-duty operations exceeding 24 hours. The technology is electrifying competitive positioning by compressing maintenance intervals and enabling longer validated production runs between clean-in-place cycles.
The EU Green Deal's industrial emissions benchmarks are pivoting European dairy processors toward pumps with verified energy efficiency and clean-in-place validation documentation. EMA Annex 1 revisions on sterile manufacturing are simultaneously mandating fully drainable housings for pharmaceutical applications. German pharmaceutical manufacturers around Frankfurt are responding by pre-qualifying magnetic-drive suppliers against combined EHEDG and 3-A Sanitary Standards.
Service contract unbundling is reshaping how pharmaceutical facilities acquire pump maintenance capabilities. Large-scale biotechnology manufacturers are separating equipment purchase from validation support, creating specialized third-party service channels. This pattern is most visible in California's cell therapy manufacturing corridor, where facilities outsource clean-in-place protocol development to independent validation specialists.
Sanitary Pumps Market Segmentation
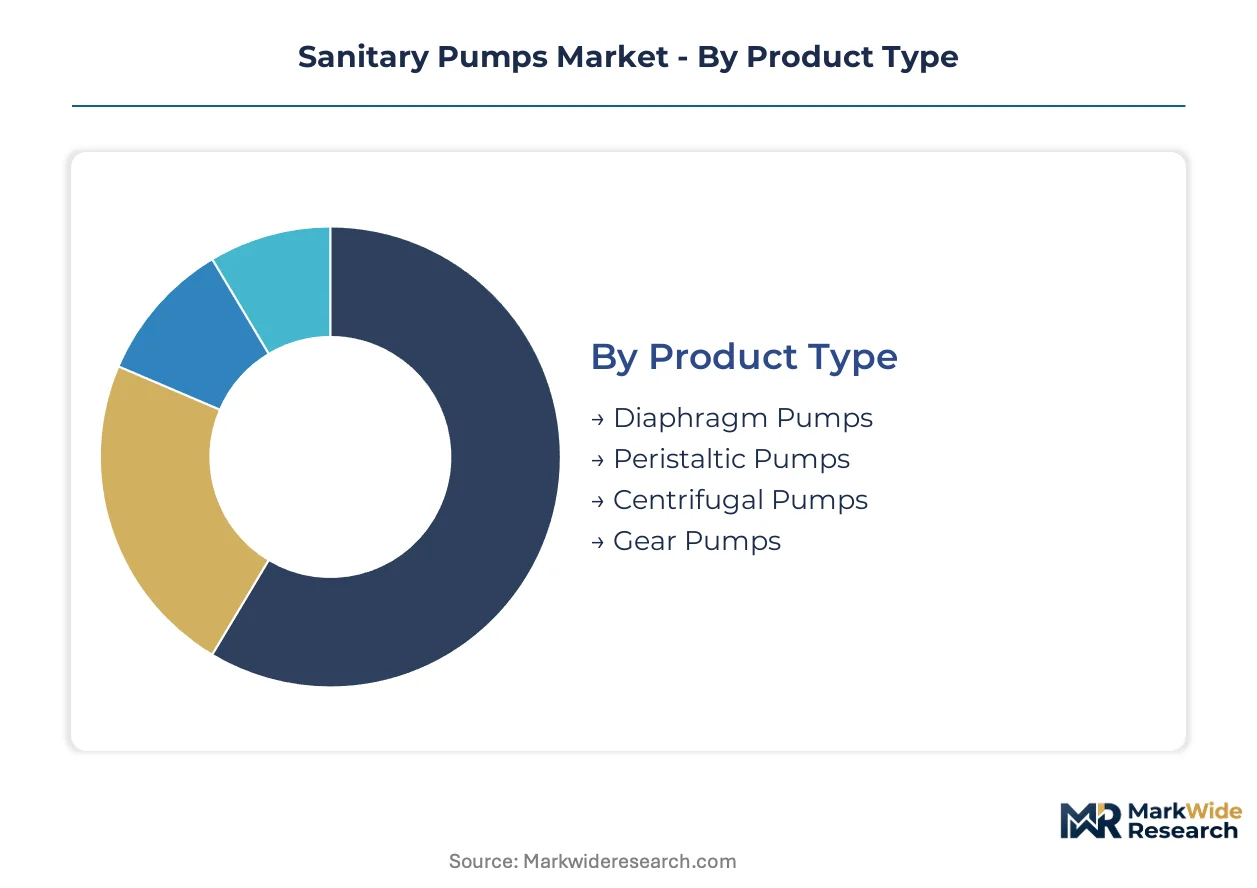
Sanitary pump procurement decisions hinge on cleanability validation requirements that vary sharply across product architectures and end-use environments. Segmentation reveals where FDA 3-A Sanitary Standards, EMA Annex 1 sterile manufacturing rules, and EHEDG guidelines impose distinct certification burdens on equipment categories.
Product Type:
Certification intensity diverges across pump architectures, with sterile manufacturing applications demanding magnetic-drive validation while dairy operations prioritize clean-in-place documentation.
- Centrifugal Pumps:Kinetic machines with 316L stainless steel wetted surfaces and surface finishes below 0.8 micrometers Ra dominate high-temperature pasteurization lines. Wisconsin and California dairy processors specify these for continuous 24-hour operations where clean-in-place cycles compress maintenance windows.
- Peristaltic Pumps:Positive-displacement designs with disposable fluid paths capture biotechnology fill-finish demand. Cell therapy manufacturers in California's manufacturing corridor specify these for rapid batch changeover without cross-contamination risks.
- Diaphragm Pumps:Polymer-wetted construction eliminates metal contamination in pharmaceutical applications.
- Gear Pumps:Precision volumetric delivery suits viscous personal care formulations.
Centrifugal pumps sit at the top of the volume ranking, with peristaltic pumps climbing the fastest.
End User:
Margin structures align with regulatory stringency, where pharmaceutical and biotechnology buyers absorb premium pricing for sterile manufacturing compliance.
- Pharmaceuticals:Aseptic filling operations around Frankfurt and Ludwigshafen mandate fully drainable magnetic-drive pumps under EMA Annex 1 revisions. German facilities pre-qualify suppliers against combined EHEDG and 3-A Sanitary Standards.
- Biotechnology:Cell and gene therapy manufacturing excludes conventional metal-contact designs. Single-use fluid path pumps penetrate this segment where batch flexibility requirements override capital equipment economics.
- Food Processing:Dairy expansions in Wisconsin and California drive centrifugal pump orders with validated clean-in-place protocols.
- Personal Care:Viscous product handling favors positive-displacement architectures with polymer compatibility.
Pharmaceutical procurement commands the steepest pricing tier, while biotechnology represents the most rapid application expansion.
Material:
Supply chain configuration determines cost volatility exposure, with nickel and molybdenum input swings compressing margins for stainless steel fabricators.
- Stainless Steel:316L grade dominates dairy pasteurization and pharmaceutical aseptic applications. Surface finish verification below 0.8 micrometers Ra requires profilometer investments that strain mid-tier fabricator quality control budgets.
- Plastic:PTFE and EPDM elastomer constructions eliminate metal contamination risks in biotechnology disposable fluid paths. Fatigue life constraints restrict continuous-duty pharmaceutical applications.
- Alloy:Specialized corrosion resistance serves aggressive chemical processing environments.
- Rubber:Flexible diaphragm and tubing components enable peristaltic pump disposable paths.
Stainless steel anchors the installed base by volume, with plastic gaining share fastest in single-use biotechnology adoption.
Application:
Functional requirements map to pump architecture selection, where continuous versus batch operating modes dictate kinetic versus positive-displacement technology choices.
- Liquid Transfer:High-volume dairy operations specify centrifugal designs for continuous flow dominance. Clean-in-place validation compresses downtime between production runs.
- Mixing:Shear-sensitive biotechnology formulations demand controlled agitation without mechanical seal contamination risks.
- Heating:High-temperature pasteurization lines integrate pumps with thermal processing equipment.
- Filtering:Precision flow control supports membrane separation processes in pharmaceutical purification.
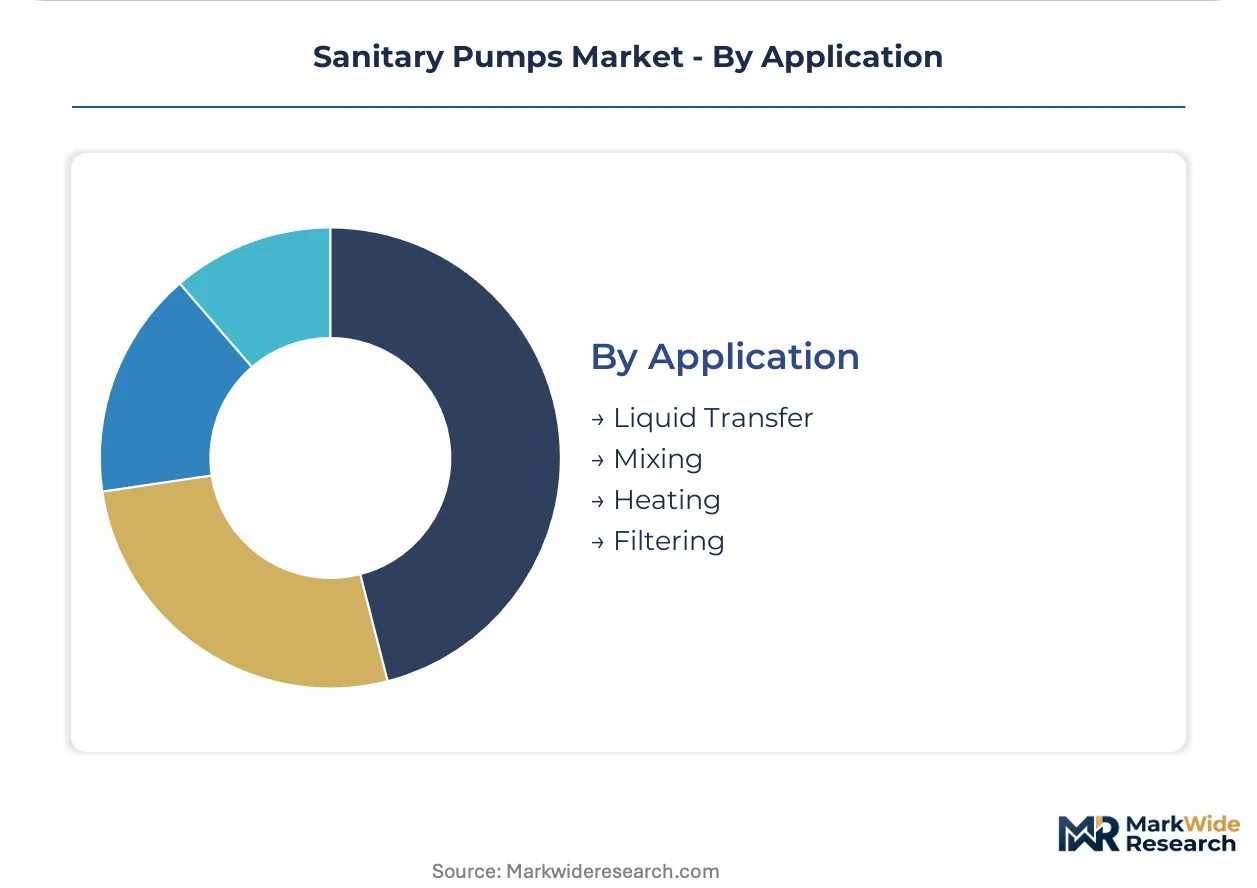
Liquid transfer commands the largest application footprint, with mixing applications expanding most quickly in biotechnology process intensification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent clusters around Frankfurt and Ludwigshafen anchor premium aseptic pump design capabilities. Wisconsin and California dairy processing expansions concentrate North American demand. Chinese pharmaceutical manufacturing investments reshape Asia-Pacific procurement patterns.
United States
Dairy processing capacity expansions in Wisconsin and California drive centrifugal pump orders for high-temperature pasteurization lines. FDA Food Safety Modernization Act enforcement compresses cleanability validation timelines for equipment deployments. California's cell therapy manufacturing corridor specifies single-use peristaltic pumps for rapid batch changeover without cross-contamination risks.
Germany
Pharmaceutical manufacturing around Frankfurt and Ludwigshafen mandates fully drainable magnetic-drive pumps under EMA Annex 1 sterile manufacturing revisions. EU Green Deal industrial emissions benchmarks pivot dairy processors toward pumps with verified clean-in-place validation. German facilities pre-qualify suppliers against combined EHEDG and 3-A Sanitary Standards certification requirements.
China
Biotechnology fill-finish expansion creates demand for disposable fluid path pumps in cell therapy manufacturing. NMPA sterile manufacturing guidelines tighten cleanability requirements for pump surfaces in pharmaceutical applications. Yangtze River Delta pharmaceutical clusters specify magnetic-drive designs to eliminate contamination risks in aseptic operations.
India
Domestic dairy processing modernization drives centrifugal pump procurement for continuous pasteurization operations. CDSCO pharmaceutical manufacturing standards elevate cleanability documentation requirements for capital equipment. Maharashtra and Gujarat food processing clusters expand hygienic fluid handling capacity to serve export markets.
Switzerland
Precision pharmaceutical manufacturing sustains premium positioning for aseptic filling pump suppliers. Swissmedic sterile product guidelines mandate fully drainable housings and seal-less magnetic drives. Basel-area biotech facilities specify pumps with sub-0.8 micrometer Ra surface finishes to eliminate bacterial adhesion risks.
Sanitary Pumps Market Competitive Environment
Capital-heavy producers compete with asset-light designers across sanitary pump supply. The vendor base stratifies between integrated stainless steel fabricators with captive foundry operations and specialized designers outsourcing casting and machining. Three archetypes dominate: European engineering-centric premium suppliers, Asian scale-driven fabricators, and North American modular skid integrators. Competitive moves center on M&A for magnetic-drive technology access and greenfield capacity expansion near dairy processing clusters.
Among European engineering-centric suppliers, Alfa Laval AB and GEA Group Aktiengesellschaft exemplify premium-tier positioning anchored in Scandinavian and German manufacturing heritage. SPX Flow, Inc. occupies a position within the North American modular integration archetype. These three represent distinct strategic postures: European precision engineering heritage versus American system integration capabilities versus diversified industrial conglomerate scale.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Grundfos Holding A/S |
| Alfa Laval AB |
| Inoxpa S.A. |
| Dover Corporation |
| SPX Flow, Inc. |
| KSB SE & Co. KGaA |
| Spirax-Sarco Engineering plc |
| GEA Group Aktiengesellschaft |
| Others |
Value Chain & Pricing Dynamics
EU CSRD recycled content mandates gate qualified supply and premium-tier pricing access for pump manufacturers certifying recycled 316L stainless steel supply chains ahead of upstream supplier deadlines. German pharmaceutical facilities around Frankfurt pre-qualify magnetic-drive suppliers against combined EHEDG and 3-A Sanitary Standards, compressing validated supplier pools and sustaining pricing power for certified fabricators.
Pricing Analysis
The bundled-vs-unbundled service split separates equipment purchase from validation support across pharmaceutical procurement. Three-tier pricing structure across premium, standard, and economy levels aligns with certification intensity, where EMA Annex 1 sterile manufacturing compliance commands steepest premiums. Cost compression in standard-tier centrifugal pumps is intensifying because nickel and molybdenum input swings compress margin pools for small-batch producers. Biotechnology buyers show least price sensitivity due to batch flexibility requirements overriding capital equipment economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Wisconsin and California dairy clusters, while specialized distributors serve mid-tier pharmaceutical fabricators. Supply concentrates in Germany for precision magnetic-drive engineering, China for stainless steel casting capacity, and the United States for modular skid integration. Raw material dependencies rest on nickel and molybdenum for 316L housings, PTFE and EPDM for polymer-wetted diaphragms, and rare-earth magnets for seal-less drives. Single-source vulnerability clusters around Frankfurt-area engineering talent for complex aseptic configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sanitary pumps market functions as a stable compounder, with FDA Food Safety Modernization Act enforcement and EMA Annex 1 revisions sustaining replacement demand across regulated processing facilities.
For Market Incumbents: Anticipate margin pressure from nickel and molybdenum volatility by securing captive supply of 316L stainless steel through backward integration into recycled content certification. Defend positioning by accelerating clean-in-place validation expertise development ahead of technician scarcity bottlenecks in dairy and pharmaceutical facilities. For New Entrants and Emerging Players: Begin with disposable fluid path peristaltic pumps for California's cell therapy manufacturing corridor, where metal contamination risks exclude conventional designs and batch flexibility requirements override incumbent relationships. Pursue modular skid pre-validation partnerships with greenfield dairy processors to compress installation timelines against established competitors. For Investors and Strategic Acquirers: Roll-up economics work for specialized magnetic-drive engineering boutiques because German talent concentration around Frankfurt and Ludwigshafen creates acquisition scarcity value for sterile manufacturing capabilities. Monitor NMPA guideline tightening in China's Yangtze River Delta as inflection indicator for Asia-Pacific demand migration toward certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Stainless Steel Certification | EU CSRD mandates create first-mover advantage for validated supply chain documentation ahead of upstream deadlines. |
| Magnetic-Drive Technology Acquisition | EMA Annex 1 sterile manufacturing revisions displace conventional sealed pumps with fully drainable seal-less designs. |
| Modular Skid Pre-Validation | Greenfield dairy plants in Wisconsin and California specify pre-validated pump skids to compress commissioning labor costs. |
| Disposable Fluid Path Development | Cell therapy manufacturers require single-use peristaltic pumps for rapid batch changeover without cross-contamination risks. |
| Clean-in-Place Validation Services | Service contract unbundling creates specialized third-party channels for protocol development in California's biotech corridor. |
Study Parameters
Multiple input streams — technical interviews with plant engineers and maintenance directors, regulatory affairs consultations with FDA and EMA compliance leads, and aftermarket service head discussions — were reconciled against secondary validation from 3-A Sanitary Standards documentation, EHEDG guideline publications, and SEC filings from listed pump manufacturers. Bottom-up sizing of centrifugal, peristaltic, and diaphragm pump deployments across dairy, pharmaceutical, and biotechnology facilities was cross-checked against top-down industry association estimates.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include pump architecture, end-use regulatory intensity, material grade tier, and regional manufacturing cluster. CAGRs were derived from installed base turnover rates and capacity expansion pipelines. Forecast inputs incorporated FDA enforcement timeline acceleration and EMA Annex 1 implementation pacing for sterile manufacturing compliance.
Several conditions sit outside the modeled scope, including abrupt nickel price spikes beyond historical volatility bands and trade policy disruptions affecting 316L stainless steel tariff structures. Forecasts reflect base-case assumptions about regulatory enforcement continuity and cleanability validation standard stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
United States Positive Displacement Pumps Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Regenerative Turbine Pump Market
Pumps and Control Devices
Mud Pumps Market
Pumps and Control Devices
Radial Piston Pumps Market
Pumps and Control Devices
Subsea Pump System Market
Pumps and Control Devices
Slurry Pumps Market
Pumps and Control Devices
Dewatering Pumps Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market
Pumps and Control Devices
Vertical Turbine Pumps Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Hydraulic Pumps Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Vane Pump Market