

3-Way Pilot Operated Directional Control Valves Market Size, Share, and Industry Trends Forecast 2026-2036
3-Way Pilot Operated Directional Control Valves Market Insights
Germany's precision hydraulics manufacturing base is tilting toward higher-specification pilot operated valves for industrial automation. Bosch Rexroth leverages its Stuttgart-area engineering depth to dominate proportional technology development. Parker Hannifin anchors North American supply through vertically integrated cartridge manufacturing. HAWE Hydraulik specializes in compact, high-pressure designs that serve mobile equipment OEMs.
Three-way pilot operated directional control valves regulate fluid flow paths between three ports using a pilot pressure signal to shift a main-stage spool, typically handling pressures from 210 to 420 bar in industrial hydraulic circuits. These valves enable precise actuator control in automated machinery where intermediate flow positions are required. Solenoid operated variants occupy the largest installed base across factory automation, while proportional technology captures expanding margin pools in closed-loop motion control. Pneumatic pilot configurations lead packaging equipment applications where clean, dry air systems predominate. Hydraulic pilot types sustain demand in construction plants and agricultural machinery operating under high-load, contaminated conditions.
ISO 4401 porting standards and CE marking requirements under the EU Machinery Directive shape product interoperability and market access across European manufacturing. EPA leak detection mandates and OSHA hydraulic safety regulations in the United States tighten specifications for seal materials and pressure containment. China's GB standards and NMPA-equivalent equipment certifications add compliance layers for imported valve assemblies. Stakeholders must monitor how regional carbon-border adjustments and embodied-emissions tracking reshape sourcing decisions for cast-iron valve bodies and copper coil windings.
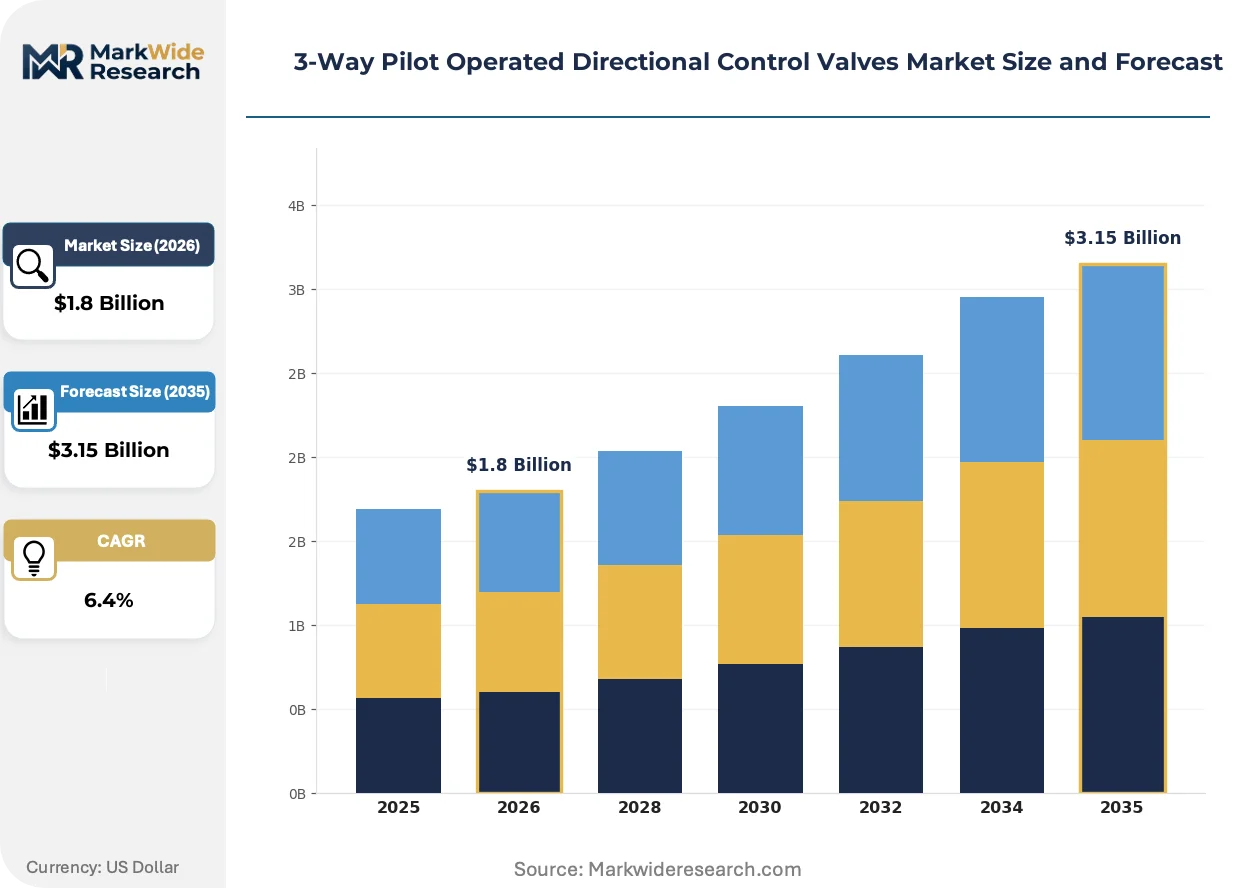
Market Dynamics
The EU F-Gas Regulation is compressing acceptable leakage thresholds for hydraulic sealing systems, forcing manufacturers to redesign pilot valve architectures around fluoropolymer alternatives and metal-to-metal sealing interfaces. This single mandate is restructuring R&D priorities across the European industrial automation supply base.
Growth Catalysts
- Construction machinery electrification:Battery-powered excavators and loaders require compact pilot valves with lower standby losses, creating specification upgrades across OEM supply chains.
- REACH restrictions on PFAS:The European Chemicals Agency's phasedown of perfluorinated seal materials is accelerating validation programs for hydrogenated nitrile and thermoplastic elastomer alternatives.
- Proportional control adoption:Closed-loop motion systems in German packaging lines and machine tools are displacing on-off solenoid architectures with continuously variable spool positioning.
Market Restraints
- Cast iron supply concentration:Ductile iron body casting capacity clusters in Chinese foundries and select German suppliers, creating vulnerability to energy cost volatility and export licensing delays.
- Copper coil winding costs:Solenoid actuator production depends on copper price exposure that has compressed margin structures for standard-duty valve variants.
- Technical limitation in high-frequency cycling:Pilot stage response times below 15 milliseconds remain difficult to achieve without proportional servo-valve architectures that carry 3-4x cost premiums.
Strategic Opportunities
- Indian industrial corridor penetration:The Delhi-Mumbai Industrial Corridor's smart manufacturing zones lack established hydraulic component suppliers, opening distribution partnerships for compact cartridge valve assemblies.
- Regulatory tailwind from EU Green Deal:Embodied carbon tracking requirements favor locally manufactured valve bodies over Asian imports, rewarding European production footprint expansion.
- IoT convergence with hydraulic systems:Integration of pressure transducers and edge computing modules into pilot valve manifolds enables predictive maintenance services that unbundle hardware from recurring software revenue.
Industry Challenges
- Proportional valve calibration expertise:The shift from digital on-off to analog closed-loop control requires servohydraulics technicians that OEM field service organizations struggle to recruit and retain.
- CE marking timeline compression:The EU Machinery Directive's expanded noise and safety documentation requirements extend certification cycles by 4-6 months for new pilot valve platforms.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Way Pilot Operated Directional Control Valves Market Trends and Innovations
Digital twin technology is virtualizing valve development workflows, compressing prototype iterations and enabling remote commissioning of hydraulic circuits before physical installation.
Digital hydraulic valve architectures replace discrete solenoid banks with software-defined flow control, reducing component count by 60-70% in complex manifold assemblies. Mining equipment OEMs in Australia and Chile are piloting these systems for shovel and dragline applications. The technology is virtualizing traditional hardware redundancy strategies, replacing physical backup valves with algorithmic fault detection and graceful degradation modes.
The EU F-Gas Regulation's 2027 leakage threshold reduction is mandating sealed-for-life pilot stages and welded rather than threaded port connections across mobile hydraulic applications. Industrial valve manufacturers serving construction and agriculture must redesign seal grooves and surface finishes to achieve sub-1 gram annual loss rates. German and Italian OEMs are responding fastest, leveraging existing precision machining capabilities to qualify new sealing systems before the compliance deadline.
Aftermarket service unbundling is fragmenting traditional distributor relationships as end-users source seal kits and spool cartridges directly from manufacturer digital platforms. North American factory automation integrators now combine original equipment procurement with captive repair capabilities, bypassing authorized distributor networks for consumable components. This pattern is most pronounced in automotive stamping plants and tire manufacturing facilities where downtime costs exceed $50,000 per hour.
3-Way Pilot Operated Directional Control Valves Market Segmentation
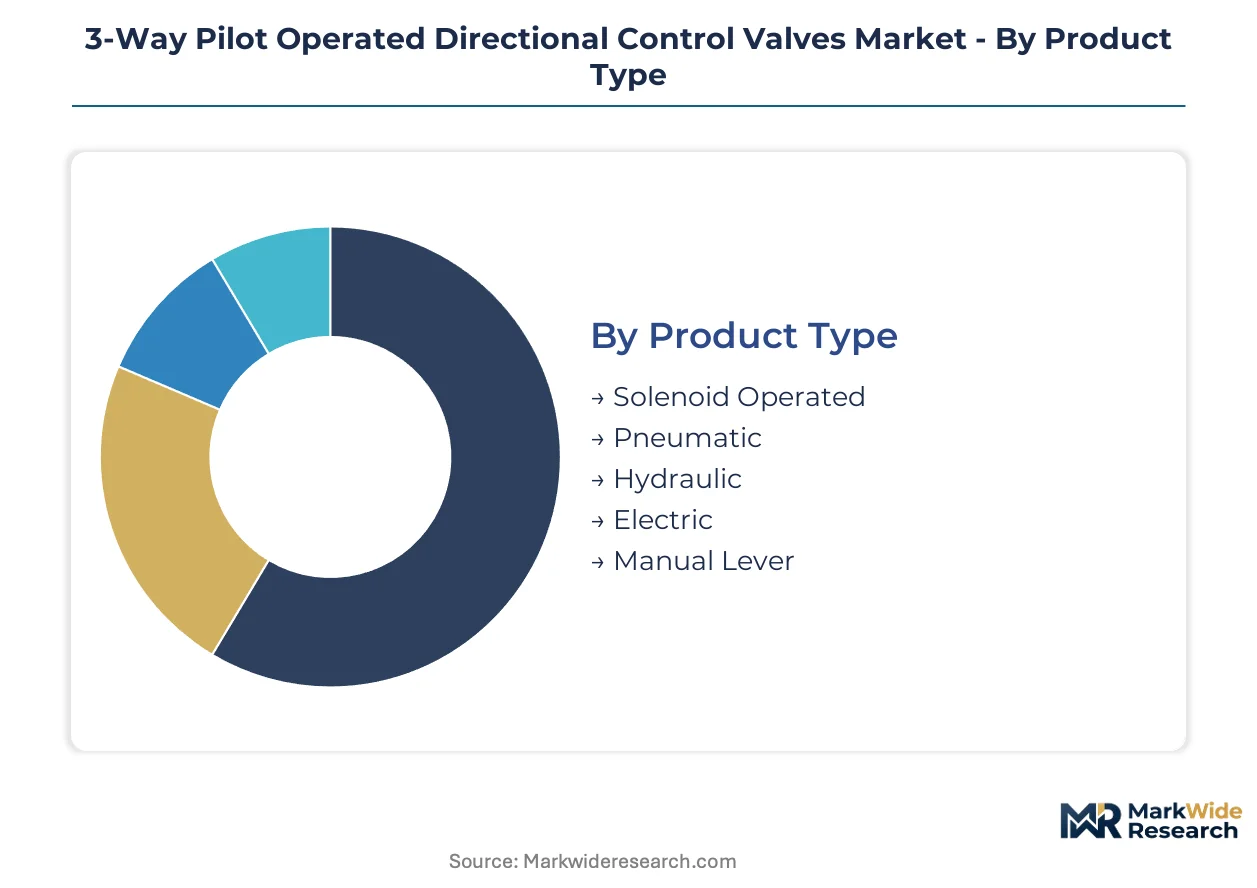
Three-way pilot operated directional control valves fragment across actuation methods, control architectures, and end-use intensities. Each segmentation axis reveals distinct margin structures, certification requirements, and supply chain configurations that shape procurement decisions across industrial automation.
Product Type:
Solenoid operated variants anchor the mature installed base while pneumatic and hydraulic pilots occupy specialized niches with diverging growth trajectories.
- Solenoid Operated:Electromagnetic actuation dominates factory automation with response times under 30 milliseconds and standardized 24V DC coil configurations. German automotive stamping lines and Japanese machine tool OEMs specify these for high-frequency cycling sequences where deterministic switching matters more than flow proportionality.
- Hydraulic:Pilot pressure from the main circuit shifts the main-stage spool without external power, sustaining demand in construction plants and agricultural machinery where electrical infrastructure is unreliable or explosive atmospheres prohibit solenoids. Contamination tolerance and sub-zero operability keep hydraulic pilots essential in mining and forestry equipment.
- Pneumatic:Clean dry air actuation serves packaging equipment and food processing lines where oil-free operation is mandatory. Lower force output limits these to lighter-duty circuits under 100 bar.
- Electric:Servomotor-driven spool positioning eliminates hysteresis for closed-loop motion control in semiconductor manufacturing and medical device assembly. Higher cost and complexity restrict penetration to precision-critical segments.
- Manual Lever:Direct mechanical override and maintenance bypass functions persist in safety-critical marine and oilfield applications. Operators retain these for emergency isolation despite automation trends.
Solenoid operated retains volume leadership; electric holds the steepest expansion curve.
Technology:
Control sophistication stratifies from binary switching to continuous position modulation, with cost premiums expanding across the capability ladder.
- On-Off:Binary spool positioning commands full flow or complete blockage, saturating legacy factory automation where intermediate actuator speeds are unnecessary. Simple coil-and-spring architectures minimize procurement cost and field service complexity for standard-duty machinery.
- Proportional:Variable spool positioning enables infinite flow adjustment through PWM coil control, displacing servo valves in mid-precision German packaging lines and Italian plastics machinery. Closed-loop feedback with onboard electronics captures margin expansion as OEMs consolidate manifold complexity.
- Servo:Zero-lapped spool geometries and high-frequency response below 5 milliseconds serve flight simulators, turbine controls, and defense platforms where tracking accuracy exceeds proportional capabilities. Prohibitive cost and filtration requirements constrain adoption.
- Step:Digitally indexed spool positions approximate proportional control through discrete switching, bridging cost-performance gaps in emerging Asian manufacturing markets.
- Pilot Operated:The foundational architecture using pilot pressure to shift main-stage elements, implemented across all product types above. Miniaturization trends push pilot stages into cartridge formats for integrated manifold designs.
On-Off commands the largest installed base; proportional is climbing the fastest as closed-loop motion control standardizes.
Application:
Load severity and duty cycle intensity separate applications into stationary automation versus mobile equipment with diverging reliability requirements.
- Construction Plants:Excavator boom, bucket, and swing circuits demand pilot valves rated to 350 bar with contamination-hardened spool geometries. Battery-electric machine development is compressing package sizes and standby loss specifications across OEM supply chains.
- Packaging Equipment:High-speed carton forming and palletizing lines in Bavaria and Emilia-Romagna specify pneumatic and low-pressure hydraulic pilots with ISO 4401 subplate mounting. Cycle rates exceeding 60 per minute prioritize response consistency over pressure capacity.
- Material Handling:Forklift mast control and automated guided vehicle steering circuits balance cost against durability in 24-hour warehouse operations. Reach truck manufacturers in Baden-Württemberg specify proportional cartridges for smooth load positioning.
- Agricultural Machinery:Tractor loader and harvester header controls operate under dust exposure and temperature swings that stress seal materials. Hydraulically piloted monoblock valves dominate this segment.
- Robotics:Collaborative arm joints and mobile manipulators require compact pilot valves with integrated position feedback for force-controlled interaction. Semiconductor cleanroom and surgical robot applications impose particulate and outgassing constraints.
Construction plants sustain the heaviest volume throughput; robotics is gaining share fastest on precision automation expansion.
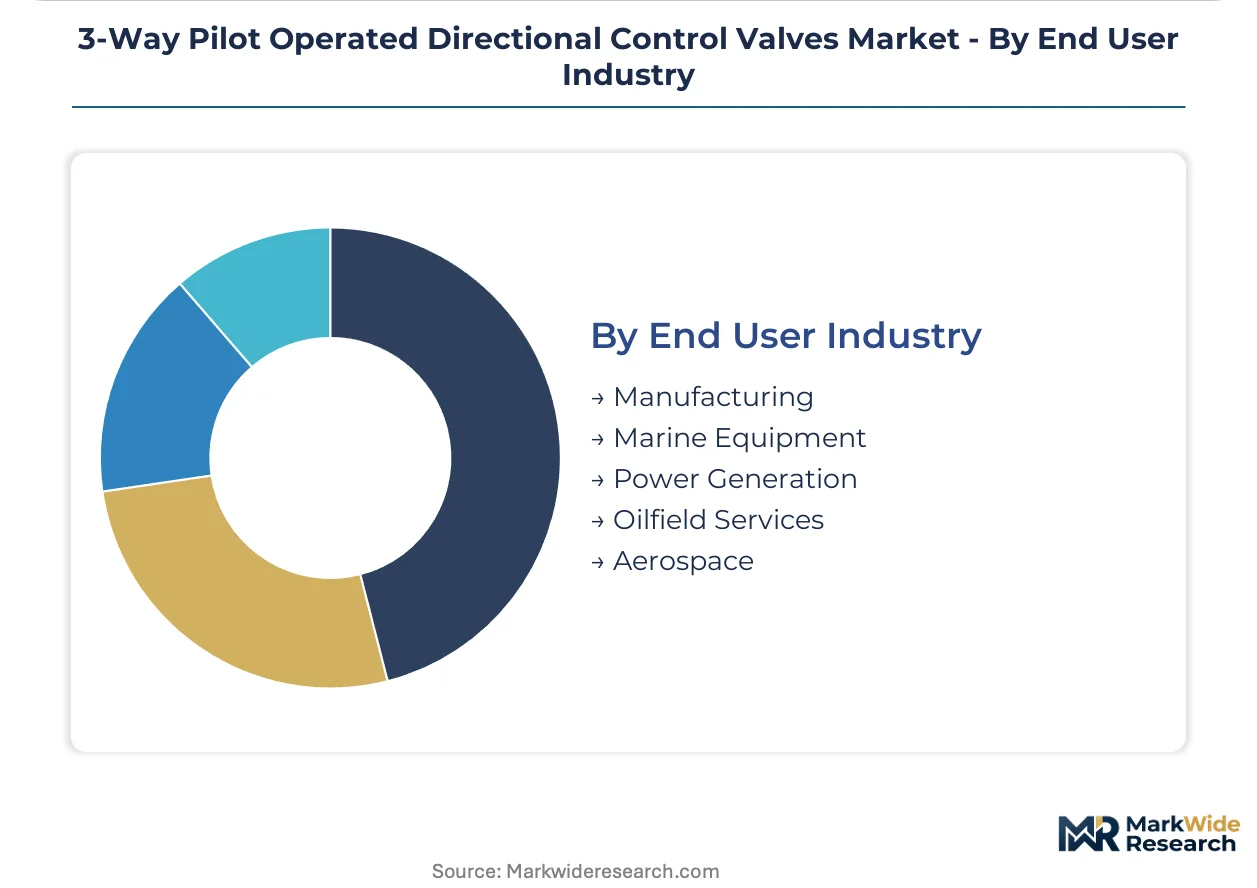
End User Industry:
Regulatory exposure and asset criticality stratify end users from commodity manufacturing to safety-certified aerospace with order-of-magnitude price tolerance spreads.
- Manufacturing:General machinery and automotive production lines in Stuttgart and Turin consume standardized solenoid and proportional valves through distributor networks. Volume concentration enables three-tier pricing stratification across premium certified, standard industrial, and economy unbranded tiers.
- Aerospace:Flight control and landing gear systems demand DO-160 environmental qualification and traceable material certification. AS9100 quality systems and FAA/EASA dual approvals create 5-10 year supplier development timelines that lock incumbents against price competition.
- Oilfield Services:BOP control systems and wellhead intervention equipment require NACE-compliant materials for sour gas exposure. API 16D certification and subsea pressure ratings concentrate supply among Norwegian and Scottish specialists.
- Power Generation:Hydroelectric turbine governors and steam valve actuators need fail-safe positioning and seismic qualification. Long replacement cycles and utility procurement procedures favor established supplier relationships.
- Marine Equipment:Classification society rules from DNV, Lloyd's Register, and ABS govern materials and testing for propulsion and cargo handling systems. Corrosion-resistant coatings and redundant pilot channels address saltwater exposure and single-failure criteria.
Manufacturing retains volume leadership; aerospace holds the steepest expansion curve on next-generation aircraft programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network underwrites Germany's centrality in precision hydraulics manufacturing, while the Port of Shanghai's container throughput anchors Chinese foundry supply chains for valve castings.
United States
Shale field hydraulic fracturing fleets and agricultural machinery OEMs in Iowa and Illinois sustain demand for contamination-hardened pilot valves. EPA leak detection mandates under the Clean Air Act tighten seal specifications for mobile equipment. Houston's oilfield services cluster concentrates procurement of NACE-compliant valve assemblies for sour gas exposure.
Germany
Stuttgart's automotive stamping lines and Bavarian packaging machinery OEMs specify proportional pilot valves for closed-loop motion control. EU F-Gas Regulation leakage thresholds force redesigns of pilot stage architectures. Baden-Württemberg's precision machining ecosystem qualifies fluoropolymer sealing alternatives ahead of 2027 compliance deadlines.
China
Construction machinery electrification in Xuzhou and battery-electric excavator programs drive compact valve specifications. GB standards and NMPA-equivalent certifications layer compliance requirements on imported assemblies. Yangtze River Delta foundries supply ductile iron valve bodies to domestic and export markets.
Japan
Machine tool OEMs in Nagoya and semiconductor capital equipment manufacturers specify ultra-clean pilot valves for precision automation. METI industrial efficiency programs incentivize lower standby loss designs. Kanto region integrators combine hydraulic and electromechanical actuation in collaborative robotics.
India
The Delhi-Mumbai Industrial Corridor's smart manufacturing zones lack established hydraulic component suppliers, opening distribution gaps for compact cartridge assemblies. BIS certification requirements and DGFT import procedures shape procurement timelines. Pune and Chennai automotive clusters generate pull for standardized solenoid valves.
3-Way Pilot Operated Directional Control Valves Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in manifold and cartridge fabrication. Market structure concentrates around diversified motion control conglomerates with captive hydraulics divisions, while mid-scale specialists occupy niche pressure ratings and regional aftermarket channels. Three archetypes dominate: vertically integrated full-line suppliers, focused cartridge valve engineers, and pneumatic-hydraulic crossover manufacturers. Competitive moves center on geographic expansion through distribution partnerships and technology licensing for digital hydraulic architectures.
Among diversified motion control conglomerates, Emerson Electric Co., Parker Hannifin, and Bosch Rexroth exemplify the full-line archetype spanning industrial automation, mobile equipment, and energy sectors. These entities anchor premium-tier positioning through integrated electronics and software-enabled service offerings. Mid-scale specialists such as HAWE Hydraulik and Sun Hydraulics occupy focused positions in high-pressure compact designs and cartridge valve engineering respectively. The competitive terrain rewards backward integration into coil winding and casting capabilities, while digital twin development and IoT-enabled predictive maintenance reshape differentiation vectors.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Parker Hannifin |
| Bosch Rexroth |
| Eaton |
| HAWE Hydraulik |
| Sun Hydraulics |
| Daikin Industries |
| IMI |
| SMC Corporation |
| Others |
Pricing and Supply Chain Analysis
Chinese foundry concentration for ductile iron valve bodies concentrates margin capture downstream with OEMs and tier-one distributors who control specification-setting relationships. Copper coil winding costs for solenoid actuators and fluoropolymer seal materials under EU F-Gas pressure now determine tier boundaries between economy, standard, and premium valve assemblies.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by mandating sealed-for-life pilot stages and welded port connections that add 15-25% manufacturing cost premiums. Pricing stratifies across premium certified, standard industrial, and economy unbranded tiers, with AS9100 aerospace qualification and API 16D oilfield certification commanding 3-5x multiples over general machinery specifications. Cost compression in standard-duty solenoid variants is intensifying because copper price volatility has eroded supplier margins. Automotive stamping plants and tire manufacturing facilities show lowest price sensitivity due to downtime costs exceeding $50,000 per hour, while general machinery OEMs in emerging Asian markets drive procurement toward economy tiers.
Supply Chain Analysis
Ductile iron feedstock draws from Yangtze River Delta foundries in China, select German suppliers in Baden-Württemberg, and scattered Italian casting operations. Copper coil windings, fluoropolymer seals, and precision-machined spool cartridges constitute the critical input trinity. Single-source vulnerability clusters in Chinese foundry capacity expose the supply base to energy cost volatility and export licensing delays. Distribution runs through authorized distributor networks for original equipment, though aftermarket service unbundling now lets end-users source seal kits and spool cartridges directly from manufacturer digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital hydraulic architectures are shifting valve economics from hardware margins toward software-enabled service platforms, with interoperability standards determining ecosystem lock-in. This platform transition rewards first movers who integrate edge computing modules into pilot valve manifolds.
For Market Incumbents: Insulate proportional valve margins by deepening backward integration into coil winding and cartridge manufacturing capabilities. Capture certification investment returns by accelerating EU F-Gas compliance qualification ahead of 2027 deadlines. Defend against digital hydraulic disintermediation by bundling predictive maintenance software with hardware procurement contracts.
For New Entrants and Emerging Players: Build out distribution partnerships in the Delhi-Mumbai Industrial Corridor where established hydraulic component suppliers remain scarce. Target compact cartridge valve assemblies for battery-electric construction machinery OEMs seeking lower standby loss specifications. Pursue white-label manufacturing relationships with German packaging machinery OEMs requiring ISO 4401 subplate mounting compatibility.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial automation conglomerates seeking to monetize hydraulics divisions amid electrification headwinds. Five-to-ten year viability hinges on software service revenue attach rates rather than hardware shipment volumes. Watch for inflection signals in proportional valve calibration technician scarcity, which indicates servohydraulics capability gaps that acquisition targets could fill.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Development | Bosch Rexroth and Parker Hannifin compress prototype iterations through virtual commissioning workflows. |
| Sealed-for-Life Pilot Stage Redesign | German and Italian OEMs leverage precision machining to qualify fluoropolymer alternatives before EU F-Gas deadlines. |
| IoT Module Integration | Edge computing embedded in valve manifolds enables predictive maintenance services that unbundle hardware from recurring software revenue. |
| Backward Integration into Casting | Captive ductile iron foundry capacity insulates against Chinese supply concentration and energy cost volatility. |
| Regional Production Footprint Expansion | EU Green Deal embodied carbon tracking favors locally manufactured valve bodies over Asian imports. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade association filings, customs databases, and regulatory disclosure archives. Interviews with maintenance directors at automotive stamping plants, OEM procurement teams at construction machinery manufacturers, aftermarket service heads at fluid power distributors, and plant engineers at packaging equipment facilities grounded demand-side validation. SEC 10-K filings, EU ECHA substance restriction notices, ISO standard revision drafts, and national industrial production statistics provided supply-side triangulation. Bottom-up valve shipment estimates and top-down industrial automation capex flows were cross-referenced for convergence.
Forecast inputs span actuation method, control technology tier, application intensity, and end-user industry regulatory exposure across the analysis window. Segment-level CAGRs emerged from installed base turnover rates, replacement cycle compression, and specification upgrade elasticities. Construction machinery electrification programs, REACH PFAS restriction timelines, and proportional control adoption curves in German packaging lines shaped scenario-weighted projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital hydraulic platform entrants or battery-electric OEMs verticalizing valve supply would shift outcomes. Cross-checking against fluid power trade association shipment benchmarks and industrial automation capex survey data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.