
 Pipeline Integrity Management (PIM) Market | 2026-2036
Pipeline Integrity Management (PIM) Market Size, Share, and Industry Trends Forecast 2026-2036
Pipeline Integrity Management (PIM) Market Analytics
Digital twin integration is tilting how pipeline operators model asset degradation in real time. Baker Hughes Company leverages proprietary simulation software to anchor its position in predictive analytics services. SGS S.A. competes through its extensive geographic laboratory network that sustains cross-border certification workflows. ROSEN Group specializes in high-resolution inline inspection tools that dominate challenging subsea and unpiggable pipeline geometries.
Pipeline Integrity Management encompasses the systematic framework of technologies, processes, and services designed to ensure continuous safe operation of pipeline infrastructure through defect detection, risk quantification, and remediation scheduling. The discipline relies on inline inspection tools operating at specified pressure ratings, electromagnetic sensors detecting wall-thickness variations down to fractions of a millimeter, and fiber optic cables measuring strain and temperature disturbances along thousands of kilometers. Inspection services command the largest revenue share within the service type dimension, while fiber optics represents the fastest-expanding technology category as distributed acoustic sensing penetrates both new-build and retrofit installations. The oil and gas end user segment retains the deepest spending pool, though water utilities are emerging as a structurally underpenetrated vertical with accelerating capital deployment.
PHMSA in the United States mandates comprehensive integrity management programs for pipelines in high-consequence areas, directly shaping vendor qualification requirements and inspection frequencies. The EPA's spill prevention regulations and OSHA process safety standards further tighten operational compliance obligations across the North American installed base. Stakeholders must weigh capital allocation between incremental sensor deployment and full platform modernization as regulatory thresholds for detectable defect sizes continue tightening without corresponding timeline extensions.
Market Dynamics
Digital twin deployment is compressing inspection cycles from quarterly to continuous monitoring, forcing midstream operators to restructure capital allocation between sensor hardware and predictive software platforms.
Growth Catalysts
- PHMSA integrity management mandates:US pipeline operators in high-consequence areas must maintain documented inspection programs, creating sustained demand for inline assessment tools and fiber optic monitoring systems.
- Permian Basin infrastructure density:Concentrated gathering networks in West Texas and southeastern New Mexico require coordinated integrity programs across multi-operator corridors.
- Distributed acoustic sensing:Fiber optic cables installed during new construction or retrofitted onto existing lines detect third-party intrusion, leaks, and ground movement without pipeline shutdown.
Market Restraints
- Specialized sensor supply concentration:High-fidelity electromagnetic transducers and photonic components rely on limited manufacturing capacity in East Asia, creating vulnerability to trade friction.
- Legacy pipeline metallurgy:Pre-1980s vintage lines with unknown seam types and corrosion histories resist standard inline inspection tool passage, forcing costly direct assessment alternatives.
- Specialized technician scarcity:Qualified analysts capable of interpreting magnetic flux leakage data and ultrasonic thickness readings command premium compensation, inflating service delivery costs.
Strategic Opportunities
- Water utility vertical expansion:Municipal transmission mains and wastewater force mains remain structurally underpenetrated by formal integrity management frameworks.
- Carbon capture pipeline networks:CO2 transport infrastructure under development in the US Gulf Coast and North Sea corridors will require corrosion monitoring adapted to supercritical fluid chemistry.
- AI-driven predictive maintenance:Machine learning models trained on historical failure databases enable transition from time-based to condition-based intervention scheduling.
Industry Challenges
- Data integration complexity:Operators struggle to normalize inspection data formats across multiple inline inspection vendors and legacy SCADA architectures.
- Certification timeline compression:Third-party qualification of new inspection technologies under API 1163 and similar frameworks lags behind commercial availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipeline Integrity Management (PIM) Market |
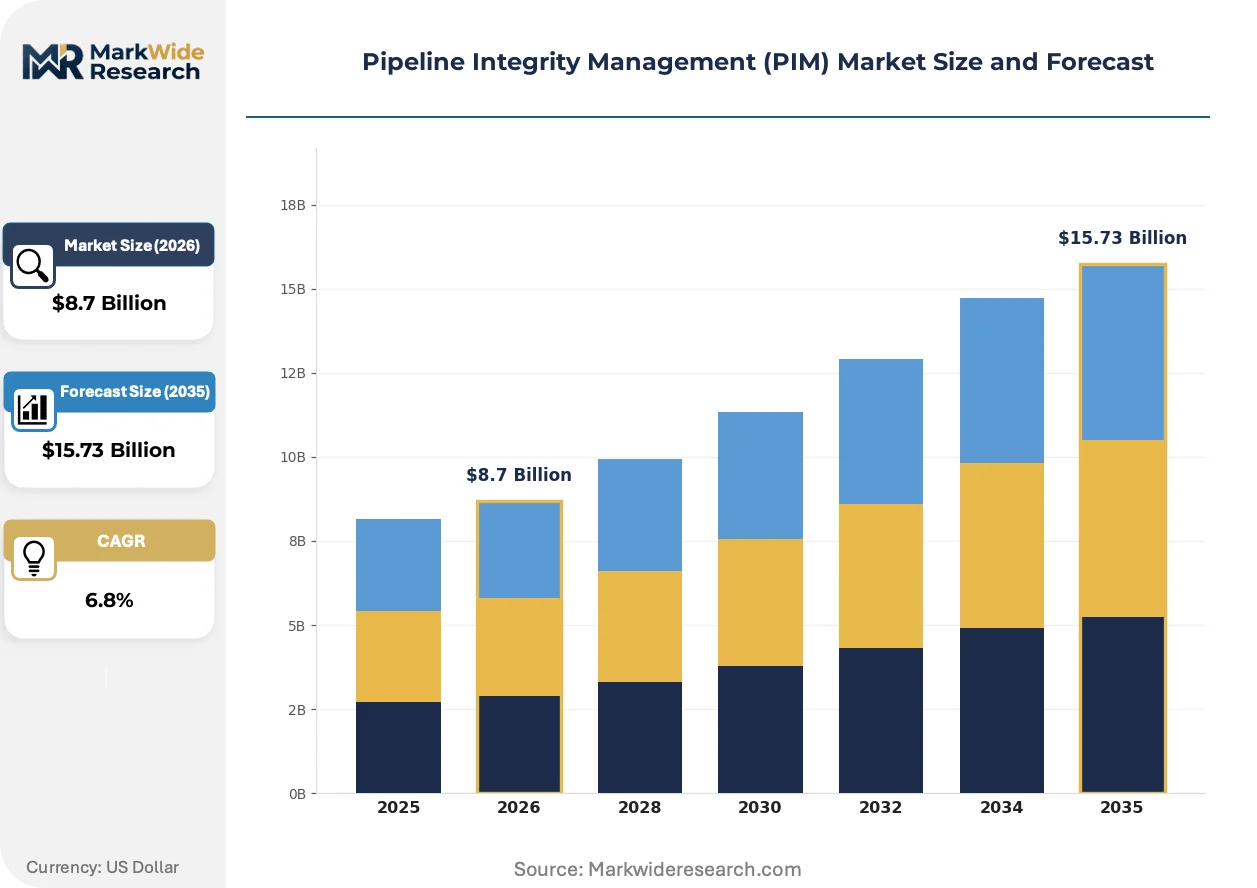
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Maintenance, Monitoring, Risk Assessment Technology: Ultrasonic, Magnetic Flux Leakage, Smart Pigs, Fiber Optics End User: Oil & Gas, Water Utilities, Chemical Plants, Energy Sector Application: Corrosion Management, Leakage Detection, Condition Assessment, Compliance |
| Companies Covered | T.D. Williamson, Inc., SGS S.A., Baker Hughes Company, Intertek Group plc, Bureau Veritas S.A., ROSEN Group, Applus+ S.A., NDT Global, MISTRAS Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipeline Integrity Management (PIM) Market Evolving Landscape
Sensor fusion architectures are collapsing the distinction between discrete inspection campaigns and continuous monitoring, embedding intelligence directly into pipeline infrastructure rather than treating assessment as a periodic service event.
Ultrasonic phased array sensors paired with fiber optic strain monitoring are hybridizing into unified hardware packages. Midstream operators in the Permian Basin and US Gulf Coast are deploying these integrated systems on new-build gathering lines. This convergence is hybridizing procurement patterns, as buyers now specify combined sensor suites rather than contracting separate electromagnetic and acoustic vendors.
PHMSA's updated leak detection and repair regulations are tightening response-time thresholds for hazardous liquid pipelines. Operators must now demonstrate capability to identify and locate releases within tighter windows. High-consequence area pipelines face the most stringent requirements, driving adoption of real-time monitoring platforms that can trigger automated valve closure sequences.
Asset owners are unbundling integrity services from traditional engineering procurement contracts. Major pipeline operators now directly contract specialized inspection firms for recurring assessment programs, bypassing generalist construction managers. This disintermediation is most pronounced in North American unconventional basins, where producers maintain dedicated integrity teams that source technology and execution separately.
Pipeline Integrity Management (PIM) Market Segmentation
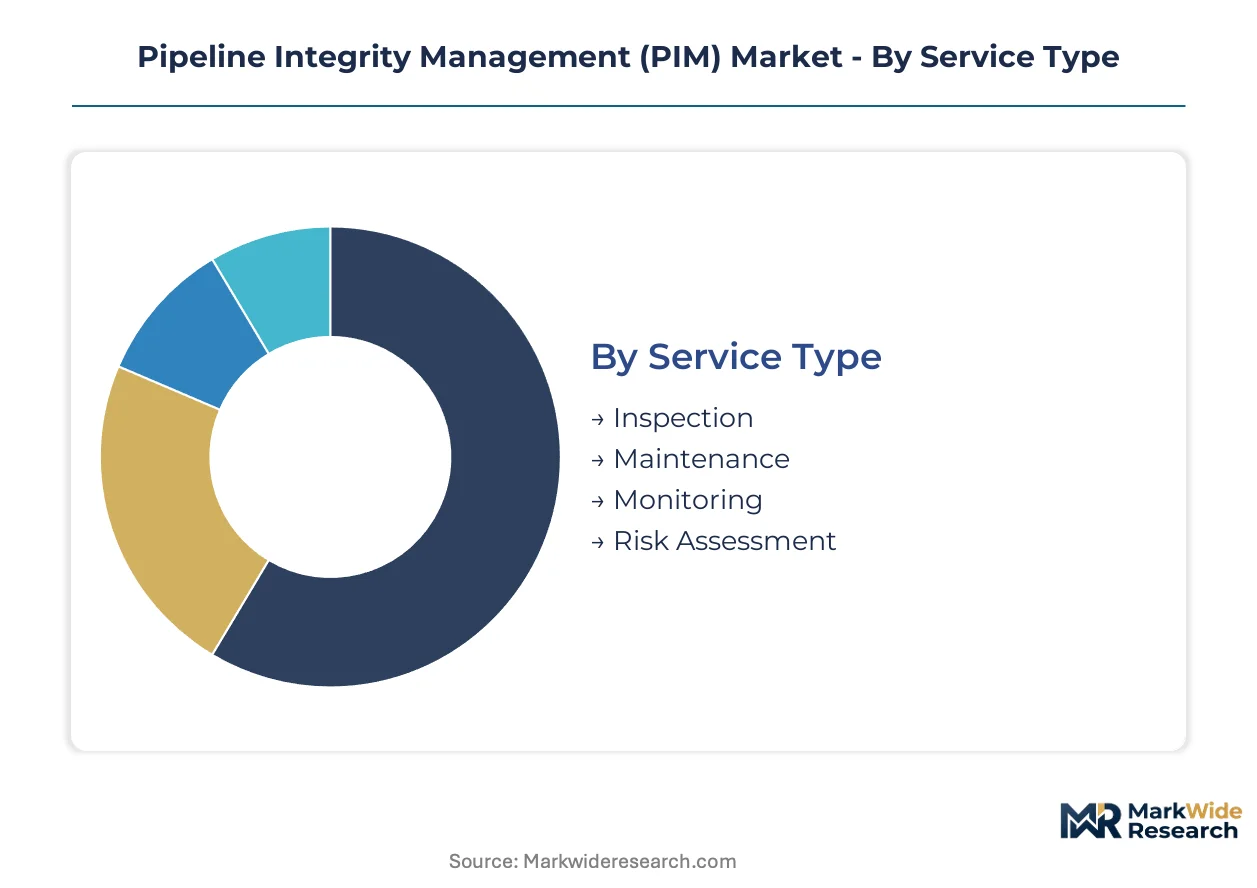
Pipeline integrity management vendors structure their offerings across four intersecting dimensions that determine procurement patterns and margin profiles. Service delivery models, sensing technologies, end-user verticals, and application focus areas each create distinct competitive arenas with specialized qualification requirements.
Service Type:
Mature inspection protocols anchor the revenue base while predictive monitoring services are accelerating fastest as operators shift from scheduled campaigns to continuous oversight.
- Inspection:Inline assessment tools traverse pressurized pipelines to detect metal loss, cracks, and geometric anomalies through magnetic flux leakage or ultrasonic waves. Permian Basin gathering systems and Gulf Coast transmission corridors sustain concentrated demand as PHMSA mandates intensify inspection frequencies for high-consequence areas.
- Monitoring:Fiber optic distributed acoustic sensing and permanently installed sensor arrays deliver real-time strain, temperature, and vibration data without pipeline shutdown. Water utilities in the southwestern United States are deploying these systems on aging transmission mains where internal inspection remains impractical.
- Maintenance:Scheduled remediation programs address identified defects through recoating, sleeve installation, or pipe replacement.
- Risk Assessment:Quantitative models integrate inspection history, operational stress, and environmental factors to prioritize capital allocation.
Inspection retains volume leadership; monitoring holds the steepest expansion curve.
Technology:
Cost tier differentiation separates high-precision electromagnetic methods from emerging photonic alternatives that reduce per-kilometer assessment expense.
- Ultrasonic:Phased array and time-of-flight sensors deliver millimeter-scale wall thickness resolution independent of pipeline product or flow conditions. Subsea export lines in the Gulf of Mexico and North Sea corridors specify ultrasonic tools for corrosion mapping beneath thick marine deposits.
- Smart Pigs:Self-propelled inspection vehicles carry multiple sensor payloads through piggable pipeline geometries. Midstream operators in West Texas and southeastern New Mexico deploy smart pigs quarterly across Permian Basin gathering networks to satisfy PHMSA documentation requirements.
- Magnetic Flux Leakage:Saturates pipe walls with magnetic fields to detect volumetric metal loss and stress-corrosion cracking.
- Fiber Optics:Distributed sensing along standard telecommunications cable enables leak detection and third-party intrusion monitoring.
Smart pigs command the largest installed base; fiber optics is climbing the fastest.
End User:
Application maturity varies sharply across verticals, with hydrocarbon pipelines operating under decades-old regulatory frameworks while water infrastructure remains structurally underpenetrated.
- Oil & Gas:Midstream operators and integrated majors deploy comprehensive integrity programs spanning transmission, gathering, and distribution assets. PHMSA regulations and EPA spill prevention mandates in the United States enforce documented assessment cycles with escalating penalties for non-compliance.
- Water Utilities:Municipal transmission mains and wastewater force mains lack formal integrity frameworks despite aging cast-iron and asbestos-cement inventories. California and Texas water districts are piloting acoustic leak detection and structural assessment programs on pre-1980s distribution networks.
- Chemical Plants:Process safety management under OSHA standards drives inspection of internal piping and transfer lines.
- Energy Sector:Power generation cooling water systems and fuel supply lines require corrosion monitoring adapted to thermal cycling regimes.
Oil & gas retains volume leadership; water utilities hold the steepest expansion curve.
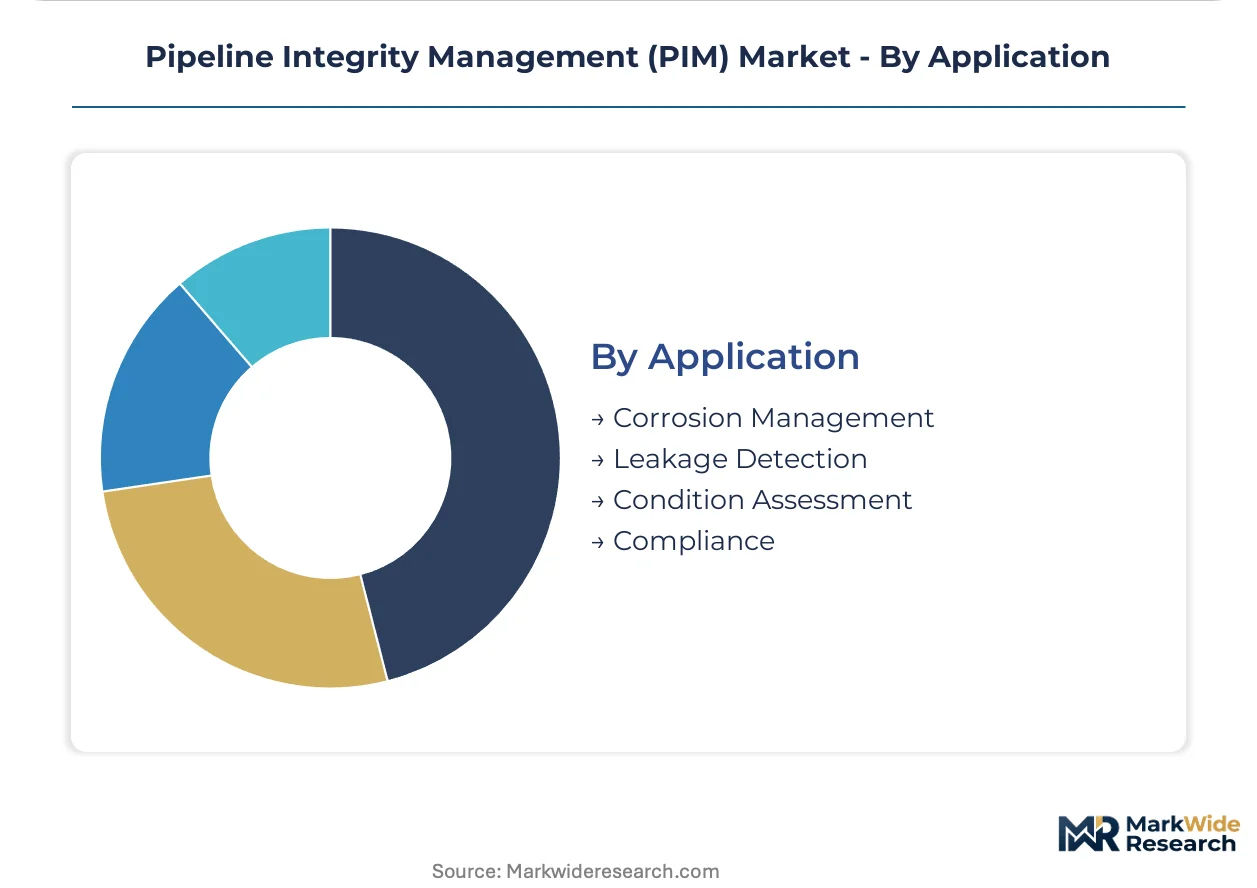
Application:
Customer type differentiation separates compliance-driven procurement from performance-optimized investment, with regulatory deadlines forcing faster adoption in hazardous liquid corridors.
- Corrosion Management:Electrochemical monitoring, coating surveys, and cathodic protection optimization address external and internal degradation mechanisms. Offshore platforms in the Gulf of Mexico integrate sacrificial anode monitoring with ROV-deployed ultrasonic thickness verification.
- Leakage Detection:Computational pipeline monitoring and fiber optic sensing identify releases before they reach receptors. PHMSA's tightened response-time thresholds for hazardous liquid pipelines in the United States are accelerating deployment of real-time platforms with automated valve actuation.
- Condition Assessment:Integrated inspection data synthesis determines remaining service life and revalidation intervals.
- Compliance:Documentation and reporting systems satisfy regulator audit requirements and operator management system standards.
Corrosion management retains volume leadership; leakage detection holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline integrity management services flow predominantly toward export-oriented energy economies with dense hydrocarbon infrastructure and stringent regulatory regimes. Import demand concentrates in industrialized markets retrofitting aging transmission networks. The United States, Germany, China, Saudi Arabia, and Brazil represent the primary nodes of procurement activity, each driven by distinct regulatory and infrastructure imperatives.
United States
PHMSA mandates for high-consequence area pipelines sustain demand for inline inspection and fiber optic monitoring across the Permian Basin and Gulf Coast. The EPA's spill prevention regulations tighten operational compliance obligations for hazardous liquid carriers. West Texas gathering systems and Louisiana export terminals anchor concentrated deployment of smart pigging services and distributed acoustic sensing.
Germany
Natural gas transit infrastructure and chemical corridor pipelines drive investment in corrosion monitoring and leak detection systems. The country's national energy regulator enforces integrity standards for cross-border transmission lines amid supply diversification efforts. The Rhine-Ruhr industrial cluster and Bavarian chemical parks host dense networks requiring continuous condition assessment.
China
West-to-east pipeline corridors and offshore import terminals expand procurement of ultrasonic inspection tools and cathodic protection systems. The Ministry of Ecology and Environment tightens emission and safety standards for hydrocarbon transport infrastructure. The Sichuan-Chongqing shale gas region and Yangtze River Delta refining clusters sustain concentrated vendor activity.
Saudi Arabia
Master Gas System expansion and Red Sea coastal development accelerate deployment of subsea inspection technologies and predictive maintenance platforms. The country's national oil company mandates comprehensive integrity frameworks for new gathering and transmission assets. The Eastern Province oilfields and Jubail industrial city anchor specialized service demand.
Brazil
Pre-salt offshore production corridors and coastal refining logistics sustain demand for ROV-deployed inspection and computational monitoring systems. The national petroleum regulator enforces integrity documentation for deepwater export lines. The Santos Basin cluster and Rio de Janeiro technical services hub concentrate vendor presence and procurement authority.
Pipeline Integrity Management (PIM) Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers: integrated energy technology conglomerates, specialized inspection service providers, and certification-focused testing laboratories. Strategic archetypes include full-stack platform vendors bundling hardware and analytics, pure-play inspection contractors executing campaign-based assessments, and laboratory networks sustaining cross-border certification workflows. Dominant competitive moves encompass vertical integration into sensor manufacturing and strategic partnerships binding fiber optic cable suppliers with analytics software developers.
Within the integrated technology tier, Baker Hughes Company and ROSEN Group occupy positions spanning tool fabrication, data analytics, and field execution. SGS S.A. exemplifies the certification-laboratory archetype, anchoring geographic coverage through distributed testing infrastructure. These three entities represent contrasting strategic postures: technology-led platform consolidation, specialized inline inspection dominance, and compliance-documentation scale.
| Leading Market Players |
|---|
| T.D. Williamson, Inc. |
| SGS S.A. |
| Baker Hughes Company |
| Intertek Group plc |
| Bureau Veritas S.A. |
| ROSEN Group |
| Applus+ S.A. |
| NDT Global |
| MISTRAS Group, Inc. |
| Others |
Value Network & Pricing Analysis
East Asian photonic component manufacturing concentrates supply of high-fidelity electromagnetic transducers and fiber optic sensors, anchoring margin capture at the specialty materials tier while midstream operators downstream face compressed procurement leverage.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with PHMSA certification grade and inspection frequency volume scale driving differentiation. Pricing pressure stems from qualified analyst scarcity inflating service delivery costs, while municipal water utilities exhibit highest price sensitivity due to constrained capital budgets.
Supply Chain Analysis
Extended payment terms from pipeline operators to inspection contractors now stretch 90-120 days, with supply-chain finance facilities emerging as working capital bridges. Manufacturing concentrates in Japan, Germany, and the United States for precision sensor fabrication, drawing from specialty steel alloys, rare-earth magnetic materials, and single-mode fiber cable. Single-source vulnerability around photonic integrated circuits creates tariff exposure. Distribution runs through direct vendor-operator contracts disintermediating generalist construction managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as major midstream operators unbundle integrity services from engineering procurement contracts, consolidating vendor rosters around direct technology sourcing.
For Market Incumbents: Harden platform consolidation through backward integration into sensor manufacturing and captive supply of fiber optic cable, defending against pure-play analytics entrants eroding software margins. Priority lever sits with certification investment under API 1163 to maintain qualification timelines ahead of commercial technology availability. For New Entrants and Emerging Players: Water utility transmission mains in California and Texas represent the most penetrable entry point, with acoustic leak detection on pre-1980s cast-iron networks offering low competitive density. Carbon capture pipeline corridors in the US Gulf Coast provide secondary white-space. Go-to-market should lead with subscription-based monitoring SaaS rather than capital-intensive inspection hardware. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed inspection service platforms holding Permian Basin contract backlogs but lacking predictive analytics capabilities. Long-term viability hinges on software recurring revenue attachment rates. Signal to watch is fiber optic retrofit penetration rates on legacy hydrocarbon corridors as indicator of technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive supply of electromagnetic transducers insulates margin from East Asian trade friction. |
| AI-Driven Predictive Platform Launch | Machine learning models trained on PHMSA incident databases enable condition-based intervention scheduling. |
| Water Utility Vertical Expansion | Municipal transmission mains in southwestern states lack formal integrity frameworks despite aging infrastructure. |
| Carbon Capture Pipeline Certification | Supercritical CO2 corrosion monitoring protocols create first-mover advantage in Gulf Coast development corridors. |
| Strategic Partnership with Fiber Optic Suppliers | Binding cable vendors with analytics developers collapses procurement complexity for integrated sensor suites. |
Research Methodology
Desk research of PHMSA enforcement databases, API standards documentation, and midstream operator capital expenditure disclosures preceded structured interviews with integrity management directors, pipeline control room operators, fiber optic sensing vendors, and regulatory compliance officers. Primary fieldwork combined with secondary validation from SEC 10-K filings, EIA pipeline inventory data, and FERC certificate applications. Bottom-up service revenue estimates triangulated against top-down infrastructure spending projections.
Assumptions around PHMSA regulatory stringency and Permian Basin production trajectories were held fixed, while sensor technology adoption curves and water utility capital allocation were varied across sensitivity scenarios. Segmentation modeling spanned service type, sensing technology, end-user vertical, and application focus. CAGRs derived from fitted growth curves against historical inspection frequency trends and regulatory deadline pacing. Forecast inputs incorporated pipeline mileage additions, high-consequence area reclassifications, and fiber optic retrofit penetration assumptions.
Macroeconomic conditions sit as an overlay; deviation in hydrocarbon commodity prices, interest rate environments, or infrastructure stimulus appropriations would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology qualification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
One-Way Valve Market
Valves
Gas Equipment Market
Valves
GCC and MENA Valves Market
Valves
Hydraulic Valves Market
Valves
Pipeline and Process Services Market
Valves
Tank Hydrogen Valve Market
Valves
Rupture Discs Market
Valves
Electro Pneumatic Positioner Market
Valves
Choke and Kill Manifold Market
Valves
Global Fluid Management Systems Market
Valves
Valve Seat Inserts Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Europe Industrial Valves Market
Valves
Valve Cover Gasket Market
Valves
Industrial Valves and Actuators Market
Valves
Aerospace Valves Market