
 Railway Emergency Valves Market | 2026-2036
Railway Emergency Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Emergency Valves Market Analytics
Electro-pneumatic integration is narrowing the performance gap between legacy hydraulic systems and modern digital control architectures. Parker Hannifin leverages its fluid power heritage to dominate pneumatic emergency valve specifications for North American freight operators. Emerson Global anchors its position through embedded sensor architectures that enable predictive maintenance protocols. Flowserve competes on severe-service metallurgy for high-pressure steam applications in legacy locomotive fleets.
Railway emergency valves are mechanical or electromechanical devices engineered to arrest fluid or gas flow within rail vehicle braking, fuel, or coolant circuits, typically rated for operating pressures exceeding 10 bar and temperatures from -40°C to +85°C under EN 50155 environmental conditions; their primary purpose is to prevent catastrophic system failure, fire propagation, or uncontrolled energy release during transit operations. Ball valves command the largest installed base across emergency shutdown applications due to their quarter-turn actuation speed and bidirectional sealing reliability. Pneumatic technology leads new procurement for mainline passenger fleets, while electric actuation gains traction in metro and light-rail deployments where building-mounted control rooms enable centralized diagnostics.
The Federal Railroad Administration enforces 49 CFR Part 232 brake system standards that mandate redundant emergency valve configurations on all US freight equipment, while the EU Agency for Railways administers TSIs requiring interoperable emergency isolation devices across member state networks. China's National Railway Administration imposes GB/T rail vehicle standards that increasingly reference IEC 61373 shock and vibration testing for valve-mounted electronics. Stakeholders must weigh the capital cost of full electric actuation retrofits against the extended service intervals and diagnostic granularity these systems deliver.
Market Dynamics
The transition from pneumatic to electro-pneumatic actuation is compressing replacement cycles and forcing suppliers to reconfigure their certification pipelines around embedded electronics standards. This technology migration is reshaping competitive positioning across mainline and urban rail segments simultaneously.
Growth Catalysts
- EN 50155 Railway Electronics Standards:Mandates for shock-resistant valve-mounted control units are accelerating retrofit programs across European passenger fleets. Operators in Germany and France now specify IP67-rated enclosures as baseline procurement requirements.
- India's Dedicated Freight Corridors:The 1,500-kilometer Eastern and Western freight corridors are generating concentrated demand for high-cycle pneumatic emergency valves rated for 25-ton axle loads. Indian Railways mandates indigenous sourcing under its phased manufacturing program.
- Condition-Based Monitoring Integration:Embedded pressure and temperature sensors are enabling predictive maintenance protocols that extend service intervals by 40%. This sensor convergence is virtualizing traditional inspection schedules across Japanese Shinkansen networks.
Market Restraints
- Specialized Alloy Supply Concentration:High-nickel stainless steels for severe-service steam applications source predominantly from German and Austrian metallurgical suppliers. Geopolitical friction is extending lead times for pressure-boundary castings.
- Electric Actuation Cost Premium:Full motor-operator retrofits carry 2.5-3x capital cost versus pneumatic equivalents. Freight operators with thin margins defer upgrades until regulatory mandates force compliance.
- Hydraulic System Entrenchment:Legacy locomotive fleets in Russia and Eastern Europe retain mineral-oil hydraulic emergency circuits. Parts commonality and maintenance familiarity slow substitution rates despite superior pneumatic reliability data.
Strategic Opportunities
- Southeast Asian Metro Expansion:Vietnam's Ho Chi Minh City Metro and Indonesia's Jakarta MRT Phase 2 are specifying electric emergency valves for centralized control room architectures. These greenfield projects bypass pneumatic legacy constraints entirely.
- GB/T Standard Harmonization:China's National Railway Administration is aligning domestic rail vehicle standards with IEC 61373 vibration testing protocols. This regulatory convergence creates export pathways for certified suppliers into Belt and Road rail projects.
- Digital Twin Integration:Valve manufacturers are partnering with fleet management software providers to embed asset performance data directly into operator maintenance platforms. This convergence is virtualizing traditional spare parts forecasting.
Industry Challenges
- Cross-Disciplinary Engineering Talent:Electro-pneumatic valve development requires simultaneous competence in fluid power, embedded systems, and railway safety integrity levels. This skill intersection is scarce in traditional mechanical engineering labor pools.
- Multi-Standard Certification Overlap:Suppliers seeking global footprint must simultaneously navigate EN 50155, IEC 61373, and 49 CFR Part 232 testing regimes. Parallel certification timelines extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Emergency Valves Market |
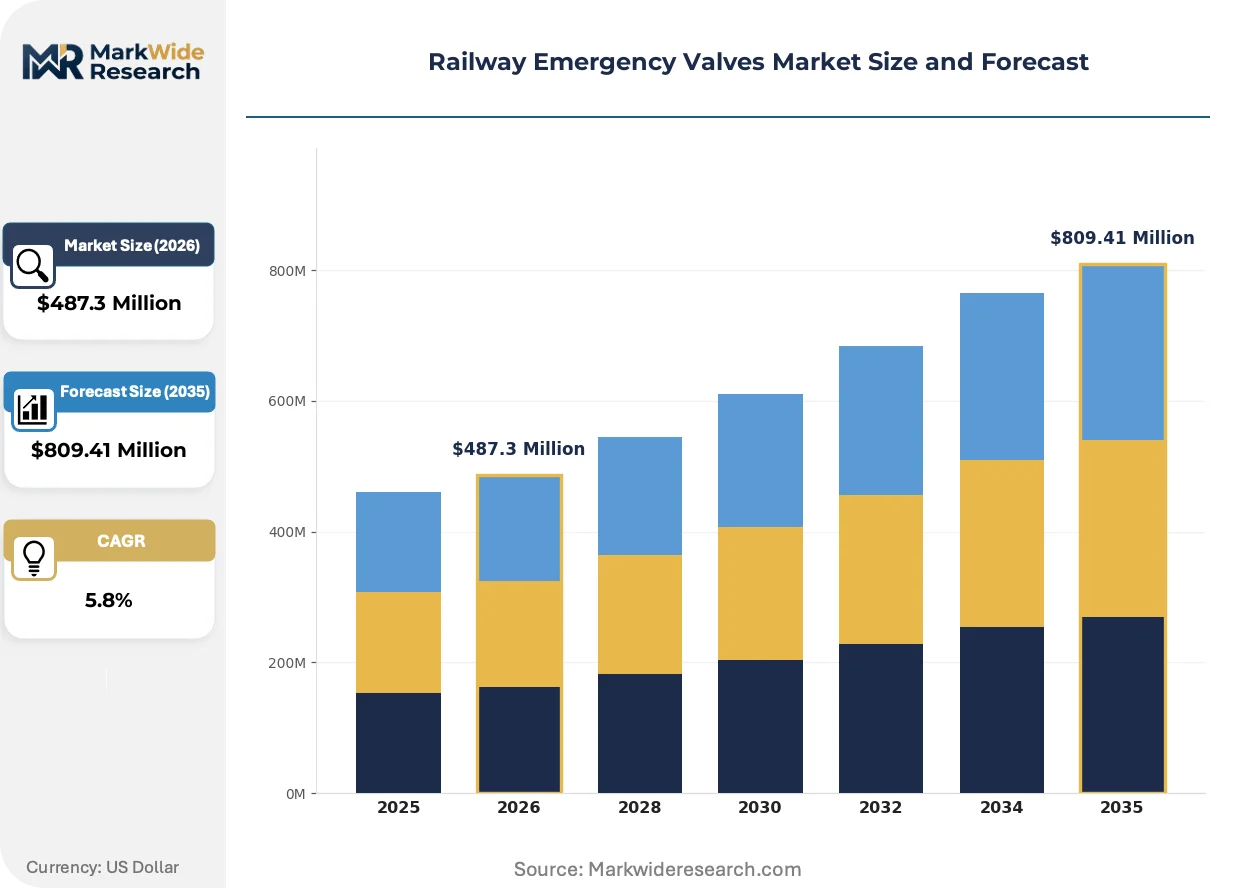
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Check Valves, Globe Valves Technology: Pneumatic, Hydraulic, Electric, Manual End User: Rail Operators, Manufacturing Plants, Maintenance Providers, Government Agencies Application: Emergency Shutdown, Pressure Relief, Safety Isolation, Fluid Control |
| Companies Covered | Johnson Control, Parker Hannifin, Emerson Global, Metso, General Electric, Flowserve, IMI, Cameron, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Emergency Valves Market Evolving Landscape
Digitalization of valve control architectures is collapsing the distinction between mechanical safety devices and intelligent network nodes. This transformation is redefining supplier value propositions across specification, commissioning, and operational phases.
Edge-computing valve controllers are virtualizing traditional hardwired safety interlocks. These distributed processing units execute local diagnostic routines while streaming telemetry to centralized maintenance platforms. High-speed rail operators in Spain and South Korea are specifying this architecture for real-time brake circuit monitoring. The technology is virtualizing scheduled preventive maintenance into condition-triggered interventions.
The EU Agency for Railways is tightening Technical Specification for Interoperability requirements for emergency isolation devices across member state networks. This regulatory pressure is forcing cross-border harmonization of valve interface standards and test protocols. Rolling stock OEMs in Poland and Czechia are consolidating supplier bases to reduce certification duplication costs.
Service contract unbundling is fragmenting traditional valve procurement bundles. Fleet operators are separating hardware acquisition from commissioning support and lifecycle maintenance. This pattern is most visible in British passenger franchises, where rolling stock leasing companies now contract diagnostics separately from component supply. Channel intermediaries specializing in railway asset management are capturing margin previously held by manufacturers.
Railway Emergency Valves Market Segmentation
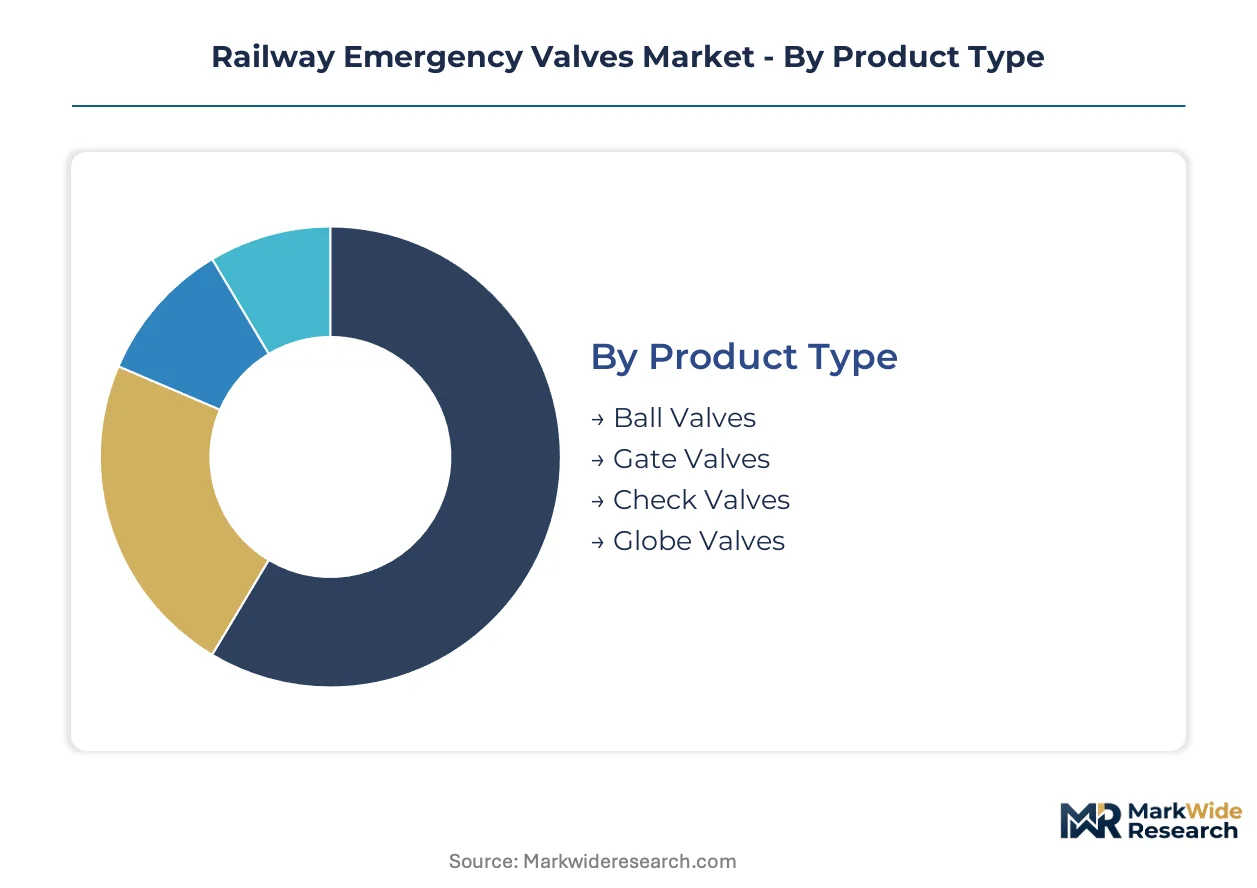
Railway emergency valve procurement splits across four orthogonal dimensions: mechanical configuration, actuation method, buyer type, and functional deployment. Each axis carries distinct certification requirements and margin profiles that reshape supplier positioning.
Product Type:
Use-case spectrum spans high-cycle pneumatic systems to severe-service steam applications, with metallurgy and sealing architecture driving specification divergence.
- Ball Valves:Quarter-turn actuation delivers sub-second closure speeds critical for brake circuit emergencies. Bidirectional sealing reliability dominates procurement specifications for Indian freight corridors and Chinese intercity networks where cycle frequency exceeds 500,000 operations annually.
- Gate Valves:Linear motion design suits full-bore flow requirements in high-pressure coolant circuits. Linear sealing surfaces tolerate thermal expansion cycling in legacy locomotive fleets across Russia and Eastern Europe where hydraulic system entrenchment slows substitution.
- Check Valves:Passive flow prevention for gravity-fed fuel systems.
- Globe Valves:Throttling precision for regulated pressure reduction in auxiliary circuits.
Established volume favors ball valves; emerging adoption favors gate valves in severe-service retrofits.
Technology:
Cost tier stratification separates legacy pneumatic infrastructure from electric premium deployments, with hybrid electro-pneumatic architectures capturing mid-market specification.
- Pneumatic:Compressed air actuation leverages existing locomotive auxiliary systems. Mainline passenger fleets in Germany and France specify IP67-rated enclosures under EN 50155 mandates, while Indian Railways mandates indigenous sourcing for its dedicated freight corridors.
- Electric:Motor-operator designs enable centralized diagnostics from building-mounted control rooms. Metro deployments in Vietnam and Indonesia specify these architectures for greenfield projects that bypass pneumatic legacy constraints entirely.
- Hydraulic:Mineral-oil circuits persist in Russian legacy fleets.
- Manual:Mechanical backup for maintenance isolation procedures.
Pneumatic systems retain installed base dominance; electric architectures are gaining share fastest in urban rail greenfields.
End User:
Customer type determines procurement rhythm, with rolling stock OEMs driving specification standards and maintenance providers capturing lifecycle service revenue.
- Rail Operators:Fleet owners specify integrated brake system architectures. High-speed rail networks in Spain and South Korea demand edge-computing valve controllers for real-time circuit monitoring and predictive maintenance protocols.
- Maintenance Providers:Independent service companies unbundle diagnostics from hardware supply. British rolling stock leasing companies now contract condition-based monitoring separately from component procurement, fragmenting traditional manufacturer margins.
- Manufacturing Plants:Rolling stock OEMs integrate valves into original brake system builds.
- Government Agencies:Regulatory procurement for safety-critical infrastructure mandates.
Rail operators concentrate specification authority; maintenance providers are climbing the fastest on service revenue expansion.
Application:
Functional deployment separates safety-critical emergency systems from operational fluid management, with regulatory intensity scaling accordingly.
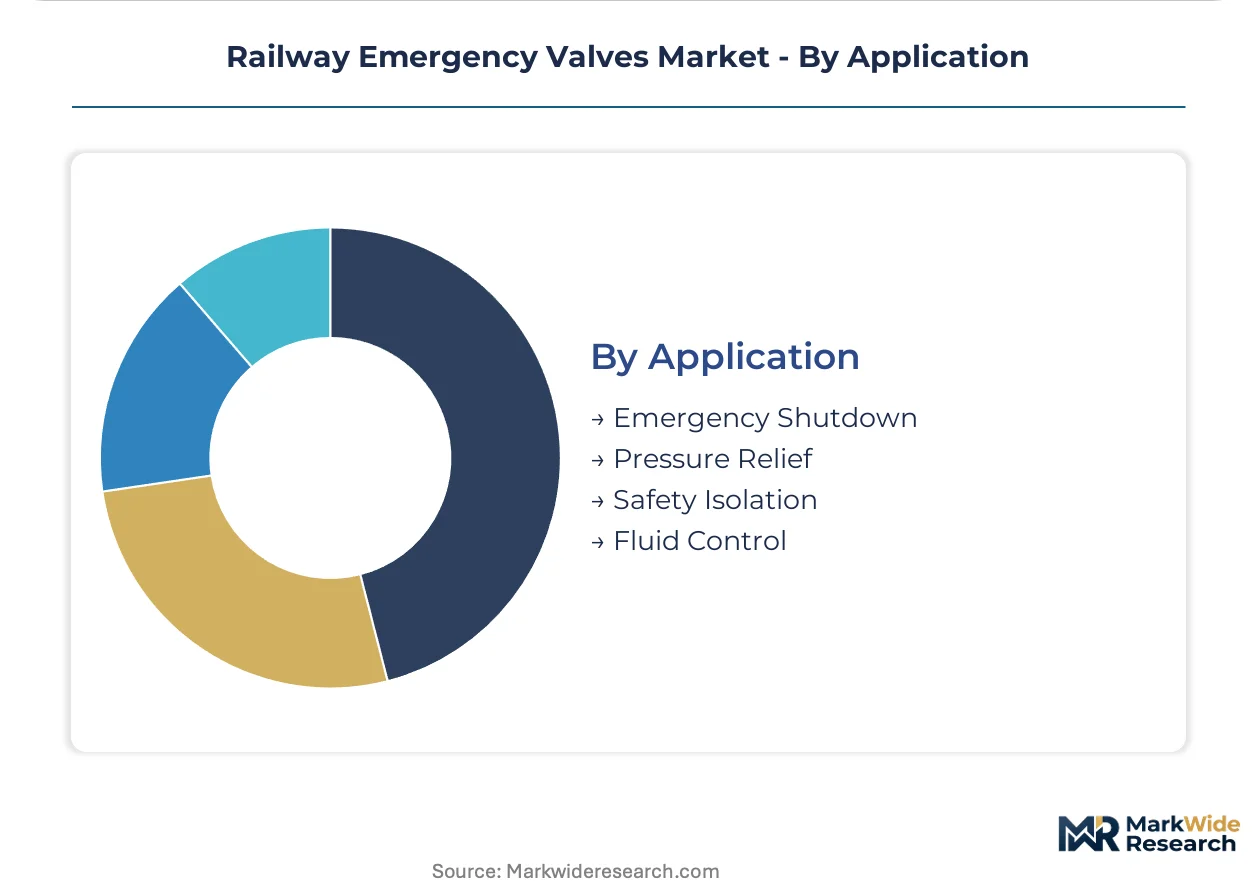
- Emergency Shutdown:Catastrophic failure prevention systems rated for 10 bar+ operating pressures. US freight equipment mandates redundant configurations under 49 CFR Part 232, while EU TSIs require interoperable isolation devices across member state networks.
- Safety Isolation:Circuit segmentation for maintenance lockout procedures. Japanese Shinkansen networks integrate embedded pressure and temperature sensors that virtualize traditional inspection schedules through predictive maintenance protocols.
- Pressure Relief:Overpressure protection for thermal expansion events.
- Fluid Control:Operational flow regulation in auxiliary systems.
Emergency shutdown commands regulatory premium pricing; safety isolation follows the steepest expansion trajectory on sensor integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight operators and high-speed rail developers concentrate procurement authority across distinct national programs. Regulatory mandates and infrastructure investment cycles determine specification intensity in each market.
United States
The Federal Railroad Administration enforces 49 CFR Part 232 brake system standards that mandate redundant emergency valve configurations on all freight equipment. Class I railroads operate concentrated procurement through Omaha and Chicago headquarters. Union Pacific and BNSF Railway specify pneumatic emergency shutdown systems for their 25,000-mile combined networks.
China
China's National Railway Administration imposes GB/T rail vehicle standards that increasingly reference IEC 61373 shock and vibration testing for valve-mounted electronics. The expanding intercity network generates demand for high-cycle pneumatic systems. CRRC Qingdao Sifang Rolling Stock anchors specification standards for high-speed trainsets.
India
Indian Railways mandates indigenous sourcing under its phased manufacturing program for dedicated freight corridor equipment. The 1,500-kilometer Eastern and Western freight corridors require valves rated for 25-ton axle loads. Alstom's manufacturing facility in Madhepura and Siemens' operations in Aurangabad concentrate domestic production capacity.
Germany
EN 50155 railway electronics standards mandate shock-resistant valve-mounted control units across European passenger fleets. Deutsche Bahn specifies IP67-rated enclosures as baseline procurement requirements. Siemens Mobility in Munich and Knorr-Bremse in Munich anchor continental supply chain coordination.
Japan
East Japan Railway Company and Central Japan Railway Company integrate embedded pressure and temperature sensors that virtualize traditional inspection schedules. The Shinkansen network demands predictive maintenance protocols extending service intervals. Hitachi's rail systems division in Kawasaki and Nabtesco's valve operations in Kyoto concentrate technical development.
Railway Emergency Valves Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification, procurement, and aftermarket service layers. The vendor base organizes around fluid power heritage, embedded electronics integration, and severe-service metallurgy capabilities. Three archetypes dominate: diversified industrial conglomerates with rail divisions, pure-play valve specialists with railway certifications, and regional fabricators serving indigenous procurement mandates. Competitive moves concentrate on M&A to acquire electronics competence and strategic partnerships to embed predictive maintenance platforms.
Among diversified industrial conglomerates, Parker Hannifin and Emerson Global occupy positions spanning pneumatic and electro-pneumatic architectures. Flowserve represents the severe-service metallurgy archetype for high-pressure steam applications. These three companies exemplify how heritage in adjacent industrial markets translates into railway specification authority through certification accumulation and fleet reference data.
| Leading Market Players |
|---|
| Johnson Control |
| Parker Hannifin |
| Emerson Global |
| Metso |
| General Electric |
| Flowserve |
| IMI |
| Cameron |
| Schneider Electric |
| Others |
Value Network & Pricing Analysis
Overcapacity in German and Austrian metallurgical forging capacity is compressing margin capture for high-nickel stainless castings while simultaneously extending payment terms demanded by tier-one valve assemblers. This utilization asymmetry between raw material suppliers and finished goods manufacturers is reshaping procurement leverage across the pneumatic emergency valve tier.
Pricing Analysis
Cost-plus contracts indexed to LME nickel pricing dominate procurement for severe-service pressure-boundary components. Three-tier pricing structure across EN 50155-certified premium, standard industrial-grade, and economy non-certified tiers reflects certification investment amortization. Pricing pressure stems from Indian Railways' phased manufacturing program mandating indigenous sourcing at benchmarked rates. Freight operators exhibit highest price sensitivity due to thin operating margins, while high-speed rail developers accept premium tier pricing for predictive maintenance integration.
Supply Chain Analysis
Extended payment terms to 120 days and supply-chain finance facilities anchored by rolling stock OEMs are squeezing working capital for tier-two foundries. High-nickel stainless steel castings draw from German, Austrian, and Japanese metallurgical suppliers; pneumatic actuator assemblies rest on Chinese and South Korean electronics integration. Single-source vulnerability concentrates in aerospace-grade nickel superalloy forging capacity. Distribution runs through authorized service networks controlled by Knorr-Bremse and Siemens Mobility rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
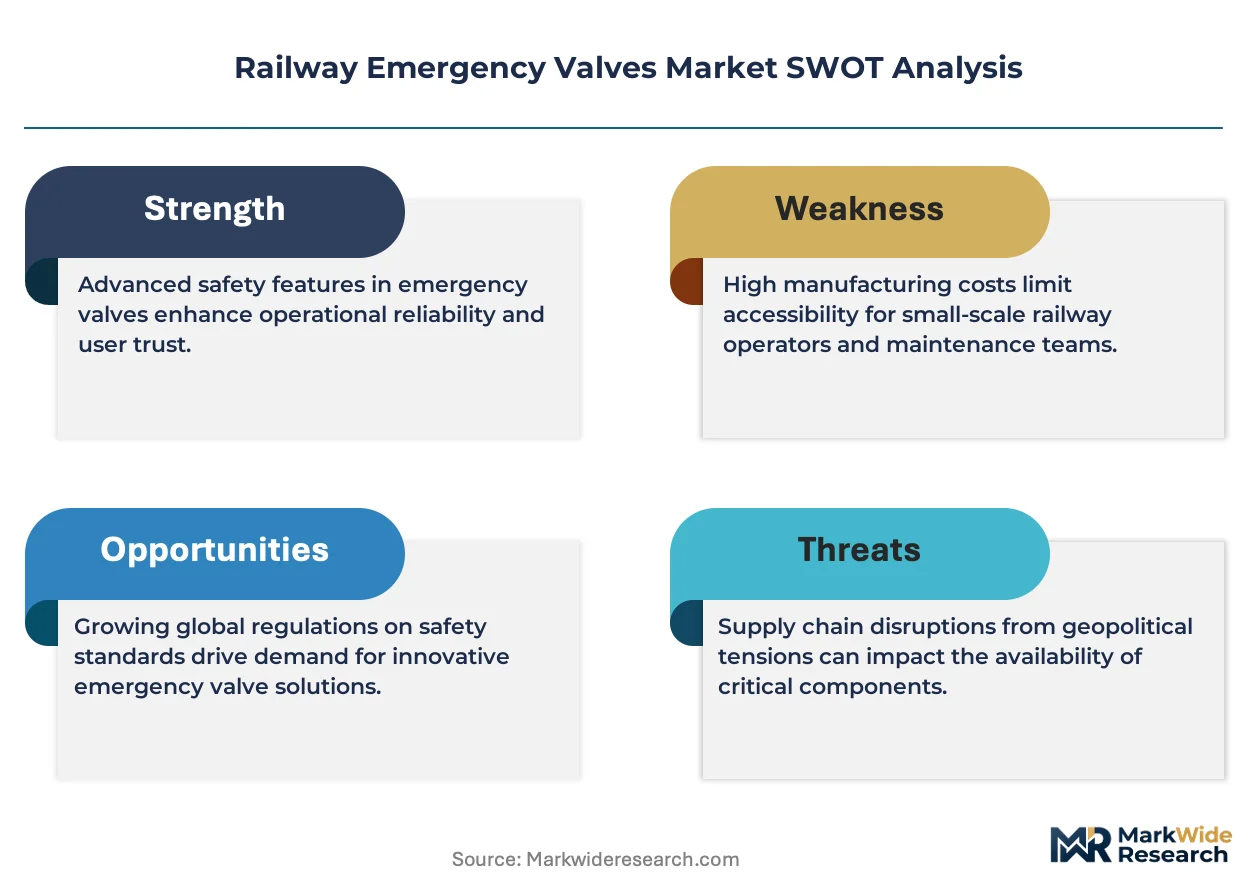
Railway emergency valves represent a service-attach opportunity where condition-based monitoring contracts expand at double the hardware replacement rate. Predictive maintenance platform subscriptions now outpace pneumatic valve unit sales in revenue growth across European passenger fleets.
For Market Incumbents: Build certification moats by accelerating EN 50155 and IEC 61373 dual-compliance ahead of regulatory harmonization deadlines. Acquire embedded sensor competence through targeted electronics partnerships to defend against pure-play IoT entrants. Expand indigenous production footprints in India to satisfy phased manufacturing mandates before local fabricators achieve scale.
For New Entrants and Emerging Players: Vietnam's Ho Chi Minh City Metro and Indonesia's Jakarta MRT Phase 2 present underpenetrated greenfield specifications for electric emergency valves. These projects bypass pneumatic legacy constraints entirely. Target British rolling stock leasing companies with unbundled diagnostics offerings that fragment incumbent service margins. Partner with fleet management software providers for digital twin integration rather than competing on hardware specification alone.
For Investors and Strategic Acquirers: Capital is best deployed toward electro-pneumatic valve specialists with embedded electronics capabilities and existing railway safety integrity level certifications. Long-term viability hinges on positioning ahead of the technology migration from pneumatic to full electric actuation. Monitor GB/T standard harmonization progress with IEC 61373 as the inflection signal for Chinese export pathway viability into Belt and Road rail projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Sensor Architecture Development | Enables predictive maintenance protocols that extend service intervals by 40% for Shinkansen operators. |
| Indigenous Manufacturing Footprint Expansion | Satisfies Indian Railways' phased manufacturing program for dedicated freight corridor equipment mandates. |
| Digital Twin Platform Partnership | Virtualizes spare parts forecasting by embedding valve performance data into operator maintenance systems. |
| Multi-Standard Certification Investment | Reduces product launch windows currently extended 18-24 months by parallel EN 50155 and IEC 61373 testing. |
| Aftermarket Service Contract Unbundling | Captures margin from British rolling stock leasing companies separating diagnostics from hardware procurement. |
Research Methodology
A spread of perspectives from rolling stock OEM procurement directors, railway maintenance engineering heads, pneumatic system integrators, and valve metallurgy specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EN 50155 certification databases, Indian Railways tender documentation, and customs records for high-nickel alloy trade flows. Bottom-up unit economics triangulated against top-down infrastructure investment forecasts across the analysis window.
Demand-supply balance modeling anchored projections, with segmentation across ball valve and gate valve configurations, pneumatic versus electric actuation technologies, and emergency shutdown versus safety isolation applications. CAGRs derived from rolling stock delivery schedules, freight corridor commissioning timelines, and retrofit program intensities. Forecast inputs incorporated EN 50155 adoption curves and indigenous sourcing mandate phase-ins without year-specific anchoring.
Practitioners should monitor regulatory harmonization progress, nickel alloy supply disruptions, and electric actuation cost curves for early signals of forecast revision. Forecasts reflect assumptions about technology migration pace and certification timeline convergence. Macroeconomic infrastructure investment shifts, geopolitical friction in metallurgical supply chains, or breakthroughs in solid-state actuation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Hydraulic Diaphragm Valve Market
Valves
Dense Phase Vessels Market
Valves
Hot Blast Valves Market
Valves
Diaphragm Valve Market
Valves
North America Irrigation Valves Market
Valves
Global Marine Actuators and Valves Market
Valves
Valve Interlocks Market
Valves
Christmas Tree Valves Market
Valves
Global Valve Positioners Market
Valves
Global Level Gauge Market
Valves
Valve Cover Gasket Market
Valves
North America Butterfly Valve Market
Valves
Refrigeration Valves Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Gate Impellers Market
Valves
Global Gas Pressure Regulator Market