
 Christmas Tree Valves Market | 2026-2036
Christmas Tree Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Christmas Tree Valves Market Outlook
National oil companies are redrawing procurement priorities for Christmas tree valve systems. Baker Hughes Co. leverages its digital valve portfolio to capture integrated project awards across deepwater basins. TechnipFMC plc anchors its position through modular subsea tree architectures that compress installation timelines. NOV Inc. competes on manufacturing scale, sustaining cost advantages in high-volume onshore configurations.
Christmas tree valves are pressure-containing wellhead assemblies fabricated from forged alloy steel, rated for API 6A pressure classes up to 20,000 psi, designed to control hydrocarbon flow from reservoir to surface facilities. Manual valves retain dominant share in legacy onshore fields where retrofit economics favor mechanical simplicity, while automated valves represent the fastest-growing product category as remote monitoring protocols reduce wellsite staffing requirements. Offshore solutions command premium positioning due to subsea qualification testing and corrosion-resistant metallurgy demands, whereas modular solutions expand addressable market reach among marginal field developers seeking standardized, redeployable assets.
API 6A and ISO 10423 govern material qualification and pressure testing protocols, while NORSOK standards shape North Sea supplier eligibility through stringent documentation and traceability requirements. The EPA and BSEE in the United States enforce methane emission thresholds that accelerate pneumatic-to-electric actuator conversions across wellhead installations. Stakeholders must weigh capital deployment between digitally enabled automated architectures and conventional mechanical systems as regulatory compliance timelines tighten and operator labor models evolve.
Market Dynamics
Automated wellhead architectures are compressing installation timelines while API 6A certification requirements intensify qualification barriers for forged alloy steel suppliers serving deepwater and unconventional basins.
Growth Catalysts
- Subsea qualification testing:Offshore Brazil and the North Sea drive demand for corrosion-resistant metallurgy in high-pressure Christmas tree assemblies, expanding addressable market among marginal field developers.
- EPA methane emission thresholds:Pneumatic-to-electric actuator conversions accelerate across Permian Basin wellhead installations as BSEE enforcement tightens.
- Digital twin integration:Remote monitoring protocols reduce wellsite staffing requirements, pulling adoption curves toward automated valve architectures in legacy onshore retrofits.
Market Restraints
- Forged alloy steel supply concentration:Premium-grade material qualification bottlenecks concentrate among North American and European forging houses, extending lead times for 20,000 psi pressure-class components.
- NORSOK documentation requirements:Stringent traceability protocols create supplier eligibility friction for entrants lacking established North Sea project histories.
- Manual valve retrofit economics:Mechanical simplicity in legacy fields delays replacement cycles, constraining near-term revenue capture from automated system upgrades.
Strategic Opportunities
- Modular subsea tree architectures:Standardized, redeployable assets unlock marginal field economics in offshore West Africa and Southeast Asian basins.
- ISO 10423 harmonization:Convergence between API and international testing standards reduces dual-certification burdens for suppliers targeting multiple regulatory jurisdictions.
- Integrated project awards:Deepwater operators bundle valve procurement with digital monitoring platforms, favoring vendors with captive actuator and sensor capabilities.
Industry Challenges
- API 6A pressure testing timelines:Extended qualification cycles for new alloy formulations delay product commercialization and compress R&D return windows.
- Legacy system integration:Automated valve retrofits face mechanical incompatibility with decades-old wellhead geometries, requiring custom adapter engineering.
- Subsea installation skill scarcity:Specialized technician pools for subsea tree deployment concentrate among Gulf of Mexico and North Sea service contractors, constraining global deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Christmas Tree Valves Market |
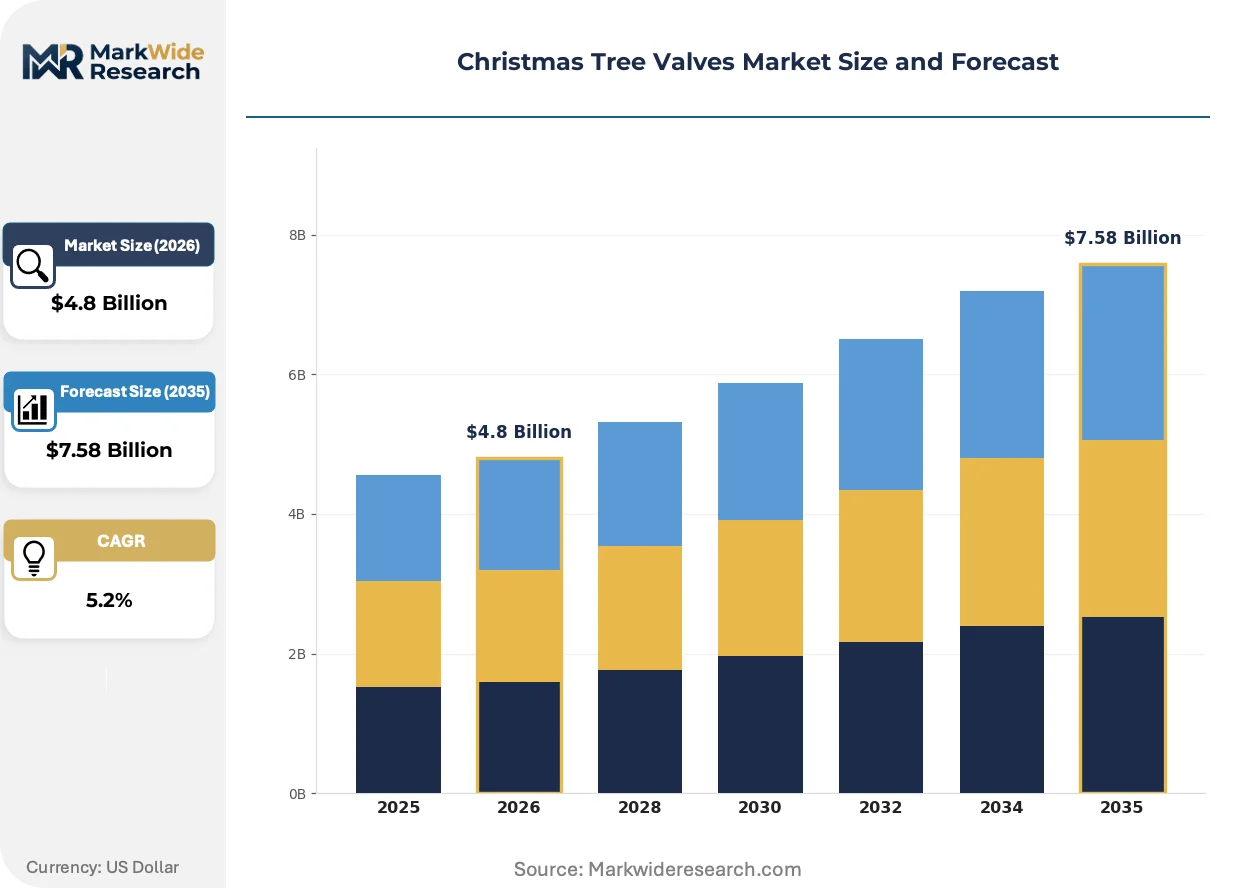
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Valves, Manual Valves, Automated Valves, Control Valves Application: Oil Extraction, Gas Extraction, Water Management, Pressure Control End User: Oil & Gas Companies, Research Institutions, Utility Providers, Engineering Firms Solution: Onshore Solutions, Offshore Solutions, Modular Solutions, Integrated Solutions |
| Companies Covered | NOV Inc., Stream Flo Industries Ltd., Aker Solutions ASA, Vatac Valve Corp, Cactus Inc., Baker Hughes Co., TechnipFMC plc, Neway valve, Schlumberger Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Christmas Tree Valves Market Strategic Shifts
Digital instrumentation layers are redefining valve lifecycle economics. Three developments dominate competitive differentiation.
Subsea choke valve actuation is miniaturizing through compact electro-hydraulic power units that eliminate umbilical complexity. Independent operators in Brazil's pre-salt fields deploy these systems to reduce vessel-day requirements. The technology is miniaturizing installation footprints while expanding intervention windows for subsea well maintenance.
EPA and BSEE methane rules are forcing pneumatic device replacements across US onshore assets. Electric actuator retrofits now dominate Permian Basin capital allocations. High-volume onshore configurations face compressed compliance timelines as state-level regulations in Texas and New Mexico layer additional inspection requirements.
Buyer concentration among national oil companies is compressing supplier negotiation cycles. Integrated project tenders now bundle Christmas tree valves with digital monitoring platforms, displacing component-only procurement. This pattern concentrates in Saudi Arabia and UAE where ADNOC and Aramco centralize wellhead standardization programs.
Christmas Tree Valves Market Segmentation
Christmas tree valve procurement patterns diverge sharply across operating environments. Pressure ratings, automation protocols, and installation logistics create distinct commercial segments with incompatible qualification requirements.
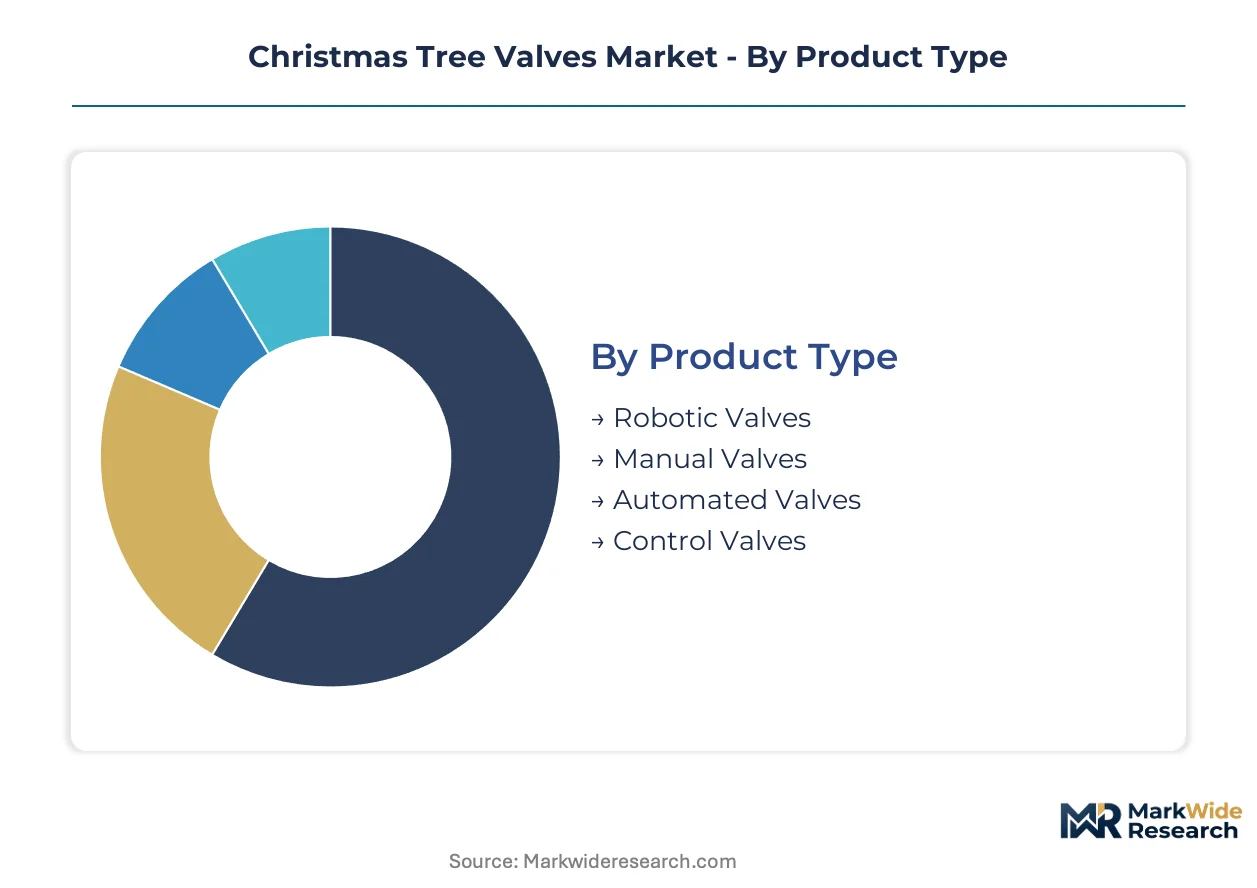
Product Type:
Manual valve architectures face intensifying substitution pressure from electric actuation systems as methane compliance deadlines compress retrofit timelines.
- Automated Valves:Electro-hydraulic and all-electric actuators integrate position sensors and remote telemetry for unmanned wellsite operations. Permian Basin operators deploy these systems to eliminate pneumatic methane venting under EPA enforcement timelines. Digital twin compatibility pulls adoption curves toward this architecture in legacy field retrofits.
- Manual Valves:Handwheel-operated gate and globe valves fabricated from forged alloy steel retain dominant installed base in mature onshore fields. Mechanical simplicity defers capital replacement where well economics favor minimal intervention. API 6A certification concentrates supply among established forging houses with pressure-class pedigree.
- Control Valves:Choke valves with adjustable trim geometries regulate flow rates and pressure drop across production tubing.
- Robotic Valves:Remotely operated intervention systems for subsea wellhead maintenance and emergency isolation.
Manual valves retain volume leadership; automated valves hold the steepest expansion curve.
Application:
Cost tier stratification separates high-pressure hydrocarbon service from lower-specification utility applications.
- Oil Extraction:Christmas tree assemblies for crude production require 10,000-20,000 psi pressure ratings and H2S-resistant metallurgy. Deepwater Brazil pre-salt fields drive specification intensity for corrosion-resistant alloy formulations. Subsea qualification testing extends lead times for forged component suppliers.
- Gas Extraction:Dry gas and associated gas production demands tight seal integrity across thermal cycling regimes. North Sea high-pressure high-temperature (HPHT) fields concentrate demand for metal-to-metal sealing technologies. BSEE methane rules accelerate pneumatic-to-electric conversions across US offshore platforms.
- Pressure Control:Master valves, wing valves, and swab valves manage annular and production pressure boundaries.
- Water Management:Injection and disposal wellhead systems for produced water and enhanced recovery operations.
Oil extraction commands premium pricing tiers; gas extraction faces the most compressed compliance timelines.
End User:
Customer type determines procurement centralization and technical specification authority.
- Oil & Gas Companies:National oil companies and independents dominate volume with standardized wellhead programs. ADNOC and Aramco centralization in Saudi Arabia and UAE bundles valve procurement with digital monitoring platforms. Integrated project awards favor vendors with captive actuator and sensor capabilities.
- Engineering Firms:EPC contractors specify Christmas tree valves within larger facility construction contracts.
- Research Institutions:Universities and national laboratories procure valves for experimental well simulation and materials testing.
- Utility Providers:Natural gas distribution utilities acquire wellhead equipment for storage and peaking field operations.
Oil and gas companies retain specification authority; engineering firms intermediate procurement for project-based demand.
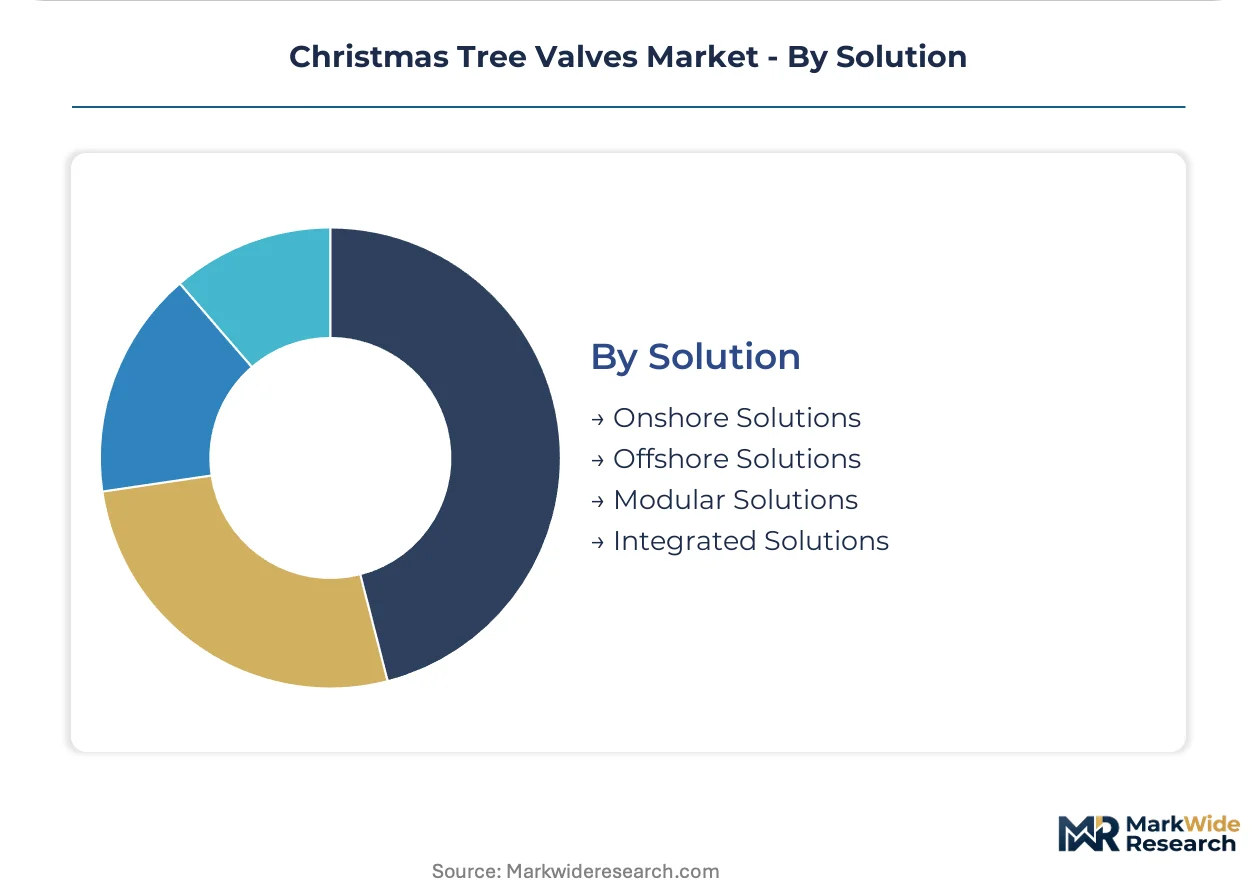
Solution:
Supply concentration shapes margin structure across installation environments.
- Offshore Solutions:Subsea Christmas trees with subsea control modules (SCM) and flying lead connections demand specialized fabrication facilities. North Sea and Gulf of Mexico installation contractors concentrate deployment expertise. Corrosion-resistant cladding and qualification testing create qualification barriers for new entrants.
- Modular Solutions:Standardized, skid-mounted wellhead packages enable rapid redeployment across marginal fields. West Africa and Southeast Asian basin developers favor these assets for short-cycle production economics. Factory acceptance testing compresses offshore commissioning timelines.
- Onshore Solutions:Conventional surface Christmas trees for land-based drilling and production operations.
- Integrated Solutions:Bundled wellhead, actuator, and digital monitoring platforms from single-source vendors.
Offshore solutions capture premium margins; modular solutions expand addressable market reach among capital-constrained developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports subsea Christmas tree assemblies to West African marginal field developers, while US forging houses supply pressure-class components to North Sea operators facing NORSOK qualification deadlines.
United States
Permian Basin operators drive pneumatic-to-electric actuator conversions under EPA methane enforcement timelines. BSEE offshore regulations tighten seal integrity requirements for Gulf of Mexico platforms. Houston-area fabrication clusters concentrate forged alloy steel production for 20,000 psi pressure-class valves.
Brazil
Pre-salt field expansion demands corrosion-resistant metallurgy for high-pressure subsea installations. ANVISA-equivalent petroleum regulator protocols govern subsea equipment import certification. Santos Basin service contractors deploy compact electro-hydraulic actuation systems to reduce vessel-day requirements.
Norway
North Sea HPHT fields concentrate demand for metal-to-metal sealing technologies in Christmas tree assemblies. NORSOK documentation and traceability requirements filter supplier eligibility through stringent project history verification. Stavanger-based engineering clusters anchor subsea qualification testing infrastructure.
Saudi Arabia
Aramco centralization programs bundle valve procurement with digital monitoring platforms across onshore and offshore developments. The country's national oil company standardization drives integrated project tender structures. Eastern Province industrial cities host wellhead assembly fabrication for Red Sea and Arabian Gulf fields.
United Kingdom
North Sea decommissioning timelines intersect with residual production optimization, sustaining replacement demand for wellhead components. The Health and Safety Executive enforces pressure equipment integrity standards across aging platform infrastructure. Aberdeen service clusters specialize in subsea tree installation and intervention contracting.
Christmas Tree Valves Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and certification pedigree dimensions. The vendor base stratifies into forging-integrated majors, modular architecture specialists, and regional fabrication houses. Three archetypes dominate: integrated energy technology conglomerates with captive actuator capabilities, subsea-focused engineering contractors with installation expertise, and high-volume onshore manufacturers competing on forged component scale. Competitive moves concentrate on M&A for digital monitoring capabilities and capacity expansion in corrosion-resistant alloy forging.
Within the integrated technology tier, Baker Hughes Co. and TechnipFMC plc exemplify vendors bundling valve hardware with digital platforms for deepwater project awards. NOV Inc. occupies a position among scale-driven manufacturers sustaining cost advantages in high-volume onshore configurations. These three entities represent contrasting strategic postures: digital integration, modular subsea architecture, and manufacturing scale.
| Leading Market Players |
|---|
| NOV Inc. |
| Stream Flo Industries Ltd. |
| Aker Solutions ASA |
| Vatac Valve Corp |
| Cactus Inc. |
| Baker Hughes Co. |
| TechnipFMC plc |
| Neway valve |
| Schlumberger Ltd. |
| Others |
Value Chain & Pricing Dynamics
Six-month lead times for 20,000 psi forged alloy steel components concentrate pricing power among North American and European forging houses with API 6A pedigree, compressing margins for valve assemblers lacking backward integration into premium-grade material supply.
Pricing Analysis
Prior-generation manual valve architectures trade at substantial discounts to current-generation electro-hydraulic automated systems, while next-generation all-electric subsea actuators command additional premiums for deepwater qualification. Three-tier pricing structure across premium, standard, and economy levels separates subsea-certified assemblies from onshore standard configurations from marginal-field modular packages. Cost compression in manual valve tiers is intensifying because national oil company procurement centralization squeezes component-only suppliers. Independent operators in West African basins exhibit highest price sensitivity; deepwater majors in Brazil and the North Sea demonstrate lowest.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for corrosion-resistant alloy feedstock sourced from East Asian mills. Forged alloy steel supply concentrates in the United States, Germany, and Japan, with cladding and subsea control module fabrication anchored in Norway and the United Kingdom. The supply chain draws from nickel-chromium-molybdenum alloy bar stock, electro-hydraulic actuator components, and digital sensor telemetry. Single-source vulnerability around 20,000 psi forging capacity creates qualification bottlenecks. Distribution runs through EPC contractors for integrated project awards and direct OEM relationships for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across automation technology generations creates niche entry points as methane compliance deadlines and digital twin adoption curves misalign incumbent upgrade timelines.
For Market Incumbents: Consolidate captive forging capacity for 20,000 psi pressure-class components to defend against emerging Asian forging houses seeking API 6A entry. Acquire digital actuator specialists to preserve integrated project award eligibility as ADNOC and Aramco procurement centralization accelerates. For New Entrants and Emerging Players: Lead with modular subsea tree architectures for marginal field developers in West Africa and Southeast Asia, where standardized redeployable assets unlock economics that bespoke engineering cannot match. Target electric actuator retrofits in Permian Basin legacy fields facing compressed EPA compliance timelines. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement centralization among national oil companies will compress the vendor base to integrated technology conglomerates with captive digital capabilities. Acquisition targets should display subsea qualification testing infrastructure and established NORSOK documentation protocols. The signal to watch is Aramco and ADNOC tender structures shifting from component procurement to bundled wellhead-digital platform awards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging | Captive 20,000 psi alloy steel supply secures margin control against material qualification bottlenecks. |
| Digital Actuator Acquisition | Integrated electro-hydraulic capabilities satisfy bundled tender requirements from Saudi Aramco and ADNOC. |
| Modular Subsea Architecture Development | Standardized tree designs compress installation timelines for West African marginal field economics. |
| NORSOK Certification Investment | Traceability protocol compliance unlocks North Sea supplier eligibility for HPHT field opportunities. |
| Electric Actuator Retrofit Program | Permian Basin pneumatic replacement addresses EPA methane enforcement timelines. |
Study Parameters
Desk research of API specification databases, BSEE enforcement records, and NORSOK standards documentation preceded structured interviews with wellhead engineering directors, procurement managers at national oil companies, subsea installation contractors, and forged alloy steel suppliers. Primary fieldwork captured installation timeline data, qualification testing protocols, and procurement centralization trends. Secondary validation drew from customs trade records, EPC contract disclosures, and regulatory filing repositories. Bottom-up segment sizing triangulated against top-down energy production forecasts.
Variance decomposition across product type, application pressure class, automation protocol, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level volume trajectories and pricing band migrations. Modeled inputs included wellhead installation counts by basin, subsea tree deployment schedules, and pneumatic-to-electric conversion timelines under EPA enforcement protocols.
Forecasts assume regulatory continuity in EPA methane thresholds and BSEE offshore requirements; material policy shifts would require re-modeling. Commodity alloy price volatility and subsea installation contractor availability present additional forecast sensitivity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Flare Stack Monitoring Systems Market
Valves
Sliding Sleeves Market
Valves
Middle East and Africa Machined Seals Market
Valves
Blow - Off Valves Market
Valves
Global Pipeline Safety Market
Valves
Pipeline Equipment Market
Valves
Global Globe Valve Market
Valves
Harmonic Dampers Market
Valves
Valve Cover Gasket Market
Valves
Blasting Stemming Plugs Market
Valves
Global Valve Positioners Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Sand Control System Market
Valves
Flow Computer Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Transmission Overload Protectors Market