
 Safety Valve Market | 2026-2036
Safety Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Valve Market Analysis
Buyer concentration in the oil and gas sector is pivoting toward integrated supermajors and national oil companies with centralized technical procurement teams. Emerson Electric Co leverages its global instrumentation network to anchor long-term service contracts with these consolidated buyers. LESER GmbH & Co. KG specializes in spring-loaded pressure relief technology for European chemical complexes. Curtiss-Wright Corporation competes through its nuclear-qualified safety valve portfolio, sustaining relevance in power generation retrofit programs.
A safety valve is a mechanical device engineered to automatically release a substance from a boiler, pressure vessel, or other system when the pressure or temperature exceeds preset limits, typically constructed with corrosion-resistant alloys and precision-machined seats rated for specific pressure classes. Its primary industrial purpose is protecting personnel, equipment, and the environment from catastrophic overpressure events in continuous-process operations. Pressure relief valves occupy the largest volume share across oil and gas applications, where margin pools concentrate in aftermarket parts and recertification services. Electronic safety valves represent the fastest-expanding product category, driven by digital twin integration and predictive maintenance protocols in chemical processing facilities. Stainless steel dominates material selection for high-temperature hydrocarbon service, while alloy specifications gain share in sour gas environments requiring NACE MR0175 compliance.
ASME Section VIII and API 526 standards govern pressure relief device design and capacity certification in North American jurisdictions, while the EU Pressure Equipment Directive (PED) and ATEX directives shape product conformity requirements for European market access. OSHA Process Safety Management regulations in the United States mandate documented inspection intervals for pressure relief systems, creating recurring demand for testing and replacement services. Stakeholders must monitor evolving hydrogen infrastructure codes, as repurposed natural gas networks and ammonia storage terminals introduce new overpressure scenarios requiring revised valve specifications and certification protocols.
Market Dynamics
ASME Section VIII certification tightening is compressing supplier qualification timelines while simultaneously lengthening replacement cycles for installed base, forcing manufacturers to recalibrate service revenue models around recertification rather than new unit sales.
Growth Catalysts
- Refinery modernization mandates:United States Gulf Coast petrochemical corridor operators are replacing legacy mechanical valves with electronic safety valves to enable remote monitoring and predictive maintenance protocols.
- API 526 standard revisions:Updated capacity certification requirements for pressure relief devices are driving replacement demand across North American oil and gas infrastructure.
- Hydrogen infrastructure buildout:Repurposed natural gas networks and ammonia storage terminals require revised valve specifications, creating specification upgrade cycles for high-pressure gas service.
Market Restraints
- Alloy supply concentration:Corrosion-resistant alloy feedstock for sour gas service concentrates with limited specialty steel producers, exposing valve manufacturers to NACE MR0175-compliant material cost volatility.
- Certification timeline friction:ASME Boiler and Pressure Vessel Code recertification intervals create administrative burden for operators managing large installed bases across multiple pressure classes.
- Mechanical valve substitution:Electronic safety valves with digital twin integration threaten traditional spring-loaded pressure relief valve aftermarket revenue streams.
Strategic Opportunities
- Underpenetrated hydrogen storage:Germany and the Netherlands are advancing ammonia terminal projects requiring specialized high-pressure safety valve configurations for cryogenic and high-temperature hydrogen service.
- EU Pressure Equipment Directive alignment:ATEX directive compliance requirements for chemical processing facilities create specification upgrade pathways for valve manufacturers with existing PED certification infrastructure.
- Digital twin convergence:Integration of IoT sensor arrays with predictive maintenance software is enabling valve-as-a-service business models in continuous-process chemical operations.
Industry Challenges
- Specialized welding certification scarcity:Precision joining of corrosion-resistant alloys for high-temperature hydrocarbon service requires qualified technicians, constraining production scaling for sour gas valve specifications.
- Legacy system integration complexity:Electronic safety valve deployment in brownfield refinery environments demands retrofit engineering to interface with existing distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Valve Market |
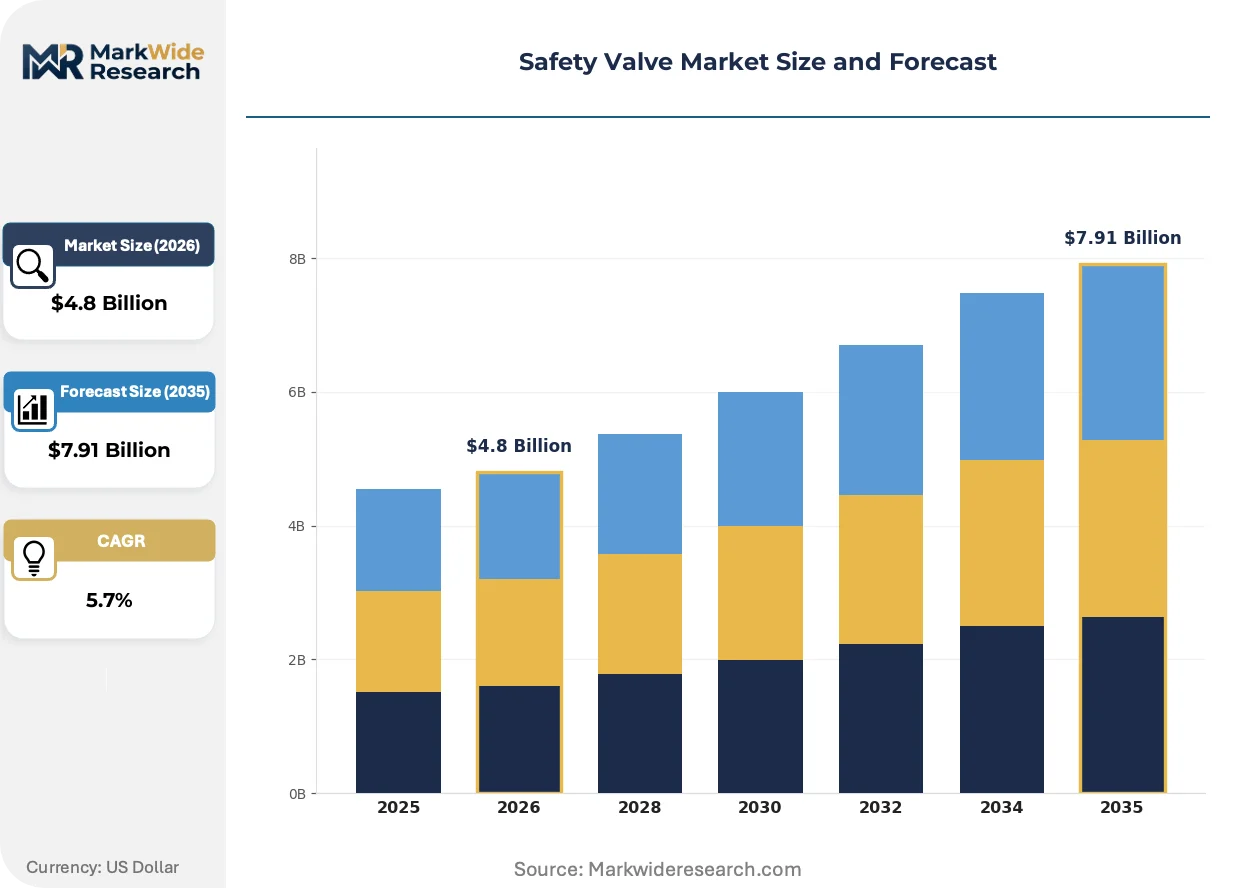
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Relief Valves, Safety Relief Valves, Electronic Safety Valves, Thermal Safety Valves Material: Stainless Steel, Brass, Alloy, Plastics Application: Oil & Gas, Chemical Processing, Power Generation, Water Treatment End User: Industrial Manufacturing, Construction, Utilities, Aerospace |
| Companies Covered | Emerson Electric Co, LESER GmbH & Co. KG, Curtiss-Wright Corporation, Schlumberger Limited, IMI plc, Bosch Rexroth AG, The Weir Group PLC, Alfa Laval, Forbes Marshall, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Valve Market Emerging Trajectories
Digital instrumentation is embedding intelligence directly into pressure relief hardware, compressing the traditional separation between mechanical safety systems and process control networks while redistributing value capture toward software-enabled service providers.
Electronic safety valve architecture is integrating edge computing modules that process pressure and temperature data locally before transmitting anomalies to central monitoring systems. Chemical processing facilities in the Rotterdam-Antwerp chemical cluster are piloting these configurations for predictive maintenance protocols. This integration is compressing response times for overpressure events while shifting competitive advantage toward vendors with instrumentation software capabilities.
REACH chemical substance restrictions are accelerating material substitution timelines for valve seat elastomers and sealing compounds used in European chemical service. Industrial consequence includes accelerated qualification cycles for fluoropolymer alternatives in high-temperature applications. German chemical complexes are responding by front-loading specification reviews to lock in compliant material designs before regulatory phase-in deadlines.
Buyer technical procurement teams at integrated supermajors are consolidating vendor panels and demanding bundled lifecycle service contracts rather than transactional valve purchases. Traditional distribution channels serving independent maintenance contractors are losing share to direct manufacturer relationships. This concentration is most visible in United States Gulf Coast refinery operations where centralized engineering standards now mandate single-source accountability for pressure relief system integrity.
Safety Valve Market Segmentation
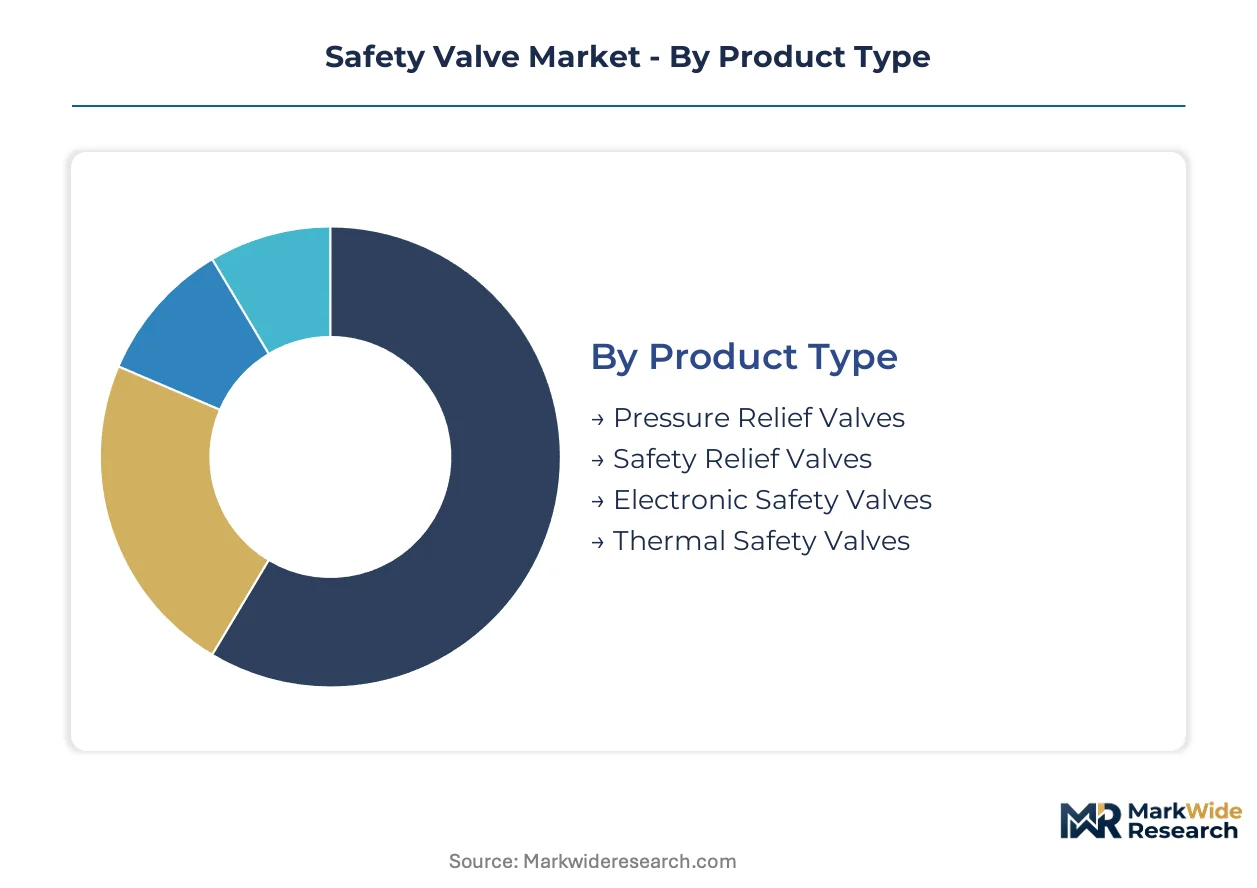
Safety valve procurement patterns diverge sharply across operational contexts. Specification requirements for sour gas service bear little resemblance to water treatment standards. Material certification depth and digital integration capability now determine vendor selection more than unit cost alone.
Product Type:
Customization intensity spans from commodity spring-loaded designs to fully programmable electronic architectures with embedded edge computing.
- Pressure Relief Valves:Spring-loaded mechanical devices with precision-machined seats rated for specific ASME pressure classes. Demand concentrates in United States Gulf Coast refinery modernization programs where API 526 recertification mandates sustain replacement cycles for legacy installed base.
- Electronic Safety Valves:Sensor-integrated architectures enabling remote monitoring and predictive maintenance protocols through digital twin integration. Rotterdam-Antwerp chemical cluster facilities are piloting these configurations for continuous-process operations requiring sub-second anomaly response.
- Safety Relief Valves:Hybrid designs accommodating both liquid and vapor phase relief scenarios in multi-phase hydrocarbon service.
- Thermal Safety Valves:Temperature-actuated devices protecting against thermal expansion in closed liquid systems.
Leading the category by volume: Pressure Relief Valves. Expanding most quickly: Electronic Safety Valves.
Material:
Cost tier stratification runs from commodity brass specifications to NACE MR0175-compliant alloy grades commanding substantial procurement premiums.
- Stainless Steel:Austenitic and duplex grades dominating high-temperature hydrocarbon service across chemical processing facilities. German chemical complexes are front-loading specification reviews to lock in REACH-compliant material designs before regulatory phase-in deadlines.
- Alloy:Corrosion-resistant compositions including Inconel and Hastelloy for sour gas environments. Supply concentrates with limited specialty steel producers, exposing manufacturers to feedstock cost volatility.
- Brass:Cost-effective specification for low-pressure steam and water service in commercial applications.
- Plastics:Fluoropolymer and thermoplastic options for aggressive chemical media where metal corrosion rates exceed acceptable thresholds.
Highest volume material: Stainless Steel. Steepest specification upgrade trajectory: Alloy.
Application:
Maturity gradients separate established hydrocarbon processing from emerging hydrogen infrastructure codes still under technical committee review.
- Oil & Gas:Upstream production, midstream transmission, and downstream refining operations with standardized API certification requirements. United States Gulf Coast petrochemical corridor operators are replacing legacy mechanical valves with electronic configurations for centralized monitoring.
- Chemical Processing:Continuous-process operations requiring ATEX directive compliance for explosive atmosphere protection. EU Pressure Equipment Directive alignment creates specification upgrade pathways for manufacturers with existing PED certification infrastructure.
- Power Generation:Nuclear-qualified safety valve portfolios sustaining relevance in retrofit programs for aging reactor fleets.
- Water Treatment:Municipal and industrial desalination facilities with lower pressure-class requirements and reduced certification burden.
Dominant application by installed base: Oil & Gas. Gaining share fastest: Chemical Processing.
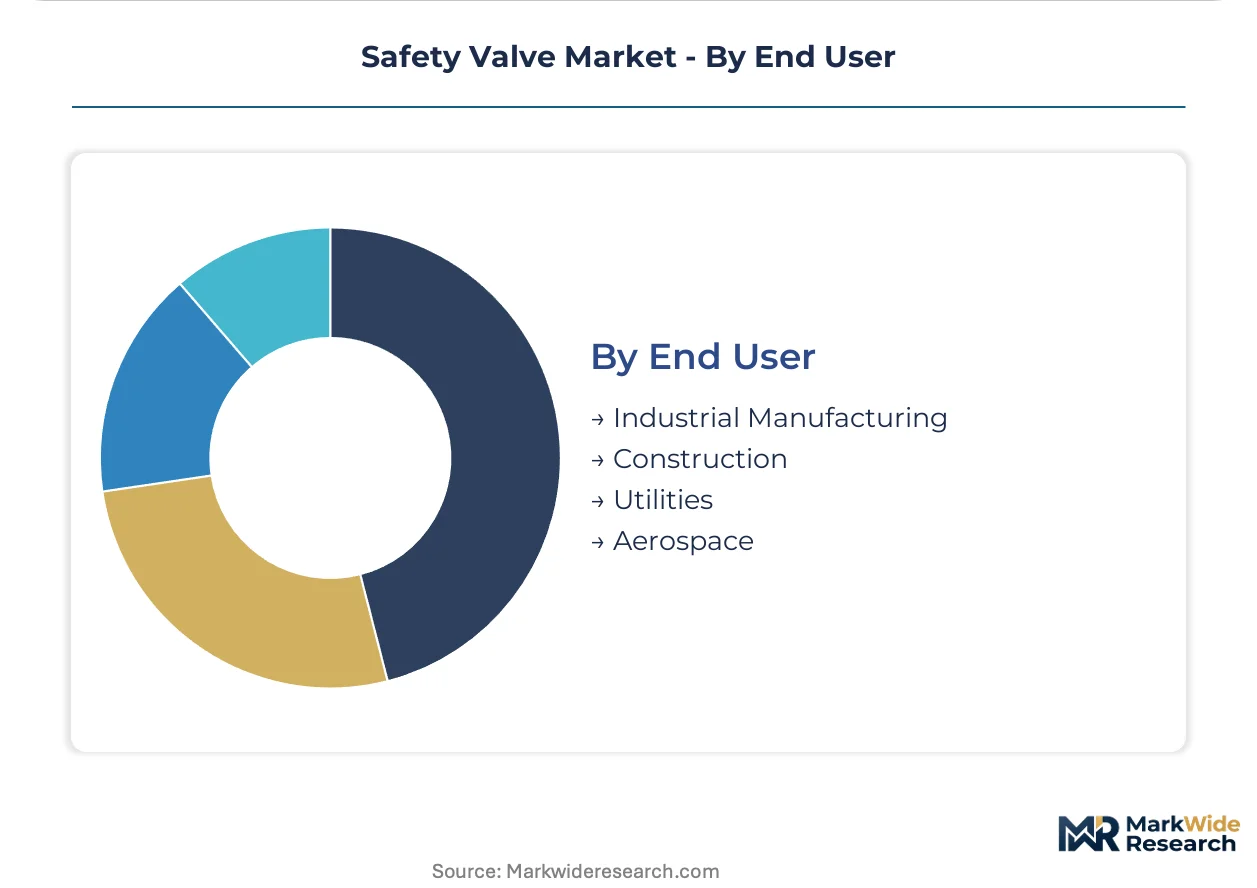
End User:
Customer type fragmentation spans from centralized supermajor procurement teams to distributed independent maintenance contractors.
- Industrial Manufacturing:Petrochemical, pharmaceutical, and food processing facilities with documented OSHA Process Safety Management inspection intervals. Buyer technical procurement teams are consolidating vendor panels and demanding bundled lifecycle service contracts.
- Utilities:Power generation and water distribution operators with regulatory-mandated replacement schedules. FERC pipeline safety regulations govern pressure relief system integrity for natural gas transmission networks.
- Construction:Project-based procurement for greenfield industrial facilities with front-loaded specification locking.
- Aerospace:Specialized high-reliability requirements for propulsion and environmental control systems with extended qualification timelines.
Largest procurement volume: Industrial Manufacturing. Fastest specification evolution: Utilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in industrial corridors with heavy process industry presence, where refinery modernization and chemical complex expansion sustain replacement cycles. Regulatory tightening around pressure equipment certification creates geographic differentiation in vendor qualification timelines. Hydrogen infrastructure buildouts are emerging as a new demand vector in specific national markets.
United States
United States Gulf Coast petrochemical corridor operators are replacing legacy mechanical valves with electronic configurations for centralized monitoring capabilities. OSHA Process Safety Management regulations mandate documented inspection intervals for pressure relief systems, creating recurring service demand. Houston and Corpus Christi industrial clusters anchor North American procurement volume for API 526-certified devices.
Germany
German chemical complexes are front-loading specification reviews to lock in REACH-compliant material designs before regulatory phase-in deadlines. EU Pressure Equipment Directive alignment with ATEX directive requirements shapes product conformity pathways for explosive atmosphere protection. The Ludwigshafen chemical cluster and Ruhr industrial region sustain demand for NACE MR0175-compliant alloy specifications in sour gas service.
China
Chinese refinery expansion and coal-to-chemical projects drive procurement of high-pressure safety valve configurations for continuous-process operations. GB standards and SAMR oversight govern pressure equipment certification timelines for domestic market access. The Yangtze River Delta petrochemical corridor concentrates demand for stainless steel specifications in high-temperature hydrocarbon service.
Saudi Arabia
Saudi Aramco and SABIC expansion programs sustain demand for corrosion-resistant alloy valves in sour gas and high-sulfur crude processing. The country's national oil company procurement standards increasingly mandate electronic valve architectures for remote monitoring integration. The Jubail and Yanbu industrial cities anchor Middle Eastern demand for ASME Section VIII-certified pressure relief devices.
Netherlands
Rotterdam-Antwerp chemical cluster facilities are piloting electronic safety valve configurations with edge computing modules for predictive maintenance protocols. REACH chemical substance restrictions accelerate material substitution timelines for valve seat elastomers in European chemical service. The Port of Rotterdam hydrogen import terminal projects require specialized high-pressure safety valve specifications for ammonia storage and cryogenic hydrogen service.
Safety Valve Market Vendor Landscape
United States producers anchor one tier; German specialists hold certification depth in European chemical markets. The vendor base spans diversified industrial conglomerates with instrumentation networks and focused mechanical fabricators with alloy welding expertise. Three archetypes dominate: integrated automation providers bundling valves with control systems, precision mechanical specialists with ASME-certified foundry operations, and regional fabricators serving maintenance contractor channels. Competitive moves concentrate on long-term service contract capture and hydrogen-ready product qualification.
Within the integrated automation tier, Emerson Electric Co represents the instrumentation-network archetype, leveraging global service infrastructure for lifecycle contract anchoring. Among German mechanical specialists, LESER GmbH & Co. KG exemplifies the precision-certified foundry model with deep ASME and PED qualification infrastructure. Curtiss-Wright Corporation occupies a position bridging nuclear-qualified portfolios with power generation retrofit programs. These three anchors illustrate how competitive positioning splits between software-enabled service bundling and alloy-certification technical depth.
| Leading Market Players |
|---|
| Emerson Electric Co |
| LESER GmbH & Co. KG |
| Curtiss-Wright Corporation |
| Schlumberger Limited |
| IMI plc |
| Bosch Rexroth AG |
| The Weir Group PLC |
| Alfa Laval |
| Forbes Marshall |
| Others |
Supply Flow & Price Mechanics
Centralized technical procurement teams at integrated supermajors are consolidating vendor panels and mandating bundled lifecycle service contracts, forcing suppliers to absorb certification and inventory carrying costs while compressing transactional margin pools toward recertification services. This demand-side consolidation reshapes supplier economics around long-term contract capture rather than unit volume throughput.
Pricing Analysis
Volume concentrates in commodity spring-loaded mechanical valves where margins thin on standardized API 526 certification, while electronic safety valves with embedded edge computing command substantial premiums through predictive maintenance software bundling. Three-tier pricing structure across premium alloy specifications, standard stainless steel grades, and economy brass configurations reflects NACE MR0175 compliance depth and digital integration capability. Cost compression in the mechanical valve tier intensifies as electronic architectures displace legacy installed base, eroding aftermarket parts revenue. Independent maintenance contractors exhibit highest price sensitivity, whereas national oil companies prioritize lifecycle cost guarantees over unit procurement expense.
Supply Chain Analysis
Dual-sourcing requirements for ASME Section VIII-certified pressure relief devices mandate that operators qualify multiple suppliers per pressure class, stretching certification timelines and concentrating procurement leverage with vendors possessing parallel PED and ATEX qualification infrastructure. Specialty steel production for corrosion-resistant alloys concentrates in Germany, Japan, and the United States, with valve manufacturers drawing from limited NACE MR0175-compliant feedstock producers exposed to nickel and chromium price volatility. Single-source vulnerability runs through precision-machined seat suppliers qualified to specific ASME pressure classes. Distribution runs through direct manufacturer relationships with centralized engineering procurement teams, bypassing traditional maintenance contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASME certification tightening and buyer consolidation are accelerating margin compression for undifferentiated mechanical fabricators, forcing a consolidation play where instrumentation-capable incumbents absorb alloy-specialist targets to anchor long-term service contracts.
For Market Incumbents: Extend predictive maintenance software capabilities through digital twin integration to capture valve-as-a-service revenue streams before electronic architectures displace spring-loaded aftermarket parts. Acquire NACE MR0175-qualified welding specialists to secure alloy supply chain control and compress competitor qualification timelines for sour gas specifications. For New Entrants and Emerging Players: Launch via specialized hydrogen-ready valve configurations for ammonia terminal projects in Germany and the Netherlands, where infrastructure buildout has outpaced incumbent product qualification cycles. Target underpenetrated cryogenic hydrogen service with modular edge computing architectures that bypass legacy distributed control system integration complexity. For Investors and Strategic Acquirers: The window for entry favors precision mechanical specialists with ASME-certified foundry operations and existing PED infrastructure, positioned for hydrogen specification upgrade cycles. Watch for inflection when German and Dutch ammonia terminal projects release tender packages requiring revised valve specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Emerson Electric Co leverages instrumentation networks to bundle predictive maintenance software with valve hardware. |
| Alloy Welding Certification Investment | LESER GmbH & Co. KG deepens NACE MR0175-compliant production capacity for sour gas service expansion. |
| Hydrogen-Ready Product Qualification | Curtiss-Wright Corporation extends nuclear-qualified portfolios into high-pressure hydrogen storage specifications. |
| Long-Term Service Contract Anchoring | Supermajor procurement consolidation favors vendors offering single-source accountability for pressure relief system integrity. |
| REACH-Compliant Material Substitution | German chemical complexes front-load specification reviews to lock in fluoropolymer alternatives before regulatory deadlines. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant engineers, maintenance directors at Gulf Coast refineries, OEM procurement teams, and aftermarket service heads. ASME Boiler and Pressure Vessel Code certification databases, API 526 capacity listings, and EU Pressure Equipment Directive conformity assessments provided standardization benchmarks. Bottom-up unit demand estimates triangulated against top-down petrochemical capacity expansion announcements.
Data-stream reconciliation across product type, material specification, application sector, and end-user procurement archetype generated volume and value outputs throughout the forecast period. CAGRs derived from installed base replacement cycle analysis, hydrogen infrastructure project pipelines, and electronic safety valve adoption curves in Rotterdam-Antwerp chemical cluster pilots. Modeled inputs included refinery modernization program announcements, REACH regulatory phase-in timelines, and NACE MR0175 alloy supply constraints.
ASME Section VIII recertification interval revisions, hydrogen infrastructure code finalization delays, and specialty steel feedstock price volatility are the dominant revision risks. Deviation in ASME certification timeline compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Carbon Seal Rings Market
Valves
Global Valve Positioners Market
Valves
Industrial Valves Market
Valves
Pressure Gauge Market
Valves
Global Thermostatic Radiator Valve Market
Valves
Mechanical Shaft Seal Market
Valves
Portable Valve Actuator Market
Valves
Pup Joint Market
Valves
Pressure Reducing Valve Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
Total Containment Vessels Market
Valves
Valve Remote Control System Market
Valves
Air Heated Vaporizer Market
Valves
Valve Driver Market
Valves
Vacuum Insulated Pipe Market
Valves
Explosion Isolation Valves Market