
 Subsea Valves Market | 2026-2036
Subsea Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Subsea Valves Market Outlook
Deepwater oil and gas extraction is broadening the addressable market for subsea valve systems. SLB OneSubsea leverages integrated subsea production technologies to anchor its position in high-pressure environments. Baker Hughes sustains competitive differentiation through extensive R&D in metallurgy and sealing systems. TechnipFMC dominates the umbilical and flowline integration segment, controlling project economics for integrated subsea packages.
Subsea valves are pressure-containing devices engineered to operate at depths exceeding 3,000 meters, with pressure ratings up to 20,000 psi and materials specified to resist chloride-induced stress corrosion cracking in seawater environments. Their primary purpose is to isolate, regulate, and direct hydrocarbon flow across subsea wellheads, manifolds, and export pipelines. Ball valves capture the largest product type share due to their quarter-turn operation reliability and bidirectional sealing capability, while hydraulic actuation technology leads installation preference for remote subsea applications where electric power infrastructure remains limited. The offshore installation segment generates premium margin pools tied to project complexity and diving support vessel availability.
API 6DSS and ISO 13628-4 standards govern subsea valve design verification and factory acceptance testing, while NORSOK M-001 imposes additional material requirements for Norwegian continental shelf deployments. The EPA and BSEE in the United States enforce spill containment mandates that directly shape blow-off valve specification and redundancy architecture. Stakeholders must monitor regulatory divergence between prescriptive North Sea standards and performance-based Gulf of Mexico frameworks when configuring global product portfolios.
Market Dynamics
Deepwater field development economics now hinge on subsea valve reliability at extreme pressures, forcing operators to consolidate procurement around certified suppliers capable of API 6DSS-compliant manufacturing and integrated system architecture.
Growth Catalysts
- Pre-salt exploration:Brazil's Santos Basin discoveries require subsea production systems rated for 20,000 psi operating pressure, driving specification upgrades across valve portfolios.
- API 6DSS certification mandates:Operator procurement policies now require third-party witnessed factory acceptance testing, filtering supplier bases toward qualified manufacturers.
- Hydraulic actuation advances:Subsea control module miniaturization enables remote valve operation at 3,000-meter depths without subsea power infrastructure.
Market Restraints
- Nickel alloy supply concentration:Super duplex and Inconel feedstock sourcing concentrates among specialty steel mills in Sweden and Japan, exposing valve fabricators to raw material availability risk.
- Extended qualification timelines:API 6DSS design verification and subsea factory acceptance testing cycles stretch 18-24 months, constraining supplier capacity expansion.
- Subsea processing substitution:All-electric subsea systems reduce hydraulic valve dependency in greenfield developments, threatening legacy actuator architectures.
Strategic Opportunities
- West African frontier basins:Senegal and Mauritania offshore discoveries lack established subsea service infrastructure, creating first-mover positioning for integrated valve-package suppliers.
- Carbon capture integration:Subsea CO2 injection wells require corrosion-resistant valve metallurgy adapted from hydrocarbon service, opening adjacent application expansion.
- Digital twin deployment:Real-time valve performance monitoring combined with predictive maintenance contracts enables recurring revenue streams beyond equipment sale.
Industry Challenges
- Subsea welding certification scarcity:Qualified hyperbaric welders and weld procedure qualification records limit fabrication throughput at specialist facilities.
- Legacy system interoperability:New intelligent valve actuators must interface with 1990s-era subsea control systems through protocol translation layers, complicating field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subsea Valves Market |
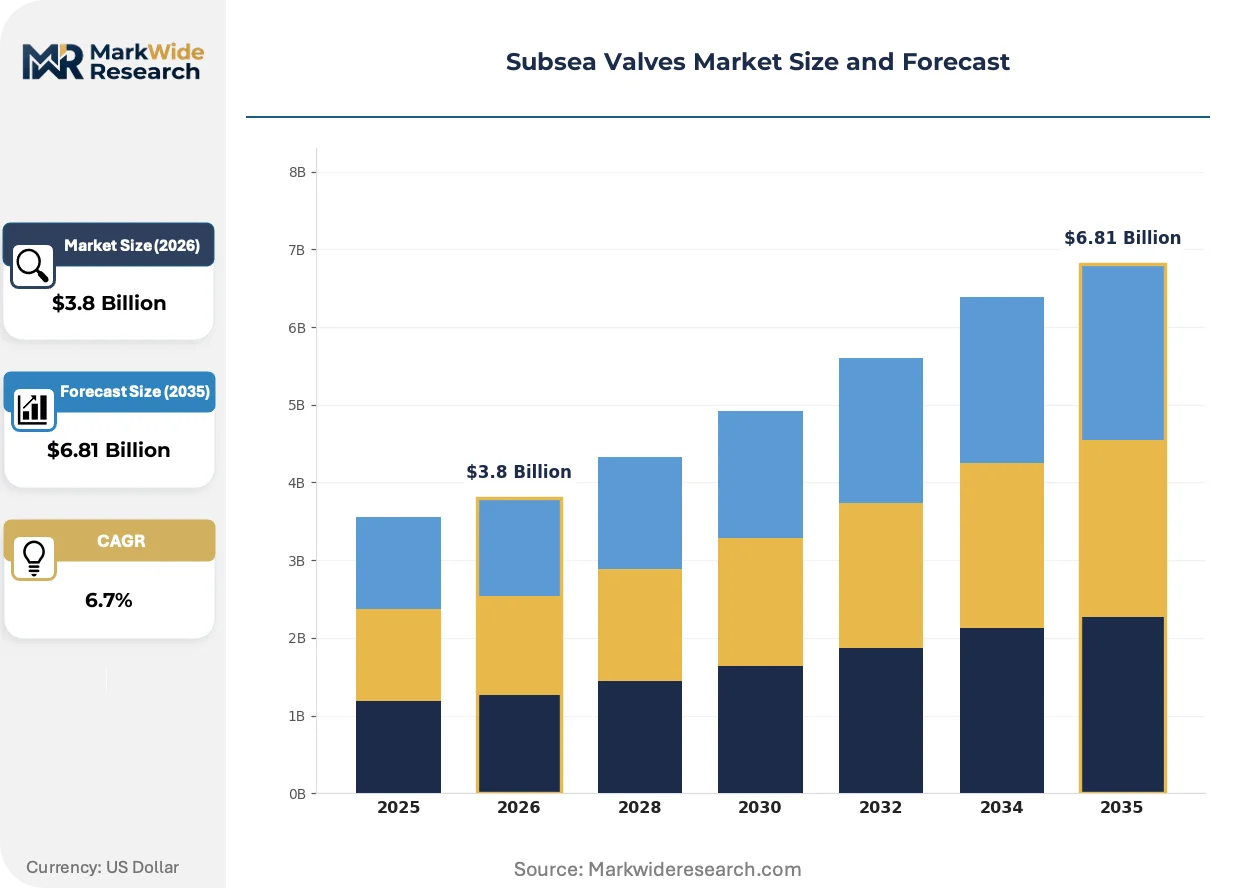
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Check Valves, Blow-off Valves Technology: Manual, Electric, Hydraulic, Pneumatic End User: Oil & Gas, Marine, Renewable Energy, Mining Installation: Onshore, Offshore, Submarine, Platform |
| Companies Covered | FITOK Group, BEL Valves, Oliver Valves, Flowserve Corporation, SLB OneSubsea, Baker Hughes, TechnipFMC, Perar S.p.A., PetrolValves, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subsea Valves Market Strategic Shifts
Subsea valve engineering is converging with digitalization and materials science to extend operational envelopes beyond conventional pressure-temperature ratings. Three developments are redefining competitive differentiation.
Additive manufacturing of Inconel valve bodies is integrating lattice structures that reduce weight by 40% while maintaining pressure containment integrity. Norwegian fabricators are qualifying laser powder bed fusion components for subsea choke valve applications. This technology is integrating complex internal flow geometries previously impossible with conventional machining, compressing lead times for custom pressure-drop specifications.
EPA spill containment mandates under BSEE regulations now require redundant blowout preventer valve architectures with independent shear and seal capabilities. Offshore operators in the Gulf of Mexico are retrofitting existing subsea trees with secondary isolation systems. High-pressure high-temperature (HPHT) developments above 15,000 psi face the most stringent compliance timelines, accelerating qualification programs for dual-barrier valve designs.
Integrated service contracts now bundle valve supply with installation supervision and life-of-field maintenance, displacing transactional equipment procurement. National oil companies in Brazil and Norway are mandating operator presence commitments from valve suppliers. This model concentrates procurement authority with integrated subsea contractors capable of warrantying system-level performance rather than component-level specifications alone.
Subsea Valves Market Segmentation
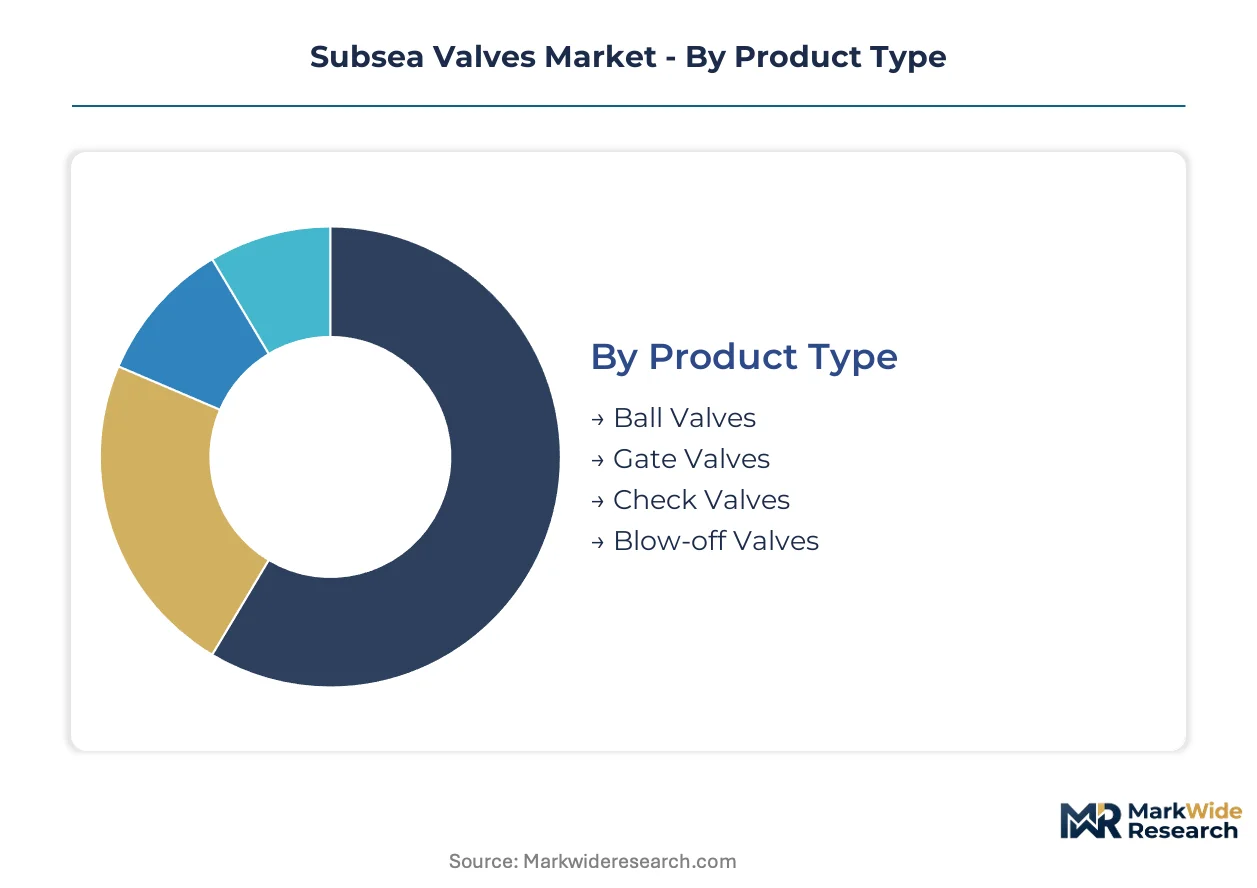
Subsea valve procurement patterns diverge sharply across technical specifications and deployment contexts. Understanding these fault lines exposes where specification upgrades concentrate and which customer archetypes drive replacement cycles.
Product Type:
Replacement cycles in mature subsea fields now favor higher-specification valve architectures over like-for-like swaps, reshaping demand composition across product categories.
- Ball Valves:Quarter-turn sealing mechanisms with bidirectional pressure containment suit high-cycle isolation duties at wellheads and manifolds. Brazil's pre-salt developments specify forged Inconel 625 bodies rated for 20,000 psi, forcing fabricators to expand superalloy machining capacity.
- Gate Valves:Linear-motion closure elements provide full-bore flow paths essential for pigging operations and sand-laden production streams. Norwegian continental shelf operators favor expanding gate designs with metal-to-metal seats for HPHT Christmas tree installations, where API 6DSS qualification timelines stretch procurement lead times.
- Check Valves:Passive flow-direction devices prevent backflow in subsea distribution manifolds.
- Blow-off Valves:Emergency pressure relief mechanisms protect against overpressure events in enclosed subsea modules.
Ball valves sit at the top of the volume ranking, with gate valves climbing the fastest as HPHT field complexity intensifies.
Technology:
Actuation technology selection hinges on subsea power infrastructure availability and control system vintage, creating divergent cost tiers across installation archetypes.
- Hydraulic:Pressurized fluid networks enable reliable valve operation at 3,000-meter depths without electric umbilical dependency. Gulf of Mexico brownfield tiebacks favor hydraulic actuation for compatibility with 1990s-era subsea control systems, though all-electric substitution threatens long-term demand.
- Electric:All-electric actuators eliminate hydraulic fluid leak paths and enable precise position feedback for digital twin integration. Norway's Equinor-led developments specify electric valve control for environmental compliance, driving supplier R&D into high-torque subsea motor sealing.
- Manual:Diver-operated valve systems serve shallow-water inspection and maintenance scenarios.
- Pneumatic:Compressed-gas actuation finds niche application in platform-based processing equipment.
Hydraulic technology commands the largest installed base, while electric actuation gains share fastest as greenfield projects prioritize all-electric architectures.
End User:
Customer procurement sophistication varies dramatically by sector, with hydrocarbon operators imposing the most stringent qualification regimes.
- Oil & Gas:Exploration and production companies dominate subsea valve procurement through integrated subsea production system contracts. Brazil's Petrobras mandates local content requirements that force valve suppliers to establish domestic fabrication partnerships, extending project timelines but securing market access.
- Marine:Subsea mining and dredging operations require corrosion-resistant valve specifications adapted from hydrocarbon service.
- Renewable Energy:Offshore wind foundation installation vessels deploy subsea valve systems for jacket pile-driving and cable-laying equipment.
- Mining:Deep-sea mineral extraction prototypes test valve reliability in abrasive slurry environments.
Oil and gas sits at the top of the volume ranking, with renewable energy climbing the fastest as offshore wind installation fleets expand.
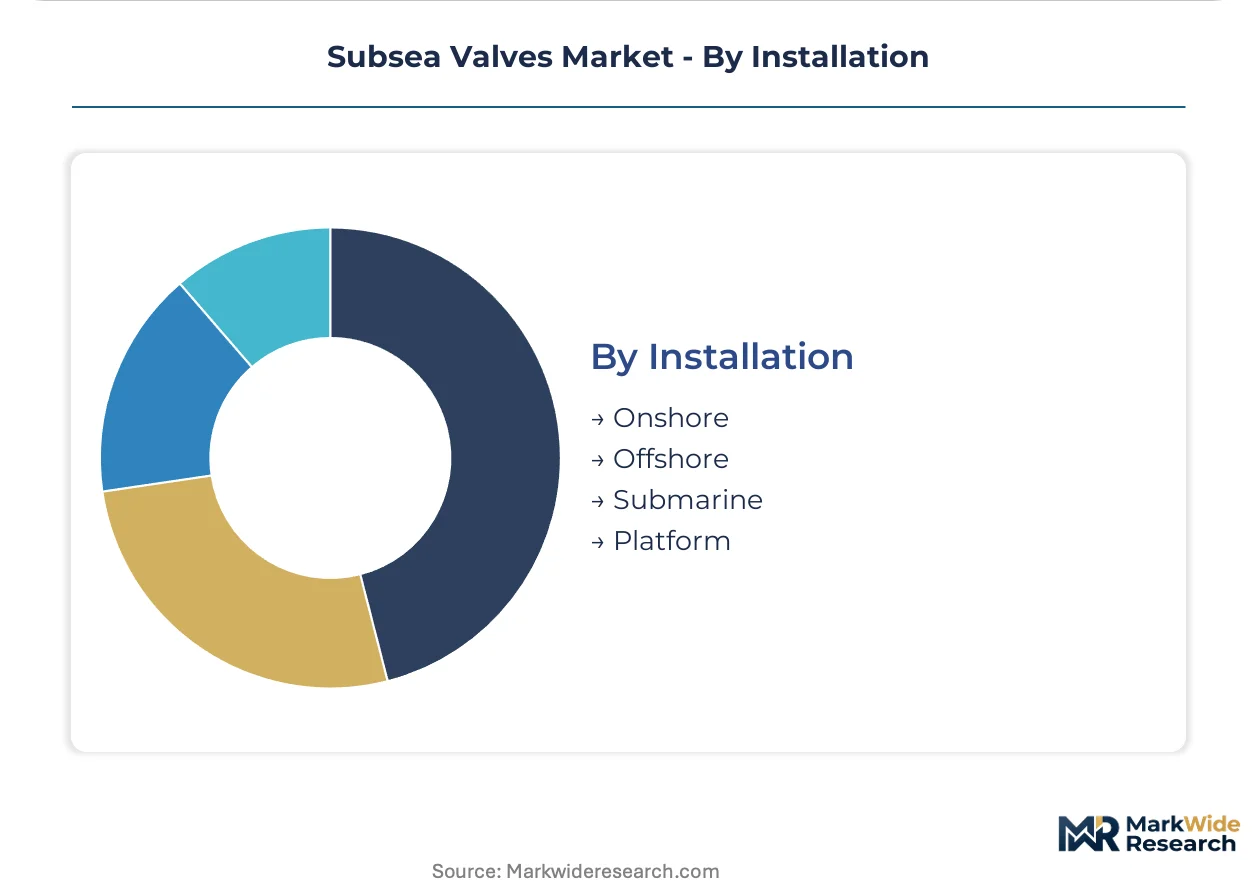
Installation:
Deployment context determines margin structure, with subsea installation commanding premium pricing tied to diving support vessel day rates and hyperbaric welding certification scarcity.
- Offshore:Subsea tree and manifold installations require valves qualified for direct seawater exposure and cathodic protection compatibility. United States Gulf Coast developments face BSEE spill containment mandates that specify redundant barrier valve architectures, doubling component counts for critical isolation points.
- Submarine:Pipeline end manifold and tie-in spool applications demand valves with diverless installation interfaces.
- Onshore:Surface facility valve specifications align with conventional oil and gas processing standards.
- Platform:Fixed and floating production platform valve systems operate above the splash zone with reduced environmental exposure.
Offshore installation sits at the top of the volume ranking, with submarine deployment climbing the fastest as remote tieback architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Gulf Coast anchors subsea valve procurement intensity through deepwater developments in the Gulf of Mexico. Brazil and Norway concentrate the next tier of demand through pre-salt and North Sea field expansions.
United States
The Gulf of Mexico drives procurement through HPHT developments exceeding 15,000 psi operating pressure. BSEE spill containment mandates under EPA oversight require redundant blowout preventer valve architectures. Houston hosts the dominant engineering cluster where SLB OneSubsea and Baker Hughes coordinate integrated subsea package delivery.
Brazil
Petrobras pre-salt discoveries in the Santos Basin specify 20,000 psi rated valve systems for ultra-deepwater production. ANP local content regulations force foreign suppliers to establish domestic fabrication partnerships. The Macaé industrial corridor hosts valve qualification facilities serving Campos and Santos basin developments.
Norway
Equinor-led developments in the Norwegian continental shelf prioritize all-electric valve actuation for environmental compliance. NORSOK M-001 imposes additional material requirements beyond API 6DSS for subsea deployments. Stavanger and Bergen anchor the supplier engineering cluster where TechnipFMC coordinates umbilical and flowline integration.
United Kingdom
North Sea decommissioning and brownfield tiebacks sustain replacement demand for hydraulic valve systems. The Health and Safety Executive enforces functional safety standards for subsea isolation systems. Aberdeen maintains its position as the primary subsea engineering hub through OFS operator concentration.
China
State-owned oil companies expand deepwater exploration in the South China Sea, driving specification upgrades for high-pressure subsea valves. MIIT domestic equipment procurement policies favor local valve fabricators for offshore platform projects. Shenzhen and Tianjin host emerging subsea equipment manufacturing clusters serving CNOOC developments.
Subsea Valves Market Competitive Environment
Capacity expansion dominates the current landscape as qualified suppliers invest in superalloy machining and hyperbaric welding certification. The market structures around a tiered supplier base with integrated subsea contractors at the apex and specialized valve fabricators occupying mid-tier positions. Three archetypes define competitive positioning: full-system integrators bundling valves with production trees, component specialists focusing on high-pressure metallurgy, and regional fabricators serving local content mandates. M&A activity and strategic partnerships represent the dominant competitive moves as suppliers seek API 6DSS qualification breadth.
Among integrated subsea contractors, SLB OneSubsea, Baker Hughes, and TechnipFMC exemplify the full-system archetype. These entities occupy positions where valve supply merges with installation supervision and life-of-field maintenance commitments. FITOK Group and BEL Valves represent the component specialist tier, anchoring procurement alternatives for operators seeking qualified valve sourcing outside integrated packages. Flowserve Corporation sits within the diversified industrial valve segment, bridging onshore process expertise with offshore qualification requirements.
| Leading Market Players |
|---|
| FITOK Group |
| BEL Valves |
| Oliver Valves |
| Flowserve Corporation |
| SLB OneSubsea |
| Baker Hughes |
| TechnipFMC |
| Perar S.p.A. |
| PetrolValves |
| Others |
Value Chain & Pricing Dynamics
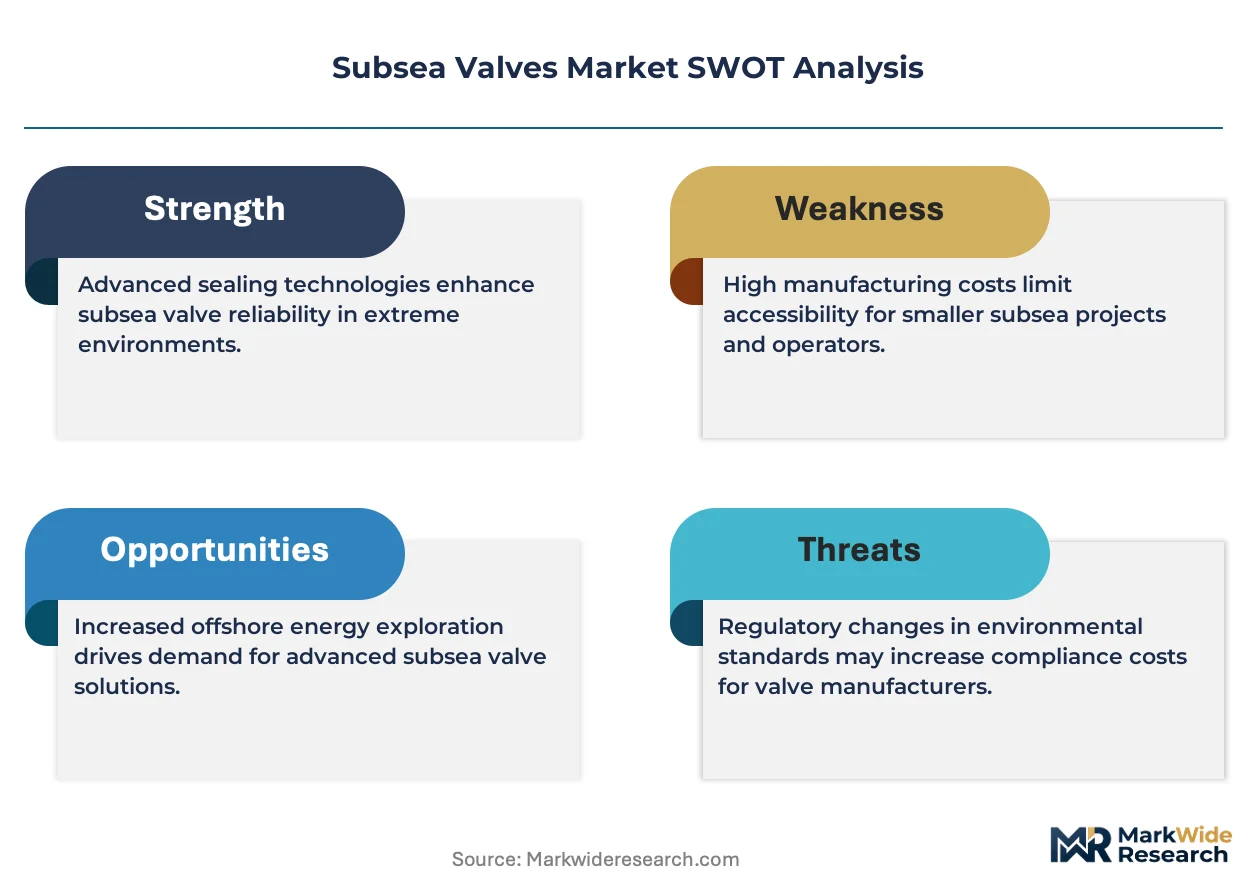
API 6DSS certification mandates from Petrobras and Equinor are forcing valve fabricators toward superalloy machining investments and extended qualification timelines, compressing supplier margins and elevating pricing power for qualified manufacturers capable of third-party witnessed factory acceptance testing.
Pricing Analysis
Input-cost pass-through from Inconel 625 and super duplex stainless steel feedstock dominates pricing dynamics, with specialty steel mills in Sweden and Japan anchoring raw material sourcing. Three-tier pricing structure across API 6DSS-certified premium, standard-qualified, and non-certified economy levels separates procurement tiers, with certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from nickel alloy supply concentration, with margins tightening most acutely for mid-tier fabricators lacking backward integration into superalloy sourcing. National oil companies in Brazil and Norway exhibit lowest price sensitivity due to local content mandates, while independent operators in West African frontier basins drive hardest bargaining on unit costs.
Supply Chain Analysis
API 6DSS and NORSOK M-001 qualification requirements gate supply chain participation, concentrating certified fabrication capacity in Norway, the United States, and Brazil where hyperbaric welding certification and witnessed testing infrastructure exists. Super duplex stainless steel, Inconel 625, and subsea hydraulic control modules constitute critical input dependencies, with sourcing anchored in Swedish and Japanese specialty metallurgy. Single-source vulnerability around qualified hyperbaric welders and weld procedure qualification records constrains throughput expansion at specialist facilities. Distribution runs through integrated subsea contractors bundling valve supply with installation supervision and life-of-field maintenance commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, with pre-salt and HPHT field developments forcing procurement consolidation around certified suppliers capable of 20,000 psi rated system architecture.
For Market Incumbents: Cement API 6DSS qualification breadth across ball, gate, and choke valve portfolios to defend against all-electric substitution threats from greenfield developments. Expand hyperbaric welding capacity in Brazil's Macaé industrial corridor to satisfy Petrobras local content mandates. Deepen backward integration into Inconel feedstock sourcing through long-term offtake agreements with Swedish specialty mills. For New Entrants and Emerging Players: Digital-channel routes through predictive maintenance platforms and valve performance digital twins offer lower-friction entry paths than hardware fabrication. Target West African frontier basins in Senegal and Mauritania where subsea service infrastructure remains underdeveloped and qualification timelines are less entrenched. Pursue carbon capture integration opportunities by adapting corrosion-resistant hydrocarbon valve metallurgy for subsea CO2 injection service. For Investors and Strategic Acquirers: Asymmetric upside sits with component specialists possessing API 6DSS qualification in choke valve applications where additive manufacturing of Inconel lattice structures is compressing lead times. Five-to-ten year viability hinges on positioning for all-electric architecture transition while maintaining hydraulic legacy system interoperability. Watch Equinor procurement specifications for electric actuator mandates as inflection signal for technology substitution pace.| Strategic Initiative | Industry Significance |
|---|---|
| API 6DSS Certification Expansion | Third-party witnessed testing unlocks Petrobras and Equinor procurement eligibility. |
| Superalloy Machining Capacity Buildout | Inconel 625 forging capability satisfies 20,000 psi pre-salt pressure ratings. |
| Additive Manufacturing Qualification | Laser powder bed fusion reduces choke valve weight by 40% while maintaining integrity. |
| All-Electric Actuator R&D Investment | High-torque subsea motor sealing addresses Norway environmental compliance mandates. |
| Digital Twin Platform Deployment | Real-time performance monitoring enables recurring revenue beyond equipment sale. |
Study Parameters
Direct dialogue with subsea procurement managers at national oil companies, valve fabrication engineers, hyperbaric welding specialists, and subsea control system integrators grounded qualitative findings in operational reality. Secondary validation drew from API 6DSS specification documents, BSEE spill containment enforcement records, NORSOK M-001 material standards, ANP local content regulations, and SEC filings from integrated subsea contractors. Bottom-up and top-down triangulation cross-checked fabrication capacity estimates against field development project pipelines.
Bottom-up modeling aggregated individual valve unit economics across ball, gate, check, and blow-off categories, while top-down analysis calibrated aggregate market expansion against deepwater capital expenditure trajectories across the analysis window. Segmentation dimensions included product type, actuation technology, end-use sector, and installation context, with pressure rating tiers and regional regulatory clusters as additional industry-specific variables. CAGRs were derived from project-level procurement timing and replacement cycle analysis in mature North Sea fields.
Pre-salt exploration delays, nickel alloy supply disruptions, and accelerated all-electric substitution are the dominant revision risks to forecast assumptions. Deviation in Brazilian or Norwegian regulatory stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Flanges Market
Valves
Europe Butterfly Valve Market
Valves
Air Jet Ejectors Market
Valves
Explosion Proof Solenoid Valves Market
Valves
Global Solenoid Valves Market
Valves
Global Automotive Valves Market
Valves
North America Irrigation Valves Market
Valves
Industrial Safety Valves Market
Valves
Stainless Steel Valve Tag Market
Valves
Ball Valves Market
Valves
High-Purity Fluoropolymer Valves Market
Valves
Pneumatic Positioner Market
Valves
Explosion Vents Market
Valves
Air Heated Vaporizer Market
Valves
Carbon Seal Rings Market
Valves
Emergency Shutdown Valves Market