
 North America Industrial Valves Market | 2026-2036
North America Industrial Valves Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Valves Market Foresight
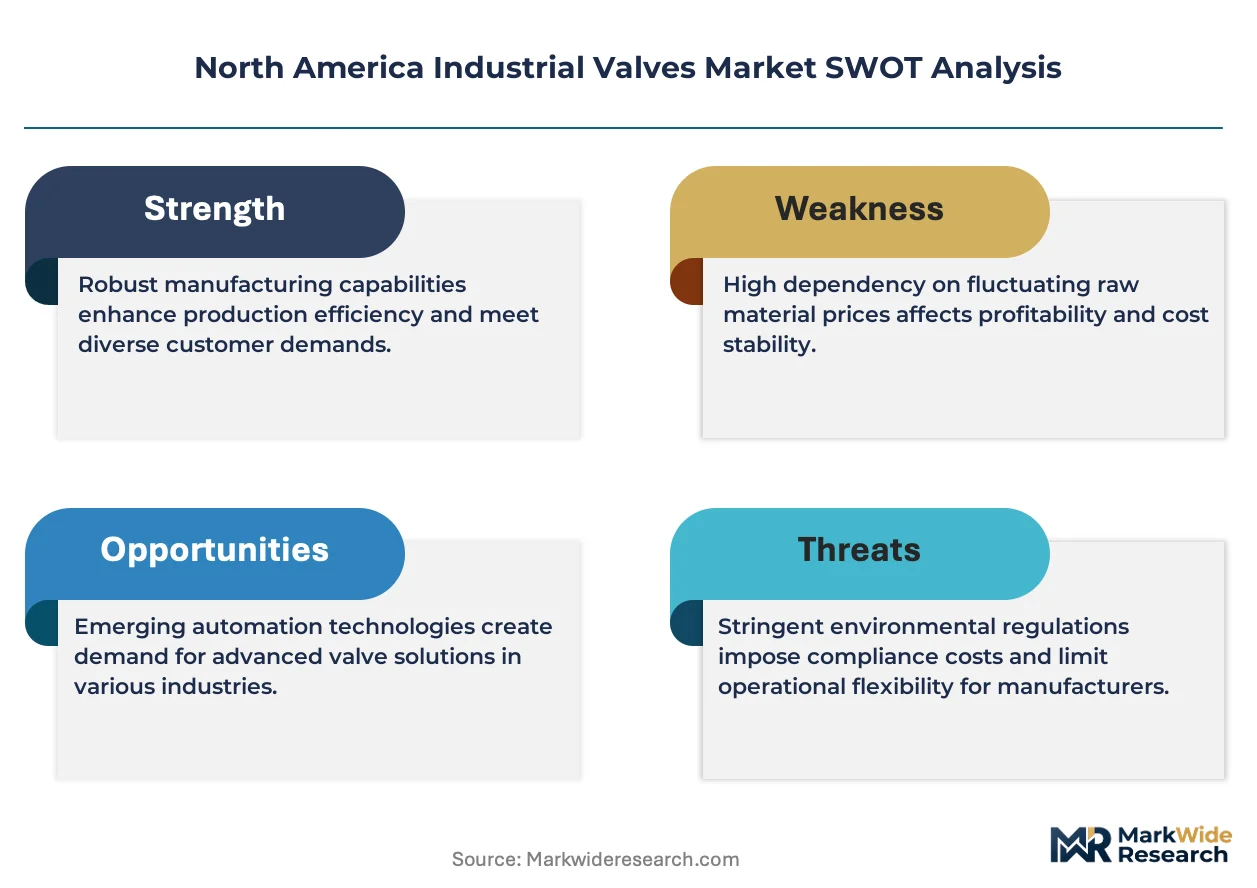
Asset-light leasing and performance-based contracting for critical valve fleets is reshaping competitive entry barriers across North America. Emerson Electric Co. leverages its distributed automation platform to bundle valve diagnostics with process control. Flowserve Corporation anchors its position through aftermarket service networks spanning Gulf Coast refineries. Baker Hughes competes via turbomachinery integration that positions valves within broader rotating equipment packages.
Industrial valves are mechanical devices engineered to regulate, direct, or control fluid flow through pipelines and process systems, typically rated by pressure class, temperature tolerance, and CV flow coefficient to match specific operational envelopes. Ball valve configurations dominate high-cycle applications across chemical manufacturing due to quarter-turn sealing reliability and reduced maintenance intervals. Stainless steel material grades command premium positioning in power generation steam circuits where corrosion resistance extends replacement cycles. Gate valve demand concentrates in water treatment distribution networks where full-bore, low-pressure-drop operation remains essential for bulk flow management.
The EPA enforces fugitive emissions standards under New Source Performance Standards that mandate low-leak packing and bellows-sealed designs for valve installations in volatile organic compound service. API 6D and API 600 certification requirements from the American Petroleum Institute govern pipeline and refinery valve construction, effectively filtering market access for uncertified manufacturers. ASME Boiler and Pressure Vessel codes further constrain product qualification for power sector applications. Stakeholders must monitor how evolving methane rules and state-level water infrastructure funding allocations redistribute demand across end-user segments and material specifications.
Market Dynamics
The EPA's methane emissions rules are compressing replacement cycles across aging pipeline infrastructure while simultaneously filtering uncertified suppliers from volatile organic compound service. This regulatory pressure is concentrating procurement authority among operators with capital to absorb compliance-driven fleet upgrades.
Growth Catalysts
- EPA Methane Standards:The New Source Performance Standards mandate low-leak packing and bellows-sealed designs, forcing systematic valve replacement across oil and gas gathering lines and expanding addressable demand for certified manufacturers.
- Petrochemical Cluster Density:Texas and Louisiana host concentrated refining and chemical processing capacity where single-operator procurement scale drives multi-year framework agreements and reduces vendor switching.
- Ball Valve Quarter-Turn Reliability:Chemical manufacturers favor high-cycle ball configurations for reduced maintenance intervals, sustaining replacement demand even in flat production environments.
Market Restraints
- Stainless Steel Input Volatility:Nickel and chromium price swings compress margin predictability for power sector steam circuit suppliers locked into long-delivery contracts.
- ASME Certification Barriers:The Boiler and Pressure Vessel code qualification timeline extends 18-24 months, freezing out new entrants from power generation procurement cycles regardless of technical capability.
- Bellows-Sealed Cost Premium:Fugitive emissions compliance hardware adds 40-60% material cost over conventional packing, limiting adoption among municipal water operators with constrained capital budgets.
Strategic Opportunities
- Canadian Oil Sands Expansion:Alberta thermal extraction projects require severe-service valve specifications that command premium positioning and long-term service attachment rates.
- Digital Positioner Convergence:Integration of HART-enabled diagnostics with distributed control systems enables predictive maintenance contracts that capture recurring revenue streams.
- State Water Infrastructure Funding:Bipartisan infrastructure allocations to Great Lakes region treatment facilities are accelerating gate valve procurement for distribution network rehabilitation.
Industry Challenges
- API 6D Testing Bottlenecks:Fire-safe and cryogenic certification queues at accredited laboratories extend product launch timelines, delaying revenue recognition for new product lines.
- Legacy SCADA Integration Friction:Smart valve actuator deployment requires protocol translation layers that complicate commissioning and expand field engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Valves Market |
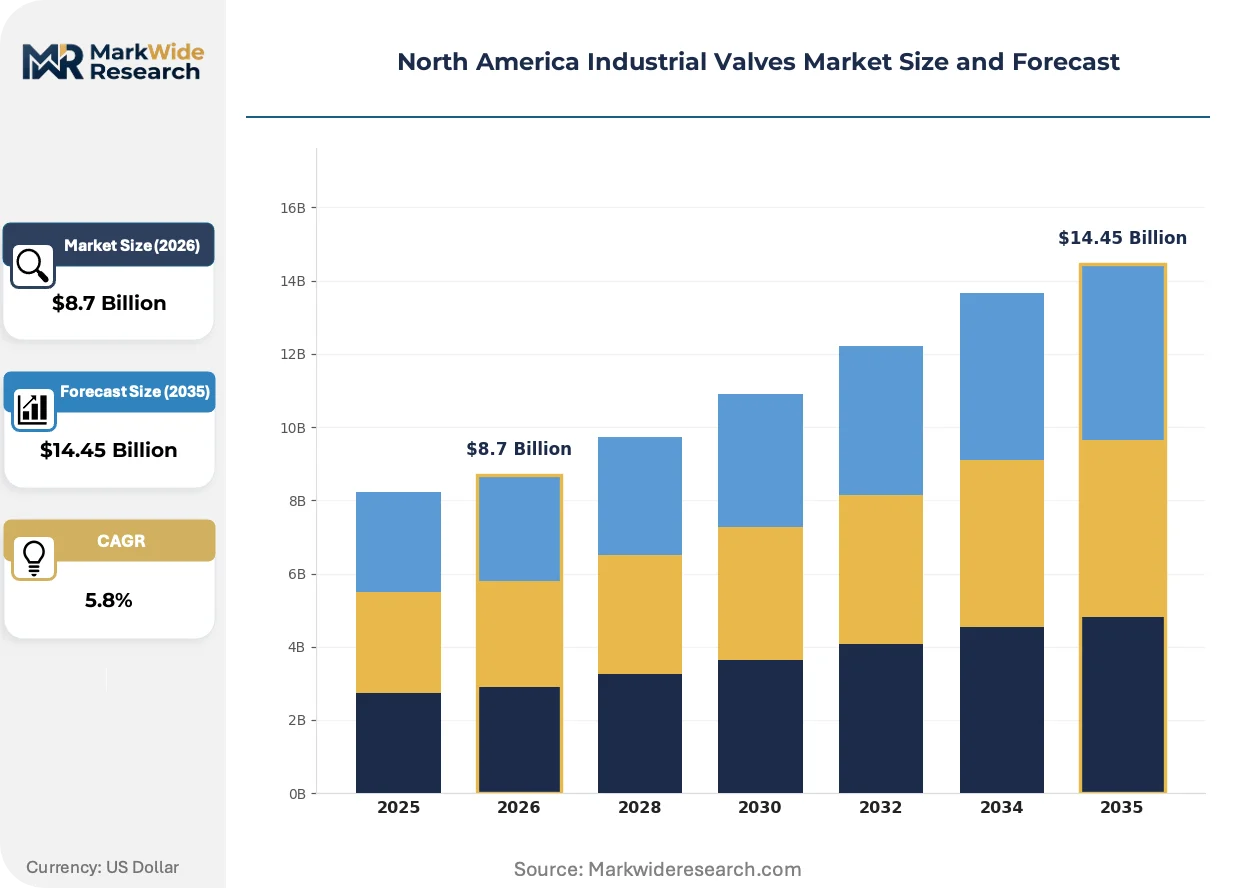
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gate Valve, Globe Valve, Check Valve, Ball Valve Material: Stainless Steel, Carbon Steel, Brass, PVC End User: Oil & Gas, Water Treatment, Power Generation, Chemical Manufacturing Size: Small, Medium, Large, Extra Large |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Crane Company, Alfa Laval, Baker Hughes, IMI, Curtiss-Wright, KITZ Corporation, Schlumberger Limited, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Valves Market Shifts & Advancements
Valve intelligence is migrating from discrete hardware to embedded diagnostic platforms that compress maintenance intervals and shift supplier revenue toward service attachment. This evolution favors automation-integrated vendors with field service density.
Metal-seated ball valve technology is hybridizing ceramic and tungsten carbide coating processes to extend service life in erosive slurry applications. Mining operators in Alberta's oil sands and Arizona's copper belt are specifying these configurations for 10-year replacement cycles. The technology is hybridizing procurement criteria by merging sealing performance with predictive wear monitoring.
The EPA's New Source Performance Standards are tightening fugitive emissions thresholds for volatile organic compound service. Refinery operators must now document packing leakage rates below 500 ppm, driving specification shifts toward live-loaded packing systems. Gulf Coast petrochemical complexes are responding by consolidating vendor lists to suppliers with certified low-leak product lines.
Buyer concentration among supermajor operators is compressing negotiation leverage for mid-tier valve manufacturers. Integrated oil companies are unbundling valve supply from installation and commissioning, forcing suppliers to compete on unit cost while engineering contractors capture service margins. This pattern is most pronounced in Texas Permian Basin development where drilling efficiencies have concentrated procurement with five dominant exploration operators.
North America Industrial Valves Market Segmentation
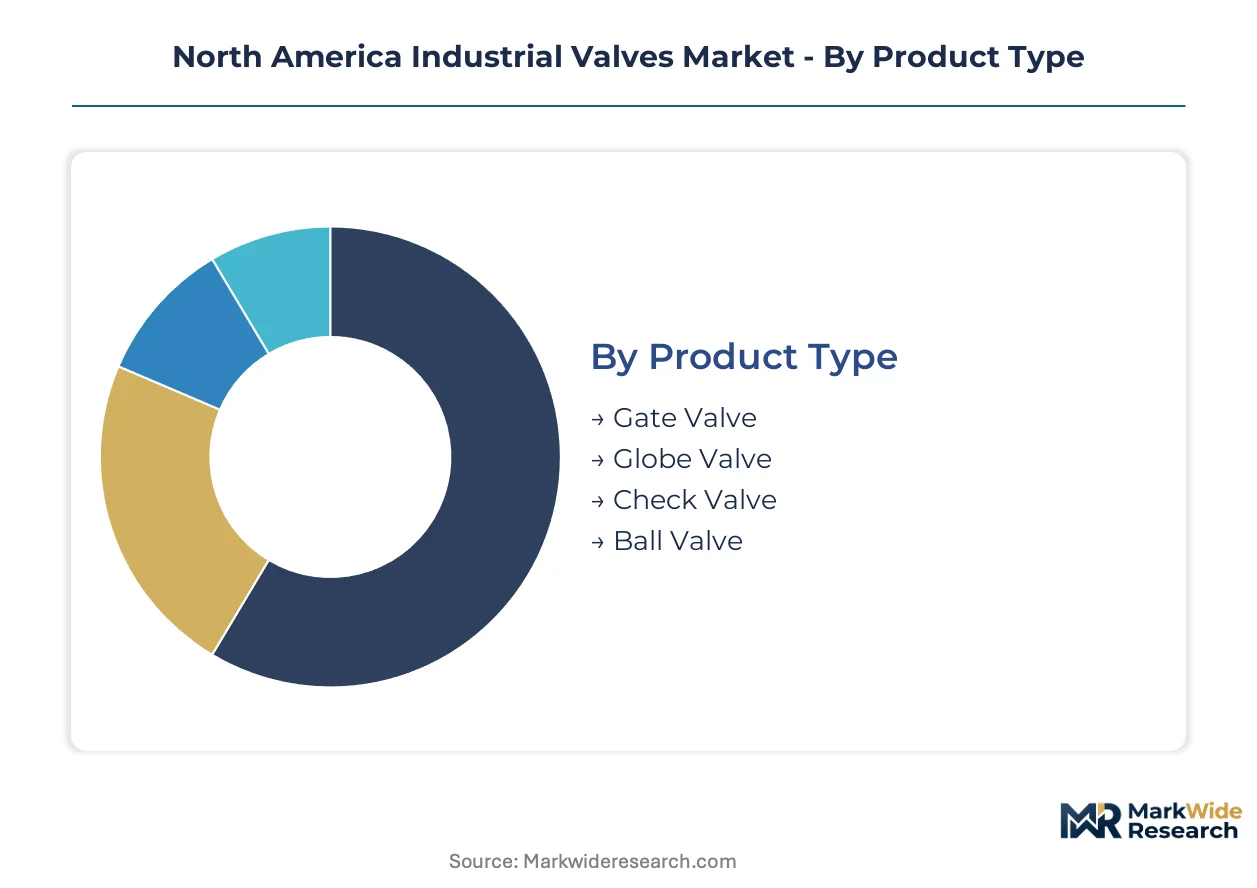
Industrial valve procurement patterns diverge sharply across operational environments, with pressure ratings and media compatibility dicting material and configuration choices. Understanding these segment boundaries clarifies where specification premiums concentrate and where commoditization pressures dominate.
Product Type:
Quarter-turn and multi-turn mechanisms serve distinct cycle-frequency and sealing demands across pipeline and process applications.
- Ball Valve:Quarter-turn sealing delivers reliable shutoff across high-cycle chemical processing lines. Texas and Louisiana petrochemical operators specify these configurations for reduced maintenance intervals in continuous-duty service.
- Gate Valve:Full-bore, low-pressure-drop operation remains essential for bulk water distribution networks. Great Lakes region municipalities are accelerating procurement for infrastructure rehabilitation funded by bipartisan allocations.
- Globe Valve:Throttling precision suits steam regulation in power generation circuits where flow modulation matters more than absolute shutoff.
- Check Valve:Passive flow prevention protects pumping systems across upstream oil and gas gathering infrastructure.
The dominant share belongs to Ball Valve configurations, while Gate Valve procurement is climbing the fastest on water infrastructure renewal momentum.
Material:
Corrosion resistance and temperature tolerance stratify procurement budgets, with alloy grades commanding multiples over standard carbon specifications.
- Stainless Steel:Austenitic and duplex grades withstand corrosive steam environments in power generation. Nickel price volatility compresses margin predictability for suppliers locked into long-delivery contracts.
- Carbon Steel:Standard pressure classes dominate oil and gas transmission where coating systems supplement base metal protection. Permian Basin gathering line replacement programs sustain volume demand.
- Brass:Lead-free formulations satisfy potable water service codes across municipal distribution systems.
- PVC:Thermoplastic corrosion immunity supports chemical handling in secondary containment applications with moderate pressure requirements.
Carbon Steel retains volume leadership across hydrocarbon infrastructure, though Stainless Steel specification is expanding most quickly on EPA emissions compliance requirements.
End User:
Regulatory exposure and capital cycle timing create divergent procurement rhythms across vertical markets.
- Oil & Gas:Fugitive emissions mandates under EPA New Source Performance Standards are compressing replacement cycles across aging pipeline infrastructure. Low-leak packing and bellows-sealed designs filter uncertified suppliers from volatile organic compound service.
- Water Treatment:Distribution network rehabilitation concentrates gate valve demand in state-funded capital programs. Bellows-sealed cost premiums limit adoption among municipal operators with constrained budgets.
- Power Generation:ASME Boiler and Pressure Vessel code qualification timelines extend 18-24 months, freezing new entrants from procurement cycles.
- Chemical Manufacturing:High-cycle ball valve reliability sustains replacement demand even in flat production environments.
Oil & Gas commands the largest specification value, while Water Treatment procurement is gaining share fastest on infrastructure funding acceleration.
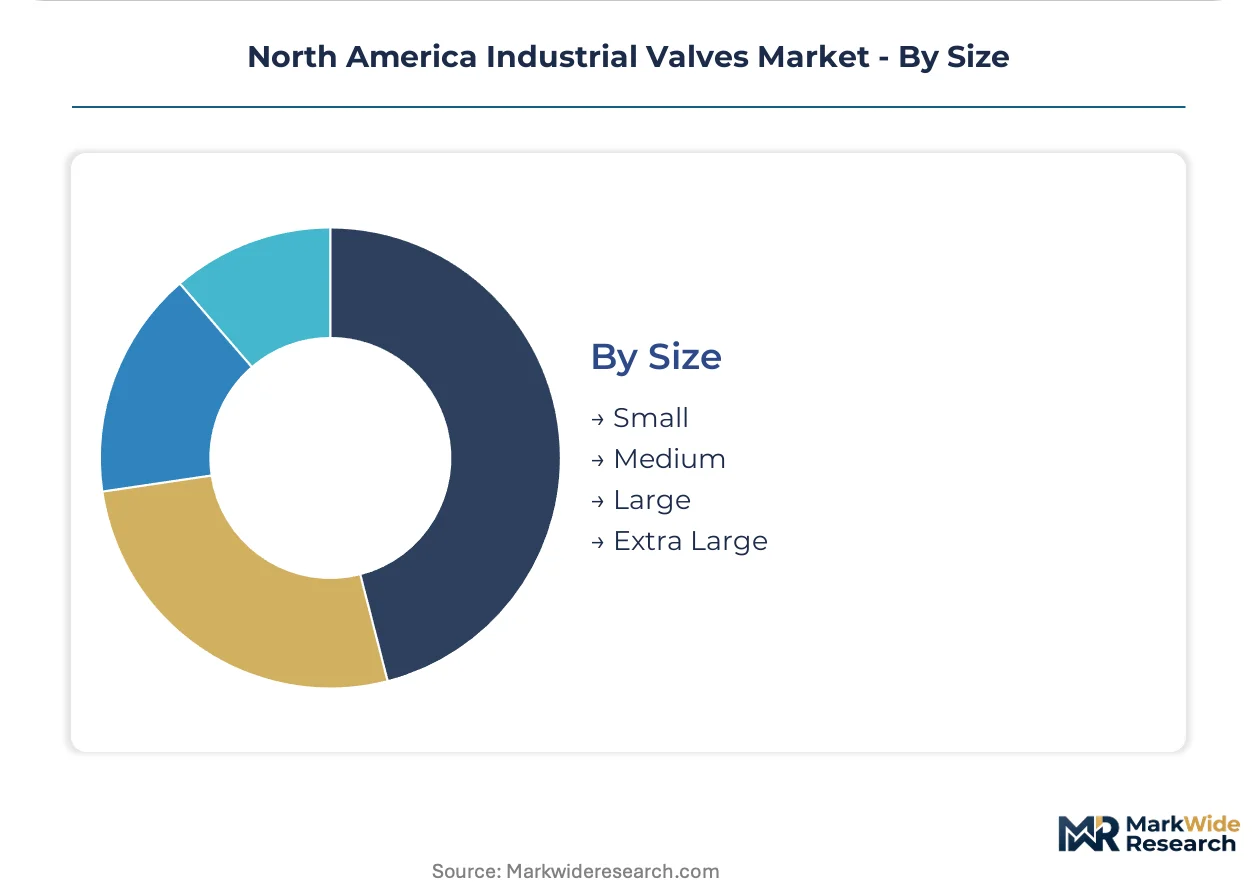
Size:
Pressure class and flow coefficient requirements scale with pipeline diameter and process throughput.
- Large:Pipeline transmission and mainline isolation demand robust pressure containment. Alberta oil sands thermal extraction projects specify severe-service ratings that command premium positioning.
- Medium:Process unit isolation balances accessibility with flow capacity across refinery and chemical plant unit operations.
- Small:Instrumentation and sampling lines require precision machining for leak-tight performance.
- Extra Large:Water transmission mains and cooling water systems specify custom fabrication with extended lead times.
Large diameter valves anchor revenue concentration, while Medium sizes are expanding most quickly on petrochemical cluster capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated oil companies and municipal water authorities concentrate procurement authority across North America, with regulatory compliance timelines and infrastructure funding cycles dictating regional demand rhythms. The United States dominates specification value through petrochemical cluster density and emissions-driven replacement programs. Canada and Mexico present distinct opportunity profiles tied to resource extraction and manufacturing integration respectively.
United States
Texas and Louisiana host the densest concentration of refining and chemical processing capacity, where single-operator procurement scale drives multi-year framework agreements. The EPA's New Source Performance Standards mandate low-leak packing and bellows-sealed designs across volatile organic compound service, filtering uncertified suppliers from Gulf Coast projects. Permian Basin drilling efficiencies have concentrated valve procurement with five dominant exploration operators, compressing vendor negotiation leverage.
Canada
Alberta's thermal extraction projects require severe-service valve specifications that command premium positioning and long-term service attachment rates. Health Canada and provincial regulators enforce fugitive emissions protocols that align with EPA stringency, ensuring cross-border certification portability for US manufacturers. Oil sands mining operators in the Athabasca region are specifying metal-seated ball valves with ceramic coatings for 10-year replacement cycles in erosive slurry applications.
Mexico
Petrochemical capacity expansion in Veracruz and Tamaulipas is integrating valve procurement into Pemex operational frameworks and private downstream investments. The country's national oil regulator enforces equipment standards that increasingly reference API certification requirements, creating compliance alignment with US suppliers. Manufacturing clusters in Nuevo León are developing valve fabrication capabilities to serve regional oil field services and automotive fluid power applications.
North America Industrial Valves Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates procurement authority among certified suppliers with Gulf Coast service density. The vendor base stratifies into three tiers: automation-integrated platforms with diagnostic bundling, aftermarket service networks with refinery anchoring, and component specialists with severe-service material expertise. Dominant competitive moves include strategic partnerships for digital positioner convergence and geographic expansion into Alberta oil sands service territories.
Within the automation-integrated tier, Emerson Electric Co. exemplifies platform-based positioning through distributed control system bundling. Flowserve Corporation anchors the aftermarket-intensive archetype with Gulf Coast refinery service networks. Baker Hughes occupies the turbomachinery-integrated position, situating valves within broader rotating equipment packages. These three US-based entities represent distinct competitive vectors rather than direct product substitution.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Crane Company |
| Alfa Laval |
| Baker Hughes |
| IMI |
| Curtiss-Wright |
| KITZ Corporation |
| Schlumberger Limited |
| Others |
Supply & Pricing Matrix
Overcapacity in Asian stainless steel forging capacity is compressing input costs for North American valve fabricators while simultaneously eroding pricing power for commodity-grade carbon steel specifications. This utilization dynamic forces Gulf Coast suppliers to differentiate through certified low-leak designs that command material premiums over generic alternatives.
Pricing Analysis
Long-term offtake contracts with London Metal Exchange indexation dominate procurement between Texas petrochemical operators and certified valve manufacturers. Three-tier pricing structure across API-certified premium, standard commercial-grade, and economy non-certified levels separates procurement budgets across oil and gas, water treatment, and general industrial segments. Cost compression in economy-tier carbon steel specifications is intensifying because Permian Basin operators are consolidating vendor lists to five dominant exploration companies. Municipal water authorities exhibit highest price sensitivity due to bellows-sealed cost premiums, while oil sands operators in Alberta demonstrate lowest sensitivity given severe-service specification requirements.
Supply Chain Analysis
Export control restrictions on advanced ceramic coating technologies limit US valve manufacturers' access to Japanese and German surface treatment innovations for metal-seated ball valve production. Forging capacity concentrates in China, India, and South Korea for carbon steel castings, while specialty alloy bar stock sources from Sweden, Germany, and domestic US melt shops. Nickel and chromium price volatility creates margin unpredictability for stainless steel steam circuit suppliers. Distribution runs through authorized distributor networks with Gulf Coast stocking locations serving refinery maintenance turnarounds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among five dominant Permian Basin exploration operators and integrated Gulf Coast petrochemical complexes, fragmenting negotiation leverage for mid-tier valve manufacturers.
For Market Incumbents: Build switching-cost moats through embedded diagnostic platform integration that locks customers into predictive maintenance contracts. Anchor position via backward integration into severe-service alloy casting capabilities that reduce dependence on Swedish and German specialty bar stock suppliers. Defend against automation-integrated competitors by expanding field service density across Alberta oil sands territories where long-term service attachment rates command premium positioning. For New Entrants and Emerging Players: Mid-market municipal water treatment facilities in the Great Lakes region represent the most penetrable entry point given infrastructure funding acceleration and incumbent neglect of bellows-sealed economy-tier specifications. Target severe-service repair and aftermarket segments in Alberta thermal extraction projects where incumbent response times create service gaps. Pursue digital positioner retrofit kits as the primary go-to-market angle, enabling legacy valve intelligence upgrades without full replacement. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-recurring-revenue play because EPA methane standards and ASME certification barriers create structural vendor consolidation with predictable replacement cycle visibility. Acquisition targets should emphasize Gulf Coast service network density and API 6D fire-safe certification portfolios. Monitor state water infrastructure funding appropriation velocity as the primary inflection signal for gate valve demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Positioner Convergence | HART-enabled diagnostic integration with Emerson and Honeywell DCS platforms captures recurring predictive maintenance revenue streams. |
| Backward Integration into Forging | In-house stainless steel casting capability insulates margin from nickel price volatility and ASME certification timeline compression. |
| Alberta Oil Sands Service Expansion | Severe-service valve specifications for thermal extraction projects command 10-year replacement cycles and premium service attachment rates. |
| API 6D Certification Acceleration | Fire-safe and cryogenic qualification at accredited laboratories filters uncertified competitors from Gulf Coast petrochemical procurement. |
| Municipal Water Infrastructure Partnership | Great Lakes region gate valve procurement funded by bipartisan infrastructure allocations accelerates volume in flat production environments. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with valve procurement directors at Texas and Louisiana petrochemical complexes, maintenance supervisors at Alberta oil sands operations, and municipal water authority engineers; alongside secondary validation through API certification registries, EPA New Source Performance Standards documentation, and ASME Boiler and Pressure Vessel code filings. Bottom-up triangulation across product-type shipment volumes and top-down reconciliation against end-user capital expenditure disclosures anchored market sizing.
Forecast inputs span product type, material grade, end-user vertical, pressure class, and regional regulatory cluster across the projection horizon. Modeled CAGRs derive from segment-level replacement cycle analysis, infrastructure funding appropriation trajectories, and emissions compliance timeline impacts. Industry-specific inputs include nickel price volatility coefficients and API 6D certification queue duration estimates.
Macroeconomic conditions sit as an overlay; deviation in industrial construction spending, hydrocarbon capital allocation patterns, or alloy commodity price bands would shift the trajectory. Forecasts embed assumptions regarding EPA enforcement continuity and state water infrastructure funding disbursement velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Industrial Safety Valves Market
Valves
Vaneometer Market
Valves
Gate Impellers Market
Valves
Explosion Vents Market
Valves
Wind Energy Fasteners Market
Valves
Penstock Market
Valves
Battery Safety Valve Market
Valves
One-Way Valve Market
Valves
Degassing Valves Market
Valves
Construction Valve Seat Insert Market
Valves
Sanitary Valves Market
Valves
Compressor Valves Market
Valves
Rising Stem Ball Valve Market
Valves
Isolator Valves Market
Valves
Pressure Reducing Valve Market
Valves
Electronic Expansion Valves Market