

Water Draw Off Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Water Draw Off Valves Market Insights
Power generation plants are rotating toward automated condensate recovery systems, displacing municipal water utilities as the fastest-growing buyer archetype. Emerson Electric leverages its actuator integration capabilities to capture premium positioning in thermal power retrofits. Flowserve Corporation anchors its presence through severe-service metallurgy for high-pressure steam applications. Velan Inc. competes on nuclear-grade certifications that few rivals replicate.
Water draw off valves are pressure-retaining devices engineered to extract accumulated liquids, sediments, or condensate from pipelines, tanks, and process vessels, typically rated for pressures from ANSI Class 150 to 2500 and temperatures spanning cryogenic to superheated steam service. Their primary function centers on protecting downstream equipment, maintaining thermal efficiency, and enabling controlled drainage in continuous-process environments. Ball valves dominate municipal and industrial utility applications where full-bore flow and quarter-turn operation reduce maintenance cycles, while actuated valves represent the fastest-expanding technology segment as distributed control system integration becomes standard in power and food processing plants. Gate valves retain entrenched positions in mining slurry and raw water intake systems where straight-through flow minimizes erosion.
The EPA enforces Clean Water Act effluent limits that mandate zero-liquid-discharge approaches in power generation, directly stimulating demand for precision draw-off systems with sealed bonnet designs. ISO 5208 and API 598 testing protocols govern seat leakage classifications, creating market access barriers for uncertified suppliers across North American and European procurement frameworks. ASTM material specifications and ASME B16.34 pressure-temperature ratings further constrain acceptable construction methods. Stakeholders must monitor the divergence between legacy manual installations and digitally actuated replacements, as capital planning cycles in municipal utilities increasingly lag industrial automation timelines.
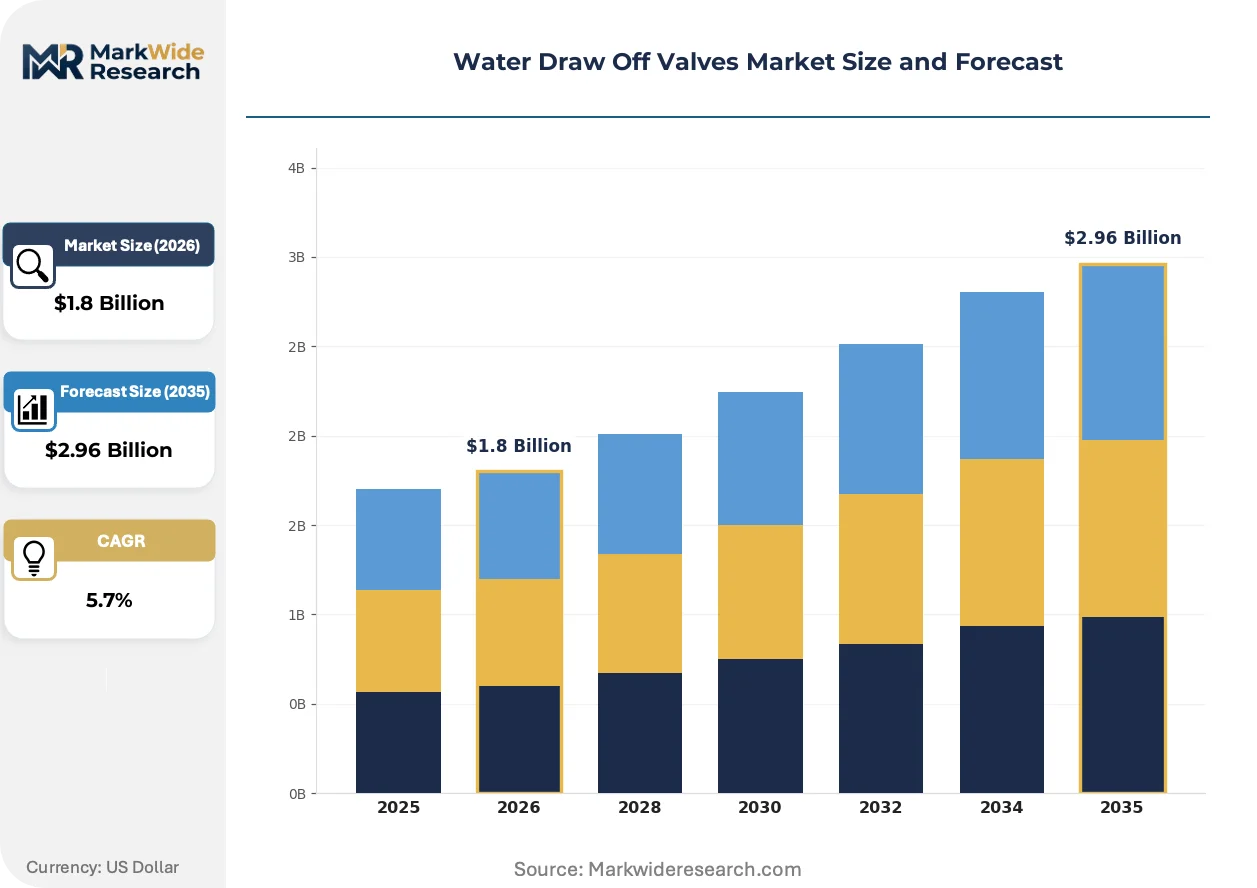
Market Dynamics
The transition from manual to actuated draw-off systems constitutes the dominant structural force reshaping competitive positioning, as power generators and food processors retrofit legacy installations with distributed control integration to meet tightening EPA effluent mandates.
Growth Catalysts
- EPA Clean Water Act zero-liquid-discharge mandates:Power generation facilities must install precision draw-off systems with sealed bonnet designs to eliminate process wastewater discharge, creating immediate replacement demand across aging thermal fleets.
- Actuator technology convergence:Distributed control system integration enables remote monitoring and automated blowdown cycles, reducing labor costs and improving thermal efficiency in continuous-process environments.
- Aging municipal infrastructure replacement cycles:United States water utilities face accelerated valve renewal timelines as distribution systems exceed design life, concentrating procurement in ANSI Class 150-300 rated ball and gate configurations.
Market Restraints
- Specialized metallurgy supply concentration:Severe-service alloys for high-pressure steam applications depend on limited North American and European foundry capacity, creating input cost volatility and extended lead times.
- ISO 5208 and API 598 certification barriers:Seat leakage testing protocols require capital-intensive validation infrastructure that excludes uncertified suppliers from North American and European procurement frameworks.
- Manual valve substitution inertia:Municipal utilities with constrained capital budgets defer actuated system upgrades, extending replacement cycles and compressing near-term addressable demand.
Strategic Opportunities
- Nuclear-grade certification scarcity:Few competitors replicate ASME Section III quality standards, creating protected market segments for qualified suppliers in domestic and international reactor maintenance programs.
- Condensate recovery automation in food processing:Thermal efficiency regulations and water cost pressures drive adoption of actuated draw-off systems in dairy and beverage pasteurization operations.
- Industrial IoT convergence with predictive maintenance:Smart actuator integration enables condition-based monitoring, opening recurring revenue streams through sensor-enabled service contracts.
Industry Challenges
- Distributed control system integration complexity:Retrofit projects require specialized commissioning expertise to harmonize legacy pneumatic actuators with modern digital control architectures.
- ASME B16.34 pressure-temperature rating compliance:Extended certification timelines for new alloy formulations delay product launches and constrain rapid response to custom specification requests.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Draw Off Valves Market Trends and Innovations
Electromechanical actuator miniaturization and sealed bonnet design evolution are compressing equipment footprints while expanding operational envelopes. These developments intersect with tightening emissions protocols and shifting procurement authority from maintenance departments to centralized engineering functions.
Smart electromechanical actuators with embedded positioners and diagnostic capabilities are miniaturizing control enclosures, enabling installation in confined pipeline corridors previously reserved for manual operators. Power generation retrofit contractors specify these compact units for boiler blowdown applications where space constraints previously blocked automation. The technology is compressing total installed cost differentials between manual and actuated systems, accelerating displacement in municipal and industrial segments.
The EPA enforces progressively stringent effluent limitation guidelines under Clean Water Act authority, mandating sealed bonnet designs that eliminate fugitive emissions from valve stem packing. Thermal power operators respond by specifying live-loaded packing systems and welded bonnet constructions that exceed baseline regulatory thresholds. This regulatory trajectory most severely affects aging coal and combined-cycle facilities in the Ohio River Valley and Southwestern United States, where zero-liquid-discharge investments concentrate.
Engineering-procurement-construction firms and original equipment manufacturers now specify valve packages rather than delegating component selection to plant maintenance departments. This buying-pattern shift compresses supplier direct relationships and elevates technical specification authority to front-end engineering design phases. The phenomenon is most visible in United States utility-scale power projects, where integrated automation packages disperse discrete valve procurement across multi-year construction timelines.
Water Draw Off Valves Market Segmentation
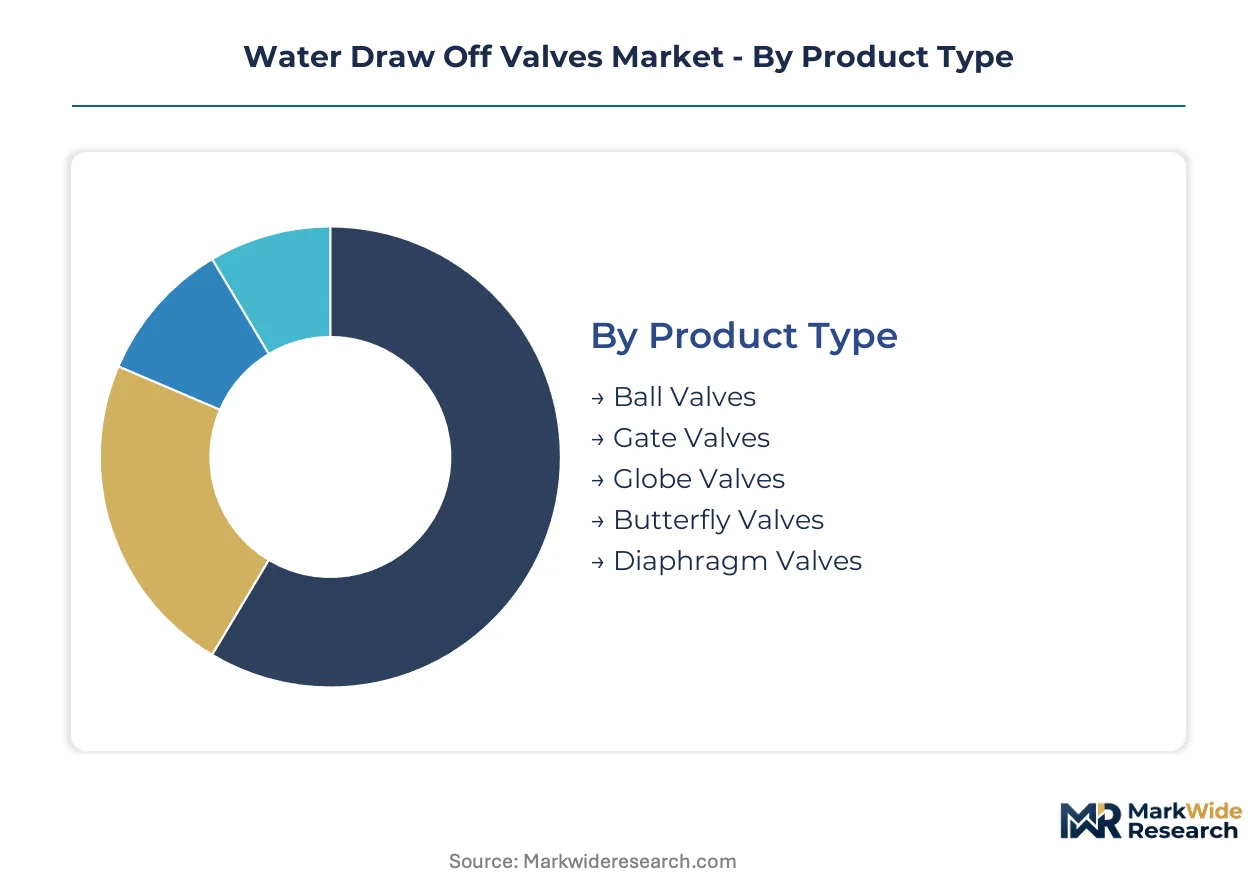
Segmentation in the water draw off valves market reveals how procurement authority, automation requirements, and regulatory exposure fragment demand across incompatible specification regimes. Understanding these divisions exposes where capital planning cycles concentrate and which technology transitions compress replacement timelines.
Product Type:
Ball valve demand concentrates in domestic North American procurement for municipal infrastructure renewal, while severe-service configurations for power generation increasingly source from specialized European and Japanese foundries.
- Ball Valves:Full-bore quarter-turn designs with ANSI Class 150-600 ratings dominate United States municipal distribution systems where maintenance access is constrained. Cities across the Ohio River Valley specify these configurations for aging water main draw-off points where sediment accumulation accelerates valve degradation.
- Gate Valves:Straight-through flow paths with rising or non-rising stems retain entrenched positions in mining slurry and raw water intake applications across the Southwestern United States and Australian iron ore districts. Extended bonnet designs accommodate buried service where excavation costs dominate lifecycle economics.
- Globe Valves:Throttling-capable configurations with S-pattern or Y-pattern bodies serve high-pressure steam blowdown in thermal power stations.
- Butterfly Valves:Compact wafer and lug designs with resilient or metal seats address space-constrained retrofits in combined-cycle plants.
- Diaphragm Valves:Weir-type and straight-through elastomer-lined constructions isolate aggressive media in chemical processing and pharmaceutical water systems.
Ball valves command the established base. The steepest expansion runs through actuated gate valve configurations for automated mining water management.
End Use Industry:
Power generation procurement concentrates in domestic United States thermal fleet retrofits, while food processing demand fragments across export-led European and Asian equipment supply chains.
- Power Generation Plants:Zero-liquid-discharge mandates under EPA Clean Water Act authority force precision draw-off system upgrades across aging coal and combined-cycle facilities. Boiler blowdown and condensate recovery applications specify sealed bonnet designs with live-loaded packing to eliminate fugitive emissions.
- Municipal Water Systems:Distribution infrastructure exceeding design life drives accelerated replacement cycles in United States cities, concentrating procurement in ANSI Class 150-300 rated configurations where maintenance departments retain specification authority.
- Agriculture Irrigation:Center-pivot and flood irrigation systems in California Central Valley and High Plains states utilize low-pressure draw-off assemblies for sediment purging.
- Food & Beverage Processing:Dairy pasteurization and beverage sterilization operations specify sanitary-grade actuated systems for condensate recovery under thermal efficiency regulations.
- Mining Operations:Slurry transport and tailings management in copper districts of Arizona and Chile require abrasion-resistant gate and ball configurations.
Municipal water systems command the established base. Food and beverage processing shows the steepest expansion trajectory as water cost pressures intensify.
Technology:
Manual operation retains dominance in cost-constrained municipal procurement, while actuated systems concentrate in premium industrial segments where distributed control integration justifies capital expenditure.
- Actuated Valves:Electromechanical and pneumatic actuators with embedded positioners enable remote monitoring and automated blowdown cycles in power generation and food processing. Smart actuator miniaturization compresses installed cost differentials versus manual alternatives, accelerating displacement in corridor-constrained retrofits.
- Manual Operation:Handwheel or lever-actuated configurations with gear operators persist in municipal and agricultural segments where capital budgets defer automation investments. These installations concentrate in United States water utilities with extended replacement cycles.
- Pneumatic Control:Compressed air-powered actuation serves explosion-rated environments in chemical and petrochemical co-located power facilities.
- Hydraulic Control:High-force actuation for large-bore severe-service valves in hydroelectric penstock drainage.
- Electric Control:Motor-operated valves with variable speed drives for precise throttling in condensate recovery systems.
Manual operation commands the established base. Electric control configurations are gaining share fastest through industrial IoT convergence.
Distribution Channel:
Direct sales concentrate in large power generation and municipal utility contracts, while distributors and system integrators fragment access across mid-scale industrial accounts.
- Direct Sales:Engineering-procurement-construction firms and original equipment manufacturers specify integrated valve packages for utility-scale power projects, compressing supplier relationships and elevating technical authority to front-end engineering phases. United States thermal retrofits concentrate procurement through this channel.
- System Integrators:Automation specialists harmonize legacy pneumatic actuators with modern digital control architectures, capturing value in distributed control system retrofit complexity. These intermediaries dominate food processing and smaller power facility upgrades.
- Distributors:Industrial valve distributors with ANSI certification inventory serve maintenance-driven replacement demand across fragmented municipal and agricultural accounts.
- Online Retailers:Standardized Class 150 ball and gate configurations for small-scale irrigation and commercial building applications.
- Industrial Supply Stores:Emergency replacement inventory for maintenance departments with constrained procurement lead times.
Direct sales command the established base. System integrators are climbing the fastest as automation retrofit complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian valve fabricators export severe-service configurations to North African desalination projects, while Japanese precision manufacturers supply nuclear-grade assemblies to Southeast Asian reactor programs.
United States
Ohio River Valley thermal plants drive demand for zero-liquid-discharge retrofits under EPA Clean Water Act enforcement. FERC licensing requirements for hydroelectric facilities mandate penstock drainage valve redundancy. Pittsburgh-area engineering-procurement-construction firms consolidate procurement authority for utility-scale automation packages.
Germany
Ruhr industrial clusters specify DIN-standard actuated systems for chemical co-generation facilities. REACH compliance pressures accelerate substitution of traditional packing materials with low-emission alternatives. Bavarian pump and valve OEMs integrate draw-off assemblies into packaged boiler systems for export markets.
Japan
Tokyo Electric Power and regional utilities replace aging manual installations with METI-subsidized smart actuator retrofits. JIS B 2001 pressure testing protocols create certification barriers for non-domestic suppliers. Nagoya-area fabricators concentrate nuclear-grade valve production for domestic reactor maintenance and overseas reactor exports.
China
Provincial environmental protection bureaus enforce MEE discharge standards that stimulate precision blowdown system adoption in coal-fired fleets. Yangtze River Delta manufacturing bases produce cost-competitive ANSI-class ball valves for Belt and Road infrastructure projects. Shandong foundries expand duplex stainless capacity for high-pressure steam service.
India
NTPC and state gencos modernize condensate recovery under CEA thermal efficiency mandates. BIS valve certification requirements delay market entry for uncertified international suppliers. Gujarat chemical clusters import severe-service configurations for specialty chemical process drainage.
Water Draw Off Valves Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with public companies dominating nuclear-grade and severe-service segments while family-owned fabricators capture municipal and agricultural volume. The vendor base arranges into three layers: integrated automation houses with actuator manufacturing, metallurgical specialists with captive foundry capacity, and regional distributors with ANSI inventory depth. Consolidation pressure runs through engineering-procurement-construction procurement centralization, while differentiation concentrates on ASME Section III qualification scarcity and smart actuator integration capability.
Within the integrated automation tier, Emerson Electric and Flowserve Corporation occupy positions defined by distributed control system convergence and severe-service metallurgy respectively. Velan Inc. exemplifies the certification-scarce nuclear-grade archetype. KSB SE & Co. KGaA represents European-scale fluid handling conglomerates with valve-to-pump integration capabilities. These anchors demonstrate how competitive positioning fragments across incompatible specification regimes rather than consolidating around interchangeable commodity supply.
| Leading Market Players |
|---|
| OCECO Inc. |
| Emerson Electric |
| Flowserve Corporation |
| Velan Inc. |
| Crane Company |
| Bray International |
| KSB SE & Co. KGaA |
| KITZ Corporation |
| Watts Water Technologies |
| Others |
Pricing and Supply Chain Analysis
Twenty-six-week lead times for ASME Section III certified castings concentrate pricing power with North American and European foundries possessing captive metallurgical capacity, while buyers without long-term offtake agreements absorb spot-market volatility in duplex stainless inputs.
Pricing Analysis
Current-generation electromechanical actuators command 40-60% premiums over legacy pneumatic configurations, while next-generation smart actuators with embedded diagnostics widen the gap further through predictive maintenance bundling. Three-tier pricing structure across nuclear-grade, severe-service, and standard industrial levels reflects ASME certification scarcity and foundry capacity constraints. Pricing pressure stems from municipal utilities deferring actuated upgrades in favor of manual valve refurbishment, compressing margins in ANSI Class 150-300 segments. Food processing and power generation buyers exhibit lowest price sensitivity due to distributed control system integration requirements and EPA compliance deadlines.
Supply Chain Analysis
Inventory cycles stretching 180-240 days for specialized alloy forgings expose procurement timelines to foundry scheduling bottlenecks in the United States, Germany, and Japan. Supply draws from duplex stainless steel feedstock, cobalt-based hardfacing alloys, and rare-earth magnet components for precision actuators. Single-source vulnerability concentrates in nuclear-grade casting facilities qualified to ASME Section III, where recertification timelines deter buyer switching. Distribution runs through engineering-procurement-construction firms for utility-scale projects, while industrial distributors with ANSI inventory serve fragmented municipal maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Distributed control system interoperability standards are transforming valve procurement from component transactions to platform-ecosystem commitments, with smart actuator integration protocols determining supplier lock-in and recurring revenue capture.
For Market Incumbents: Secure captive foundry capacity in severe-service alloys to defend against input cost volatility and extended lead times eroding project margins. Deepen backward integration into electromechanical actuator manufacturing to capture premium positioning as pneumatic-to-digital retrofits accelerate. Lock in long-term offtake agreements with Ohio River Valley and Southwestern United States power generators facing EPA zero-liquid-discharge deadlines. For New Entrants and Emerging Players: ISO 5208 and API 598 certification fast-tracks open access to North American municipal procurement frameworks previously blocked by validation infrastructure barriers. Target food processing condensate recovery automation in European dairy and beverage clusters where water cost pressures intensify specification authority shifts toward engineering departments. Pursue system integrator partnerships to bypass direct sales channel consolidation by EPC firms. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized nuclear-grade valve divisions lacking standalone scale to justify ASME recertification investments. Long-term viability favors suppliers with smart actuator integration capabilities and predictive maintenance platform architecture over pure-play metallurgical fabricators. Watch for inflection when distributed control system vendors announce native valve-actuator interoperability protocols that commoditize proprietary integration expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Actuator Platform Integration | Embedded diagnostics enable recurring revenue through sensor-enabled service contracts with power generators. |
| ASME Section III Certification Investment | Nuclear-grade qualification scarcity protects margins in domestic and international reactor maintenance programs. |
| Severe-Service Foundry Capacity Expansion | Captive duplex stainless production insulates against European and Japanese supply concentration risks. |
| System Integrator Channel Partnership | Automation specialists capture value in distributed control retrofit complexity across food processing facilities. |
| Sealed Bonnet Design Evolution | Welded bonnet constructions exceed EPA Clean Water Act thresholds in Ohio River Valley thermal retrofits. |
Research Methodology
Cross-validation between primary interviews with plant engineers, EPC procurement leads, and aftermarket service heads and secondary validation through EPA enforcement databases, FERC licensing records, and ASME certification registries anchors the qualitative findings. Bottom-up triangulation aggregates individual facility upgrade timelines across power generation and municipal utility segments, while top-down verification cross-checks against customs data for severe-service alloy imports and capital expenditure disclosures from integrated automation houses.
Sensitivity analysis around actuated valve penetration rates and municipal infrastructure replacement cycles shapes the projection horizon across product type, end-use industry, technology, and distribution channel dimensions. CAGRs derive from installed base depreciation schedules, regulatory compliance deadlines, and automation retrofit payback period modeling. Forecast inputs incorporate EPA effluent guideline enforcement intensity and distributed control system vendor interoperability roadmap announcements.
Decision-makers should treat outputs as directional under assumptions of sustained EPA Clean Water Act enforcement and continued electromechanical actuator cost compression; material deviation in regulatory timelines or foundry capacity expansion would warrant model refresh. Specific risk factors include tariff exposure on specialty alloy imports and municipal budget austerity extending manual valve replacement cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.